
 Herbs and Spices Market | 2026-2036
Herbs and Spices Market Size, Share, and Industry Trends Forecast 2026-2036
Herbs and Spices Market Outlook
Single-origin and small-batch bundling is shifting buyer choice toward curated flavor kits rather than commodity bulk purchases. McCormick & Company leverages its retail shelf presence to anchor premium positioning in North American grocery channels. Olam Group competes through backward integration into African and Asian sourcing estates, controlling quality from harvest through processing. Everest Spices dominates in India's domestic market with region-specific masala formulations that reflect hyperlocal taste profiles.
Herbs and spices comprise aromatic plant materials—leaves, seeds, bark, roots, and flowers—containing volatile essential oils and oleoresins that deliver flavor, color, and bioactive properties; they undergo drying, grinding, steam distillation, or solvent extraction to achieve specified moisture content and particle size for industrial use. Their primary commercial purpose spans food seasoning, natural preservation, pharmaceutical extraction, and fragrance compounding. Ground spices capture the largest volume share due to convenience-driven household and foodservice demand, while dried herbs generate stronger per-unit margins from premium culinary and wellness applications. Specialty stores and online retail together represent the fastest-growing distribution pathway as direct-to-consumer brands bypass traditional wholesaler markups.
The FDA enforces strict mycotoxin and pathogen limits on imported spices under the Food Safety Modernization Act, compelling exporters to upgrade testing infrastructure before US market entry. The EU's EFSA and REACH frameworks regulate pesticide residues and allergen labeling, shaping formulation standards for European-bound shipments. India's FSSAI mandates compulsory certification for spice processing units, tightening domestic compliance while building export credibility. Stakeholders must monitor evolving residue limits and traceability mandates to sustain cross-border market access.
Market Dynamics
The herbs and spices market is restructuring around residue compliance and traceability mandates, with FDA and EFSA enforcement compelling processors to rebuild testing infrastructure and documentation systems ahead of market access.
Growth Catalysts
- Clean-label preservation demand:Food manufacturers are replacing synthetic antioxidants with rosemary extract and green tea polyphenols to meet retailer ingredient blacklists.
- FSSAI certification expansion:India's compulsory spice processing unit certification is consolidating domestic supply chains while building export credibility for European and North American buyers.
- Steam distillation automation:Continuous-flow essential oil extraction systems are reducing solvent use and improving oleoresin yield consistency for industrial flavor houses.
Market Restraints
- Climate volatility in Kerala:Erratic monsoon patterns and flooding in India's cardamom and pepper heartland are compressing harvest windows and amplifying price swings.
- REACH compliance costs:European chemical registration requirements for novel extraction solvents are extending product development timelines and freezing SME participation.
- Adulteration detection gaps:Chromatography and DNA barcoding infrastructure remains concentrated in third-party labs, creating bottlenecks for small-batch exporters.
Strategic Opportunities
- Direct-to-specialty retail:Single-origin brands are bypassing traditional wholesale markups through subscription boxes and chef-curated digital storefronts.
- Pharmaceutical oleoresin contracts:Curcumin and piperine extraction for nutraceutical encapsulation is opening long-term offtake agreements with supplement manufacturers.
- EU Green Deal bioeconomy incentives:Carbon-neutral drying and solvent recovery systems qualify for green transition financing, rewarding early equipment upgrades.
Industry Challenges
- Phytosanitary certification backlogs:National plant protection organizations are struggling to clear export health certificates, delaying container shipments and spoiling time-sensitive harvests.
- Legacy ERP integration:Farm-to-fork traceability platforms require middleware development to connect with established inventory management systems at mid-sized processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbs and Spices Market |
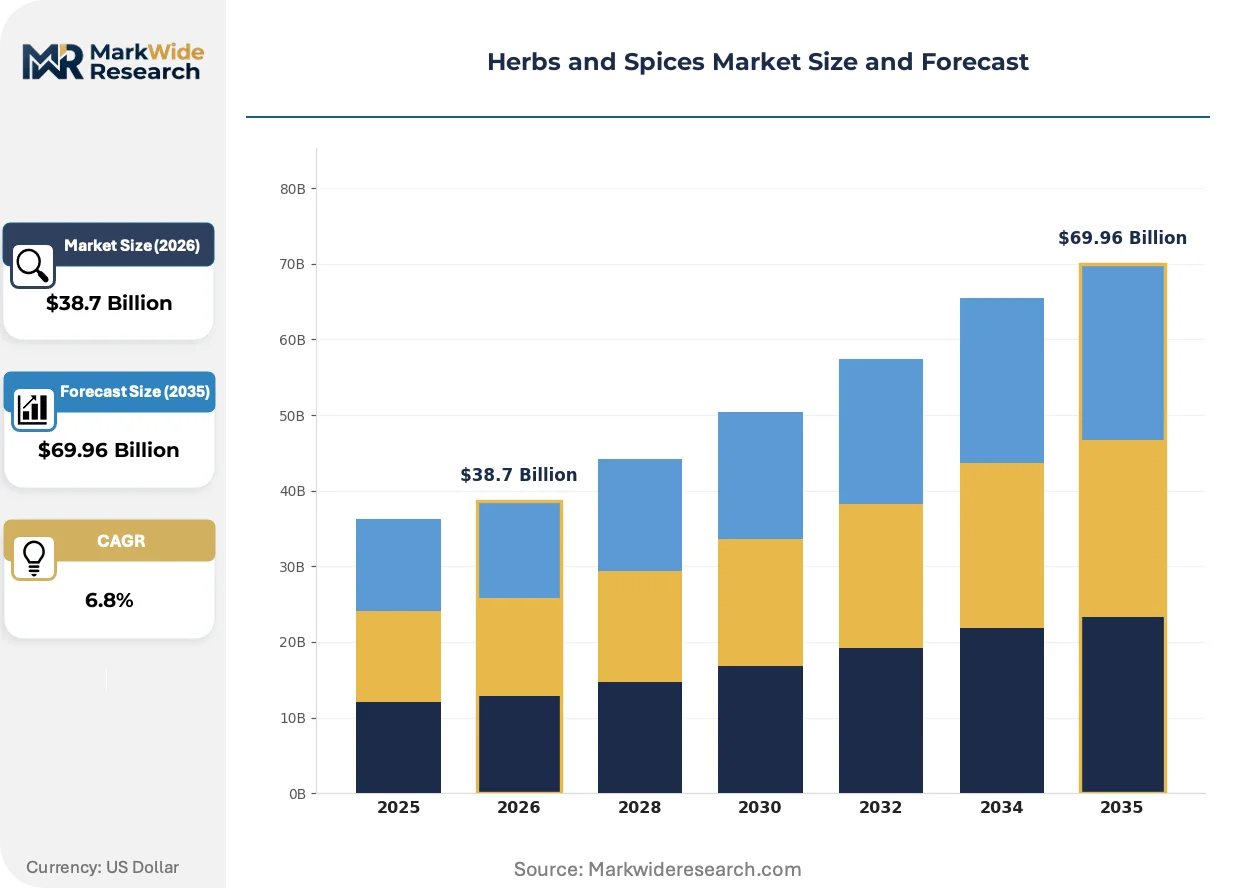
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Herbs, Dried Herbs, Whole Spices, Ground Spices Application: Culinary, Medicinal, Food Preservation, Fragrance Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores End User: Households, Restaurants, Food Processors, Healthcare Providers |
| Companies Covered | McCormick & Company, Olam Group, Givaudan, Kerry Group, Everest Spices, MDH Spices, Baria Pepper, Symrise AG, Ajinomoto Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbs and Spices Market Strategic Shifts
Processing technology and regulatory disclosure requirements are converging to reshape how herbs and spices move from harvest to formulation, with automation and molecular verification displacing traditional quality assurance.
Cold-pressing and supercritical CO2 extraction is expanding into high-value oleoresin production, replacing heat-degraded steam distillates in premium fragrance and therapeutic applications. Flavor houses in Switzerland and France are adopting these systems to preserve volatile terpene profiles. The technology is expanding into mid-tier spice processors seeking to command specialty pricing in North American and Asian markets.
EFSA's updated Food Safety and Hygiene Regulations are tightening maximum residue limits for ethylene oxide and phosphine on imported dried herbs, forcing exporters to validate alternative sterilization methods. Steam and irradiation protocols are gaining regulatory acceptance. Indian and Vietnamese suppliers are retooling processing lines to retain European market access.
Chef-driven procurement is consolidating purchase authority away from commodity traders toward direct estate relationships with named-origin documentation. Restaurant groups and premium retail chains are conducting their own supplier audits. This pattern is most visible in Southeast Asian foodservice expansion, where menu authenticity claims require verifiable sourcing.
Herbs and Spices Market Segmentation
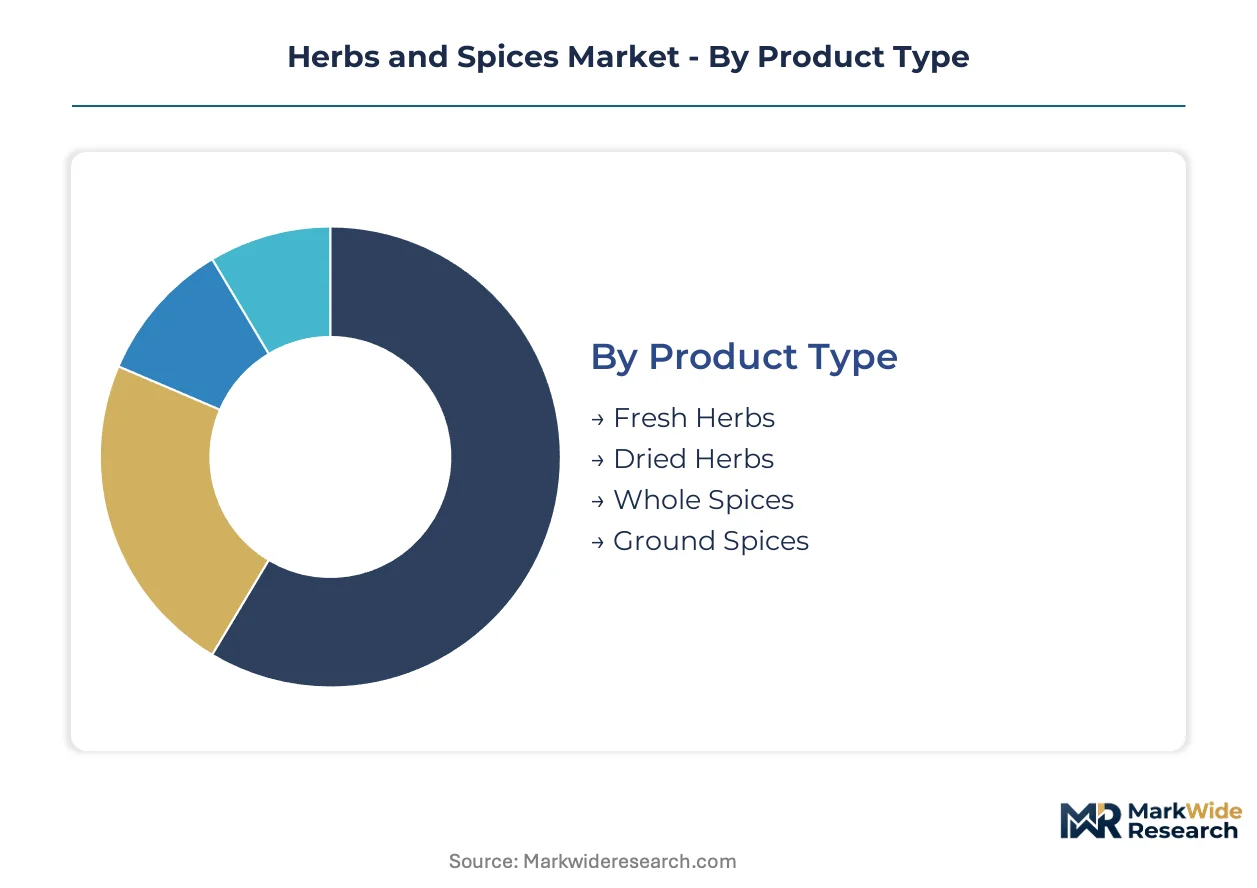
Herbs and spices move through distinct processing tiers and buyer channels, each with diverging margin profiles and compliance burdens. Understanding where value concentrates across these splits reveals which segments reward premium positioning versus commodity scale.
Product Type:
Supply concentration in Kerala and Gujarat processing hubs favors segments with longer shelf stability and export certification readiness.
- Ground Spices:Pulverized seeds, bark, and roots milled to specified particle sizes for immediate culinary use. Demand concentrates in North American and European household sectors where convenience drives repeat purchase. FDA mycotoxin screening requirements favor processors with in-house testing infrastructure.
- Dried Herbs:Dehydrated leaves and flowers with moisture content below 10 percent, preserving volatile oil potency. Premium culinary and wellness applications in France and Switzerland generate strongest per-unit margins, though EFSA residue limits on ethylene oxide force sterilization method upgrades.
- Fresh Herbs:Living or minimally processed plant materials requiring cold chain logistics. Restaurant procurement in Southeast Asian urban centers drives volume, but spoilage rates compress margins.
- Whole Spices:Intact seeds, pods, and bark pieces retaining essential oil integrity until grinding. Ethnic grocery channels and artisan roasting operations in the United States and Germany sustain niche demand.
Today's leader: Ground Spices. Tomorrow's challenger: Dried Herbs.
Application:
Cost tier stratification separates commodity seasoning from pharmaceutical-grade extraction contracts.
- Culinary:Flavoring for home cooking, foodservice, and packaged foods. Restaurant chains across Southeast Asia are expanding menu applications for authentic spice blends, pulling volume through direct estate relationships rather than commodity traders.
- Medicinal:Curcumin, piperine, and other bioactive compounds for nutraceutical encapsulation. Supplement manufacturers in Switzerland and the United States are locking in long-term offtake agreements with Indian oleoresin processors.
- Food Preservation:Natural antimicrobial and antioxidant properties replacing synthetic additives. Rosemary extract and green tea polyphenols are climbing fastest as clean-label alternatives meet retailer ingredient blacklists.
- Fragrance:Essential oil distillation for perfumery and aromatherapy. Supercritical CO2 extraction systems in French flavor houses are displacing heat-degraded steam distillates in premium therapeutic applications.
Culinary dominates volume. Medicinal commands price.
Distribution Channel:
Customer type migration from institutional buyers to direct-to-consumer brands is restructuring margin capture.
- Specialty Stores:Curated retail environments emphasizing provenance and small-batch credentials. Chef-driven procurement here bypasses traditional wholesale markups through subscription boxes and named-origin documentation.
- Online Retail:Digital storefronts enabling direct farm-to-fork traceability claims. This channel is expanding most quickly as single-origin brands build subscription revenue and reduce intermediary costs.
- Supermarkets:Mass retail shelf space dominated by established brands with retail presence. McCormick's North American grocery channel anchoring exemplifies the scale required for placement.
- Wholesalers:Bulk intermediaries serving food processors and institutional kitchens. Traditional markups here are eroding as estate-direct relationships consolidate purchase authority.
Specialty Stores hold current premium positioning. Online Retail shows steepest expansion trajectory.
End User:
Volume scale concentrates with processors, while margin expansion follows authentication capabilities toward healthcare and premium foodservice.
- Food Processors:Industrial buyers integrating spices into packaged sauces, seasonings, and ready meals. FSSAI certification requirements are consolidating supplier relationships around compliant Indian processing units.
- Restaurants:Foodservice operators demanding verifiable sourcing for menu authenticity claims. Southeast Asian chain expansion is pulling demand toward Kerala and Gujarat estates with documented harvest practices.
- Households:Consumer pack goods purchasers through retail and digital channels. Convenience-driven demand favors pre-ground formats despite flavor degradation trade-offs.
- Healthcare Providers:Hospitals, clinics, and wellness centers prescribing standardized herbal preparations. CDSCO and FDA pharmaceutical-grade requirements create entry barriers that reward GMP-certified processors.
Food Processors anchor volume. Healthcare Providers unlock premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The herbs and spices trade traces its commercial origins to ancient maritime routes connecting Kerala's Malabar Coast with Arab and European merchants, establishing India as the historical epicenter of global spice commerce that persists in concentrated processing clusters today.
United States
Clean-label reformulation drives industrial demand for rosemary extract and turmeric oleoresin in packaged foods. FDA enforcement of mycotoxin limits under FSMA compels importers to upgrade third-party testing protocols. Chicago and New Jersey warehousing hubs handle bulk redistribution to North American food processors.
India
Kerala's cardamom and pepper estates supply premium whole spices to European fragrance houses and North American specialty retailers. FSSAI mandatory certification for processing units is consolidating domestic supply chains around compliant Gujarat and Rajasthan facilities. Kochi and Unjha serve as auction and grading centers for export-bound consignments.
Germany
Industrial flavor houses in Hamburg and Frankfurt source oleoresins for meat and savory applications. REACH registration requirements for novel extraction solvents extend product development timelines for mid-sized compounders. Bavaria-based distributors coordinate EU-wide redistribution from Rotterdam port entries.
Vietnam
Pepper and cassia harvests from the Central Highlands feed into Ho Chi Minh City processing corridors. EFSA residue limit enforcement on ethylene oxide is accelerating steam sterilization adoption among export-oriented cooperatives. Binh Phuoc and Dak Lak provinces concentrate mechanized drying infrastructure.
Switzerland
Geneva and Basel flavor houses command premium pricing for supercritical CO2 extracts in therapeutic and luxury fragrance segments. Swissmedic pharmaceutical-grade requirements create entry barriers that reward GMP-certified oleoresin processors. Zürich-based trading desks coordinate long-term offtake contracts with Indian extraction units.
Herbs and Spices Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification and traceability tiers, with residue-compliant processors capturing price premiums while bulk traders compete on volume scale. The vendor base stratifies into three archetypes: integrated agricultural estates controlling harvest-to-processing quality, formulation specialists blending region-specific masalas, and extraction technology providers supplying industrial oleoresins. Dominant competitive moves include backward integration into African and Asian sourcing estates and direct-to-specialty retail channel development bypassing traditional wholesale markups.
Within the integrated estate tier, Olam Group exemplifies upstream control over harvest quality through direct African and Asian sourcing operations. McCormick & Company anchors North American grocery channel presence with retail shelf dominance. Everest Spices occupies a position reflecting hyperlocal formulation expertise in India's domestic market. These three represent distinct competitive vectors: agricultural integration, retail scale, and regional taste specialization.
| Leading Market Players |
|---|
| McCormick & Company |
| Olam Group |
| Givaudan |
| Kerry Group |
| Everest Spices |
| MDH Spices |
| Baria Pepper |
| Symrise AG |
| Ajinomoto Co. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into African and Asian sourcing estates anchors both supply security and pricing power for processors commanding residue-compliant premiums, while fragmented smallholder networks in competing regions struggle to absorb EFSA-mandated sterilization upgrades without margin erosion.
Pricing Analysis
Contract-based long-term offtake agreements dominate pharmaceutical oleoresin procurement, separating GMP-certified processors from spot-market traders. Price differentiation rests on FSSAI certification tier and volume scale, with Kerala estate-direct contracts commanding premiums over Gujarat auction lots. Cost compression in commodity ground spices is intensifying because FDA mycotoxin screening requirements favor capital-intensive processors. Food processors show highest price sensitivity; Swiss fragrance houses demonstrate lowest.
Supply Chain Analysis
Return flows of non-compliant shipments for reprocessing or alternative-market diversion create friction in cross-border herb and spice trade. Geographic supply concentrates in India, Vietnam, and Indonesia, with Kerala cardamom and Central Highlands pepper feeding global channels. Raw material dependencies center on monsoon-sensitive harvest windows, phosphine-dependent fumigation, and chromatography testing capacity. Single-source vulnerability runs through Kerala's flood-prone estates. Distribution runs through Rotterdam port entries for European-bound consignments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Chef-driven procurement across Southeast Asian restaurant chains is pulling volume toward estate-direct relationships with named-origin documentation, rewarding processors with verifiable harvest practices.
For Market Incumbents: To counter REACH compliance costs freezing SME participation, McCormick-scale players should deepen captive supply of African and Asian sourcing estates while anchoring retail shelf presence through premium positioning investments. FSSAI certification expansion in India offers a consolidation lever to absorb compliant processing units before competitors secure European market access. For New Entrants and Emerging Players: Subscription-box direct-to-consumer channels bypass traditional wholesale markups most effectively in North American and European specialty retail. Single-origin dried herbs for wellness applications present the most penetrable white space, with chef-curated digital storefronts offering the clearest go-to-market angle against established grocery-channel incumbents. For Investors and Strategic Acquirers: Roll-up economics work for GMP-certified oleoresin processors because Swissmedic and FDA pharmaceutical-grade requirements create entry barriers that reward scaled compliance infrastructure. The five-to-ten-year viability window favors acquisition targets with backward integration into Kerala or Vietnamese estates. Monitor EFSA residue limit enforcement patterns as the inflection signal for sterilization method upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sourcing Estates | Olam Group's African and Asian estate control secures harvest-to-processing quality consistency for residue-compliant exports. |
| Direct-to-Consumer Channel Launch | Single-origin brands bypass traditional wholesale markups through chef-curated subscription boxes with named-origin documentation. |
| Steam Sterilization Technology Upgrade | Indian and Vietnamese exporters retool processing lines to retain European market access under tightened EFSA ethylene oxide limits. |
| Pharmaceutical Oleoresin Capacity Expansion | Curcumin and piperine extraction units lock in long-term offtake agreements with Swiss and US supplement manufacturers. |
| FSSAI Certification Program | Compulsory spice processing unit certification consolidates domestic Indian supply chains while building export credibility. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with spice processing unit managers, procurement leads at European fragrance houses, FSSAI compliance officers, and restaurant chain sourcing directors with secondary validation from customs trade data, FDA import refusal records, EFSA scientific opinions, and FSSAI certification registries. Bottom-up estate-level production estimates and top-down regional consumption patterns were triangulated to anchor volume figures.
Historical reference periods spanning pre-pandemic baseline through post-FSMA enforcement established the forecast anchor points across the analysis window. Segmentation dimensions modeled include product processing tier, application end-use, distribution channel type, and geographic regulatory cluster. CAGRs were derived from slope analysis of normalized volume trajectories, with climate volatility indices and certification adoption curves serving as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for supercritical CO2 extraction would alter the outlook if solvent recovery economics shift faster than projected. Practitioners should monitor EFSA maximum residue limit revisions and Kerala monsoon deviation indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Incense Sticks (Agarbatti) Market
Spices and Seasonings
Middle East and Africa Ashwagandha Market
Spices and Seasonings
Global Spices and Stimulants Market
Spices and Seasonings
Cinnamon Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
South America Seasoning and Spices Market
Spices and Seasonings
Pink Himalayan Salt Market
Spices and Seasonings
Bolivian Rose Salt Market
Spices and Seasonings
Garlic Oil Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Garlic Oleoresin Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Dried Herbs Market
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Boswellia Extract Market
Spices and Seasonings
Jalapeno Salt Market