
 Pink Himalayan Salt Market | 2026-2036
Pink Himalayan Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Pink Himalayan Salt Market Intelligence
Single-serve pouch and grinder-bottle bundling is restructuring how households and foodservice buyers evaluate unit economics against bulk sack alternatives. McCormick & Company leverages its spice-aisle shelf-space dominance to cross-merchandise pink salt variants alongside pepper and seasoning blends. San Francisco Salt Company anchors its direct-to-consumer revenue through subscription bundles combining coarse and fine grades. WBM International controls private-label supply relationships with North American mass retailers seeking Himalayan-origin certification.
Pink Himalayan salt denotes halite mined from the Khewra Salt Mine in Pakistan's Punjab province, distinguished by trace minerals including iron, magnesium, and potassium that impart its characteristic rose color and subtle flavor profile; the material undergoes minimal processing beyond washing, drying, and crushing to preserve its natural mineral matrix for culinary, therapeutic, and decorative applications. Fine salt and culinary salt variants command premium shelf positioning in health-store and online channels where trace-mineral claims support price elevation above standard table salt. Coarse salt occupies substantial volume in spa and wellness personal-care formulations, while block salt for cooking surfaces and serving platters sustains niche margins among specialty-shop buyers.
FDA food-labeling standards and FSSAI purity certifications shape import documentation and retail packaging claims for Himalayan-origin salt entering the United States and Indian markets respectively. Pakistan's mining export protocols and ISO 22000 food-safety management requirements further condition supply-chain eligibility for international distribution. Stakeholders must monitor evolving traceability mandates and mineral-content disclosure rules that will determine which suppliers retain shelf access versus facing delisting from premium channel assortments.
Market Dynamics
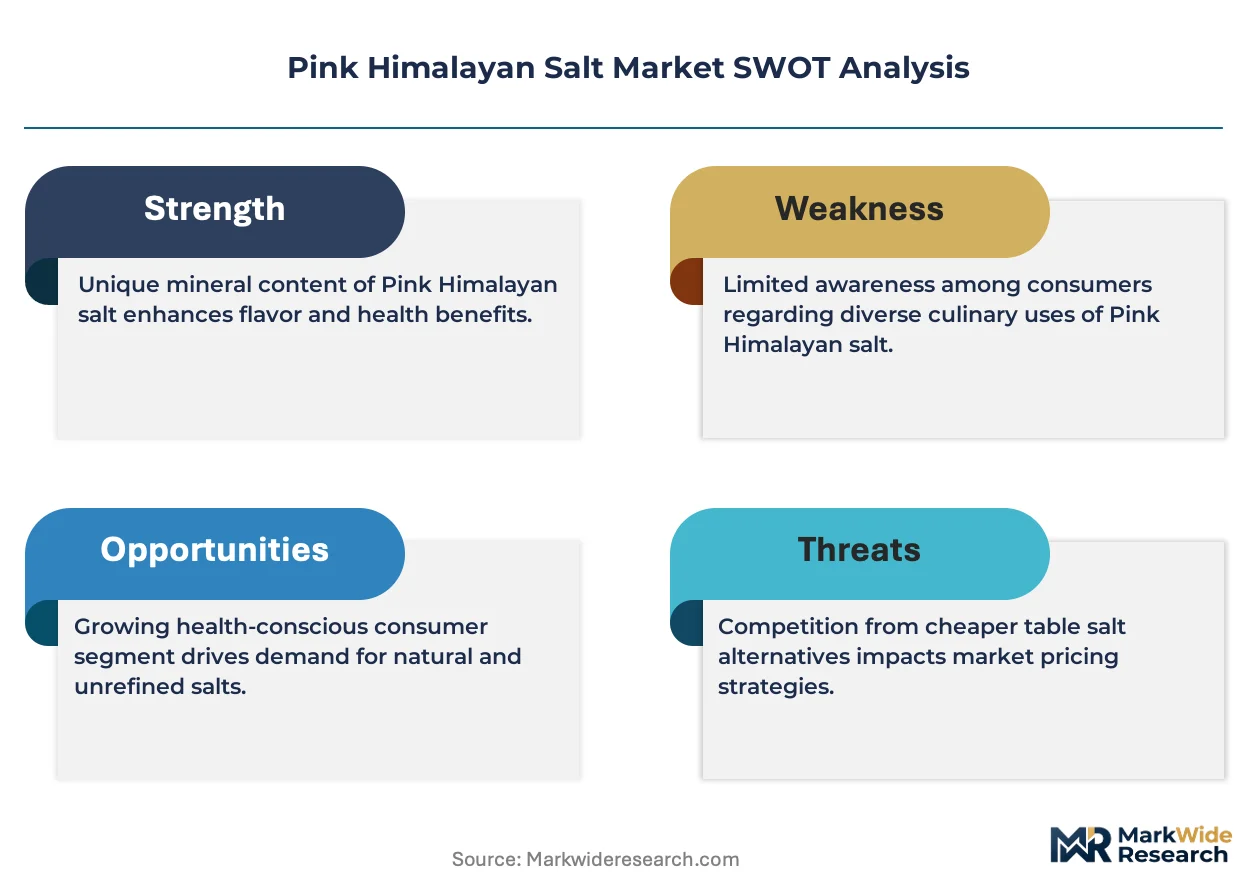
Pakistan's export licensing requirements and FDA purity verification protocols are forcing importers to restructure documentation workflows and supplier qualification timelines. Trace-mineral authentication now determines shelf access in premium retail channels.
Growth Catalysts
- Specialty Retail Channel Expansion:Health-food chains and direct-to-consumer platforms in the United States are creating dedicated fixture space for trace-mineral salts, pulling volume away from conventional table salt.
- FSSAI Food-Grade Certification:India's tightening import documentation for Himalayan-origin salt is accelerating supplier investments in ISO 22000-compliant processing facilities to maintain market eligibility.
- Spa and Wellness Formulation Demand:Personal-care manufacturers are specifying coarse-grade pink salt for bath and body products, opening volume contracts that bypass food-channel price compression.
Market Restraints
- Single-Source Mining Concentration:Khewra Salt Mine dependency creates geopolitical and logistics risk that no alternative Pakistani deposit currently mitigates at equivalent mineral purity.
- Sea Salt Price Competition:Mediterranean and Atlantic solar-evaporated alternatives undercut pink Himalayan positioning in mass-market grocery, limiting penetration beyond specialty tiers.
- FDA Label Scrutiny:Health-benefit claim restrictions on packaging compress margin recovery for brands investing in trace-mineral testing and certification documentation.
Strategic Opportunities
- Block Salt Cooking Surfaces:High-heat grilling and chilled-serving applications for Himalayan salt blocks remain underdeveloped in United States foodservice, with chef-education programs driving trial.
- Subscription Bundle Models:Direct-to-consumer platforms combining coarse and fine grades with grinder hardware are capturing recurring revenue streams that bulk sack distribution cannot replicate.
- EU REACH-Aligned Purity Standards:Alignment with European chemical safety registration opens distribution into German and French specialty retailers previously blocked by documentation gaps.
Industry Challenges
- Trace-Mineral Testing Capacity:Laboratory bottlenecks for iron, magnesium, and potassium verification are extending supplier qualification timelines beyond seasonal procurement windows.
- Blockchain Traceability Integration:Retailer mandates for mine-to-shelf digital records require capital investment in tagging and data infrastructure that smaller Pakistani exporters struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pink Himalayan Salt Market |
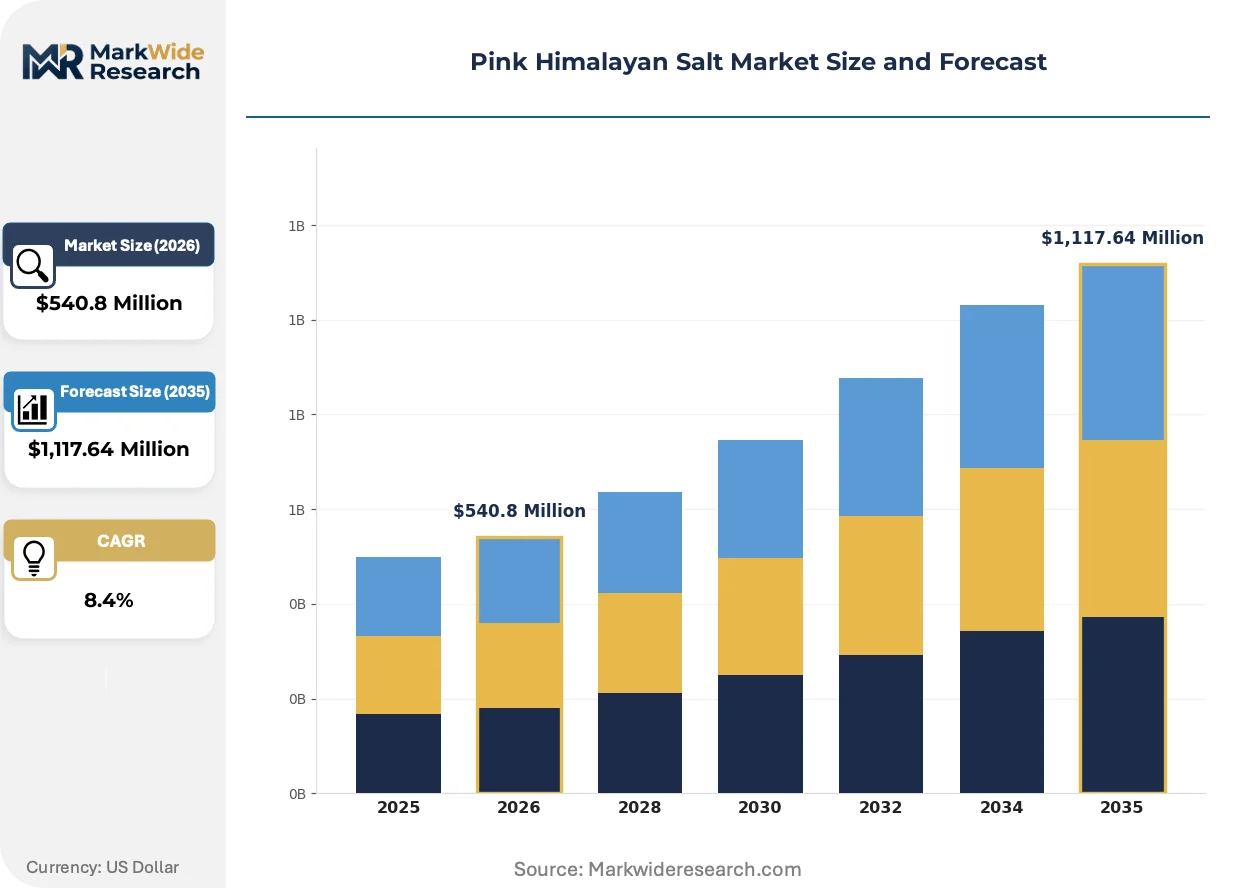
| Market Size in 2026 | $540.8 Million |
| Market Size in 2035 | $1,117.64 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coarse Salt, Fine Salt, Block Salt, Culinary Salt End Use: Food Industry, Personal Care, Agriculture, Industrial Applications Packaging Type: Sack, Jar, Pouch, Bulk Packaging Distribution Channel: Online Retailers, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Himalayan Chef, San Francisco Salt Company, McCormick & Company Inc., Himalayan Pink Salt Co, WBM International, K+S AG, The Spice Lab, Sherpa Pink, SaltWorks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pink Himalayan Salt Market Strategic Shifts & Innovations
Grinder-bottle packaging formats and mineral-authentication technologies are restructuring how buyers evaluate unit economics and supplier credibility across food and wellness channels.
Laser-induced breakdown spectroscopy for rapid trace-element verification is overtaking traditional wet-chemistry laboratory methods at import checkpoints. United States specialty retailers and direct-to-consumer brands are adopting handheld units to screen incoming shipments. This capability is compressing supplier qualification cycles and delisting uncertified competitors from premium channel assortments.
EU REACH chemical safety registration requirements are extending disclosure obligations to food-contact materials including Himalayan salt blocks and cooking surfaces. German and French importers now demand full substance inventory documentation that Pakistani exporters previously filed only for industrial minerals. Block-salt suppliers with pre-registered safety data sheets are capturing shelf space that undocumented competitors are forfeiting.
Household buyers are consolidating salt purchases through subscription bundles that pair coarse culinary grades with fine finishing salts and reusable grinder hardware. This behavior is displacing single-SKU bulk sack purchases in United States e-commerce channels. Foodservice distributors in California and New York are piloting comparable quarterly replenishment models for independent restaurants seeking menu differentiation.
Pink Himalayan Salt Market Segmentation
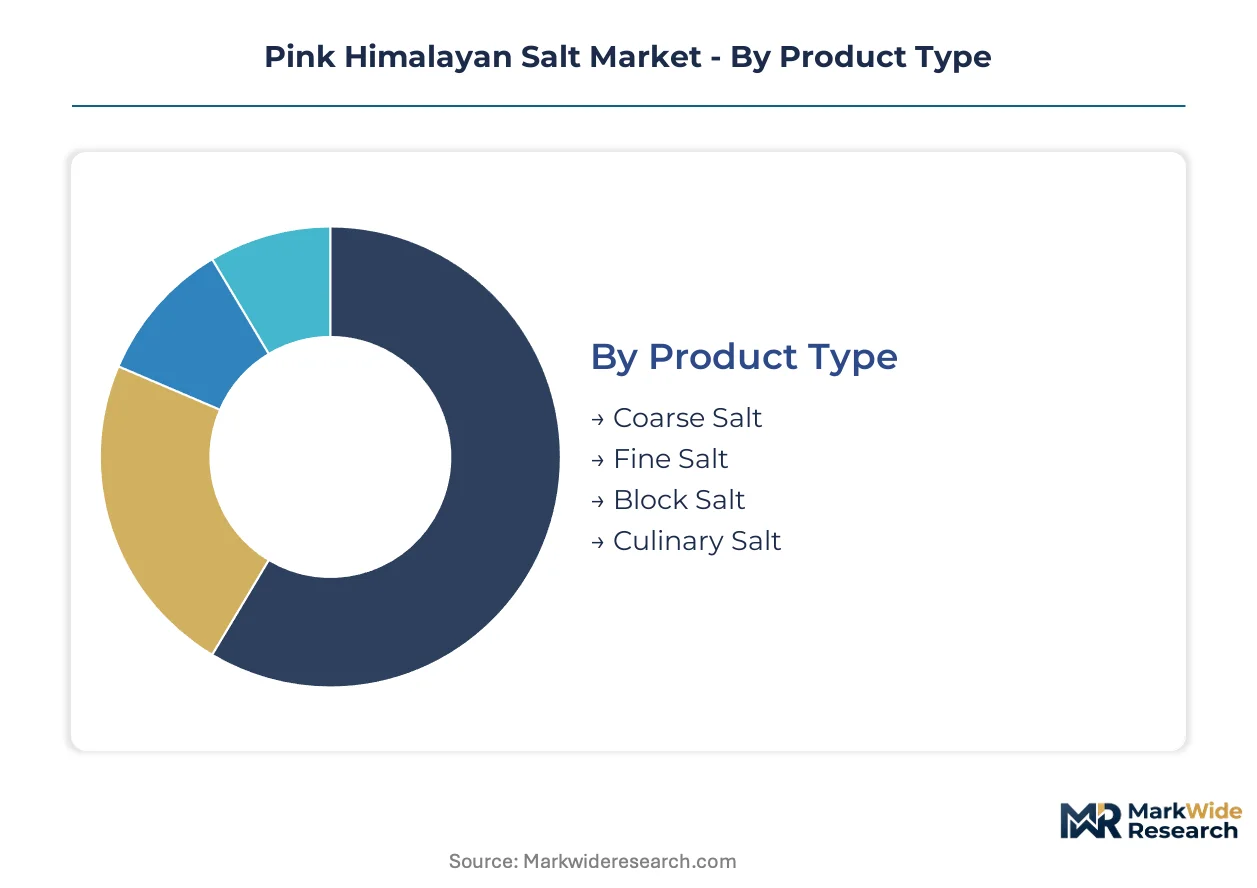
Pink Himalayan salt segmentation reflects divergent capital requirements across mining, processing, and packaging stages. Product form determines upfront investment in crushing, grinding, or block-cutting equipment, while packaging and channel choices shape working capital intensity and margin recovery timelines.
Product Type:
Capital intensity peaks in block salt production, where diamond-wire cutting and dimensional grading demand specialized quarrying infrastructure that coarse and fine milling operations do not replicate.
- Fine Salt:Powder-grade material passes through 0.5mm mesh screens for uniform dissolution in cooking and baking applications. United States health-store channels absorb the majority of volume, with FDA food-grade labeling requirements forcing suppliers to maintain dedicated processing lines that standard culinary grades bypass. Most installed capacity flows through Fine Salt. Expansion is steepest in Block Salt.
- Coarse Salt:Crystalline granules retain 2-5mm particle size for grinder compatibility and controlled release in cooking. Spa and wellness manufacturers in California and New York specify this grade for bath formulations, pulling volume away from food-channel price compression through personal-care contract premiums.
- Block Salt:Dimensionally stable slabs cut from mine-face halite serve grilling surfaces, chilled serving platters, and salt-room construction. EU REACH chemical safety registration requirements now mandate full substance inventory documentation that Pakistani exporters with pre-registered safety data sheets leverage for German and French market entry.
- Culinary Salt:Chef-grade specifications balance crystal size and mineral content for finishing applications where visual presentation matters. United States specialty retailers position this segment adjacent to pepper mills and spice blends, with cross-merchandise fixtures driving impulse conversion.
Processing asset deployment concentrates in Fine Salt. Premium margin capture is climbing fastest in Block Salt.
End Use:
Application-driven segmentation separates food-grade purity investments from industrial-grade tolerance for mineral variation, with personal care occupying a middle tier of cosmetic-grade certification.
- Food Industry:FDA food-labeling standards and FSSAI purity certifications govern import documentation for Himalayan-origin salt entering the United States and Indian markets respectively. Gourmet food manufacturers specify trace-mineral authentication for premium positioning against Mediterranean sea salt alternatives.
- Personal Care:Coarse-grade pink salt enters bath and body formulations where mineral content claims support price elevation above standard sodium chloride. California-based spa product manufacturers contract directly with Pakistani processors for ISO 22000-compliant supply chains.
- Agriculture:Livestock mineral supplementation and soil amendment applications tolerate broader particle size distribution and higher insoluble content than food channels. This segment bypasses the certification documentation that premium channels demand.
- Industrial Applications:Chemical processing and de-icing specifications prioritize volume scale over mineral matrix preservation, with Khewra Mine output competing against rock salt from Chilean and Bulgarian deposits on delivered cost.
Food Industry commands the largest share of certified processing capacity. Personal Care is expanding most quickly as wellness positioning penetrates mass retail.
Packaging Type:
Format selection determines shelf-life engineering, with moisture barriers and grinder mechanisms adding per-unit cost that bulk alternatives avoid entirely.
- Grinder Bottle:Integrated ceramic or metal grinding mechanisms in glass or PET containers support premium positioning in United States supermarkets. McCormick & Company cross-merchandises these formats alongside pepper mills in spice-aisle dominant positions.
- Pouch:Single-serve and resealable flexible packaging serves direct-to-consumer subscription bundles combining coarse and fine grades. San Francisco Salt Company anchors recurring revenue through quarterly replenishment models that bulk sack distribution cannot replicate.
- Jar:Wide-mouth glass containers target pantry storage and controlled dispensing for household culinary use. Health-store channels in New York and Los Angeles favor this format for visual mineral display.
- Bulk Packaging:25kg and 50kg woven polypropylene sacks serve foodservice distributors and industrial processors with internal repackaging capabilities. This format sacrifices margin recovery for volume throughput and logistics efficiency.
Bulk Packaging moves the greatest tonnage. Grinder Bottle is gaining share fastest as household buyers consolidate purchases through bundled formats.
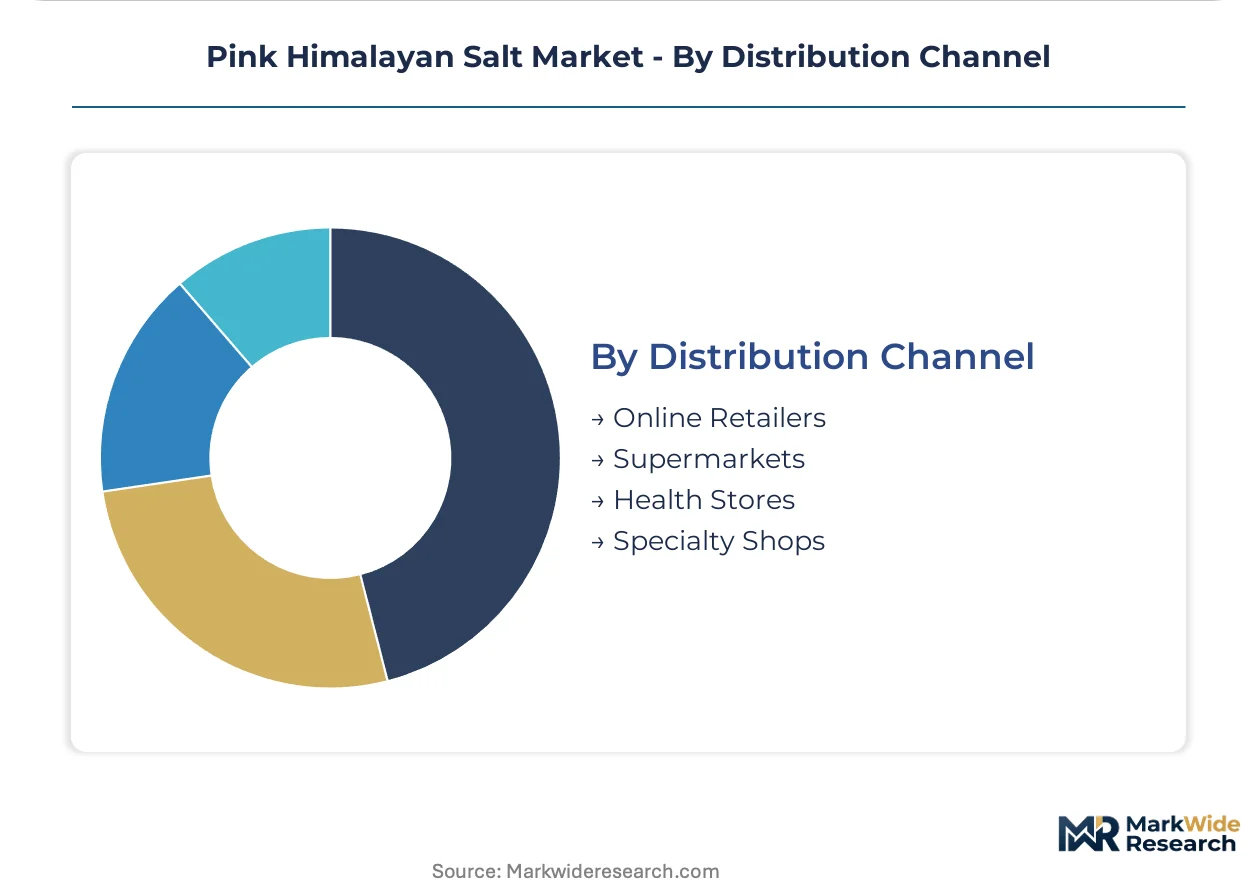
Distribution Channel:
Channel segmentation reflects divergent customer acquisition costs, with online platforms capturing lifetime value through subscription mechanics that transactional retail cannot match.
- Online Retailers:Direct-to-consumer platforms combine educational content on trace-mineral benefits with subscription bundling for recurring revenue. WBM International controls private-label supply relationships with North American mass retailers seeking Himalayan-origin certification through this channel.
- Supermarkets:Spice-aisle placement alongside standard table salt exposes pink Himalayan variants to mass-market price comparison. Sea salt alternatives undercut positioning here, limiting penetration to premium-tier store brands.
- Health Stores:Dedicated fixture space for trace-mineral salts in United States chains like Whole Foods Market and Sprouts Farmers Market supports price elevation through staff recommendation and educational signage.
- Specialty Shops:Independent gourmet retailers and cooking supply stores emphasize block salt for grilling demonstrations and salt-room ambiance products. Chef-education programs in Chicago and Austin drive trial for cooking surface applications.
Supermarkets process the highest transaction volume. Online Retailers are climbing the fastest as subscription mechanics displace single-purchase behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pink Himalayan salt commerce originated in Pakistan's Punjab province, where the Khewra Salt Mine has supplied mineral halite since the nineteenth century. Contemporary demand now spans five major import markets with divergent regulatory and channel characteristics.
United States
Specialty retailers and direct-to-consumer platforms absorb the majority of food-grade imports, with Whole Foods Market and Sprouts Farmers Market dedicating fixture space to trace-mineral salts. FDA food-labeling standards govern packaging claims and purity verification protocols for all Himalayan-origin salt entering American distribution. California-based spa product manufacturers in Los Angeles and San Francisco metropolitan areas contract directly with Pakistani processors for coarse-grade supply chains serving wellness formulations.
Germany
Gourmet retailers and cooking supply stores in Berlin and Munich drive block salt demand for grilling surfaces and salt-room construction applications. EU REACH chemical safety registration requirements now mandate full substance inventory documentation for food-contact materials including Himalayan salt blocks. Importers in Hamburg and Frankfurt leverage pre-registered safety data sheets to capture shelf space that undocumented competitors forfeit.
India
Gourmet food manufacturers specify trace-mineral authentication for premium positioning against domestic rock salt alternatives in Delhi and Mumbai metropolitan markets. FSSAI purity certifications shape import documentation requirements for Himalayan-origin salt entering Indian distribution. Processing facilities in Gujarat and Maharashtra invest in ISO 22000-compliant infrastructure to maintain eligibility under tightening food-grade standards.
United Kingdom
Health-store chains and online retailers in London and Southeast England support price elevation through staff recommendation and educational signage on mineral content. The Food Standards Agency enforces labeling requirements for imported specialty salts alongside EU-legacy regulations still in transitional application. Independent gourmet retailers in Scotland and Northern England emphasize block salt for cooking demonstrations and ambient retail experiences.
France
Specialty food distributors in Paris and Lyon metropolitan areas position pink Himalayan variants adjacent to pepper mills and spice blends in cross-merchandise fixtures. ANSM and DGCCRF oversight extends to mineral-content claims on imported food-grade salts. Chef-education programs in Provence-Alpes-Côte d'Azur drive trial for cooking surface applications among foodservice buyers seeking menu differentiation.
Pink Himalayan Salt Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification and channel positioning tiers. The vendor base clusters around three strategic groupings: established spice and seasoning conglomerates with dominant retail shelf-space control, direct-to-consumer specialists with subscription bundling capabilities, and private-label suppliers serving mass retail certification requirements. Dominant competitive moves include cross-merchandise fixture partnerships with specialty retailers and backward integration into ISO 22000-compliant Pakistani processing facilities.
Among North American specialists, San Francisco Salt Company exemplifies the direct-to-consumer archetype through recurring revenue models, while McCormick & Company Inc. anchors the spice-aisle conglomerate tier with cross-merchandise capabilities. WBM International occupies a position within the private-label supply tier serving mass retailers seeking Himalayan-origin certification.
| Leading Market Players |
|---|
| Himalayan Chef |
| San Francisco Salt Company |
| McCormick & Company Inc. |
| Himalayan Pink Salt Co |
| WBM International |
| K+S AG |
| The Spice Lab |
| Sherpa Pink |
| SaltWorks Inc. |
| Others |
Cost & Logistics Intelligence
Artisanal mining labor concentrated in Pakistan's Punjab province feeds directly into three-tier pricing spreads across premium, standard, and economy certification levels. Wage differentials between Khewra Salt Mine extraction crews and ISO 22000-compliant processing facility technicians translate into margin capture that separates trace-mineral authenticated product from bulk agricultural-grade alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy certification levels governs transactional dynamics. Price differentiation rests on FDA food-grade labeling compliance and mineral-content verification grade. Pricing pressure stems from Mediterranean sea salt alternatives undercutting mass-market positioning. Foodservice distributors exhibit highest price sensitivity, while wellness channel buyers absorb premium tiers for trace-mineral claims.
Supply Chain Analysis
Single-source vulnerability sits with Pakistan's Khewra Salt Mine as the sole commercial deposit of rose-hued halite with equivalent mineral purity. Supply draws from Pakistan for raw extraction, India for ISO 22000 processing infrastructure, and United States for direct-to-consumer fulfillment. Tariff exposure on Pakistani-origin minerals creates structural risk. Distribution runs through bulk sack foodservice, private-label mass retail, and subscription direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pink Himalayan salt functions as a stable compounder anchored by wellness positioning that sustains premium pricing through trace-mineral authentication requirements.
For Market Incumbents: Extend backward integration into ISO 22000-compliant Pakistani processing facilities to defend against FSSAI documentation tightening. Lock block-salt cutting capacity ahead of EU REACH registration deadlines to secure German and French shelf access. For New Entrants and Emerging Players: Enter via chef-education programs in underpenetrated United States foodservice markets for salt-block grilling applications. Target subscription bundle mechanics combining coarse and fine grades with grinder hardware to bypass McCormick's spice-aisle dominance. For Investors and Strategic Acquirers: Spice and seasoning conglomerates are the most active acquirer in this space, seeking trace-mineral authentication capabilities. Long-term viability centers on certification moats rather than commodity extraction. Watch for FDA enforcement actions on health-benefit claims as inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Processing | Captures ISO 22000 certification margin that raw exporters forfeit to Indian facilities. |
| Subscription Bundle Launch | San Francisco Salt Company's recurring revenue model locks household lifetime value against bulk alternatives. |
| EU REACH Registration Completion | Pre-registered safety data sheets unlock German gourmet retail and French cooking supply channels. |
| Chef Education Partnership | Chicago and Austin demonstration programs convert foodservice trial into block salt volume contracts. |
| Laser Spectroscopy Deployment | Handheld LIBS units at import checkpoints compress supplier qualification cycles and delist uncertified competitors. |
Research Approach
Coverage spans United States, Germany, India, United Kingdom, and France, with primary inputs from each market. Primary interviews with gourmet food manufacturers, spa product formulators, Pakistani mining export coordinators, FDA regulatory consultants, and specialty retail category buyers combined with secondary validation from FDA food-labeling guidance documents, FSSAI import notification records, EU REACH substance inventory filings, and Pakistani export licensing statistics. Bottom-up volume modeling and top-down value reconciliation provided triangulation.
Granularity-level modeling operated at product type, end use, packaging format, and distribution channel dimensions across the analysis window. CAGRs derived from segment-level volume trajectories and price-tier migration patterns. Mineral-content disclosure rule evolution and blockchain traceability mandate adoption curves served as industry-specific forecast inputs.
Inputs from Pakistani mining authorities and United States import customs were available through the study window; gaps in real-time blockchain traceability deployment data introduce uncertainty bands around supplier qualification timeline assumptions. Forecasts reflect documented assumptions on regulatory enforcement intensity and wellness channel penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Herb Oil Market
Spices and Seasonings
Incense Sticks (Agarbatti) Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Bolivian Rose Salt Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
Asia-Pacific Spice and Herb Extracts Market
Spices and Seasonings
Serrata Extract Market
Spices and Seasonings
Ginger Salt Market
Spices and Seasonings
Paprika Powder Market
Spices and Seasonings
Africa Spice and Herb Extracts Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
US Gourmet Salt Market
Spices and Seasonings
Frankincense Extract Market
Spices and Seasonings
Chef Bases Market
Spices and Seasonings
Wasabi Market