
 Bath and Shower Products Market | 2026-2036
Bath and Shower Products Market Size, Share, and Industry Trends Forecast 2026-2036
Bath and Shower Products Market Analysis
Multi-source ingredient procurement is broadening across the bath and shower supply base as brands hedge against raw material volatility. Procter & Gamble leverages its captive surfactant production to buffer cost swings, while Unilever anchors its competitive stance through dense emerging-market distribution networks. Beiersdorf differentiates via dermatological testing protocols that command premium shelf positioning in European pharmacies.
Bath and shower products comprise surfactant-based cleansing formulations, typically incorporating sodium lauryl sulfate or gentler glucoside alternatives, designed for epidermal hygiene and moisture retention during daily washing routines. The formulation dimension spans organic, natural, synthetic, and hydrating variants, with natural and hydrating segments capturing accelerated interest as consumers scrutinize ingredient transparency and barrier function. Shower gels and foaming washes lead product-type volume, while bar soaps occupy a mature, price-sensitive niche with concentrated demand in lower-income demographics and sustainability-focused buyers.
Regulators including the FDA, the EU's ECHA under REACH, and India's BIS shape market access through divergent safety assessment and labeling mandates that elevate compliance costs for multinational portfolios. The EU's F-Gas Regulation and emerging packaging directives in multiple jurisdictions are pressuring brands to reformulate and redesign containers ahead of tightened environmental standards. Stakeholders must track how divergent regional chemical restrictions and recyclability targets will fragment product architectures and force region-specific SKU proliferation.
Market Dynamics
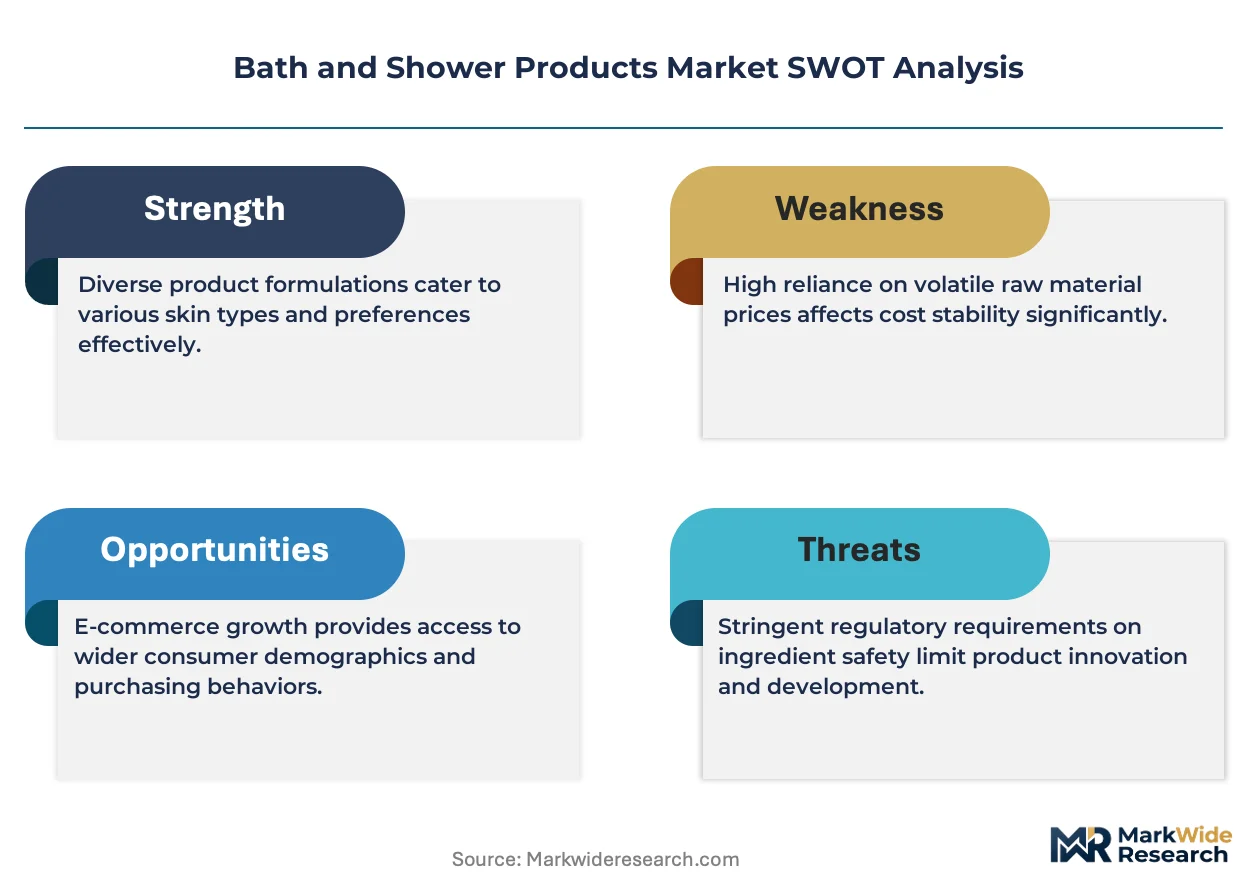
Ingredient transparency mandates and surfactant supply volatility are compressing formulation flexibility across brand portfolios, forcing simultaneous compliance investments and raw material hedging strategies.
Growth Catalysts
- EU REACH Chemical Disclosure:Tightened registration requirements for rinse-off cosmetics elevate barrier-to-entry for non-compliant imports, advantaging established European formulators with pre-certified ingredient libraries.
- Southeast Asia Tropical Climate Demand:Hydrating shower formulations capture outsized volume growth as rising disposable incomes in Indonesia, Vietnam, and Thailand drive premium personal care adoption.
- Glucoside Surfactant Substitution:Sodium lauryl sulfate displacement by milder alkyl polyglucosides accelerates in dermatological and baby-care segments, opening formulation differentiation for sensitive-skin positioning.
Market Restraints
- Palm Oil Derivative Volatility:Surfactant feedstock costs swing with Malaysian and Indonesian export policies, compressing margin predictability for mass-market bar soap producers.
- EU F-Gas Packaging Pressure:Aerosol propellant restrictions under the F-Gas Regulation force container redesign investments, elevating SKU complexity for foaming wash portfolios.
- Biodegradability Technical Ceiling:Natural preservative systems fail stability thresholds in tropical storage conditions, limiting clean-label claims in high-humidity distribution corridors.
Strategic Opportunities
- India Tier-2/Tier-3 Distribution:Penetration gaps in Lucknow, Jaipur, and Kochi create whitespace for sachet-format shower gel launches ahead of organized retail expansion.
- Refill Station Channel Innovation:Unpackaged bulk dispensing in European specialty retailers reduces per-unit packaging cost while capturing sustainability-premium price realization.
- Waterless Concentrate Formats:Solid shampoo bars and paste concentrates align with airline carry-on restrictions and cabin baggage liquid limits, opening travel-retail placement.
Industry Challenges
- Cosmetic Chemist Talent Scarcity:Formulation expertise bridging natural chemistry and regulatory compliance commands premium compensation, elevating R&D fixed costs for mid-tier brands.
- Multi-Jurisdiction Labeling Complexity:Divergent INCI disclosure requirements across FDA, ECHA, and BIS jurisdictions force parallel packaging runs, elevating working capital intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bath and Shower Products Market |
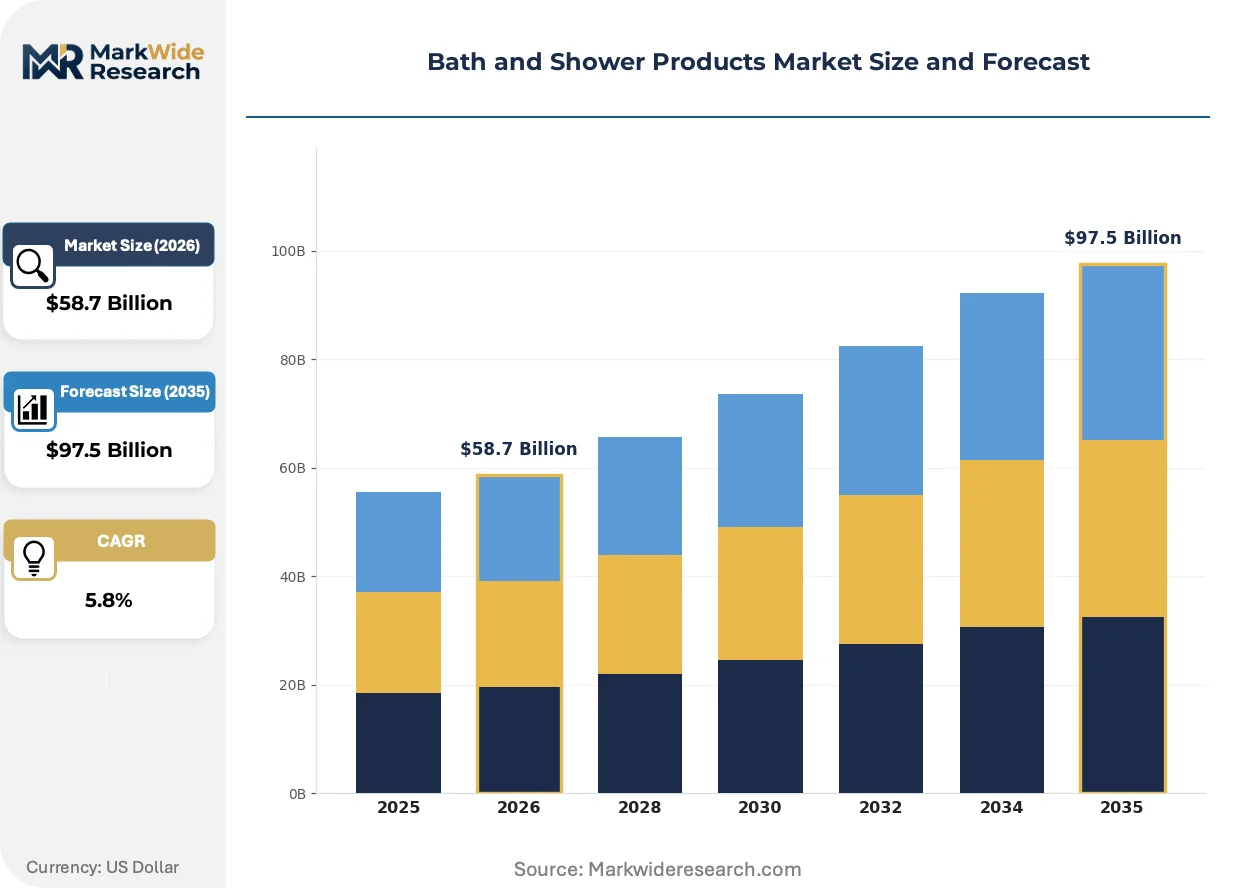
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $97.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shower Gels, Bath Oils, Bar Soaps, Foaming Washes Formulation: Organic, Natural, Synthetic, Hydrating End User: Adults, Children, Seniors, Couples Packaging Type: Plastic Bottles, Glass Jars, Tubes, Sachets |
| Companies Covered | L'Oréal, Kao Corporation, Procter & Gamble, Bath & Body Works, Johnson & Johnson, Unilever, Beiersdorf, Henkel, Colgate-Palmolive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bath and Shower Products Market Emerging Trajectories
Microbiome-targeted cleansing science and packaging material transitions are restructuring competitive advantage around epidermal health claims and circular economy credentials rather than fragrance differentiation alone.
Biome-friendly preservation systems are decentralizing formulation authority away from traditional broad-spectrum antimicrobials. Indie brands and dermatological lines are adopting postbiotic and prebiotic stabilizers at accelerated pace. This technology is decentralizing shelf-space dominance from mass-market giants toward clinically positioned challengers with ingredient-story credibility.
India's BIS mandatory quality standards for liquid toilet soaps are compressing informal manufacturer participation. The standards impose microbiological purity thresholds previously absent in unorganized production. Domestic contract manufacturers are consolidating to achieve testing laboratory accreditation, while importers face certificate-of-origin documentation burdens.
Direct-to-consumer subscription models are capturing recurring revenue from urban millennials in São Paulo, Mexico City, and Jakarta. Traditional hypermarket and pharmacy channels are losing trial-volume access as algorithmic personalization replaces aisle-based discovery. Brazil and Southeast Asian metro corridors exhibit the fastest channel-share rotation toward auto-replenishment platforms.
Bath and Shower Products Market Segmentation
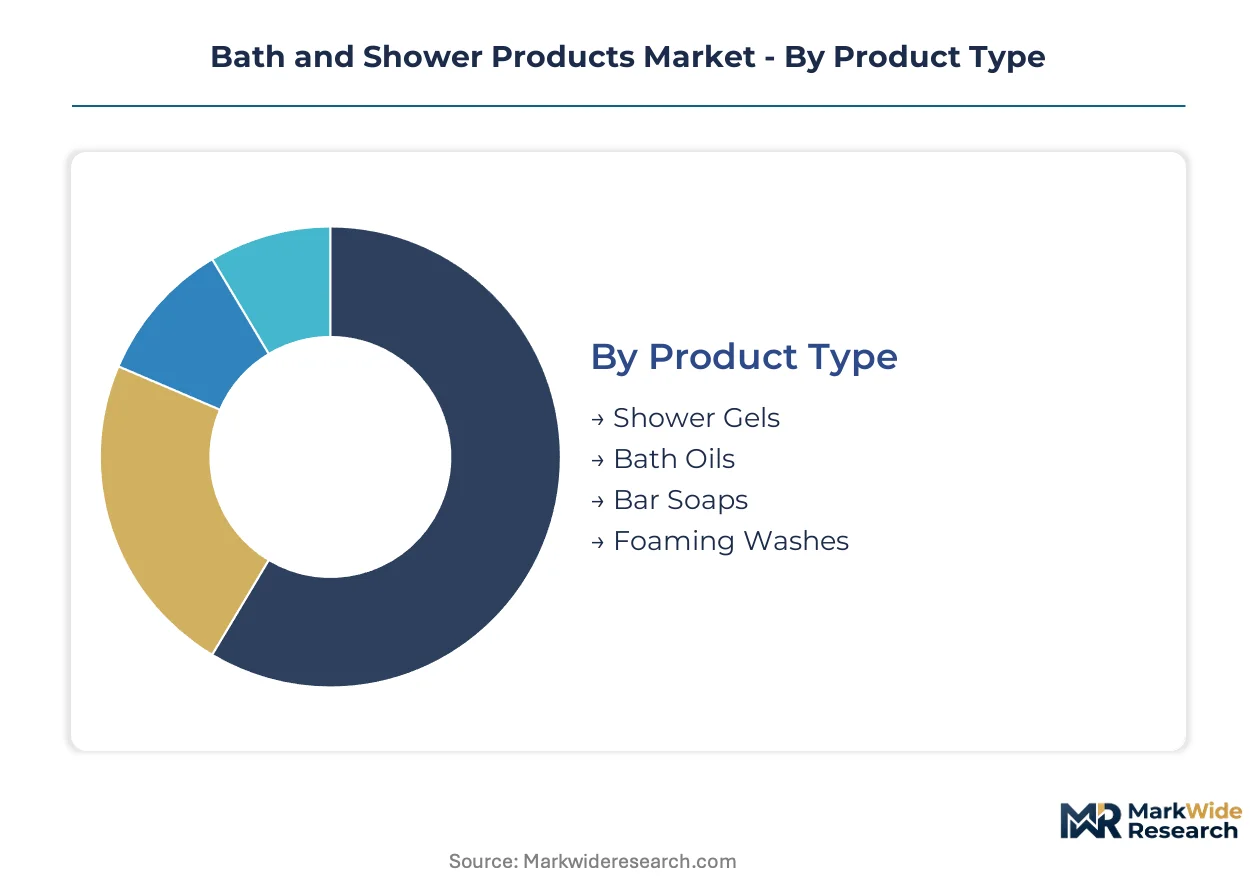
Segmentation in bath and shower products reveals how capital allocation, regulatory exposure, and channel economics fragment across distinct product architectures. Manufacturers must align R&D spend and compliance infrastructure with the specific technical and demographic requirements of each slice.
Product Type:
Capital intensity varies sharply across formats, with liquid production requiring stainless-steel mixing vessels and automated filling lines while solid formats demand compression molding and curing floor space.
- Shower Gels:Viscous surfactant suspensions with pH-balanced thickeners and fragrance encapsulation systems. Demand clusters in Southeast Asian urban centers where tropical humidity drives daily shower frequency and premium gel adoption.
- Bath Oils:Lipid-rich emollients requiring heated blending tanks and oxidation-stabilized packaging. Growth concentrates in European pharmacy channels where dermatological positioning commands price premiums for atopic skin conditions.
- Bar Soaps:Saponified fatty acid bases with minimal water content and extended shelf stability.
- Foaming Washes:Aerosol or pump-dispensed aerated formulations with specialized propellant or mechanical foaming hardware.
Most installed capacity flows through Shower Gels. Expansion is steepest in Bath Oils.
Formulation:
Margin structure diverges primarily by certification burden, with organic and natural variants absorbing disproportionate audit and documentation costs relative to synthetic baselines.
- Organic:Certified ingredient chains with prohibited synthetic inputs and third-party verification protocols. Supply concentrates in German and French contract manufacturers with ECOCERT and COSMOS laboratory accreditation.
- Natural:Plant-derived surfactants and preservative systems with flexible but documented sourcing standards. Adoption accelerates in Indonesian and Vietnamese markets where tropical storage stress-tests stability claims.
- Synthetic:Petrochemical-derived surfactants with established safety dossiers and cost-optimized supply chains.
- Hydrating:Glycerin, ceramide, and hyaluronic acid-enriched bases with barrier-function clinical testing.
Natural formulations carry the heaviest compliance load. Hydrating variants are climbing the fastest.
End User:
Distribution economics favor segments with predictable replenishment cycles and concentrated retail placement.
- Adults:Broad-spectrum cleansing and treatment products with gendered or unisex positioning across mass and premium tiers.
- Children:Tear-free, hypoallergenic formulations with pediatric dermatology endorsements and parental safety signaling.
- Seniors:Mobility-accessible packaging and dry-skin-focused emollient systems for aging epidermal barriers.
- Couples:Dual-appeal fragrance profiles and larger-format packaging designed for shared bathroom consumption.
Adult SKUs dominate shelf space allocation. Seniors represent the most underserved demographic.
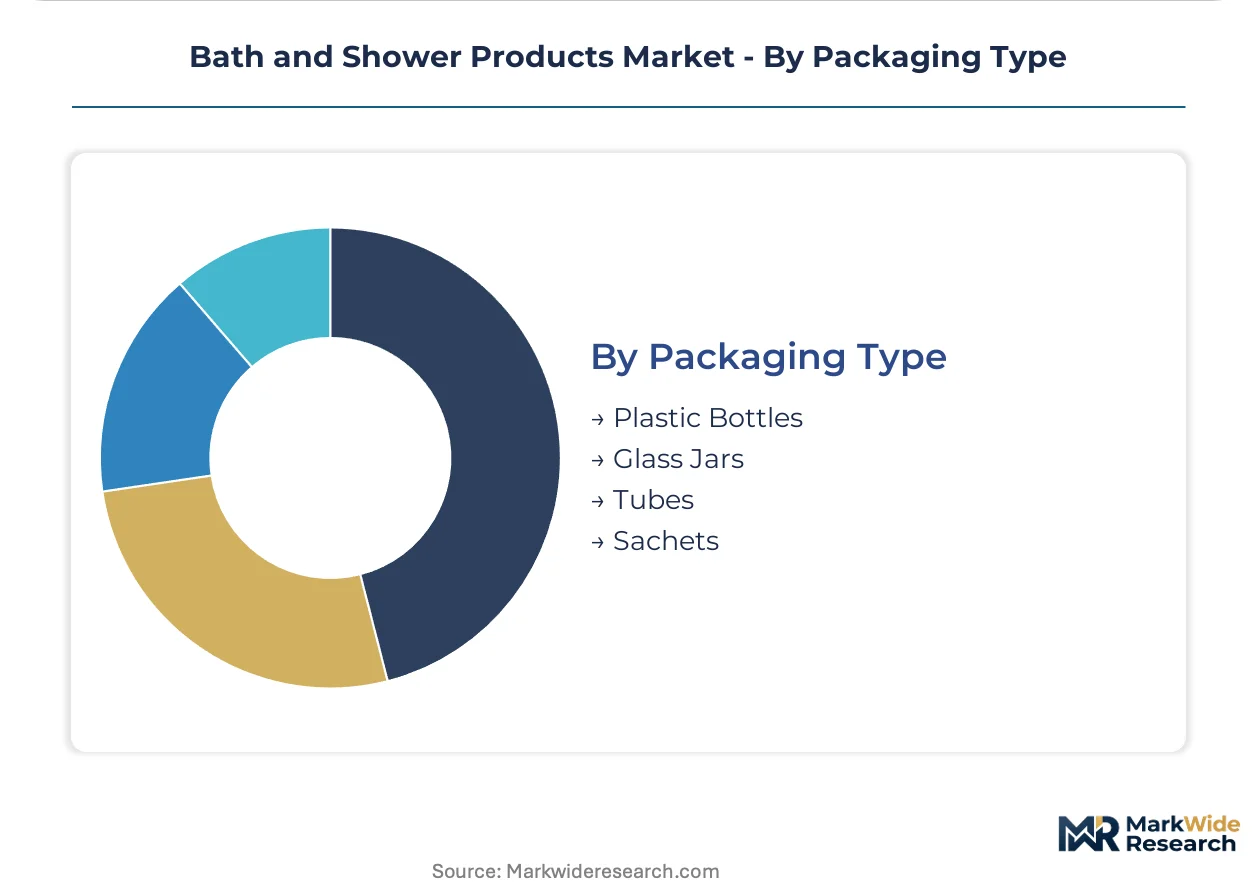
Packaging Type:
Environmental regulation intensity shapes investment priorities, with plastic formats facing redesign mandates while alternative materials absorb premium positioning value.
- Plastic Bottles:HDPE and PET containers with pump or flip-cap closures and established recycling stream compatibility.
- Glass Jars:Heavy, inert vessels for oil-based and preservative-free formulations with luxury aesthetic signaling.
- Tubes:Laminated or extruded plastic-aluminum hybrids for viscous products with controlled dispensing and travel convenience.
- Sachets:Single-serve flexible pouches with minimal material weight and lowest per-unit cost for trial and emerging-market penetration.
Plastic bottles anchor current production volume. Sachets are gaining share fastest in South Asian and Latin American expansion corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asia's tropical manufacturing corridor generates outsized demand for hydrating formulations as rising disposable incomes reshape daily hygiene routines across Indonesia, Vietnam, and Thailand.
United States
Direct-to-consumer subscription models capture recurring revenue from urban millennials in New York and Los Angeles. The FDA maintains stringent cosmetic labeling requirements that elevate compliance costs for imported rinse-off products. Texas and California host concentrated contract manufacturing capacity serving North American private-label demand.
Germany
Pharmacy-channel dermatological positioning commands premium shelf space for barrier-function formulations in Berlin and Munich. ECHA's REACH framework tightens chemical disclosure mandates for surfactant-based rinse-off cosmetics. The Rhine-Ruhr industrial zone anchors ECOCERT-accredited contract manufacturing for organic certification chains.
India
Sachet-format shower gel penetration accelerates in Lucknow, Jaipur, and Kochi ahead of organized retail expansion. BIS mandatory quality standards for liquid toilet soaps compress informal manufacturer participation. Maharashtra and Gujarat consolidate domestic contract manufacturing to achieve testing laboratory accreditation.
Brazil
Algorithmic personalization on auto-replenishment platforms displaces traditional hypermarket trial-volume access in São Paulo and Rio de Janeiro. ANVISA regulates cosmetic safety assessments with divergent timelines from FDA and ECHA processes. The São Paulo metro corridor exhibits the fastest channel-share rotation toward subscription-based bath product delivery.
Indonesia
Tropical humidity drives daily shower frequency and premium gel adoption in Jakarta and Surabaya. The country's national cosmetic regulator enforces halal certification requirements that fragment formulation architectures for Muslim-majority markets. Java's manufacturing belt concentrates surfactant production serving ASEAN distribution networks.
Bath and Shower Products Market Vendor Landscape
Global majors compete with regional champions across distribution density and formulation certification tiers, producing a tiered structure where captive surfactant production, pharmacy-channel positioning, and emerging-market sachet penetration define distinct competitive vectors. Three archetypes dominate: vertically integrated giants with backward control over raw material supply, dermatological specialists leveraging clinical testing protocols, and agile regional players optimizing for price-sensitive mass distribution. M&A activity concentrates on natural-formulation startups with ECOCERT accreditation, while capacity expansion targets Southeast Asian filling lines for tropical-climate SKUs.
Within the premium-tier vector, L'Oréal and Beiersdorf exemplify pharmacy-channel positioning strategies, while Unilever occupies a position bridging mass-market scale with emerging-market density. Procter & Gamble anchors the integrated archetype through captive production capabilities that buffer surfactant cost volatility.
| Leading Market Players |
|---|
| L'Oréal |
| Kao Corporation |
| Procter & Gamble |
| Bath & Body Works |
| Johnson & Johnson |
| Unilever |
| Beiersdorf |
| Henkel |
| Colgate-Palmolive |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap surfactant producers in Malaysia and Indonesia anchor raw material supply for mass-market bar soaps, translating palm oil export policy swings directly into pricing volatility that compresses margin predictability for downstream brands unable to hedge feedstock exposure.
Pricing Analysis
Surfactant feedstock pass-through from Malaysian and Indonesian palm derivative markets drives quarter-to-quarter price adjustments across mass-market tiers. Three-tier pricing structure across premium, standard, and economy levels separates ECOCERT-certified organic formulations from natural-positioned mid-tier products and synthetic-baseline economy lines. Pricing pressure stems from EU F-Gas aerosol propellant restrictions forcing container redesign investments. Mass-market bar soap buyers exhibit highest price sensitivity, while pharmacy-channel dermatological segments absorb premium realization with minimal volume elasticity.
Supply Chain Analysis
India's BIS mandatory quality standards for liquid toilet soaps function as de facto local-content rules, compressing informal manufacturer participation and consolidating accredited domestic contract manufacturing in Maharashtra and Gujarat. Surfactant production concentrates in Malaysia, Indonesia, and Germany's Rhine-Ruhr industrial zone. Formulation draws from palm oil derivatives, alkyl polyglucosides, and glycerin-enriched emollients. Single-source vulnerability runs through Malaysian export policy volatility. Distribution runs through hypermarket and pharmacy channels in developed markets, with sachet-format penetration accelerating via traditional trade in South Asian expansion corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between EU REACH compliance costs elevating European production expense and Southeast Asian tropical-climate demand absorbing premium hydrating formulations at margin-accretive price points.
For Market Incumbents: Anticipate glucoside surfactant substitution acceleration by securing captive alkyl polyglucoside supply agreements ahead of dermatological segment demand inflection. Consolidate ECOCERT-accredited contract manufacturing capacity in Germany and France to defend pharmacy-channel positioning against indie brand challengers leveraging biome-friendly preservation narratives. For New Entrants and Emerging Players: Specialty retailers with refill station infrastructure offer immediate channel access for unpackaged bulk dispensing formats capturing sustainability-premium price realization in European urban centers. Target India's Tier-2 and Tier-3 cities through sachet-format shower gel launches ahead of organized retail expansion in Lucknow, Jaipur, and Kochi. For Investors and Strategic Acquirers: Valuations sit cheapest among natural-formulation startups with ECOCERT or COSMOS laboratory accreditation yet limited Southeast Asian distribution footprint. Long-term viability hinges on bridging certification credibility with tropical-climate SKU development capability. Watch for BIS accreditation consolidation among Indian contract manufacturers as inflection signal for emerging-market production scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Production | Procter & Gamble's captive sodium lauryl sulfate manufacturing buffers Malaysian palm derivative volatility. |
| ECOCERT Accreditation Investment | German and French contract manufacturers capture organic certification premiums through laboratory accreditation consolidation. |
| Refill Station Channel Partnership | European specialty retailers reduce per-unit packaging cost while realizing sustainability-premium pricing. |
| Sachet-Format Geographic Expansion | Unilever's dense emerging-market networks penetrate India's Tier-2 cities ahead of organized retail buildout. |
| Microbiome-Targeted R&D Pipeline | Beiersdorf's dermatological testing protocols command pharmacy shelf positioning through biome-friendly preservation systems. |
Methodological Framework
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combining interviews with brand managers, category buyers at retailers, supply planners, and regulatory affairs leads with secondary validation from Nielsen retail audit data, customs records, SEC 10-K filings, and ECHA REACH registration databases. Bottom-up and top-down triangulation cross-validates volume estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, formulation certification tier, end-user demographic, and packaging format. CAGRs derive from trend extrapolation adjusted for regulatory inflection points and channel-shift elasticity. Industry-specific forecast inputs incorporate EU F-Gas implementation timelines and India's BIS enforcement intensity.
Revisions become necessary when Malaysian or Indonesian export policy shifts materialize, when EU packaging directive implementation accelerates, or when microbiome-targeted preservation systems achieve tropical stability thresholds. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Face Steaming Devices Market
Beauty & Personal Care
Europe Beauty and Personal Care Products Market
Beauty & Personal Care
Spray Tanning Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
Facial Epilator Market
Beauty & Personal Care
Saudi Arabia Eyelash Serum Market
Beauty & Personal Care
Facial Rollers Market
Beauty & Personal Care
Nail Salon Market
Beauty & Personal Care
Nail Strengtheners Market
Beauty & Personal Care
Natural Hair Care Product Market
Beauty & Personal Care
Coffee Beauty Products Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Nail Care Products Market
Beauty & Personal Care
Facial Wipes Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
Electric Face Cleanser Market