
 Toilet Care Wipes Market | 2026-2036
Toilet Care Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Toilet Care Wipes Market Analytics
Single-use sachet unbundling from bulk resealable packs is decoupling household trial behavior from institutional procurement patterns. Kimberly-Clark Corporation leverages its North American tissue infrastructure to control flushable wipe distribution through club and grocery channels. The Procter & Gamble Company anchors premium antibacterial positioning in moisture-wicking formats across mass retail. Reckitt Benckiser specializes in disinfecting formulations that compete for shelf space against spray alternatives in European markets.
Toilet care wipes are non-woven or cotton-based moistened sheets, typically impregnated with antimicrobial agents, surfactants, and skin-conditioning compounds, manufactured through hydroentanglement or thermal bonding processes and designed for perianal cleansing, surface disinfection, or personal hygiene maintenance. Flushable wipes lead volume but face technical scrutiny over dispersibility standards, while antibacterial variants command margin premiums in healthcare and commercial end-user segments. Biodegradable material grades are gaining fastest in household channels as synthetic substrates encounter regulatory pressure across multiple geographies.
FDA oversight of skin-contact antiseptics, EPA registration requirements for disinfecting claims, and ECHA REACH restrictions on preservative chemistry collectively determine which formulations achieve market access in the United States and Europe. The EU Green Deal's single-use plastics framework and emerging GB standards in China on flushable dispersibility are tightening compliance thresholds for cross-border suppliers. Stakeholders must monitor how divergent biodegradability certifications between North American and European test protocols reshape material sourcing and product labeling obligations.
Market Dynamics
Dispersibility standards are fragmenting across jurisdictions, forcing substrate suppliers to maintain parallel certification streams while retail buyers demand flushable claims that satisfy divergent test protocols.
Growth Catalysts
- EU Green Deal single-use plastics framework:Biodegradable fiber grades gain shelf space as synthetic substrates face mandatory disclosure requirements across member states.
- Healthcare-associated infection protocols:Antibacterial wipe formats penetrate acute care and long-term care facilities where surface disinfection workflows favor pre-moistened sheets over spray alternatives.
- Moisture-wicking chemistry:Premium household segments in Japan and Germany adopt advanced skin-conditioning formulations that reduce irritation incidence during repeated daily use.
Market Restraints
- Wood pulp price volatility:Viscose and lyocell fiber costs fluctuate with energy-intensive dissolving pulp production concentrated in Brazilian and Indonesian supply basins.
- EPA disinfectant registration timelines:New active ingredient approvals stretch 18-36 months, delaying product launches for antimicrobial wipe lines targeting institutional buyers.
- Municipal sewer infrastructure capacity:Wastewater utilities in older US metropolitan areas reject flushable claims regardless of INDA/EDANA dispersibility compliance, limiting household trial conversion.
Strategic Opportunities
- Indian urban sanitation expansion:Swachh Bharat Mission infrastructure investments create first-time access to flush toilet systems in tier-2 and tier-3 cities.
- E-commerce subscription bundling:Direct-to-consumer channels bypass traditional grocery slotting fees while capturing recurring revenue from household replenishment cycles.
- GB/T flushable standards in China:Harmonized national testing protocols reduce compliance duplication for suppliers targeting domestic retail and hospitality procurement.
Industry Challenges
- Nonwoven engineering talent scarcity:Hydroentanglement process optimization requires specialized expertise that concentrates among aging technical workforces in European and Japanese equipment manufacturers.
- Cross-border labeling complexity:Divergent biodegradability certifications between North American and European test protocols force SKU proliferation and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toilet Care Wipes Market |
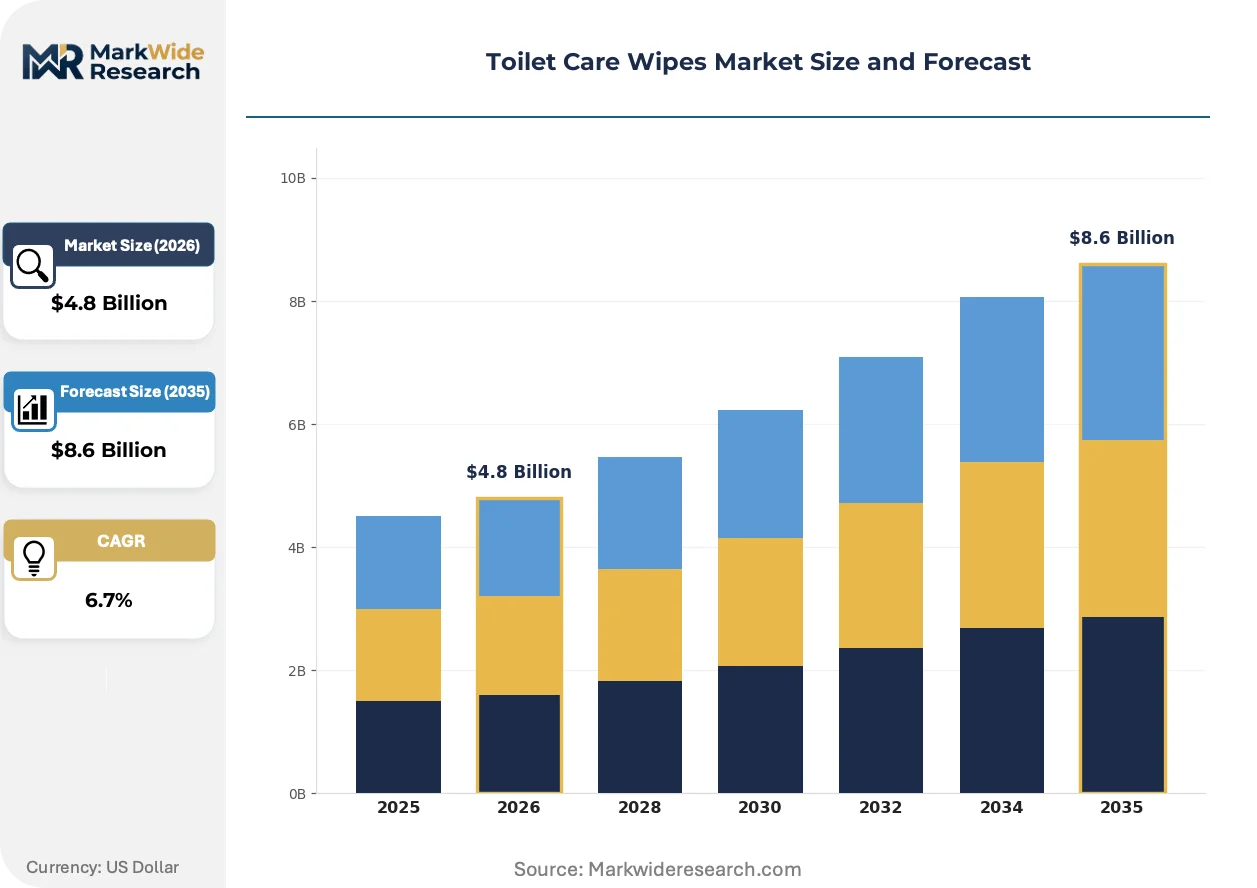
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flushable, Disinfecting, Moisture-Wicking, Antibacterial End User: Households, Commercial Establishments, Healthcare Facilities, Educational Institutions Material: Non-Woven, Cotton, Biodegradable, Synthetic Packaging Type: Resealable Packs, Tubes, Buckets, Single Use |
| Companies Covered | Kimberly-Clark Corporation, The Procter & Gamble Company, Reckitt Benckiser, Unilever, SC Johnson, Clorox Company, Redcliffe Hygiene Private Limited, Dude Products, Inc., Colgate-Palmolive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toilet Care Wipes Market Evolving Landscape
Substrate chemistry and regulatory disclosure requirements are converging to redefine what constitutes a legitimate flushable claim, compressing the viable formulation space for conventional synthetic fibers.
Cellulose-based wet-laid nonwovens with tailored fiber length distributions are electrifying dispersibility performance in municipal wastewater testing. European retail buyers are accelerating qualification timelines for these grades. The technology is compressing market access for legacy polyester-reinforced substrates that fail modified sludge volume index protocols.
ECHA REACH restrictions on isothiazolinone preservatives are forcing reformulation of antimicrobial wipe chemistries across EU member states. Industrial consequence includes accelerated migration to benzoic acid derivatives and phenoxyethanol systems. Healthcare and institutional segments in Germany and France are responding with extended validation cycles for skin-contact compatibility.
Single-unit sachet formats are displacing bulk resealable packs in travel and on-the-go consumption occasions. Convenience retail and airport hospitality channels are capturing volume growth previously concentrated in grocery club packs. This pattern is most visible in Japanese urban markets where vending machine distribution networks extend wipe access beyond traditional retail footprints.
Toilet Care Wipes Market Segmentation
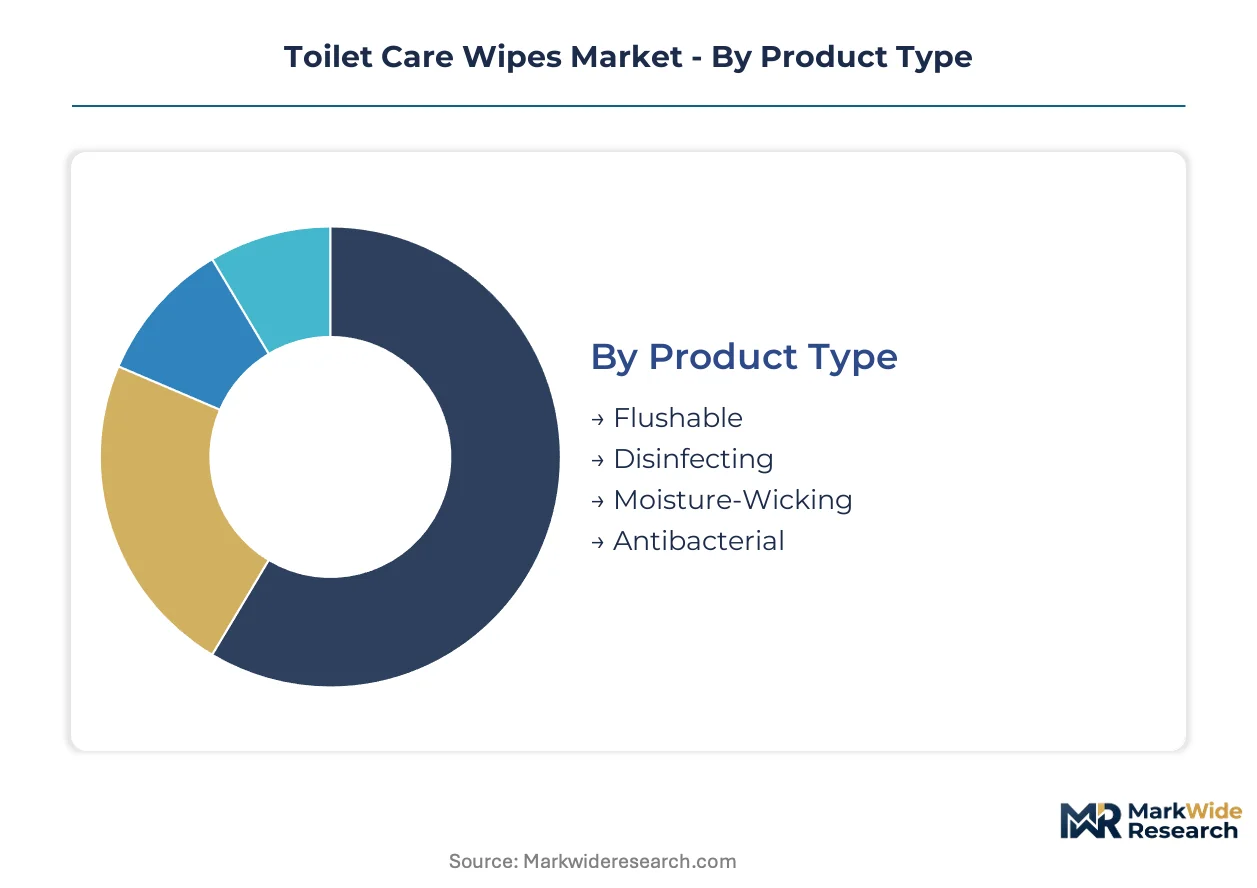
Toilet care wipes manufacturers configure product lines around divergent technical specifications and procurement workflows. Segment boundaries reflect how flushability standards, antimicrobial registration requirements, and institutional purchasing protocols reshape formulation and packaging decisions.
Product Type:
Buyers in this category separate based on dispersibility performance requirements and skin-contact versus surface-application use cases.
- Flushable:Cellulose-based wet-laid nonwovens with tailored fiber length distributions deliver municipal wastewater dispersibility. Demand concentrates in United States club and grocery channels where INDA/EDANA compliance determines shelf access, though older metropolitan sewer systems reject claims regardless of certification.
- Antibacterial:Pre-moistened sheets impregnated with EPA-registered active ingredients target healthcare-associated infection protocols. German and French institutional buyers drive qualification timelines as ECHA REACH restrictions on isothiazolinone preservatives force reformulation toward benzoic acid derivatives.
- Disinfecting:Surface-application formats compete against spray alternatives in European retail; EPA registration timelines stretch 18-36 months for new active ingredients.
- Moisture-Wicking:Premium skin-conditioning formulations reduce irritation during repeated daily use; Japanese household segments adopt advanced chemistries fastest.
Flushable leads volumes today; antibacterial is gaining share fastest.
End User:
Procurement scale and regulatory scrutiny intensity distinguish buyers across this dimension.
- Households:Trial behavior decouples from institutional patterns as single-use sachets unbundle from bulk resealable packs. United States and Western European consumers drive biodegradable fiber adoption as EU Green Deal disclosure requirements reshape shelf composition.
- Healthcare Facilities:Acute care and long-term care facilities favor pre-moistened sheets over spray alternatives for surface disinfection workflows. Infection control protocols in Germany and Japan validate extended skin-contact compatibility cycles for reformulated preservative systems.
- Commercial Establishments:Hospitality and office channels prioritize convenience retail formats; airport distribution networks in Japan extend access beyond traditional retail footprints.
- Educational Institutions:Budget-constrained procurement favors standard antibacterial formats over premium moisture-wicking variants; institutional buyers in United States school districts consolidate volume through cooperative purchasing agreements.
Households dominate absolute consumption; healthcare facilities show steepest expansion trajectory.
Material:
Regulatory pressure on synthetic substrates and fiber cost volatility drive material selection priorities.
- Biodegradable:Cellulose and lyocell grades gain shelf space as EU member states implement mandatory synthetic substrate disclosure. Brazilian and Indonesian dissolving pulp supply basins create cost volatility that compresses margin structures for European converters.
- Non-Woven:Hydroentanglement and thermal bonding processes dominate mass-market production; equipment optimization expertise concentrates among aging technical workforces in European and Japanese machinery suppliers.
- Cotton:Natural fiber positioning commands premium pricing in skin-contact applications; supply chain traceability requirements intensify for United States organic certification segments.
- Synthetic:Polyester-reinforced substrates face modified sludge volume index test failures; legacy formulations retreat to markets without harmonized flushable standards.
Non-woven leads volumes today; biodegradable is climbing the fastest.
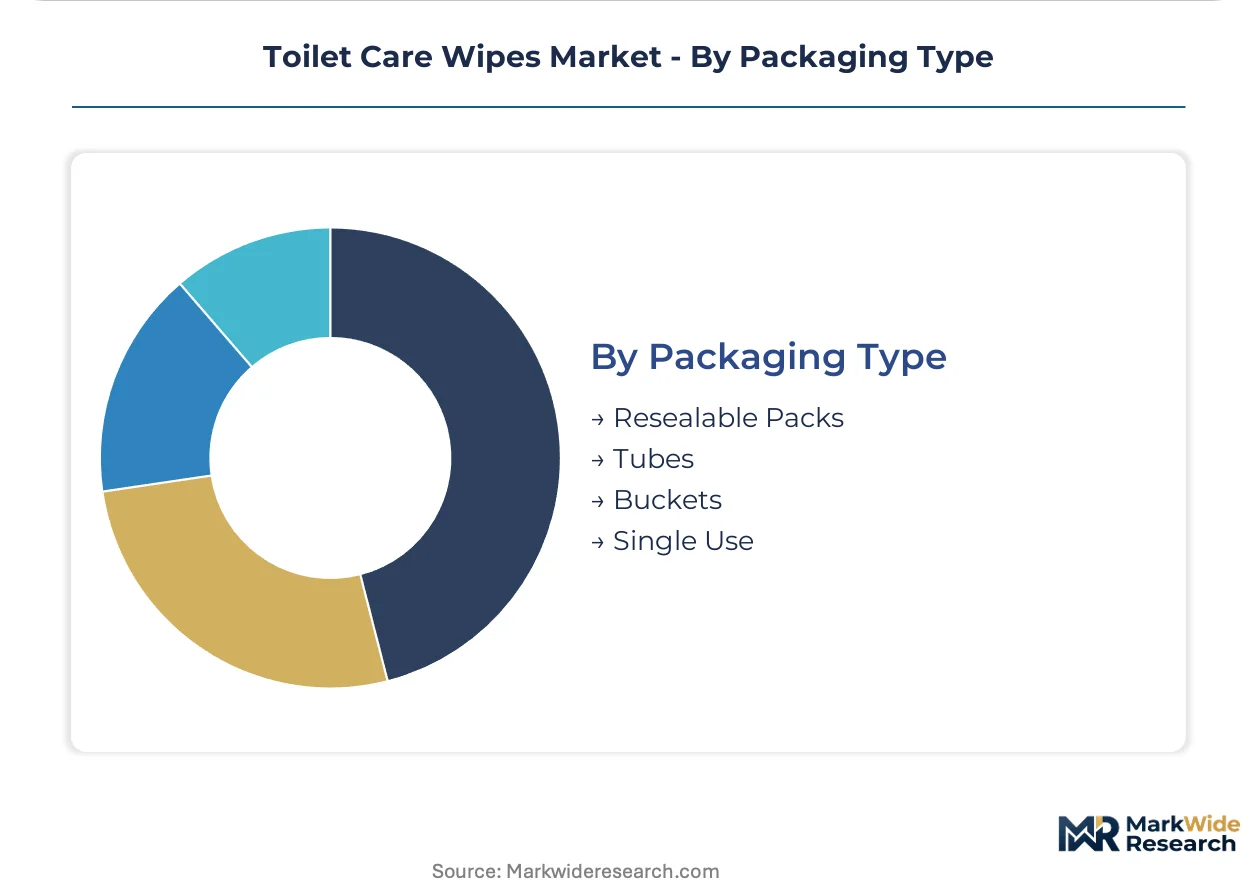
Packaging Type:
Consumption occasion and channel economics determine format selection.
- Single Use:Individual sachets capture travel and on-the-go occasions; Japanese vending machine networks and airport hospitality channels displace volume from traditional grocery club packs.
- Resealable Packs:Bulk formats dominate United States household replenishment cycles; e-commerce subscription bundling bypasses traditional grocery slotting fees.
- Tubes:Compact formats suit premium antibacterial positioning in European mass retail; shelf differentiation against bucket alternatives drives placement decisions.
- Buckets:High-capacity containers target institutional buyers in United States healthcare and educational segments; per-unit economics favor volume procurement patterns.
Resealable packs lead volumes today; single use is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The toilet care wipes industry traces its commercial origins to mid-20th century United States tissue manufacturing, where hydroentanglement technology first enabled mass production of dispersible moistened sheets. From this North American foundation, production expertise diffused to Western Europe and East Asia, creating today's geographically distributed supply base.
United States
Household adoption of flushable formats concentrates in club and grocery channels, with INDA/EDANA compliance determining retail shelf access. EPA registration requirements govern disinfecting claims, while municipal sewer utilities in older metropolitan areas reject flushable certifications regardless of test protocol compliance. Manufacturing clusters in Wisconsin and Georgia anchor North American tissue infrastructure.
Germany
Institutional procurement drives antibacterial segment qualification timelines, with healthcare-associated infection protocols favoring pre-moistened sheets over spray alternatives. ECHA REACH restrictions on isothiazolinone preservatives force preservative system reformulation toward benzoic acid derivatives. Industrial converters in North Rhine-Westphalia specialize in cellulose-based wet-laid nonwovens for dispersibility performance.
Japan
Premium moisture-wicking formats command household adoption through advanced skin-conditioning chemistries that reduce irritation during repeated daily use. Single-unit sachet formats penetrate vending machine distribution networks and airport hospitality channels beyond traditional retail footprints. Manufacturing expertise concentrates in the Kanto region around Tokyo.
China
Swachh Bharat Mission infrastructure investments create first-time access to flush toilet systems in tier-2 and tier-3 cities, expanding addressable household demand. GB/T national standards on flushable dispersibility reduce compliance duplication for domestic suppliers. Production capacity clusters in the Yangtze River Delta serve both domestic retail and export markets.
India
Urban sanitation expansion under national cleanliness programs drives trial behavior among first-time flush toilet users in emerging cities. BIS standards on nonwoven hygiene products govern quality thresholds for domestic manufacturing. Contract manufacturing activity concentrates in Gujarat and Maharashtra for regional brand supply.
Toilet Care Wipes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory certification depth. The market exhibits tiered concentration, with tissue conglomerates controlling mass retail distribution while specialty operators capture niche institutional segments. Three archetypes dominate: integrated tissue conglomerates with captive nonwoven capacity, chemical-specialist formulators with antimicrobial registration expertise, and private-label converters serving regional retail chains. Competitive moves center on substrate certification acceleration and direct-to-consumer channel bypass of traditional grocery slotting fees.
Within the integrated conglomerate tier, Kimberly-Clark Corporation and The Procter & Gamble Company exemplify North American tissue infrastructure leverage, while Reckitt Benckiser occupies a position representing chemical-specialist formulators with European antimicrobial registration depth. These three anchors illustrate how divergent capability foundations—tissue manufacturing scale, consumer brand equity, and disinfectant chemistry expertise—create distinct competitive positions without direct overlap.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| The Procter & Gamble Company |
| Reckitt Benckiser |
| Unilever |
| SC Johnson |
| Clorox Company |
| Redcliffe Hygiene Private Limited |
| Dude Products, Inc. |
| Colgate-Palmolive |
| Others |
Value Network & Pricing Analysis
Healthcare facility procurement consolidation in Germany and the United States anchors contract-based pricing for antibacterial and disinfecting formats, with volume commitments driving tiered structures that separate premium moisture-wicking variants from standard institutional grades. E-commerce subscription bundling introduces parallel direct-to-consumer pricing that bypasses traditional grocery slotting fees and compresses per-unit margins for household flushable formats.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates moisture-wicking skin-conditioning formulations from basic flushable substrates and commodity antibacterial packs. Price differentiation rests on ECHA REACH certification grade for preservative systems and EPA registration status for disinfecting claims. Cost compression in standard flushable tiers is intensifying because Brazilian and Indonesian dissolving pulp supply basins transmit energy price volatility through viscose and lyocell fiber costs. Healthcare facilities show lowest price sensitivity due to infection control protocol mandates, while educational institutions consolidate volume through cooperative purchasing agreements that maximize per-unit leverage.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian and Indonesian dissolving pulp producers that feed European and North American cellulose-based wet-laid nonwoven converters. Raw material dependencies encompass wood pulp grades, antimicrobial active ingredients, and hydroentanglement equipment spares that concentrate among aging technical workforces in European and Japanese machinery suppliers. Supply chain risk manifests as tariff exposure on imported fiber substrates under divergent EU and US trade frameworks. Distribution runs through club and grocery channels for household formats, with direct-to-consumer subscription models gaining share fastest in United States and Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through biodegradable fiber grade adoption as EU Green Deal disclosure requirements compress synthetic substrate shelf space and command premium positioning. E-commerce subscription economics further amplify recurring revenue stability relative to transactional grocery replenishment.
For Market Incumbents: Anchor certification leadership in flushable dispersibility standards to defend against private-label converters exploiting INDA/EDANA compliance gaps. Deepen backward integration into cellulose wet-laid nonwoven capacity in Wisconsin and Georgia manufacturing clusters to offset Brazilian pulp price volatility. Prioritize EPA registration pipeline investment to accelerate antibacterial active ingredient approvals that currently stretch 18-36 months and delay institutional product launches. For New Entrants and Emerging Players: Direct-to-consumer subscription bundling offers the most penetrable route to bypass traditional grocery slotting fees and capture recurring household replenishment revenue. Target tier-2 and tier-3 Indian cities where Swachh Bharat Mission sanitation infrastructure creates first-time flush toilet access and unbranded trial behavior. Lead with single-use sachet formats in Japanese vending machine distribution networks and airport hospitality channels that extend beyond established retail footprints. For Investors and Strategic Acquirers: Chemical-specialist formulators with antimicrobial registration depth are the most active acquirer in this space, seeking tissue manufacturing scale to complete integrated capability platforms. Long-term viability hinges on biodegradability certification assets that appreciate under tightening ECHA REACH and EU Green Deal frameworks. Watch for GB/T flushable standard harmonization in China as an inflection indicator that reduces compliance duplication and accelerates domestic supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Fiber Transition | ECHA REACH restrictions on synthetic substrates compel cellulose and lyocell grade adoption across EU member states. |
| Direct-to-Consumer Launch | Subscription bundling bypasses grocery slotting fees while capturing recurring revenue from household replenishment cycles. |
| EPA Registration Acceleration | Compressed approval timelines for antimicrobial active ingredients unlock institutional healthcare procurement volumes faster. |
| Backward Integration into Pulp Supply | Captive dissolving pulp sourcing insulates margin structures from Brazilian and Indonesian energy price volatility. |
| Single-Use Sachet Expansion | Vending machine networks in Japanese urban markets extend product access beyond traditional retail channel constraints. |
Research Methodology
Multiple input streams — primary interviews with brand managers and category buyers at retailers, technical R&D directors at nonwoven converters, and supply planners at tissue manufacturers — were reconciled against secondary validation from customs records, Nielsen retail audit data, EPA registration databases, and ECHA REACH substance filings. Bottom-up and top-down triangulation cross-referenced production capacity announcements with channel shipment patterns across household, healthcare, and institutional end-use segments.
Historical volume trajectories were cross-referenced against panel input from procurement officers at German healthcare facilities and Japanese vending machine operators to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled encompass product type, end-user procurement protocol, material grade tier, packaging format, and regional regulatory cluster. CAGRs were derived from fitted trend lines adjusted for ECHA preservative restrictions and GB/T standard harmonization milestones. Industry-specific forecast inputs included dissolving pulp price indices and municipal sewer infrastructure capacity constraints in older US metropolitan areas.
The model assumes a particular technology adoption path; alternative pathways for cellulose-based wet-laid nonwoven dispersibility would alter the outlook if modified sludge volume index protocols diverge further between North American and European test standards. Forecasts reflect assumptions about EU Green Deal implementation pace and Swachh Bharat Mission infrastructure rollout timing that could accelerate or delay addressable demand expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Portable Humidifiers Market
Household Items
North America Tankless Water Heater Market
Household Items
Party Supplies Market
Household Items
Industrial Vacuum Cleaner Market
Household Items
Smart Drying Racks Market
Household Items
North America B2B Air Care Market
Household Items
Barbeque Grill Market
Household Items
Robot Mops Market
Household Items
Soap Tablet Market
Household Items
Multi Pocket Holders Market
Household Items
France Digital Showers Market
Household Items
US Soap Dispenser Market
Household Items
Disposable Napkins Market
Household Items
Integrated Smart Toilet Market
Household Items
Window Rain Guards Market
Household Items
Asia Pacific Residential Vacuum Cleaners Market