
 Face Steaming Devices Market | 2026-2036
Face Steaming Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Face Steaming Devices Market Analytics
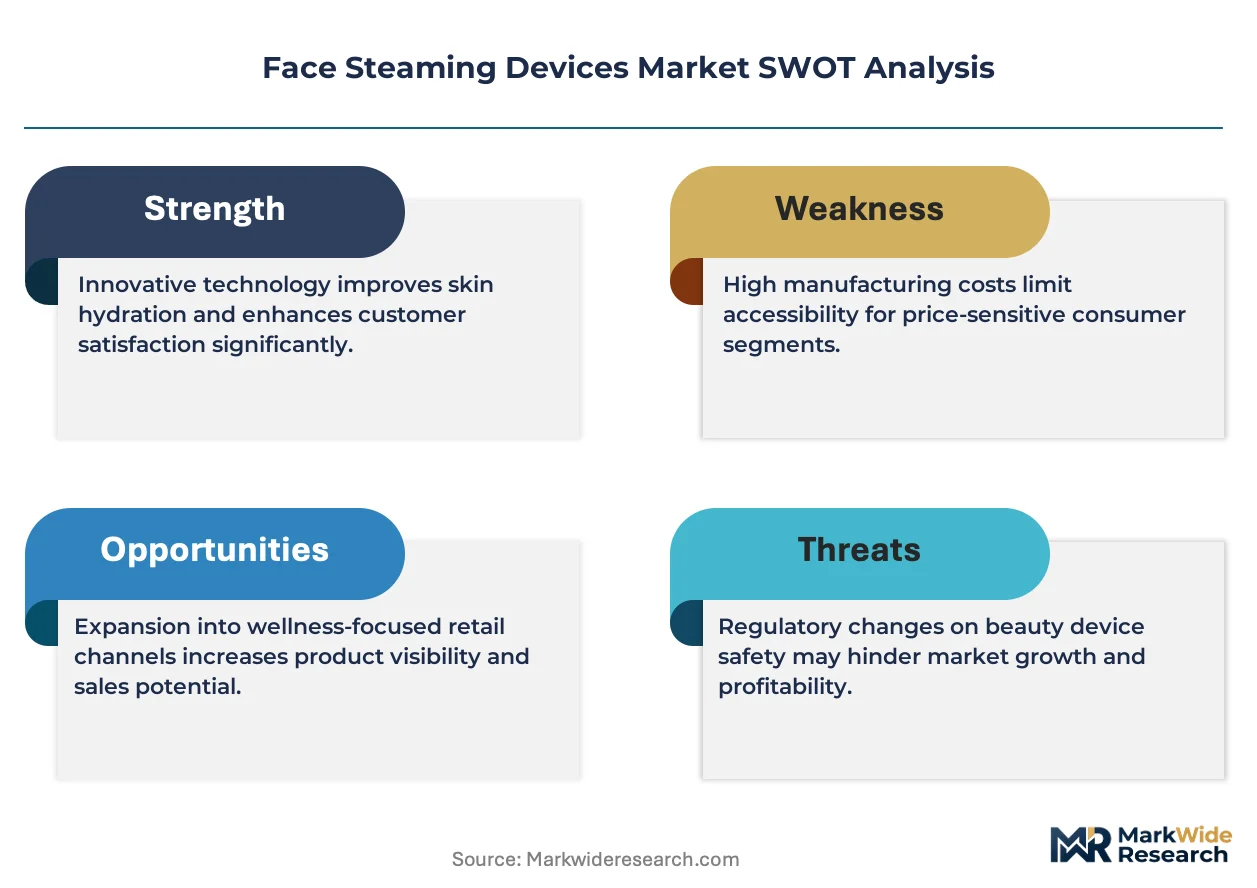
REACH is hardening material compliance costs for polycarbonate and ABS housings used in face steaming devices. Panasonic Corporation leverages its in-house ceramic heating element production to absorb these regulatory burdens without outsourcing. Conair Corporation anchors its competitive stance through mass-market channel control across North American big-box retail. Kingdom Beauty differentiates by specializing in compact ultrasonic units targeting Asian travel retail corridors.
Face steaming devices are thermal skincare appliances that generate controlled water vapor at temperatures between 40°C and 50°C to dilate pores and enhance topical absorption. Nano-ionic technology dominates the premium tier by producing finer vapor particles that penetrate deeper into skin layers than conventional steam-based units. Portable steamers represent the fastest-growing product type as consumers prioritize post-pandemic home beauty routines over salon visits. Online retail channels capture expanding margin pools through direct-to-consumer subscription models and influencer-driven conversion funnels.
EMA cosmetic device guidelines, FDA electrical appliance standards, and China's GB standards collectively shape product certification requirements across major manufacturing and consumption zones. These frameworks force manufacturers to maintain parallel testing protocols, raising fixed costs for multi-region entrants. Stakeholders must monitor evolving dermatological device reclassifications in Europe and Asia that could shift face steamers from cosmetic to medical-grade regulatory tiers.
Market Dynamics
REACH compliance in Europe is hardening material safety requirements for polycarbonate and ABS housings, forcing manufacturers to absorb elevated testing costs or redesign heating element enclosures around ceramic alternatives.
Growth Catalysts
- MFDS cosmetic device guidelines:South Korea's aesthetic clinic density creates concentrated demand for professional-grade nano-ionic units, with at-home beauty device penetration sustaining parallel consumer market expansion.
- Post-pandemic home beauty routines:Portable steamers capture preference shifts as consumers prioritize convenience over salon visits, compressing replacement cycles for tabletop units.
- Influencer-driven conversion funnels:Direct-to-consumer subscription models through online retail channels capture expanding margin pools by bypassing traditional distributor markups.
Market Restraints
- Ceramic heating element supply concentration:In-house production capabilities remain limited to established appliance manufacturers, constraining new entrant scale-up.
- Polycarbonate price volatility:Petrochemical feedstock fluctuations elevate housing material costs unpredictably, compressing margin buffers for mass-market positioning.
- Conventional steam-based technology:Older vapor generation methods face substitution pressure from nano-ionic alternatives, stranding inventory and tooling investments.
Strategic Opportunities
- Asian travel retail corridors:Compact ultrasonic units target duty-free channels where portability commands premium positioning against full-size alternatives.
- Dual carbon goals:China's energy efficiency mandates create regulatory tailwind for low-wattage ceramic heating designs in manufacturing and procurement.
- Dermatology clinic expansion:Professional-grade device fleets in medical-aesthetic settings open recurring revenue streams through maintenance contracts and consumable attachments.
Industry Challenges
- Parallel testing protocols:EMA cosmetic device guidelines, FDA electrical appliance standards, and China's GB standards force redundant certification expenditures for multi-region entrants.
- Reclassification risk:Evolving dermatological device tiers in Europe and Asia threaten to shift face steamers from cosmetic to medical-grade regulatory categories, extending approval timelines.
- Heating element thermal calibration:Precision engineering for 40°C-50°C vapor output requires specialized talent scarce outside established appliance manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Steaming Devices Market |
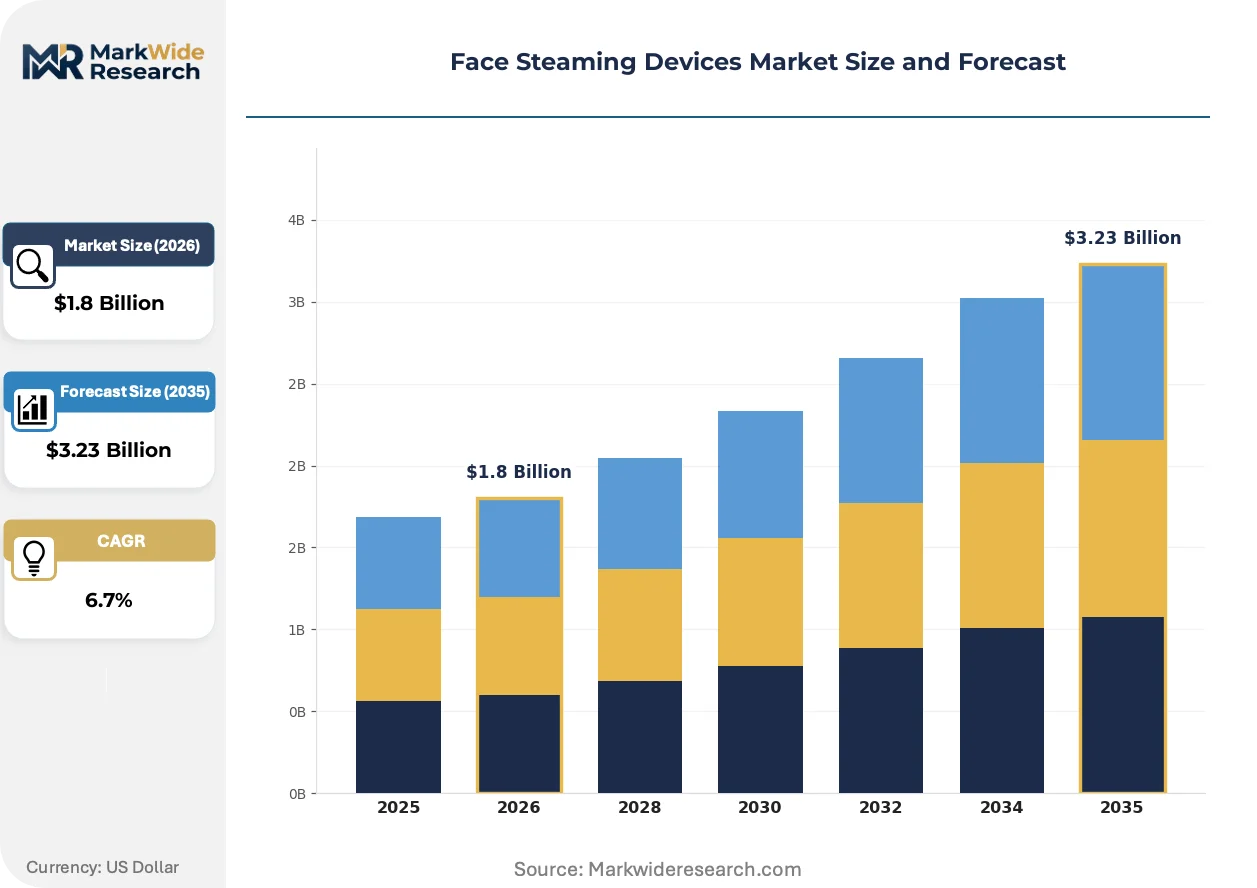
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Steamer, Tabletop Steamer, Multi-Function Device, Personal Steamer End User: Households, Salons, Spas, Dermatology Clinics Technology: Ultrasonic, Infrared, Nano-Ionic, Steam-Based Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Panasonic Corporation, Conair Corporation, Revlon Inc., Beurer GmbH, Kingdom Beauty, Secura, Vanity Planet, Dr. Dennis Gross Skincare, Pure Daily Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Steaming Devices Market Evolving Landscape
Nano-ionic vapor generation is actively compressing competitive differentiation around particle size and penetration depth, while regulatory fragmentation and channel disintermediation reshape how value flows to end users.
Ceramic heating elements generate controlled thermal output with superior energy efficiency compared to metal coil alternatives. Dermatology clinics and premium consumer segments are adopting these units at accelerated replacement cycles. This technology is overtaking conventional steam-based designs by enabling finer vapor particle control that penetrates deeper skin layers.
REACH substance restrictions are elevating compliance costs for polycarbonate and ABS housing materials across European manufacturing. Industrial consequence includes accelerated migration toward ceramic enclosures and in-house heating element production. Premium-tier manufacturers with captive ceramic capabilities absorb these burdens most effectively, widening capability gaps against outsourced competitors.
Subscription-based direct-to-consumer models are compressing traditional distributor margins by capturing recurring revenue through consumable attachments and replacement cycles. Mass-market channels face disintermediation pressure as influencer-driven conversion funnels shift purchase decisions toward brand-owned digital storefronts. This pattern concentrates in North American and South Korean markets where social commerce penetration exceeds regional benchmarks.
Face Steaming Devices Market Segmentation
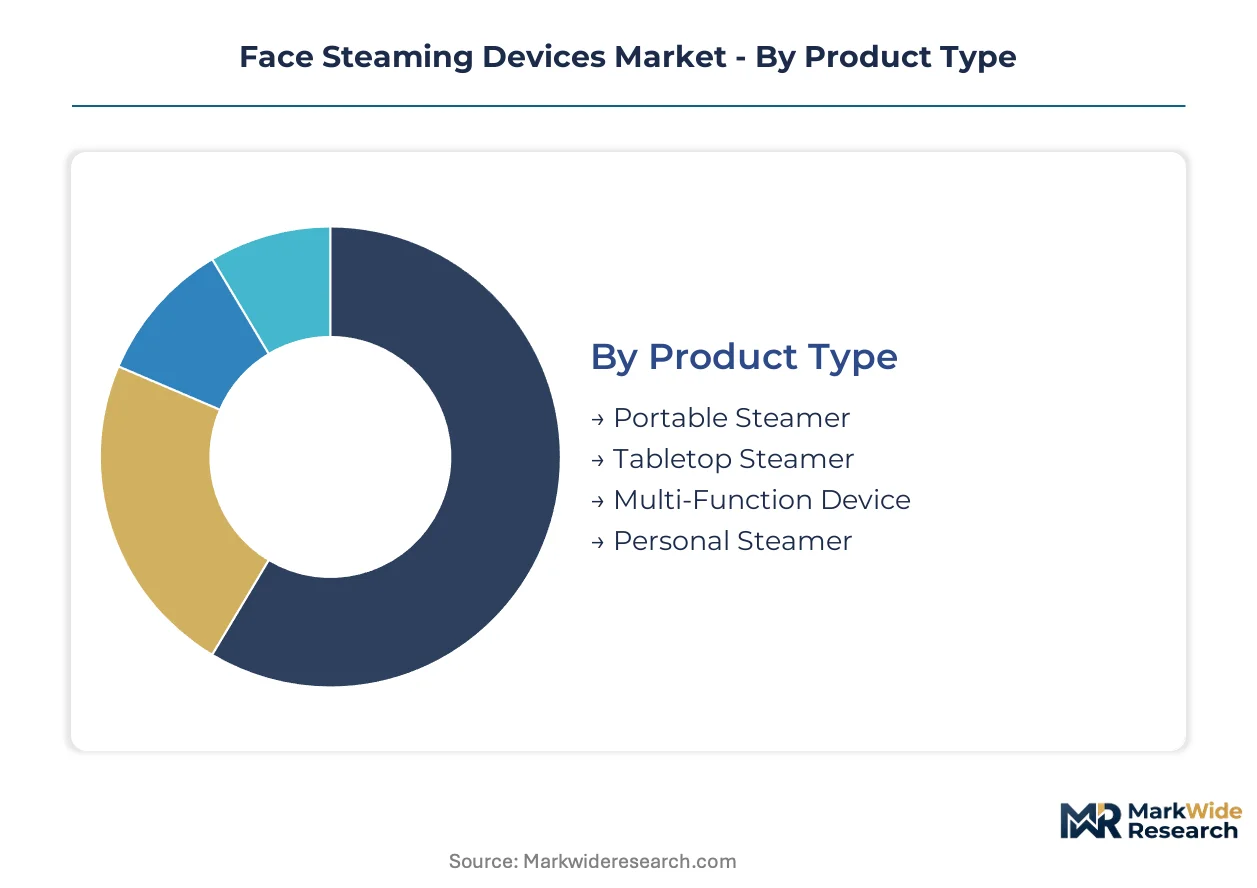
Segmentation in face steaming devices reveals divergent margin structures across portability tiers and regulatory exposure across channel strategies. Technology differentiation separates premium ceramic heating architectures from mass-market metal coil alternatives.
Product Type:
Volume concentrates in compact formats for home use, while premium pricing attaches to professional-grade stationary units with precision thermal calibration.
- Portable Steamer:Battery-powered or corded compact units weighing under 500 grams, engineered for travel and countertop flexibility. Demand clusters in South Korean at-home beauty routines and Asian duty-free corridors where portability commands price premiums against full-size alternatives. Post-pandemic convenience preferences compress replacement cycles for tabletop units.
- Tabletop Steamer:Stationary units with integrated water reservoirs and adjustable arm assemblies for seated facial positioning. Dermatology clinics in Seoul and Tokyo deploy these for pre-treatment pore dilation protocols, with ceramic heating elements enabling precise 40°C-50°C vapor output control.
- Multi-Function Device:Hybrid appliances combining steam generation with LED therapy or extraction tooling.
- Personal Steamer:Entry-level single-purpose units targeting first-time buyers through mass-market retail placement.
Mature deployment sits with Tabletop Steamer units in professional settings. Newer deployment is concentrated in Portable Steamer formats for home beauty routines.
End User:
Application context determines thermal precision requirements and replacement cycle frequency, with medical-aesthetic settings demanding certified calibration protocols.
- Households:Consumer-grade units prioritize safety interlocks and intuitive controls for unsupervised operation. South Korean and Japanese households lead penetration rates for at-home beauty device adoption, sustaining parallel consumer market expansion alongside professional channels.
- Dermatology Clinics:Medical-aesthetic settings require FDA-cleared or CE-marked devices with documented thermal output consistency. These facilities generate recurring revenue through maintenance contracts and consumable attachment replacement programs.
- Salons:Commercial beauty operators balance durability demands against capital expenditure constraints.
- Spas:Wellness-oriented facilities integrate steam treatments into broader service protocols.
Established procurement patterns dominate Dermatology Clinics. Expanding most quickly among Households as post-pandemic home beauty routines solidify.
Technology:
Heating architecture separates efficiency leaders from legacy designs facing substitution pressure.
- Nano-Ionic:Ceramic-driven vapor generation producing sub-micron particles for enhanced epidermal penetration. Premium consumer segments and professional clinics in South Korea adopt these units at accelerated replacement cycles, displacing conventional steam-based alternatives.
- Ultrasonic:High-frequency oscillation creates fine mist without thermal elevation, targeting sensitive skin applications. Compact ultrasonic units capture positioning in Asian travel retail corridors where duty-free channels favor portable formats.
- Infrared:Radiant heat supplementation for enhanced circulation effects.
- Steam-Based:Conventional boiler-element vapor generation facing inventory stranding as nano-ionic alternatives gain share.
Technology leadership concentrates in Nano-Ionic formats. Infrared and Steam-Based architectures face margin compression from substitution dynamics.
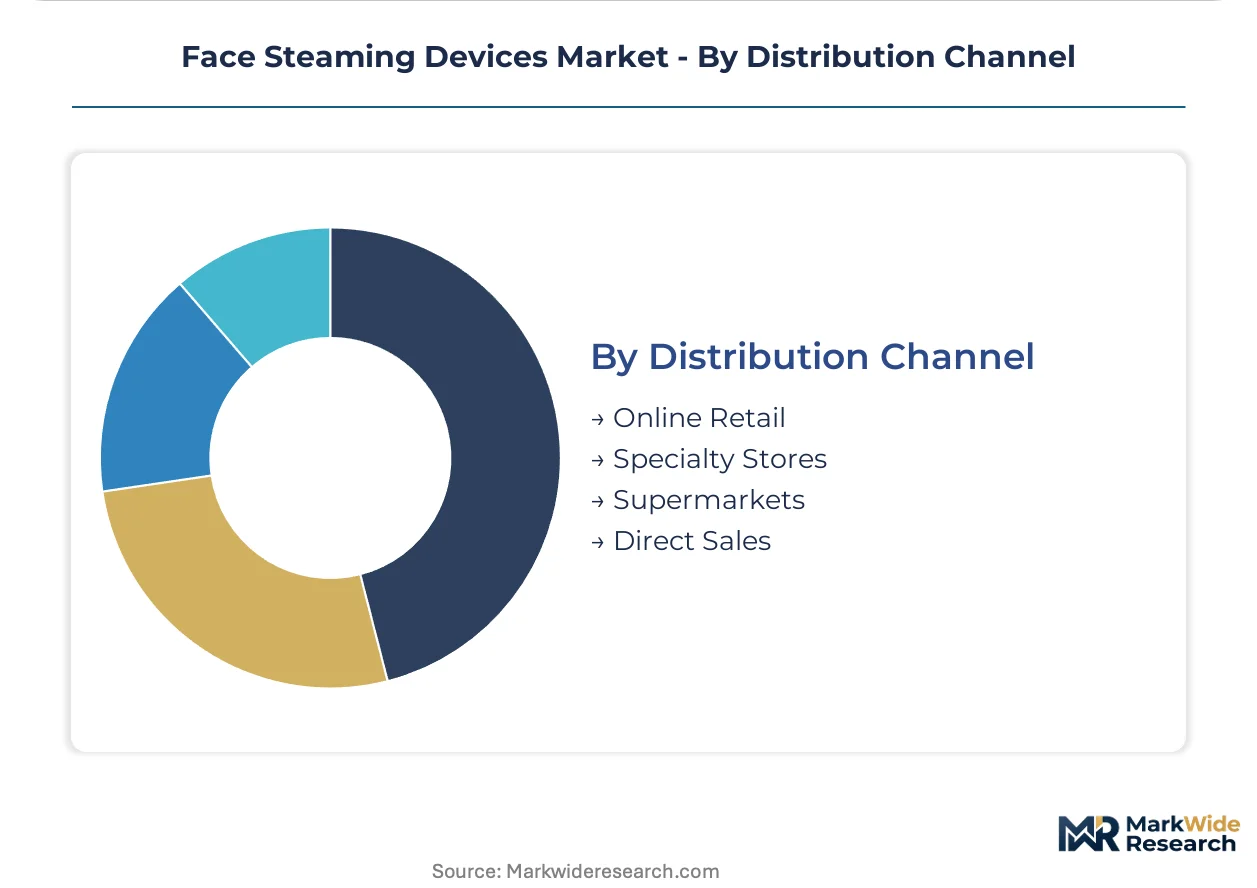
Distribution Channel:
Channel selection determines margin capture and regulatory documentation requirements.
- Online Retail:Direct-to-consumer subscription models bypass traditional distributor markups through influencer-driven conversion funnels. North American and South Korean markets concentrate this pattern where social commerce penetration exceeds regional benchmarks.
- Specialty Stores:Curated beauty retailers provide tactile evaluation and staff consultation for premium-tier selection.
- Supermarkets:Mass-market placement drives volume for entry-level personal steamers.
- Direct Sales:Manufacturer-owned channels serving professional clinic procurement with maintenance contract bundling.
Margin expansion concentrates in Online Retail. Direct Sales channels sustain professional-grade volume with attached service revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for face steaming devices concentrates in East Asian markets where aesthetic clinic density and at-home beauty device penetration sustain dual growth vectors. South Korea and Japan anchor professional-grade procurement, while China and the United States drive volume expansion through e-commerce channels.
South Korea
Seoul's Gangnam district hosts the world's densest concentration of medical-aesthetic clinics, generating sustained demand for nano-ionic tabletop steamers with precision thermal calibration. MFDS cosmetic device guidelines enforce rigorous documentation for professional-grade equipment, elevating compliance barriers for imported alternatives. Busan-Ulsan manufacturing clusters supply ceramic heating elements to domestic brands serving both clinic and household segments.
Japan
Tokyo's metropolitan households lead at-home beauty device adoption rates, compressing replacement cycles for portable steamers through continuous product refresh. METI energy efficiency standards favor low-wattage ceramic heating designs in manufacturing and procurement. Osaka-based appliance fabricators integrate steam generation with broader personal care portfolios, capturing recurring revenue through consumable attachment programs.
United States
Direct-to-consumer subscription models through influencer-driven channels capture expanding margin pools in California and New York metro areas. FDA electrical appliance standards mandate parallel testing protocols for multi-region entrants, elevating fixed costs for new market participants. Los Angeles beauty districts concentrate social commerce penetration that shifts purchase decisions toward brand-owned digital storefronts.
China
Yangtze River Delta manufacturing clusters produce ceramic heating elements for both domestic consumption and export markets, leveraging captive supply capabilities. Dual carbon goals create regulatory tailwind for energy-efficient device designs in government procurement and state-owned retail channels. Shenzhen-based electronics assemblers specialize in compact ultrasonic units targeting Asian duty-free corridors.
Germany
REACH substance restrictions elevate compliance costs for polycarbonate housings, accelerating migration toward ceramic enclosures among premium-tier manufacturers. EMA cosmetic device guidelines maintain classification clarity that prevents medical-grade reclassification risks for professional clinic equipment. Bavarian industrial zones concentrate precision engineering talent for thermal calibration systems operating at 40°C-50°C vapor output ranges.
Face Steaming Devices Market Competitive Landscape
East Asian producers anchor the premium technology tier; European specialists hold regulatory compliance advantages. The vendor base stratifies across three structural layers: diversified appliance conglomerates with captive ceramic capabilities, pure-play beauty device specialists, and contract manufacturers serving private-label brands. Two dominant competitive moves define current positioning: backward integration into heating element production and channel disintermediation through direct-to-consumer digital storefronts.
Within the diversified conglomerate tier, Panasonic Corporation exemplifies geographic diversification across manufacturing clusters, while Conair Corporation anchors mass-market positioning through big-box retail channel control. Kingdom Beauty occupies a specialist position targeting compact formats for travel retail corridors. These three entities collectively represent the strategic archetype spectrum: integrated technology leadership, mass-market scale operations, and niche portability specialization.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Conair Corporation |
| Revlon Inc. |
| Beurer GmbH |
| Kingdom Beauty |
| Secura |
| Vanity Planet |
| Dr. Dennis Gross Skincare |
| Pure Daily Care |
| Others |
Value Network & Pricing Analysis
Ceramic heating element adoption is compressing cost economics for premium-tier manufacturers while concentrating supply leverage among producers with in-house thermal engineering capabilities. This technology transition simultaneously elevates fixed investment barriers and rewards backward-integrated players with margin absorption capacity against polycarbonate price volatility.
Pricing Analysis
Volume-mass positioning captures entry-level household demand through supermarket channels, while margin concentration attaches to professional-grade tabletop units with MFDS certification and maintenance contract bundling. Three-tier pricing structure across premium nano-ionic, standard ceramic, and economy metal-coil levels separates certification grade from performance tier. Pricing pressure stems from REACH compliance elevating polycarbonate housing costs unpredictably. Household buyers exhibit highest price sensitivity; dermatology clinics prioritize thermal calibration precision over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for ceramic heating elements compel manufacturers to qualify suppliers across South Korea, Japan, and China simultaneously. Raw material dependencies center on alumina ceramic substrates, polycarbonate resin, and precision temperature sensors. Supply chain risk concentrates in single-source vulnerability for sub-micron vapor generation nozzles. Distribution runs through brand-owned digital storefronts and duty-free corridors alongside traditional appliance retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around regulatory compliance burdens and captive ceramic production capabilities, forcing outsourced heating element assemblers toward exit or acquisition.
For Market Incumbents: Hedge against REACH-driven material cost volatility by accelerating ceramic enclosure migration and locking multi-year alumina supply agreements with Busan-Ulsan clusters. Defend channel position by bundling preventive maintenance contracts with professional-grade tabletop deployments in Seoul and Tokyo aesthetic clinics. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting North American social commerce corridors, bypassing distributor markups that compress mass-market viability. Prioritize compact ultrasonic formats for Asian travel retail white space where portability premiums exceed full-size alternatives. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified appliance conglomerates seeking ceramic heating element capabilities. Long-term viability favors targets with in-house thermal engineering talent and established MFDS documentation. Watch for EMA reclassification signals that would shift face steamers into medical-grade approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Heating Element Backward Integration | Captive alumina ceramic production absorbs REACH compliance costs without margin erosion. |
| Direct-to-Consumer Subscription Launch | Influencer-driven conversion funnels bypass traditional distributor markups in California and New York metros. |
| MFDS Certification Investment | Professional-grade documentation opens Seoul dermatology clinic procurement with attached service revenue. |
| Compact Ultrasonic Product Extension | Travel retail portability commands duty-free premium positioning against full-size alternatives. |
| Maintenance Contract Bundling | Recurring revenue streams from consumable attachments stabilize clinic segment cash flows. |
Research Methodology
Trade databases, customs records, and appliance industry association filings formed the secondary backbone, cross-referenced against primary interviews with dermatology clinic procurement managers, ceramic heating element plant engineers, beauty device brand managers, and duty-free channel buyers. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Historical trendline analysis for nano-ionic and steam-based technology segments established baseline penetration curves across the projection horizon. Segmentation modeling incorporated product type, end-user application, heating architecture, and distribution channel dimensions. CAGRs derived from weighted technology substitution rates and regional regulatory adoption patterns, with ceramic heating element cost curves and social commerce penetration indices as primary forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for ultrasonic vapor generation would alter the outlook if travel retail demand shifts toward non-thermal formats. Deviation in EMA or MFDS reclassification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Slimming Cream Market
Beauty & Personal Care
Beauty Devices Market
Beauty & Personal Care
Australia Skin Care Products Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Global Organic Hair Color Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market
Beauty & Personal Care
Natural Deodorant Crystal Market
Beauty & Personal Care
Canada Dermocosmetics Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
United Kingdom Hair Care Market
Beauty & Personal Care
Wrinkle Release Spray Market
Beauty & Personal Care
Stretch Mark Removal Products Market
Beauty & Personal Care
Eyelash Curler Market
Beauty & Personal Care
Spas and Beauty Salons Market
Beauty & Personal Care
India Herbal Shampoo Market