
 Kids Shampoo Market | 2026-2036
Kids Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Shampoo Market Foresight
Contract manufacturers in South Korea is recalibrating production lines to meet surging private-label orders from Western retailers. Johnson & Johnson sustains broad pharmacy and hospital channel penetration through its heritage pediatric positioning. Procter & Gamble leverages massive consumer research infrastructure to optimize fragrance-free and tear-free formulations. The Honest Company differentiates through clean-ingredient storytelling and direct-to-parent digital engagement.
Kids shampoo denotes a mild surfactant-based cleansing formulation engineered for pediatric scalp physiology, typically featuring pH-balanced chemistry between 4.5 and 5.5, reduced eye irritancy via amphoteric or nonionic surfactant systems, and exclusion of parabens, sulfates, and synthetic dyes to accommodate developing skin barriers. Liquid formats dominate mass retail velocity due to familiar usage patterns and dispenser compatibility, while foam variants are gaining fastest traction among toddlers as parents prioritize rinse speed and reduced slip hazards during bath time. Organic ingredient positioning commands premium shelf placement and margin pools, though SLS-free claims now function as baseline hygiene rather than differentiation in specialty channels.
FDA cosmetic labeling requirements and the EU's REACH framework govern ingredient disclosure thresholds and prohibited substance lists, compelling reformulation cycles that extend R&D timelines by twelve to eighteen months. The EU AI Act's emerging transparency mandates will eventually pressure automated manufacturing lines to document algorithmic quality-control decisions for export batches. Stakeholders must monitor evolving pediatric dermatology consensus on microbiome-friendly preservatives, as this scientific frontier will likely reshape acceptable ingredient panels before regulatory bodies codify standards.
Market Dynamics
REACH reformulation mandates and the EU AI Act's emerging transparency requirements are compressing R&D cycles while elevating compliance costs for pediatric personal care manufacturers serving Western markets.
Growth Catalysts
- Pediatric Dermatology Channel Expansion:Family wellness centers in the United States and Germany are dedicating expanded retail shelf space to clinically positioned children's hair care, creating dedicated distribution corridors for pH-balanced formulations.
- REACH-Driven Clean Label Migration:ECHA's tightening substance restrictions are forcing ingredient panel simplification, which premium brands leverage for margin expansion through transparency storytelling.
- Amphoteric Surfactant Substitution:Nonionic and betaine-based cleansing chemistry is displacing traditional anionic systems in tear-free formulations, reducing eye irritancy litigation exposure for manufacturers.
Market Restraints
- Certified Organic Input Scarcity:Cold-pressed botanical surfactant supplies from South American cooperatives face harvest volatility, compressing gross margins for organic-positioned SKUs by fifteen to twenty-five percent during drought cycles.
- Preservative Regulatory Friction:FDA's evolving stance on MIT/CMIT isomers and EU restrictions on phenoxyethanol concentration are eliminating established preservation systems before microbiome-friendly alternatives achieve commercial scale.
- Private-Label Margin Compression:Contract manufacturers in South Korea and Taiwan are absorbing Western retailer procurement consolidation, eroding branded pricing power in mass pharmacy channels.
Strategic Opportunities
- Microbiome-Friendly Preservation White Space:Pediatric dermatology consensus on scalp flora compatibility is outpacing regulatory codification, creating first-mover advantage for brands investing in postbiotic preservation R&D ahead of FDA guidance.
- Foam Format Channel Innovation:Direct-to-parent subscription models and pediatric clinic dispensing systems are bypassing traditional mass retail velocity requirements for rinse-speed-optimized toddler formulations.
- US Premium Natural Segment Concentration:California and New York metropolitan markets exhibit sustained pricing power for clean-ingredient storytelling, with household penetration in these clusters running triple the national average.
Industry Challenges
- Twelve-to-Eighteen Month Reformulation Timelines:Cross-jurisdictional compliance with FDA cosmetic labeling and REACH substance restrictions requires parallel toxicology testing, extending product development cycles beyond competitive windows.
- Pediatric Formulation Chemist Scarcity:Specialized expertise in amphoteric surfactant stabilization and pediatric skin barrier science commands premium compensation, constraining mid-tier manufacturer R&D bandwidth.
- Automated Quality Control Documentation:EU AI Act algorithmic transparency mandates for export batches are forcing manufacturing line upgrades before regulatory technical standards finalize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Shampoo Market |
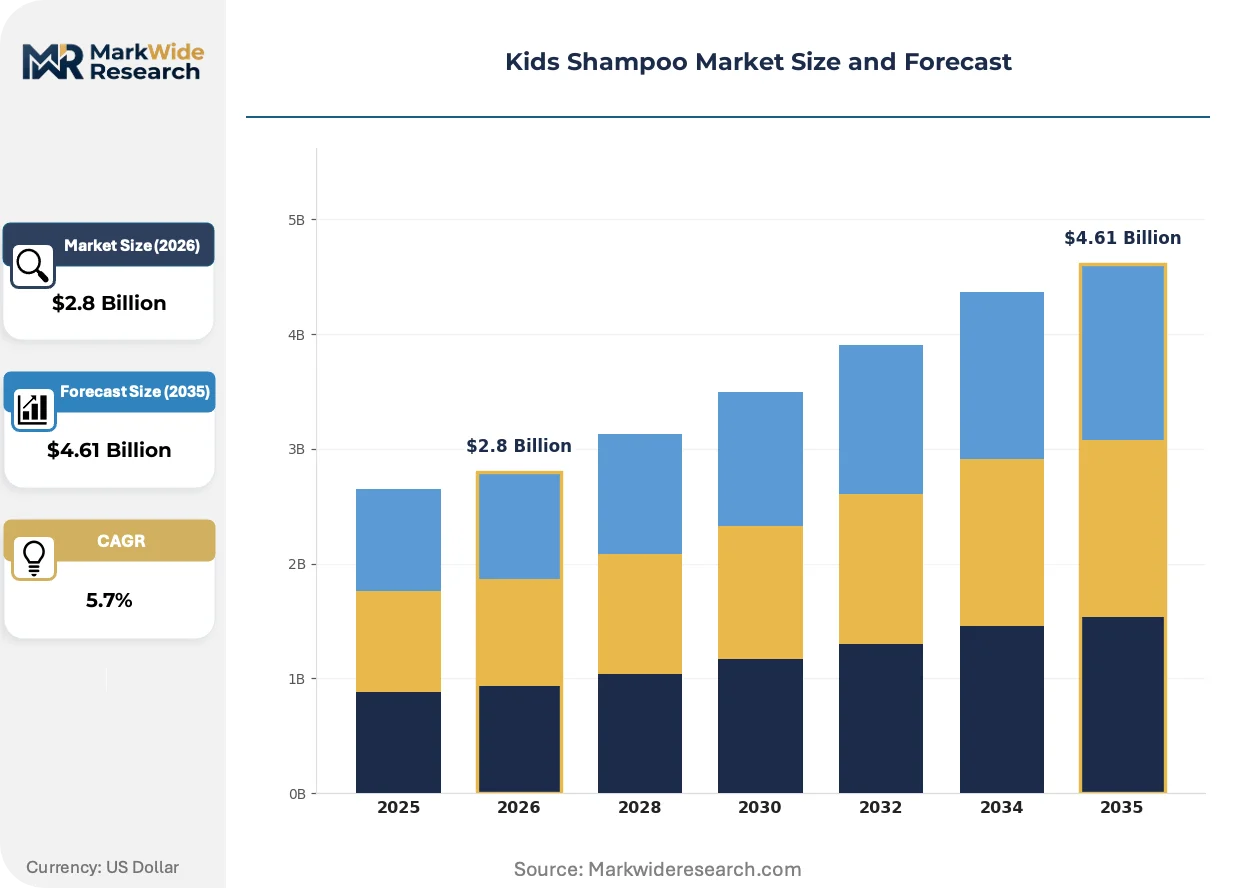
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Foam, Gel, Bar, Powder Age Group: Toddlers, Preschoolers, Early School Age, Tweens Ingredient Type: Natural, Organic, Paraben-Free, SLS-Free Packaging Type: Bottles, Tubes, Pump Dispensers, Sachets |
| Companies Covered | Johnson & Johnson, California Baby, Procter & Gamble, Shiseido, KOSE, Unilever, The Honest Company, Colgate-Palmolive, L'Oreal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Shampoo Market Shifts & Advancements
Formulation chemistry, regulatory transparency mandates, and parent purchasing behavior are converging to reshape competitive positioning in pediatric personal care, with technology adoption cycles compressing from years to months.
Postbiotic preservation systems incorporating lysed lactobacillus ferments and antimicrobial peptides are rewriting acceptable ingredient panels for microbiome-compatible children's cleansing products. Premium positioned manufacturers in Germany and the United States are accelerating pilot production, while mass-market brands face twelve-to-eighteen month catch-up timelines to achieve equivalent shelf stability without traditional preservatives. This technology is rewriting the competitive moat around clinical credibility in pediatric dermatology channels.
ECHA's 2024 updates to REACH candidate list substance restrictions are eliminating residual formaldehyde releasers and certain quaternary ammonium compounds from EU-export formulations. Manufacturers serving both US and European markets are consolidating to unified global SKUs rather than maintaining regional variants, compressing portfolio complexity but elevating per-unit compliance investment. Specialty retailers in France and the Netherlands are responding by demanding third-party certification ahead of mandatory deadlines.
Parent purchasing for children's personal care is fragmenting across telehealth-integrated subscription platforms and pediatric clinic point-of-sale dispensing, displacing traditional supermarket and pharmacy aisle discovery. Direct-to-parent digital engagement models in the United States are capturing trial-sized conversion through dermatologist endorsement content, while mass retailers respond with exclusive clean-label private-label development. This behavioral rotation is most visible in coastal US metropolitan markets where household penetration of subscription-based children's care exceeds twenty percent.
Kids Shampoo Market Segmentation
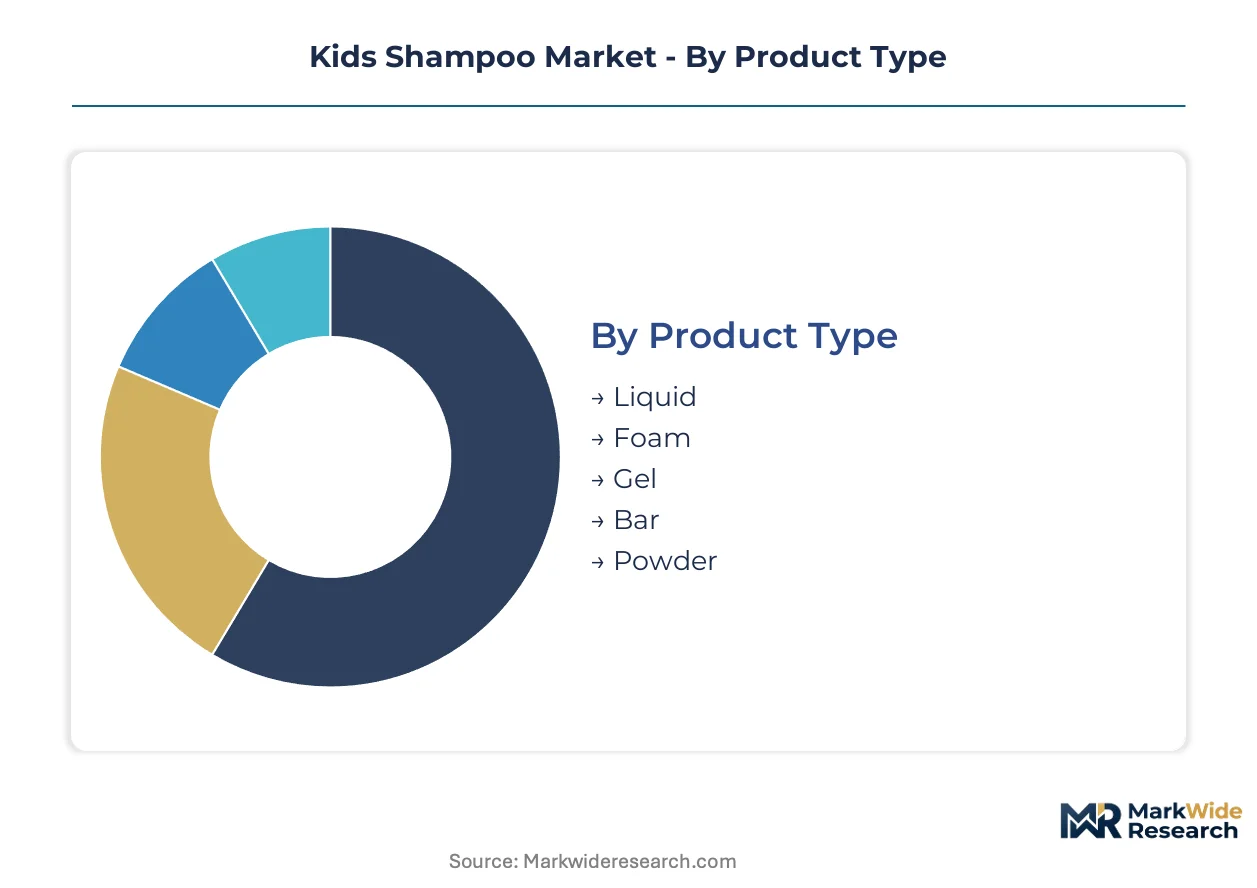
Pediatric hair care purchasing patterns diverge sharply across formulation formats, developmental stages, and ingredient positioning. Parents upgrade products as children age, creating distinct replacement cycles that manufacturers must map precisely to capture lifetime value.
Product Type:
Foam formats are accelerating replacement cycles among toddler households seeking faster rinse protocols, while liquid formats sustain longer usage tenures through dispenser compatibility and familiar application rituals.
- Liquid:Conventional surfactant suspensions in viscous aqueous bases dominate pharmacy and mass retail velocity through established pump-dispenser infrastructure and parental familiarity. Demand concentrates in United States suburban households where multi-child families prioritize economy-size packaging and extended product longevity.
- Foam:Pre-aerated mousse formulations reduce water contact time and slip hazards during toddler bathing, driving premium positioning. Direct-to-parent subscription channels in California and New York metropolitan clusters capture conversion through rinse-speed messaging and pediatric clinic endorsement content.
- Gel:Thickened aqueous systems with enhanced cling properties suit preschoolers developing independent washing habits.
- Bar:Solid surfactant concentrates eliminate plastic packaging, appealing to zero-waste household segments in Germany and France.
- Powder:Dry shampoo formats address travel and camping use cases with waterless application protocols.
Liquid sits at the top of the volume ranking, with foam climbing the fastest.
Age Group:
Developmental milestones dictate surfactant tolerance thresholds and fragrance sensitivity, pushing parents toward graduated formulation transitions rather than continuous use.
- Toddlers:Tear-free amphoteric surfactant systems with pH 4.5-5.5 chemistry accommodate developing corneal sensitivity and scalp barrier immaturity. United States dermatology clinic dispensing systems prioritize this segment for first-time parent capture and brand loyalty establishment.
- Preschoolers:Mild anionic blends introduce controlled cleansing efficacy as sebum production increases and hair density thickens. German family wellness centers expand dedicated shelf space for this transition-stage positioning.
- Early School Age:Standard pediatric formulations with enhanced conditioning agents address active lifestyle residue removal without adult-strength surfactant loading.
- Tweens:Pre-adolescent formulations bridge to adult hair care with adjusted fragrance profiles and social-acceptance positioning.
Toddlers command the steepest premium pricing tier, with early school age showing the broadest distribution footprint.
Ingredient Type:
Clean-label migration is compressing margin structures for conventional formulations while creating pricing power for certified alternatives.
- Natural:Botanical-derived surfactants and plant-based conditioning agents satisfy transparency demand without full organic certification overhead. United States coastal metropolitan markets exhibit triple the household penetration of national averages for this positioning.
- Organic:USDA or ECOCERT certified ingredient panels command specialty retail placement and fifteen-to-twenty-five percent gross margin premiums. Supply constraints from South American cooperative sourcing create harvest-dependent availability cycles.
- Paraben-Free:Preservation system reformulation addressing FDA and ECHA scrutiny on endocrine-disruptor concerns.
- SLS-Free:Sodium lauryl sulfate elimination has shifted from premium differentiator to baseline hygiene expectation in specialty channels.
Natural claims dominate current volume, with organic certification gaining share fastest among premium-positioned households.
Packaging Type:
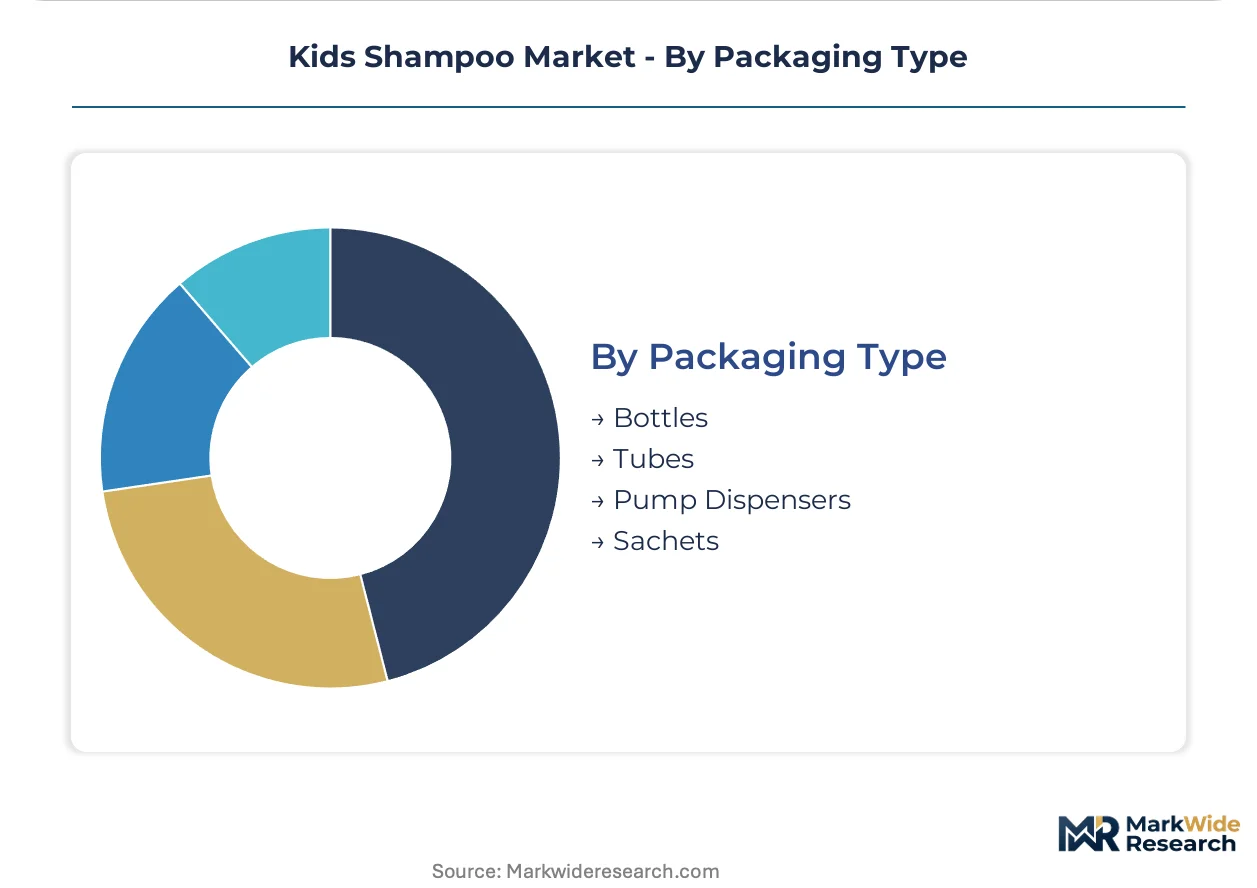
Application ergonomics and retail channel requirements drive divergent format specifications across mass and clinical distribution corridors.
- Bottles:Standard HDPE or PET containers with flip-top closures maintain mass retail economics and familiar handling protocols. United States pharmacy chains specify child-resistant cap integration for this format.
- Tubes:Collapsible aluminum or laminate structures enable precise dosing control and travel portability. German drugstore retailers favor tube formats for premium organic line extensions.
- Pump Dispensers:Metered-dose mechanisms reduce parental handling complexity during active toddler bathing.
- Sachets:Single-use foil pouches serve trial-size sampling and travel amenity channels with minimal unit economics.
Bottles retain the largest production volume, with pump dispensers expanding most quickly through pediatric clinic dispensing system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting contract manufacturing toward South Korea and Taiwan as REACH compliance costs compress margins for European-serving production lines. Manufacturers are consolidating to unified global SKUs rather than maintaining regional variants, elevating per-unit compliance investment while simplifying portfolio complexity.
United States
Premium natural and organic baby care segments command strong consumer loyalty and pricing power, particularly in California and New York metropolitan clusters where household penetration runs triple the national average. FDA cosmetic labeling requirements govern ingredient disclosure thresholds, compelling reformulation cycles that extend R&D timelines. Pediatric dermatology clinics and family wellness centers are expanding dedicated retail shelf space for clinically positioned children's hair care in suburban markets.
Germany
Family wellness centers dedicate expanded retail shelf space to pH-balanced formulations, creating distribution corridors for clinically positioned products. ECHA's tightening substance restrictions under REACH eliminate residual formaldehyde releasers and certain quaternary ammonium compounds from formulations. Specialty retailers in Frankfurt and Munich demand third-party certification ahead of mandatory deadlines, compressing margin structures for conventional formulations.
South Korea
Contract manufacturers are recalibrating production lines to meet surging private-label orders from Western retailers seeking cost-efficient clean-label output. The country's national cosmetic regulator maintains alignment with EU standards to preserve export market access. Seoul-based manufacturing clusters absorb procurement consolidation from US and European pharmacy chains, eroding branded pricing power in mass channels.
France
Specialty retailers respond to ECHA's 2024 REACH candidate list updates by demanding third-party certification ahead of mandatory deadlines. ANSM and CNIL oversight extends to algorithmic quality-control documentation for automated manufacturing lines. Paris and Lyon metropolitan markets exhibit concentrated demand for zero-waste packaging formats including solid shampoo bars.
Japan
Shiseido and KOSE anchor domestic formulation expertise in amphoteric surfactant stabilization for tear-free pediatric applications. METI and PMDA standards emphasize microbiome-compatible preservation systems ahead of commercial scale. Tokyo-Osaka industrial corridors concentrate R&D investment in postbiotic preservation technologies incorporating lysed lactobacillus ferments.
Kids Shampoo Market Competitive Landscape
United States producers anchor the premium-tier positioning through heritage pediatric credibility and direct-to-parent digital engagement; South Korean and Taiwanese contract manufacturers hold the private-label volume tier through cost-efficient clean-label output. The vendor base fragments across three strategic archetypes: multinational consumer goods conglomerates with massive research infrastructure, clean-ingredient specialists leveraging transparency storytelling, and private-label fabricators absorbing retailer procurement consolidation. Dominant competitive moves include portfolio diversification into microbiome-friendly preservation systems and geographic expansion through pediatric clinic dispensing channel integration.
Within the heritage pediatric tier, Johnson & Johnson occupies a position exemplifying pharmacy and hospital channel penetration through decades of established positioning. Procter & Gamble represents the research-intensive archetype, leveraging consumer research infrastructure to optimize formulation chemistry. The Honest Company exemplifies the clean-ingredient specialist model, differentiating through direct-to-parent digital engagement and transparency storytelling rather than traditional mass retail velocity.
| Leading Market Players |
|---|
| Johnson & Johnson |
| California Baby |
| Procter & Gamble |
| Shiseido |
| KOSE |
| Unilever |
| The Honest Company |
| Colgate-Palmolive |
| L'Oreal |
| Others |
Supply & Pricing Matrix
Horizontal integration among South Korean contract manufacturers anchors both supply resilience and pricing discipline for Western private-label buyers. This consolidation pattern compresses procurement costs for mass pharmacy chains while eroding branded pricing power in economy-tier segments.
Pricing Analysis
Retailer markup layers stratify across premium, standard, and economy tiers based on certification grade and volume scale. Organic-certified SKUs command fifteen-to-twenty-five percent gross margin premiums over natural-positioned alternatives. Pricing pressure stems from private-label absorption of procurement consolidation in United States pharmacy channels. Subscription-direct households in California and New York metropolitan clusters exhibit lowest price sensitivity, while multi-child suburban families prioritize economy-size packaging.
Supply Chain Analysis
Direct-to-retail channels handle mass pharmacy velocity through established pump-dispenser infrastructure and familiar handling protocols. Manufacturing concentrates in South Korea, Taiwan, and Germany, drawing from cold-pressed botanical surfactant supplies in South American cooperatives. Raw material dependencies include amphoteric surfactant precursors, microbiome-friendly preservation inputs, and certified organic conditioning agents. Single-source vulnerability runs through South American cooperative harvest cycles. Distribution feeds through pediatric dermatology clinic dispensing systems and direct-to-parent subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Germany and France exceed South Korean production economics by substantial margins, redirecting contract manufacturing toward East Asian fabrication clusters.
For Market Incumbents: Anticipate microbiome-friendly preservation R&D as the primary defensive moat against postbiotic specialists. Johnson & Johnson and Procter & Gamble should deepen backward integration into amphoteric surfactant supply to offset South Korean private-label erosion. Certification investment in USDA and ECOCERT tiers protects premium positioning against transparency-focused entrants. For New Entrants and Emerging Players: Pediatric clinic dispensing systems offer the most penetrable channel corridor for foam-format specialists. Target toddler households in United States coastal metropolitan markets through dermatologist endorsement content and rinse-speed messaging. Direct-to-parent subscription models bypass mass retail velocity requirements and establish brand loyalty before competitive consolidation. For Investors and Strategic Acquirers: Roll-up economics work for clean-ingredient specialists with established direct-to-parent digital engagement because parental purchasing fragmentation across telehealth-integrated platforms prevents scale concentration. Long-term viability hinges on postbiotic preservation R&D pipelines achieving commercial shelf stability. Watch for FDA guidance on microbiome-friendly preservatives as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Postbiotic Preservation R&D | First-mover advantage in microbiome-compatible formulations reshapes clinical credibility before FDA codification. |
| Pediatric Clinic Channel Integration | Dispensing system partnerships in United States dermatology clinics capture first-time parent loyalty. |
| Direct-to-Parent Subscription Launch | California and New York metropolitan penetration triples household conversion through rinse-speed messaging. |
| REACH-Compliant Global SKU Consolidation | Unified formulations for US and EU markets compress portfolio complexity while elevating per-unit compliance investment. |
| Organic Certification Investment | USDA and ECOCERT tiers command specialty retail placement and margin premiums in supply-constrained markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pediatric dermatologists, formulation chemists, pharmacy category buyers, and contract manufacturing procurement leads with secondary validation. Regulatory filings from FDA and ECHA, customs trade data, and Nielsen retail audit records anchored demand-side estimates. Bottom-up SKU-level modeling and top-down category sizing triangulated volume and value outputs.
Historical reference periods anchored the projection horizon to documented formulation transition cycles and regulatory implementation timelines. Segmentation dimensions included product format, developmental age group, ingredient positioning, and packaging type alongside geographic regulatory cluster. CAGRs derived from segment-level growth rate reconciliation and parent purchasing behavior elasticity estimates. Industry-specific inputs incorporated pediatric dermatology consensus evolution and REACH substance restriction trajectories.
Revisions become necessary when ECHA updates candidate list restrictions, FDA issues microbiome preservation guidance, or South American cooperative harvest volatility disrupts organic input supply. Forecasts reflect documented assumptions on regulatory implementation pacing and parent channel migration patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Saudi Arabia Eyelash Serum Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
Nail Art Tools and Accessories Market
Beauty & Personal Care
Global Massage Oil Market
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
Emea Beauty Devices Market
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
Organic Liquid Soaps Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Shower Gel Market
Beauty & Personal Care
Asia-Pacific Beauty and Personal Care Products Market
Beauty & Personal Care
Bath and Body Products Market
Beauty & Personal Care
Eyelash Serum Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
Zero-Waste Shampoo Market