
 Facial Wipes Market | 2026-2036
Facial Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Wipes Market Analysis
Teen skincare routines are hardening as a priority end-use vertical for facial wipe manufacturers. Procter & Gamble leverages its mass-market distribution infrastructure to dominate shelf presence in this demographic. Kimberly-Clark specializes in flushable and biodegradable formulations that anchor its positioning with environmentally conscious parents. Unilever competes through multi-brand portfolio breadth spanning premium to mass price tiers across convenience and specialty channels.
Facial wipes are nonwoven substrates pre-moistened with cleansing, moisturizing, or treatment solutions, typically constructed from polyester, viscose, or plant-based fibers bonded through hydroentanglement or thermal processes, designed for single-use skin cleansing without water access. Cleansing wipes occupy the largest volume position due to universal daily-use applicability across age cohorts, while biodegradable material substrates represent the fastest-growing structural segment as retailers impose sustainable sourcing requirements. Makeup remover wipes command premium shelf positioning and margin pools in professional beauty and theatrical supply channels.
The EPA regulates volatile organic compound emissions from wipe moistening solutions, while the EU REACH framework restricts certain preservative chemistries in cosmetic-grade wipes, collectively elevating formulation compliance costs for cross-border suppliers. The FDA's cosmetic labeling requirements and the EU MDR-adjacent cosmetic product notification obligations further shape market access documentation burdens. Stakeholders must monitor evolving state-level plastic bans and compostability certification standards to anticipate substrate investment priorities.
Market Dynamics
The EU's Single-Use Plastics Directive is compressing substrate choices across the value chain, forcing manufacturers to retool wet-laid nonwoven lines toward cellulose and polylactic acid alternatives before enforcement deadlines harden.
Growth Catalysts
- Biodegradable substrate mandates:The EU Single-Use Plastics Directive creates pull-through demand for compostable fibers in wet-laid nonwoven production, with retailers pre-emptively delisting conventional polyester wipes.
- Teen skincare vertical expansion:Social media platforms amplify early-age grooming rituals, hardening daily-use habits that sustain volume throughput in mass-market channels.
- Flushable certification standards:INDA/EDANA GD4 testing protocols enable product differentiation in wastewater-sensitive markets, unlocking municipal procurement channels previously closed to conventional wipes.
Market Restraints
- Pulp fiber cost volatility:Dissolving wood pulp prices fluctuate with textile viscose demand, squeezing margin structures for manufacturers committed to biodegradable substrates.
- Preservative chemistry restrictions:EU REACH Annex XVII limitations on isothiazolinones force reformulation cycles that extend R&D timelines and elevate compliance documentation burdens.
- Substitution by reusable alternatives:Microfiber cloth systems and oil-based cleansing balms capture sustainability-motivated consumers in premium beauty channels.
Strategic Opportunities
- Professional beauty channel penetration:Makeup artist supply houses and theatrical distributors represent underdeveloped outlets for premium-formulation wipes with higher margin structures.
- Compostability certification leverage:TÜV Austria OK Compost HOME and BPI certification enable shelf-space premiums at specialty retailers imposing sustainable sourcing requirements.
- Subscription direct-to-consumer models:Replenishment algorithms and personalized skincare regimens bypass conventional retail slotting fees while capturing lifetime value data.
Industry Challenges
- Wet-laid nonwoven engineering talent scarcity:Hydroentanglement process optimization for novel fiber blends requires specialized expertise concentrated at legacy European equipment suppliers.
- Cross-border formulation registration complexity:FDA cosmetic labeling requirements diverge from EU CPR notification obligations, fragmenting SKU portfolios and elevating inventory carrying costs.
- Legacy converting equipment retrofitting:Existing thermal-bonding lines require capital-intensive modifications to handle plant-based fiber shrinkage characteristics during moistening.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Wipes Market |
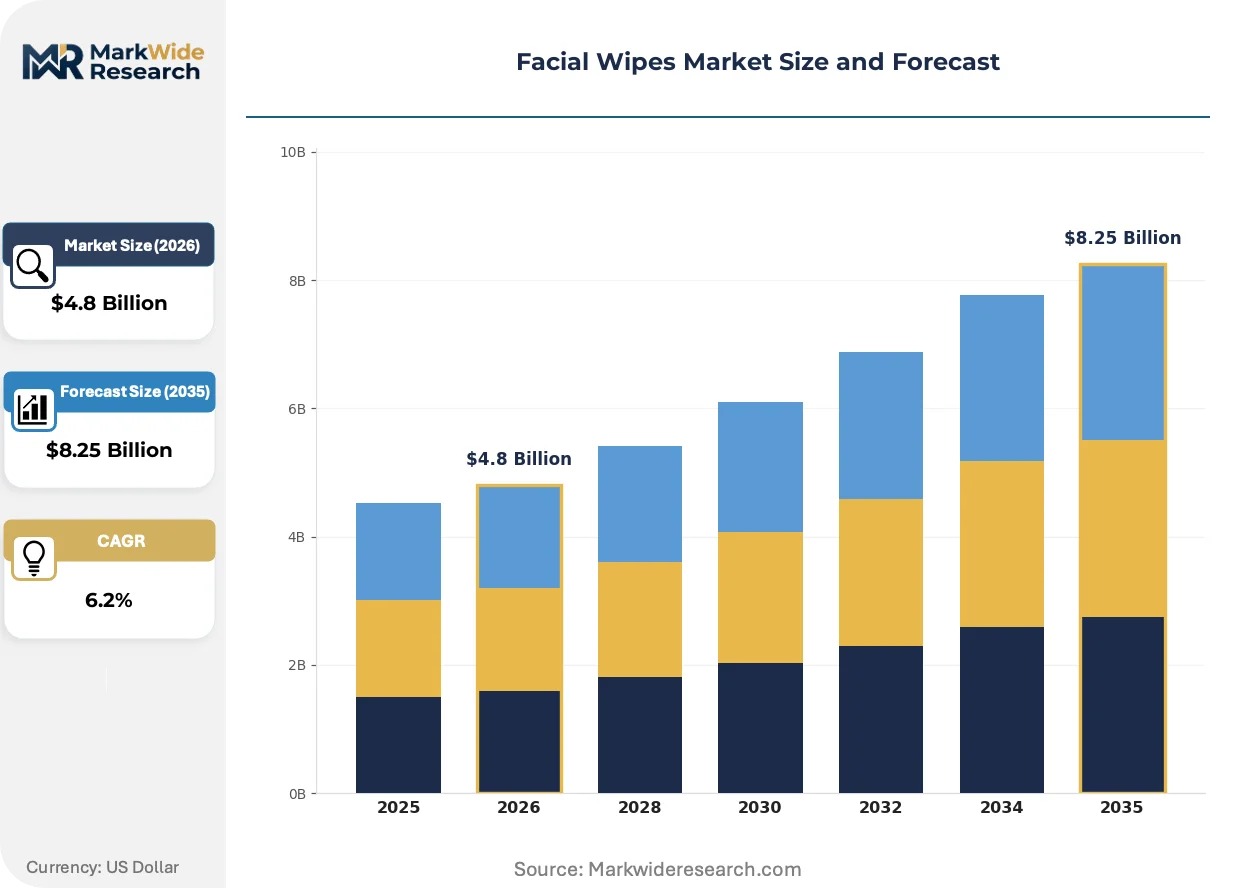
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Makeup Remover, Cleansing, Exfoliating, Hydrating Material: Biodegradable, Cotton, Synthetic Fiber, Bamboo End User: Adults, Teens, Sensitive Skin, Travel Users Packaging Type: Wipe Pack, Tub, Box, Refill |
| Companies Covered | Procter & Gamble, Johnson & Johnson, Kimberly-Clark, Unilever, Beiersdorf, Nice-Pak Products, Rockline Industries, Diamond Wipes International, L'Oréal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Wipes Market Emerging Trajectories
Active innovation clusters center on substrate chemistry, preservative system redesign, and channel-specific formulation segmentation. These forces are compressing product lifecycles while elevating technical barriers to competitive entry.
Hydroentanglement of cellulose-lignin composites is electrifying substrate performance benchmarks in the biodegradable segment. Premium private-label brands at specialty beauty retailers are adopting these materials fastest, seeking to capture shelf-space premiums ahead of mass-market conversion. The technology is electrifying competitive intensity by collapsing the performance gap between sustainable and conventional substrates.
REACH Annex XVII expansions targeting additional preservative chemistries are tightening formulation freedom across European supply chains. Manufacturers face forced reformulation cycles that extend development timelines by twelve to eighteen months. The professional beauty and theatrical supply segments bear disproportionate impact, as long-open package formats require robust preservation systems.
Algorithmic replenishment through direct-to-consumer channels is fragmenting traditional retail concentration. Subscription models capture usage-pattern data that enables predictive manufacturing and personalized SKU bundling. This behavioral shift is most visible in the United States, where teen skincare routines harden around influencer-curated regimen formats delivered through social commerce platforms.
Facial Wipes Market Segmentation
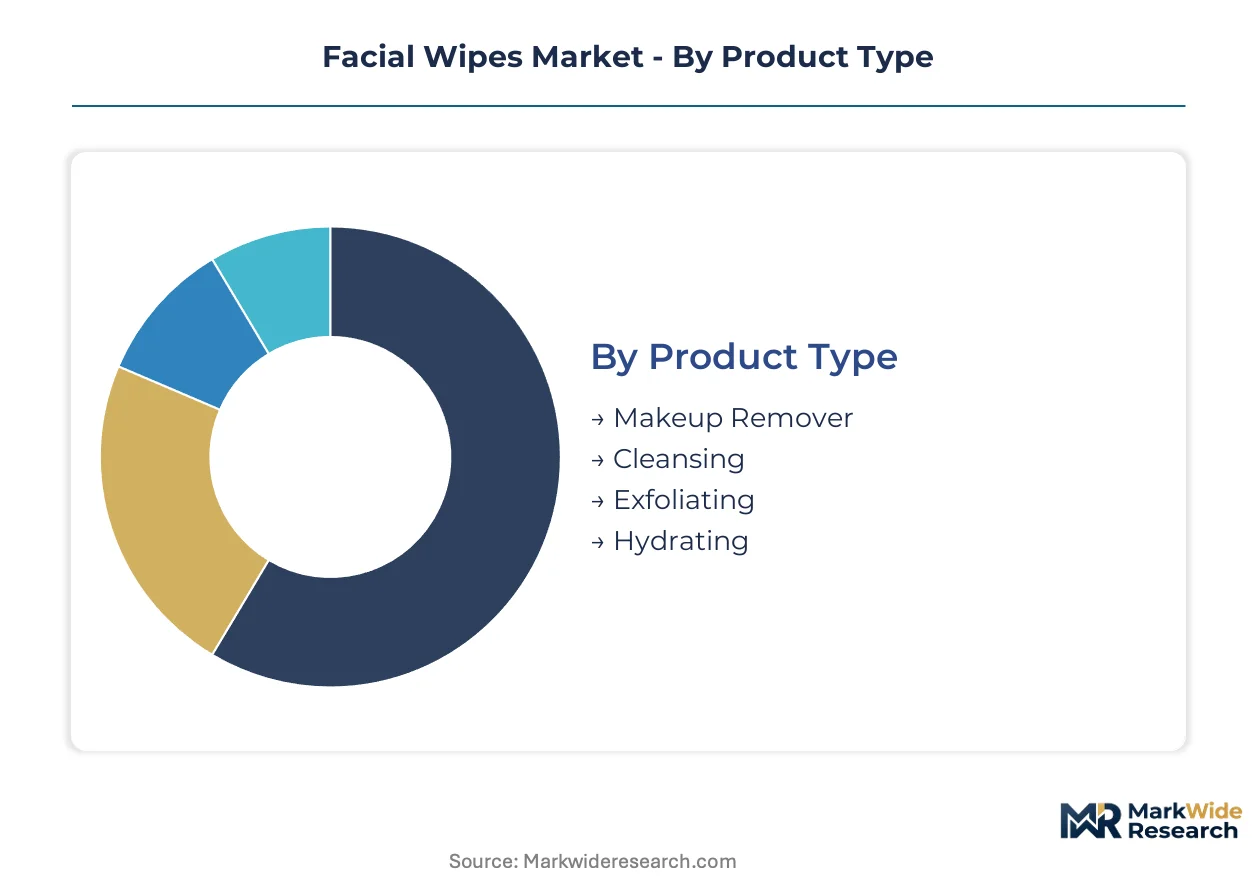
Segmentation in facial wipes reveals how formulation chemistry, substrate engineering, and channel economics intersect. Manufacturers must align R&D investments with distinct performance requirements across usage occasions and sustainability preferences.
Product Type:
Formulation chemistry distinguishes competitive positioning across daily-use and treatment-oriented occasions.
- Cleansing:Universal daily-use formulations dominate volume throughput across mass-market channels. Demand concentrates in the United States where premium private-label variants gain shelf space at specialty beauty retailers.
- Makeup Remover:Oil-in-water emulsion systems dissolve long-wear cosmetics without stripping lipid barriers. Professional beauty and theatrical supply channels command premium shelf positioning and margin pools for these specialized formulations.
- Exfoliating:Alpha-hydroxy acid or microbead-impregnated substrates target weekly treatment rituals in premium skincare regimens.
- Hydrating:Hyaluronic acid and glycerin-based moistening solutions serve air travel and post-procedure recovery use cases.
Cleansing leads on scale; makeup remover leads on momentum.
Material:
Substrate selection determines compliance trajectory against tightening single-use plastics regulations.
- Biodegradable:Cellulose-lignin composites processed through hydroentanglement collapse the performance gap with synthetic alternatives. The EU Single-Use Plastics Directive creates pull-through demand as retailers pre-emptively delist conventional polyester wipes.
- Synthetic Fiber:Polyester and polypropylene nonwovens retain cost advantages in emerging markets with lagging environmental enforcement.
- Cotton:Natural fiber purity commands allergen-conscious positioning in pediatric and dermatological channels.
- Bamboo:Rapid-renewable grass fibers appeal to sustainability-motivated consumers in direct-to-commerce subscription models.
Biodegradable substrates gain share fastest; synthetic fiber retains volume concentration.
End User:
Demographic targeting shapes packaging format, preservative system, and channel strategy decisions.
- Teens:Social media-amplified grooming rituals harden daily-use habits that sustain mass-market volume throughput. Influencer-curated regimen formats delivered through social commerce platforms concentrate demand in the United States.
- Sensitive Skin:Fragrance-free, hypoallergenic formulations with minimal preservative loads capture dermatologist recommendation channels.
- Adults:Anti-aging ingredient integration (retinol, peptides) supports premium pricing in professional beauty segments.
- Travel Users:TSA-compliant single-count packaging and leak-resistant seals address aviation-specific constraints.
Teens drive volume expansion; sensitive skin commands margin premiums.
Packaging Type:
Dispensing mechanics influence moisture retention, contamination risk, and retail slotting economics.
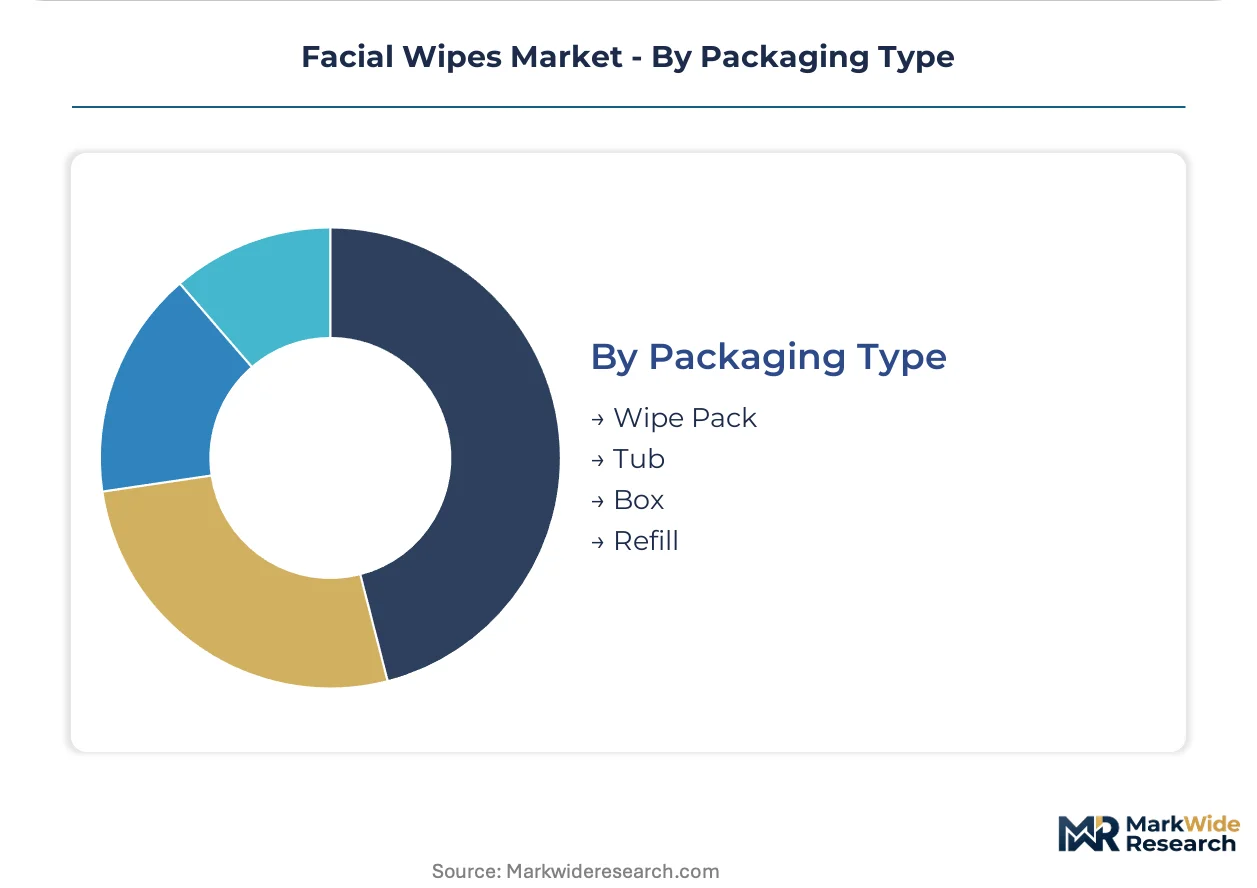
- Wipe Pack:Flexible film laminates with resealable closures dominate impulse purchase and travel occasions. Convenience stores and airport retail channels favor this format for its shelf efficiency.
- Tub:Rigid polypropylene containers with hinged lids support high-frequency household use and bulk value positioning.
- Box:Premium carton structures with decorative finishes enable gift set bundling in specialty beauty retail.
- Refill:Reduced-plastic pouch formats align with retailer-imposed sustainable sourcing requirements and subscription replenishment models.
Wipe pack leads on distribution breadth; refill climbs the fastest on sustainability tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting wet-laid nonwoven investment toward jurisdictions with extended compliance timelines, as manufacturers seek to amortize legacy polyester capacity before biodegradable mandates harden. The United States and Germany currently attract the bulk of substrate engineering talent, while Southeast Asian converters exploit cost-of-compliance gaps to serve export markets.
United States
Teen skincare routines harden around influencer-curated regimen formats delivered through social commerce platforms, sustaining mass-market volume throughput. The EPA regulates volatile organic compound emissions from wipe moistening solutions, elevating formulation compliance costs for domestic suppliers. Premium private-label variants gain shelf space at specialty beauty retailers concentrated in Los Angeles and New York metro corridors.
Germany
Professional beauty and theatrical supply channels command premium shelf positioning for makeup remover formulations with higher margin structures. ECHA REACH Annex XVII restrictions on isothiazolinones force reformulation cycles that extend R&D timelines by twelve to eighteen months. Industrial clusters around Düsseldorf and Hamburg anchor wet-laid nonwoven engineering expertise for cellulose-lignin composite development.
China
Domestic demand concentrates in tier-one cities where air travel and post-procedure recovery use cases drive hydrating wipe adoption. SAMR cosmetic product notification obligations diverge from Western frameworks, fragmenting SKU portfolios for cross-border suppliers. The Yangtze River Delta manufacturing belt hosts converters retooling thermal-bonding lines for plant-based fiber processing.
India
Sensitive skin formulations capture dermatologist recommendation channels in urban centers with rising allergen-conscious positioning. BIS standards for nonwoven substrates create technical entry barriers for imported finished goods. Maharashtra and Gujarat industrial corridors concentrate domestic wet-wipe converting capacity serving Middle East export markets.
Brazil
Mass-market cleansing wipes dominate volume through convenience store channels in São Paulo and Rio de Janeiro metropolitan areas. ANVISA cosmetic registration requirements extend product launch timelines relative to Mercosur neighbors. Local converters exploit pulp fiber cost advantages from regional dissolving wood pulp supply integration.
Facial Wipes Market Vendor Landscape
Portfolio diversification dominates the current landscape as incumbents reconfigure brand architectures to span premium private-label and mass-market price tiers simultaneously. The vendor base concentrates among multinational consumer goods conglomerates with captive nonwoven supply relationships, mid-tier regional converters with flexible private-label capacity, and specialty formulators serving professional beauty channels. Three strategic archetypes prevail: mass-market volume leaders leveraging distribution infrastructure, sustainability specialists anchoring biodegradable substrate positioning, and professional beauty channel insurgents capturing theatrical supply margins. M&A activity and wet-laid nonwoven capacity expansion constitute the dominant competitive moves, as players seek to secure fiber supply ahead of EU Single-Use Plastics Directive enforcement deadlines.
Within the multinational conglomerate tier, Procter & Gamble and Unilever occupy positions defined by mass-market distribution infrastructure and multi-brand portfolio breadth spanning convenience and specialty channels. Kimberly-Clark exemplifies the sustainability specialist archetype, with its organizational heritage in flushable and biodegradable formulations aligning with retailer-imposed sustainable sourcing requirements. These three entities collectively represent the competitive gravity that shapes substrate investment priorities and formulation compliance documentation burdens across North American and European supply chains.
| Leading Market Players |
|---|
| Procter & Gamble |
| Johnson & Johnson |
| Kimberly-Clark |
| Unilever |
| Beiersdorf |
| Nice-Pak Products |
| Rockline Industries |
| Diamond Wipes International |
| L'Oréal |
| Others |
Supply Flow & Price Mechanics
Dissolving wood pulp price indices cascade through facial wipe manufacturing into three-tier pricing stratification across premium, standard, and economy levels. Pulp fiber cost volatility compresses margins for biodegradable substrate producers while synthetic fiber alternatives retain cost advantages in enforcement-lagging markets.
Pricing Analysis
Retailer markup layers absorb the steepest cost compression as specialty beauty channels demand compostability certification premiums. Pricing stratifies across premium, standard, and economy tiers based on substrate certification grade and volume scale, with TÜV Austria OK Compost HOME and BPI tiers commanding shelf-space premiums. Price erosion runs through mass-market channels as private-label variants displace branded equivalents. Teen skincare consumers exhibit lowest price sensitivity, while travel-format purchasers in convenience channels demonstrate highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from multinational consumer goods conglomerates with captive nonwoven relationships. Wet-laid nonwoven production concentrates in Germany, the United States, and China, with Southeast Asian converters exploiting compliance timeline gaps. Supply chains draw from dissolving wood pulp, polylactic acid resin, and hydroentanglement equipment as critical inputs. Single-source vulnerability concentrates at legacy European equipment suppliers for cellulose-lignin composite processing. Distribution runs through mass-market retail, specialty beauty, and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facial wipe manufacturing arbitrage favors Southeast Asian converters serving EU markets before Single-Use Plastics Directive enforcement hardens, exploiting eighteen-month compliance gaps against European substrate retooling costs.
For Market Incumbents: Deepen captive supply relationships with wet-laid nonwoven producers in the Yangtze River Delta ahead of EU Single-Use Plastics Directive deadlines. Secure TÜV Austria and BPI compostability certifications for premium private-label portfolios. Retool thermal-bonding lines for plant-based fiber processing to defend against biodegradable substrate mandates. For New Entrants and Emerging Players: Begin with professional beauty and theatrical supply channels where makeup remover formulations command margin premiums absent mass-market slotting fee barriers. Target algorithmic replenishment models through social commerce platforms serving teen skincare regimens. Pursue flushable certification under INDA/EDANA GD4 protocols to unlock municipal procurement channels. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier regional converters possessing flexible private-label capacity and established retailer relationships. Five-to-ten year viability hinges on substrate engineering talent concentration and wet-laid nonwoven equipment access. Watch for EU REACH Annex XVII expansion announcements as inflection indicators for reformulation cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Conversion | EU Single-Use Plastics Directive compliance secures retailer shelf access ahead of delisting deadlines. |
| Compostability Certification Investment | TÜV Austria OK Compost HOME and BPI tiers unlock specialty beauty channel premiums. |
| Direct-to-Consumer Subscription Launch | Algorithmic replenishment captures teen skincare regimen data while bypassing retail slotting fees. |
| Professional Beauty Channel Expansion | Theatrical supply and makeup artist houses offer underdeveloped outlets for premium-formulation margins. |
| Flushable Certification Pathway | INDA/EDANA GD4 protocols enable differentiation in wastewater-sensitive municipal procurement markets. |
Methodological Framework
Multiple input streams — executive interviews with brand managers and category buyers, technical consultations with wet-laid nonwoven engineers, and regulatory tracking across FDA and ECHA frameworks — were reconciled against secondary validation. Primary fieldwork engaged supply planners at converting facilities, procurement leads at downstream retailers, and R&D directors at substrate producers. Secondary sources encompassed customs records for pulp fiber trade flows, EPA volatile organic compound emission databases, and EU REACH Annex XVII restriction updates. Bottom-up volume builds across product type, material, end user, and packaging segments were cross-checked against top-down market sizing.
Historical consumption patterns were cross-referenced against panel input from industry participants to anchor growth trajectory assumptions across the analysis window. The analytical framework modeled segmentation dimensions including formulation chemistry, substrate engineering, demographic targeting, and dispensing mechanics. CAGRs were derived from trend extrapolation moderated by regulatory enforcement timelines and raw material cost cycle positions. Forecast inputs incorporated social commerce penetration rates for teen skincare and retailer sustainable sourcing mandate adoption curves.
Caveats apply where EU Single-Use Plastics Directive enforcement acceleration, dissolving wood pulp price spikes, or REACH Annex XVII preservative expansion could materially shift the outlook. Forecasts reflect documented assumptions around compliance timeline adherence and substrate performance convergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
Global Personal Care Emollients Market
Beauty & Personal Care
South Korea Beauty and Personal Care Products Market
Beauty & Personal Care
Online Cosmetics Market
Beauty & Personal Care
Global Cosmetics Market
Beauty & Personal Care
Asia-Pacific Beauty and Personal Care Products Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Organic Personal Care Market
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
Hair Conditioner Market
Beauty & Personal Care
Lip Care Market
Beauty & Personal Care
Asia-Pacific Hair Conditioner Market
Beauty & Personal Care
Digitalization of Beauty Industry Market
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
Europe Male Grooming Products Market
Beauty & Personal Care
Canada Dermocosmetics Market