
 Facial Steamer Market | 2026-2036
Facial Steamer Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Steamer Market Foresight
China is rewriting production economics for facial steamers through expanded OEM capacity in Guangdong and Zhejiang provinces. Panasonic Corporation leverages its electronics heritage to dominate ultrasonic transducer integration. Beurer GmbH anchors European demand with medically certified devices that navigate Germany's strict appliance safety framework. Homedics competes aggressively in North American retail channels through mass-market tabletop positioning.
A facial steamer is an electrically powered device that heats water to produce controlled vapor, typically operating at temperatures between 40°C and 50°C with particle sizes below 10 microns for dermal penetration. It serves commercial esthetic practitioners and home users seeking enhanced skincare absorption, pore cleansing, and hydration delivery. Portable units command widening shelf space as travel wellness routines normalize, while professional-grade multi-function systems retain the strongest margin pools through bundled LED and extraction modalities. Nano-steamer technology leads R&D allocation, with ionization features differentiating mid-tier offerings from baseline vaporizer alternatives.
The FDA regulates facial steamers marketed with therapeutic claims under medical device guidelines, while the FCC governs wireless-enabled smart models. ECHA's REACH framework restricts certain plastics and coatings in devices sold across Europe, compelling reformulation of housing materials. China's GB standards for household electrical appliances set mandatory thermal cutoff and grounding requirements that shape factory compliance costs. Stakeholders must monitor whether emerging state-level right-to-repair legislation in the United States forces design changes to sealed ultrasonic chambers.
Market Dynamics
Nano-steam technology is compressing product lifecycles as manufacturers race to integrate ultrasonic transducers below the 5-micron threshold, forcing wholesale redesigns of heating chambers and vapor pathways across the device landscape.
Growth Catalysts
- Post-pandemic wellness infrastructure:Dermatology clinics in the United States are rebuilding service menus with multi-function steam systems that bundle LED therapy and extraction tools.
- REACH material compliance:ECHA's restrictions on certain housing plastics are accelerating adoption of reformulated polymer alternatives among European OEMs seeking CE marking continuity.
- Travel wellness normalization:Portable nano-steamers are capturing shelf space in airport retail and direct-to-consumer channels as consumers integrate facial steaming into mobile routines.
Market Restraints
- Ultrasonic transducer supply concentration:Production of piezoelectric components clusters in Guangdong province, exposing brands to single-source risk during factory shutdowns.
- FDA medical device classification friction:Therapeutic claims trigger 510(k) pathways that extend commercialization timelines by 12-18 months for ionization-featured models.
- Conventional vaporizer substitution:Basic humidifier units priced at one-third of entry-level facial steamers satisfy hydration needs for price-sensitive home users.
Strategic Opportunities
- Med-spa channel expansion:Medical aesthetic chains in Germany are procuring certified devices under MDR frameworks, creating premium positioning unavailable to uncertified competitors.
- Smart connectivity integration:Bluetooth-enabled units with app-controlled temperature profiles are digitizing user data for personalized skincare regimens.
- Right-to-repair legislative tailwind:Emerging state-level mandates in California and New York are forcing design changes to sealed ultrasonic chambers, opening aftermarket service revenue streams.
Industry Challenges
- Ultrasonic engineering talent scarcity:Specialized transducer calibration expertise concentrates among aging technicians in Japanese and German electronics heritage firms.
- Multi-certification capex burden:Simultaneous FDA, CE, and GB standard compliance requires redundant testing protocols that strain R&D budgets for mid-tier manufacturers.
- Legacy esthetician training gaps:Professional users require recertification on nano-steam protocols, slowing adoption curves in independent salon channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Steamer Market |
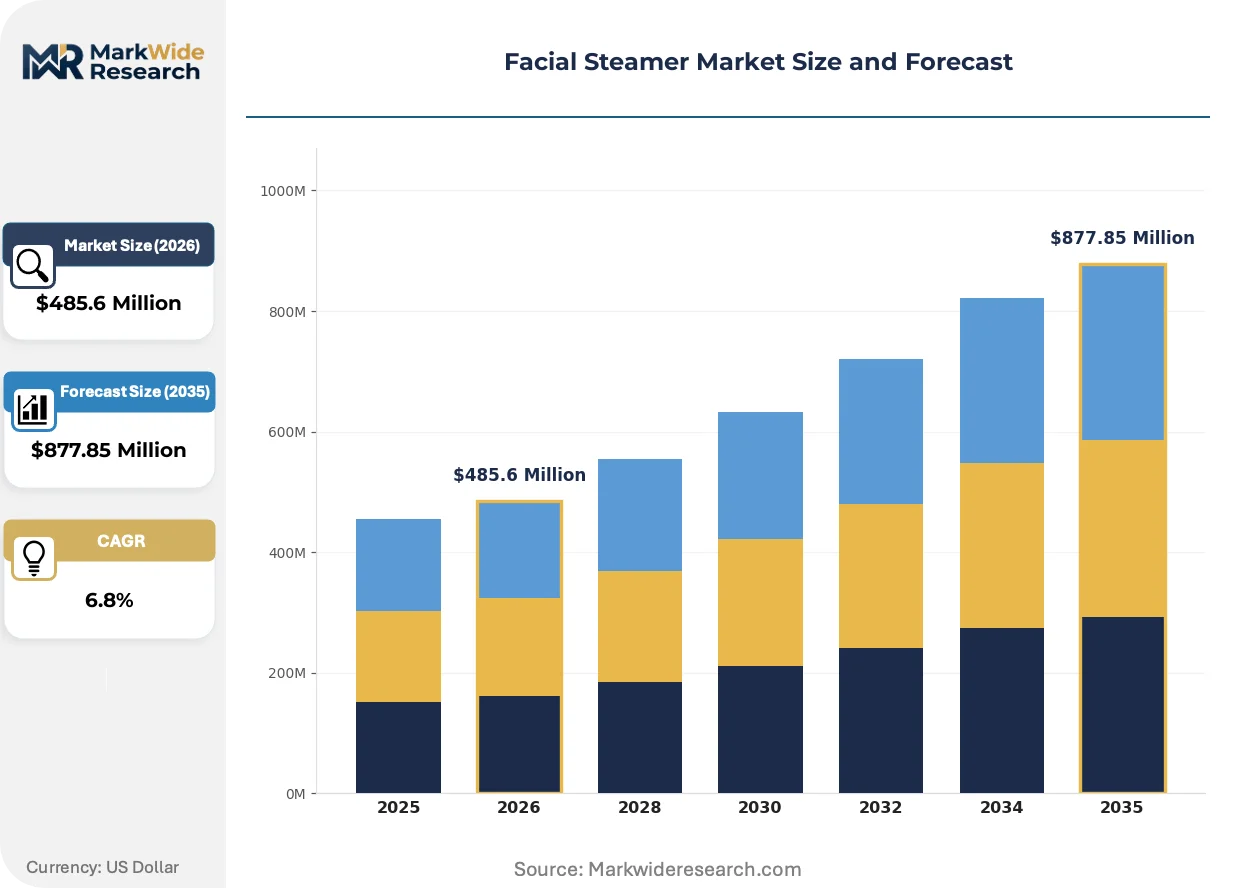
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $877.85 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Professional, Tabletop, Multi-Function Technology: Ultrasonic, Nano-Steamer, Ionization, Vaporizer Application: Beauty Salons, Home Use, Spa Centers, Dermatology Clinics End User: Professionals, Home Users, Aesthetic Practitioners, Spa Therapists |
| Companies Covered | Dr. Dennis Gross Skincare LLC, Vanity Planet, Panasonic Corporation, Pure Daily Care, Microderm GLO, Conair Corporation, Homedics, TaoTronics, Beurer GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Steamer Market Shifts & Advancements
Active digitization of device architecture is compressing the boundary between consumer electronics and clinical equipment, with connectivity features and sensor arrays becoming baseline expectations rather than premium differentiators.
Ionization modules paired with nano-steam generation are digitizing treatment protocols by enabling real-time pH monitoring and automatic dosage adjustment. Medical spa chains in South Korea are piloting these systems for personalized facial regimens. The technology is digitizing the esthetician's role from manual operator to protocol supervisor, reducing per-treatment labor intensity.
REACH framework amendments targeting per- and polyfluoroalkyl substances are forcing housing material transitions across European-bound production lines. Manufacturers are substituting fluoropolymer coatings with ceramic-based alternatives that satisfy thermal conductivity requirements. German appliance safety certification bodies are updating test protocols to accommodate these material shifts, extending validation cycles for new product introductions.
Subscription-based device-plus-consumable models are displacing outright purchase patterns among millennial and Gen Z demographics. Direct-to-consumer brands are bundling quarterly serum refills with hardware leases, capturing lifetime value through recurring revenue. This pattern is most visible in United States urban markets where apartment dwellers prioritize storage-minimal wellness equipment access over ownership.
Facial Steamer Market Segmentation
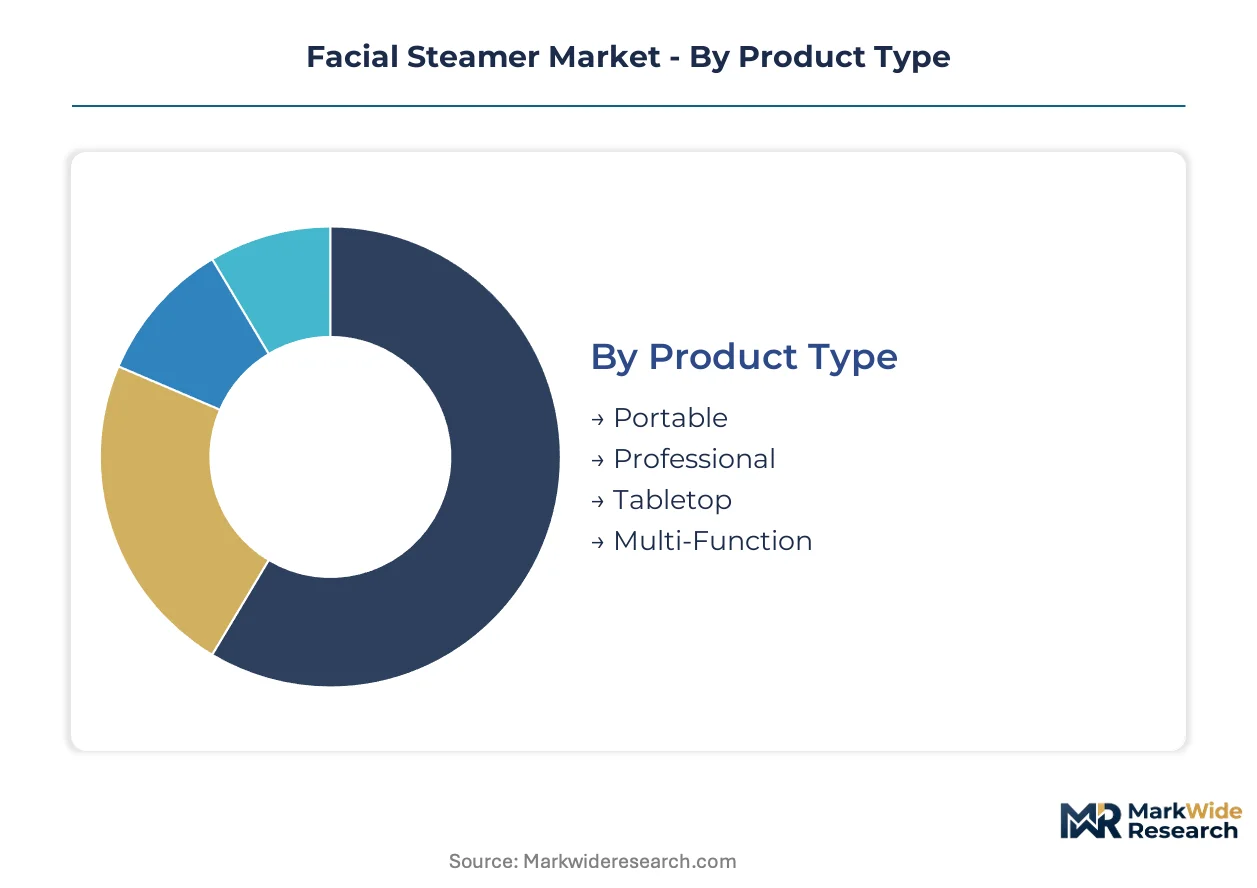
Facial steamer segmentation reveals how device specifications, user environments, and technical architectures create distinct margin profiles and certification requirements across the category. Understanding these divides clarifies why nano-steam R&D concentrates in premium tiers while portable units compete on channel accessibility.
Product Type:
Cost tier differentiation separates mass-market accessibility from clinical-grade performance specifications and bundled modality integration.
- Portable:Compact units under 500 grams with USB-C power delivery and collapsible reservoirs target travel retail and subscription-box distribution. Demand clusters in United States urban corridors where apartment storage constraints favor minimal-footprint wellness equipment.
- Professional:Multi-nozzle systems with adjustable armature mounting and 30-minute continuous operation serve dermatology clinics in Germany rebuilding post-pandemic service menus. FDA 510(k) pathways for therapeutic claims extend commercialization timelines for ionization-featured variants.
- Tabletop:Mid-size units with 150-200ml capacity balance domestic countertop footprint with adequate session duration for home facial routines.
- Multi-Function:Integrated LED therapy, extraction tools, and serum infusion modules command premium positioning in South Korean medical spa chains.
Professional holds installed capacity. Portable is rotating up the share rankings.
Technology:
Particle size thresholds and transducer architecture determine dermal penetration efficacy and regulatory classification boundaries.
- Nano-Steamer:Ultrasonic transducers generating sub-5-micron vapor particles enable epidermal penetration beyond conventional humidification. Panasonic Corporation dominates transducer integration through electronics heritage manufacturing in Osaka prefecture.
- Ionization:pH-monitoring modules with automatic dosage adjustment digitize treatment protocols in Seoul medical spa pilots, reducing per-treatment labor intensity.
- Ultrasonic:Piezoelectric component production concentrates in Guangdong province, exposing brands to single-source supply risk during factory shutdowns.
- Vaporizer:Basic heating-element designs face substitution pressure from humidifier units priced at one-third of entry-level facial steamers.
Nano-Steamer captures R&D allocation intensity. Ionization is climbing the fastest among emerging technology introductions.
Application:
End-use environment dictates certification burden, device durability specifications, and consumable attachment revenue potential.
- Dermatology Clinics:Medically certified devices under MDR frameworks create premium positioning unavailable to uncertified competitors in German aesthetic chains. Procurement emphasizes multi-function systems with bundled LED and extraction modalities.
- Home Use:Direct-to-consumer brands bundle quarterly serum refills with hardware leases, capturing lifetime value through recurring revenue in United States subscription models.
- Beauty Salons:Independent channels require esthetician recertification on nano-steam protocols, slowing adoption curves outside franchised networks.
- Spa Centers:High-throughput environments prioritize rapid heat-up times and commercial-grade housing durability.
Dermatology Clinics anchor premium pricing power. Home Use is gaining share fastest through digital-native distribution.
End User:
Customer type determines purchasing authority, technical sophistication requirements, and training support infrastructure needs.
- Aesthetic Practitioners:Licensed professionals in United States medical spas demand connectivity-enabled units with app-controlled temperature profiles for personalized regimen documentation.
- Spa Therapists:Service employees in high-turnover environments require simplified interfaces with preset protocol selections.
- Professionals:Clinic owners and franchise operators negotiate volume procurement with extended warranty terms.
- Home Users:Millennial and Gen Z demographics prioritize storage-minimal equipment access over ownership, accelerating subscription model penetration.
Aesthetic Practitioners concentrate certified-device demand. Home Users are expanding the addressable population base most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach handles containerized electronics imports that feed facial steamer assembly lines across Southern California distribution corridors.
United States
Dermatology clinic procurement and home-use premiumization drive demand concentration. FDA 510(k) pathways for therapeutic claims extend commercialization timelines for ionization-featured models. Southern California distribution corridors process containerized electronics imports through the Port of Long Beach.
Germany
Medical aesthetic chains procure certified devices under MDR frameworks, creating premium positioning unavailable to uncertified competitors. ECHA's REACH restrictions on certain housing plastics accelerate adoption of reformulated polymer alternatives. Bavaria-based certification bodies update test protocols for ceramic-based thermal conductivity materials.
China
Expanded OEM capacity in Guangdong and Zhejiang provinces rewrites production economics for global brands. GB standards for household electrical appliances mandate thermal cutoff and grounding requirements that shape factory compliance costs. Shenzhen manufacturing clusters concentrate piezoelectric component production for ultrasonic transducers.
South Korea
Medical spa chains pilot ionization modules with real-time pH monitoring for personalized facial regimens. MFDS medical device classification frameworks govern therapeutic claim substantiation. Seoul Capital Area aesthetic chains digitize esthetician roles from manual operator to protocol supervisor.
Japan
Electronics heritage firms concentrate specialized transducer calibration expertise among aging technician cohorts. METI industrial standards shape appliance safety certification requirements. Osaka prefecture manufacturing anchors ultrasonic transducer integration for premium device tiers.
Facial Steamer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in transducer and heating element supply. The vendor base stratifies across medically certified professional systems, mass-market tabletop units, and portable travel formats. Three archetypes dominate: electronics heritage conglomerates with ultrasonic engineering depth, German appliance specialists with medical certification expertise, and direct-to-consumer brands with subscription-based hardware leasing. Competitive moves concentrate on smart connectivity integration and REACH-compliant material reformulation.
Among electronics heritage conglomerates, Panasonic Corporation exemplifies platform integrators leveraging transducer manufacturing depth. Beurer GmbH represents the medically certified appliance archetype navigating strict European safety frameworks. Homedics occupies a position within mass-market tabletop positioning through North American retail channel density. These three anchors illustrate how competitive positioning separates certification-grade professional systems from accessibility-focused home-use formats.
| Leading Market Players |
|---|
| Dr. Dennis Gross Skincare LLC |
| Vanity Planet |
| Panasonic Corporation |
| Pure Daily Care |
| Microderm GLO |
| Conair Corporation |
| Homedics |
| TaoTronics |
| Beurer GmbH |
| Others |
Supply & Pricing Matrix
Guangdong province's concentration of piezoelectric component manufacturing anchors cost structures across all device tiers, concentrating margin capture with ultrasonic transducer suppliers while forcing downstream brands into hardware-plus-consumable bundling to defend profitability.
Pricing Analysis
FDA medical device classification dictates the pricing tier structure across the facial steamer landscape. Three-tier pricing separates ionization-featured professional systems from mid-market tabletop units and entry-level portable devices. Certification-grade MDR compliance in Germany commands premium positioning unavailable to uncertified competitors. Pricing pressure stems from conventional humidifier substitution in home-use segments where hydration needs are satisfied at one-third the cost. Home users exhibit highest price sensitivity; German medical aesthetic chains show lowest sensitivity due to bundled service revenue models.
Supply Chain Analysis
Feedstock for ultrasonic transducers concentrates in Guangdong province, Osaka prefecture, and Zhejiang province manufacturing clusters. Piezoelectric ceramics, medical-grade polymer housings, and precision heating elements constitute critical input dependencies. Single-source vulnerability in Guangdong exposes brands to production stoppages during factory shutdowns. Distribution runs through Southern California logistics corridors for North American demand, with direct-to-consumer channels gaining share fastest among millennial demographics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized transducer calibration expertise concentrates among aging technician cohorts in Japanese and German electronics heritage firms, creating a bottleneck that will constrain premium-tier supply expansion and reward early capability capture.
For Market Incumbents: Insulate core positioning by deepening captive supply of ultrasonic transducer components through backward integration into Osaka or Guangdong manufacturing assets. Accelerate FDA 510(k) pathway investments for ionization-featured variants before regulatory backlogs extend commercialization timelines further. Prioritize REACH-compliant ceramic housing material qualification to maintain CE marking continuity across European-bound production lines. For New Entrants and Emerging Players: Build out white-space presence in United States subscription-model distribution where millennial and Gen Z demographics prioritize equipment access over ownership. Target portable nano-steamer segments with USB-C power delivery and collapsible reservoir designs for airport retail channel penetration. Deploy direct-to-consumer digital-native marketing with quarterly serum refill bundling to capture recurring revenue streams. For Investors and Strategic Acquirers: Capital is best deployed toward medically certified device manufacturers with established MDR frameworks and German aesthetic chain procurement relationships. Long-term viability favors platforms with transducer integration depth rather than assembly-only operations. Monitor right-to-repair legislative progression in California and New York as an inflection signal for aftermarket service revenue potential.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Connectivity Integration | Bluetooth-enabled units with app-controlled temperature profiles digitize user data for personalized skincare regimens in United States medical spas. |
| REACH-Compliant Material Transition | Ceramic-based housing alternatives satisfy ECHA thermal conductivity requirements while extending validation cycles for European product introductions. |
| Subscription Model Deployment | Hardware-plus-consumable leasing captures lifetime value through recurring serum refill revenue in United States urban apartment markets. |
| Med-Spa Channel Certification | MDR-compliant device procurement by German aesthetic chains creates premium positioning unavailable to uncertified competitors. |
| Portable Form Factor Innovation | USB-C powered collapsible units capture airport retail shelf space as travel wellness routines normalize post-pandemic. |
Research Methodology
A standing panel of dermatology clinic procurement managers, aesthetic chain operations directors, ultrasonic transducer calibration technicians, and direct-to-consumer brand marketing executives provided ongoing calibration throughout the study period. Primary interview insights were cross-validated against FDA 510(k) filing databases, ECHA REACH substance restriction updates, GB standards household appliance compliance records, and customs import manifests for containerized electronics through the Port of Long Beach. Bottom-up device shipment modeling and top-down wellness equipment spending analysis were triangulated to anchor volume estimates.
Scenario bracketing around nano-steam technology adoption curves, right-to-repair legislative progression timelines, and REACH amendment implementation schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, technology architecture, end-use environment, and customer purchasing authority. CAGRs were derived from installed base growth rates and replacement cycle compression patterns, with specific inputs from medical spa capital expenditure surveys and subscription-model churn benchmarks.
Stress conditions across ultrasonic transducer supply disruptions, FDA classification pathway delays, and ECHA material restriction accelerations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding wellness spending recovery trajectories and esthetician recertification adoption curves. Cross-checking against hospital procurement database trend lines and consumer electronics retail audit data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
In-Wash Scent Booster Market
Beauty & Personal Care
Natural Hair Care Product Market
Beauty & Personal Care
Cosmetics and Personal Care Stores Market
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Deodorant Wipes Market
Beauty & Personal Care
Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Foaming Hand Soaps Market
Beauty & Personal Care
Nail Lamps Market
Beauty & Personal Care
Hair Straightener Market
Beauty & Personal Care
Hand Care Products Market
Beauty & Personal Care
Mexico Beauty and Personal Care Market
Beauty & Personal Care
Philippines Beauty & Personal Care Market
Beauty & Personal Care
Hair Salon Equipment Market