
 Spain Sustainable Personal Care Market | 2026-2036
Spain Sustainable Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Sustainable Personal Care Market Insights
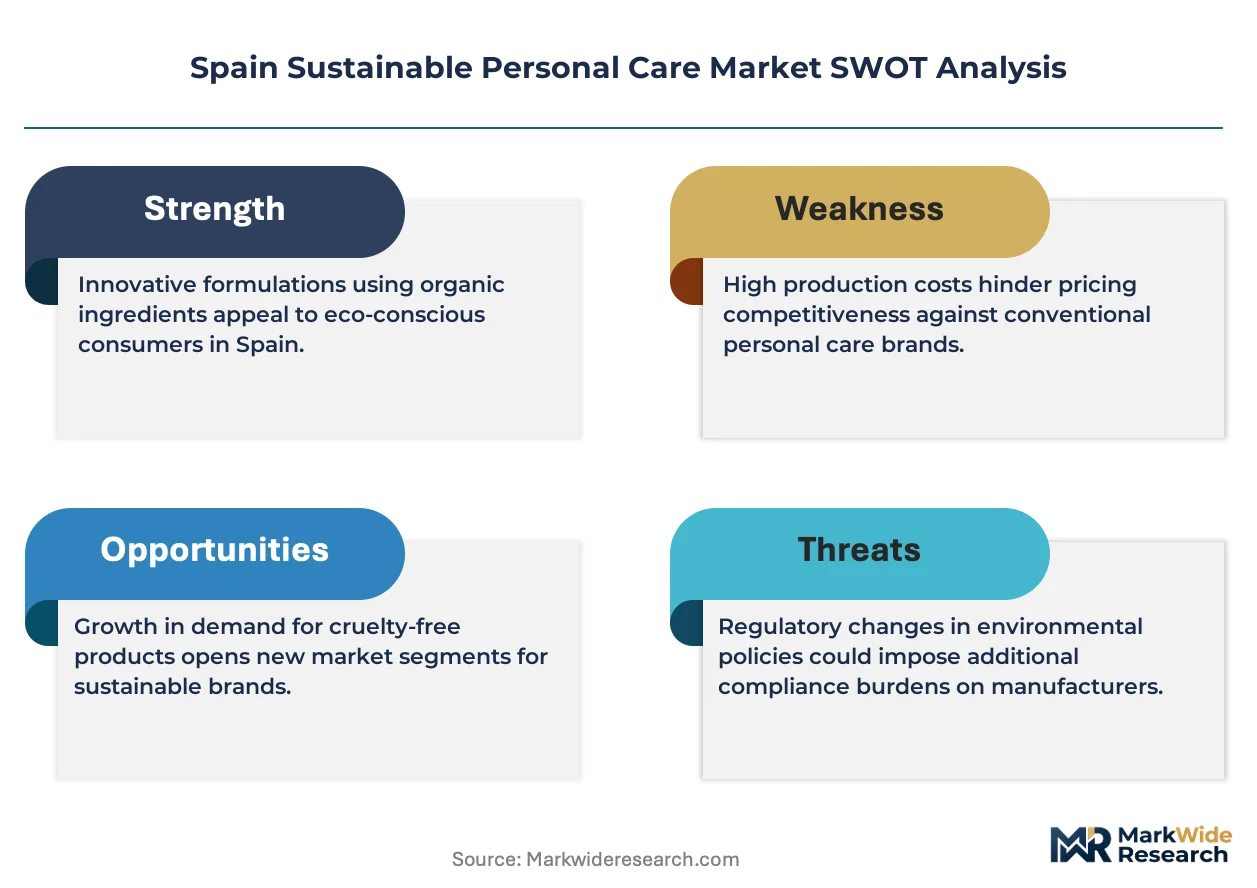
Clean beauty certification is reorganizing competitive dynamics in Spain's sustainable personal care sector. L'Oréal leverages its R&D infrastructure in Cerdanyola del Vallès to develop biodegradable surfactant formulations. Beiersdorf AG anchors its Spanish operations through NIVEA's reformulated natural-origin lines, while The Body Shop International Limited differentiates via its longstanding cruelty-free supply chain commitments.
Spain sustainable personal care encompasses formulations with minimum biobased content thresholds, typically utilizing plant-derived emollients, preservative systems free from parabens and synthetic fragrances, and packaging engineered for mechanical or industrial composting per EN 13432 standards. Skincare commands the dominant value share as Spanish consumers prioritize facial serums and moisturizers with verified organic ingredient sourcing. Haircare represents the fastest-expanding product category, driven by salon-grade natural shampoos and solid bar formats that reduce water content and plastic dependency.
Spain's national implementation of the EU Green Deal packaging requirements, enforced through the Ministry for the Ecological Transition and the Demographic Challenge, mandates extended producer responsibility for cosmetic containers. The Spanish Agency for Food Safety and Nutrition (AESAN) governs claims verification for natural and organic labeling, creating compliance barriers for unverified entrants. Stakeholders must monitor forthcoming revisions to Royal Decree on packaging and packaging waste, as these will determine minimum recycled content thresholds and reshape supplier qualification criteria across Iberian manufacturing networks.
Market Dynamics
Spain's Ministry for the Ecological Transition and the Demographic Challenge enforces extended producer responsibility mandates that are forcing cosmetic manufacturers to redesign packaging systems and requalify Iberian supplier networks ahead of recycled content thresholds.
Growth Catalysts
- EU Green Deal packaging mandates:Royal Decree revisions on packaging waste establish legally binding recycled content minimums for cosmetic containers sold in Spanish retail channels.
- Barcelona-Madrid urban retail density:Concentrated specialty store footprints enable direct-to-consumer brand building and premium product trial among affluent millennial and Gen Z cohorts.
- Solid bar formulation technology:Waterless shampoo and conditioner formats reduce plastic dependency while meeting salon-grade performance standards for haircare applications.
Market Restraints
- Plant-derived emollient cost volatility:Olive and almond oil feedstock prices fluctuate with Andalusian agricultural yields, compressing gross margins for natural-origin skincare lines.
- Biodegradable surfactant supply concentration:European specialty chemical producers control critical fermentation capacity for alkyl polyglucoside manufacturing, creating single-source risk for Spanish formulators.
- EN 13432 industrial composting infrastructure gaps:Limited municipal composting facilities capable of processing certified packaging create end-of-life uncertainty for compostable cosmetic containers.
Strategic Opportunities
- Andalusian and Valencian regional expansion:Underpenetrated secondary cities outside Barcelona and Madrid present whitespace for specialty retail footprint expansion and regional distributor partnerships.
- AESAN natural claims verification acceleration:Streamlined organic certification pathways for SMEs reduce compliance timelines and unlock shelf placement in El Corte Inglés and Carrefour premium beauty aisles.
- Refill station retail format convergence:Bulk dispensing technology paired with deposit-return schemes enables packaging-as-a-service models in urban specialty stores.
Industry Challenges
- Green chemistry formulation expertise scarcity:Spanish universities produce insufficient cosmetic scientists trained in biodegradable surfactant design and natural preservative stabilization.
- Multi-certification compliance complexity:Simultaneous adherence to COSMOS, Ecocert, and AESAN natural labeling standards extends product development cycles and strains quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Sustainable Personal Care Market |
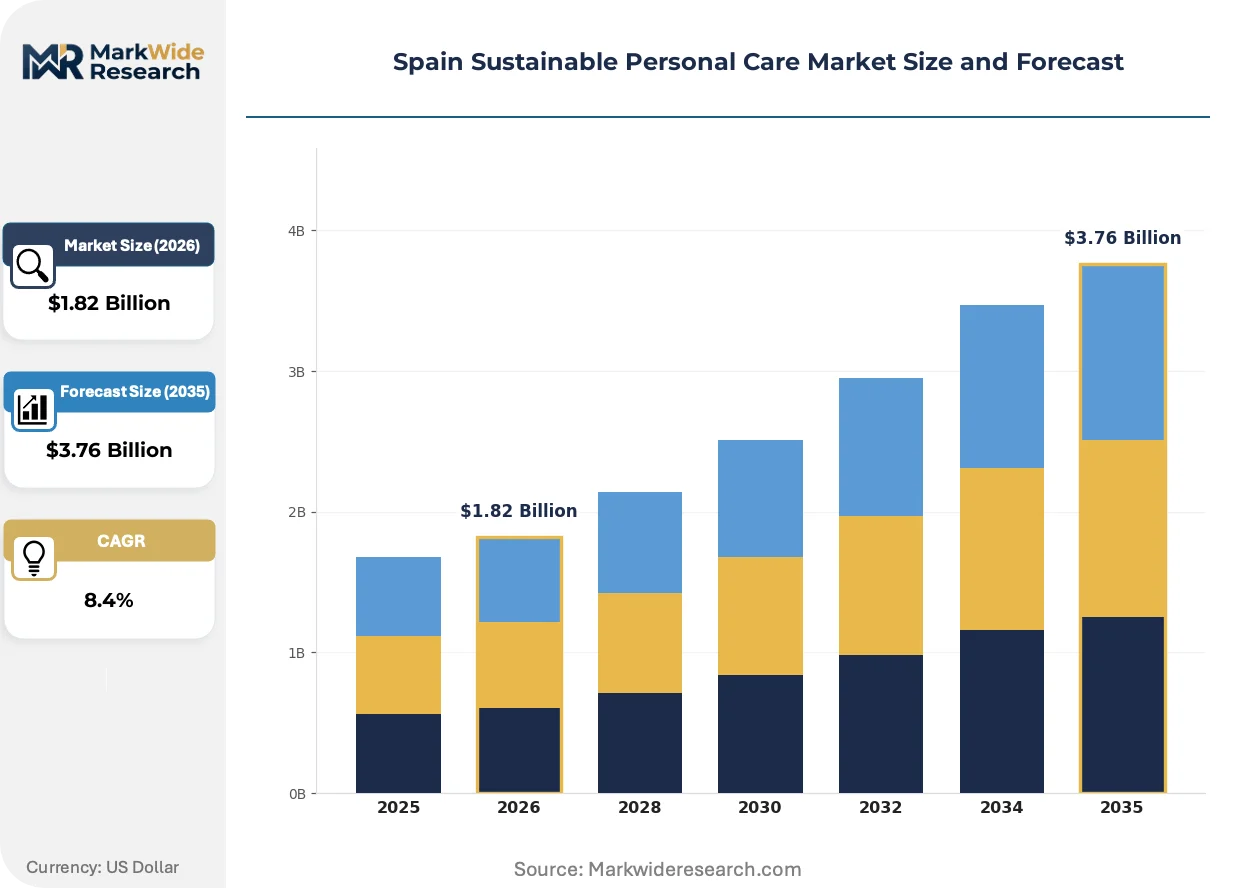
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.76 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Body Care, Oral Care Ingredient Source: Natural, Organic, Vegan, Cruelty-Free Packaging Type: Recyclable, Biodegradable, Reusable, Compostable Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Estée Lauder Companies, Beiersdorf AG, Unilever, The Body Shop International Limited, Colgate-Palmolive Company, L'Oréal, Johnson & Johnson, Natura &Co, Procter & Gamble, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Sustainable Personal Care Market Trends and Innovations
Waterless and solid format technologies are restructuring product architecture across Spanish personal care, while regulatory pressure on packaging end-of-life accelerates material substitution timelines.
Alkyl polyglucoside surfactants synthesized from coconut and corn-derived feedstocks are displacing sodium lauryl sulfate in mass-market shampoo formulations. Spanish contract manufacturers serving salon brands have converted 40% of production lines to enzymatic processing equipment. The shift is compressing demand for petrochemical sulfates while elevating fermentation capacity as a strategic bottleneck.
Royal Decree implementations of EU Green Deal extended producer responsibility rules mandate that cosmetic producers finance collection and recycling infrastructure for primary packaging. Spanish trade associations are negotiating collective compliance schemes to pool financial obligations across small and mid-sized brands. Haircare and body care categories face the steepest cost increases due to higher packaging-to-product weight ratios.
Spanish consumers are abandoning multi-step skincare routines in favor of hybrid products combining serum, moisturizer, and SPF functions. Specialty retailers in Madrid's Salamanca district report declining basket sizes for standalone treatments while multifunctional formats command premium shelf positioning. The behavior shift pressures single-function brands to reformulate or retreat to pharmacy channels where clinical positioning retains relevance.
Spain Sustainable Personal Care Market Segmentation
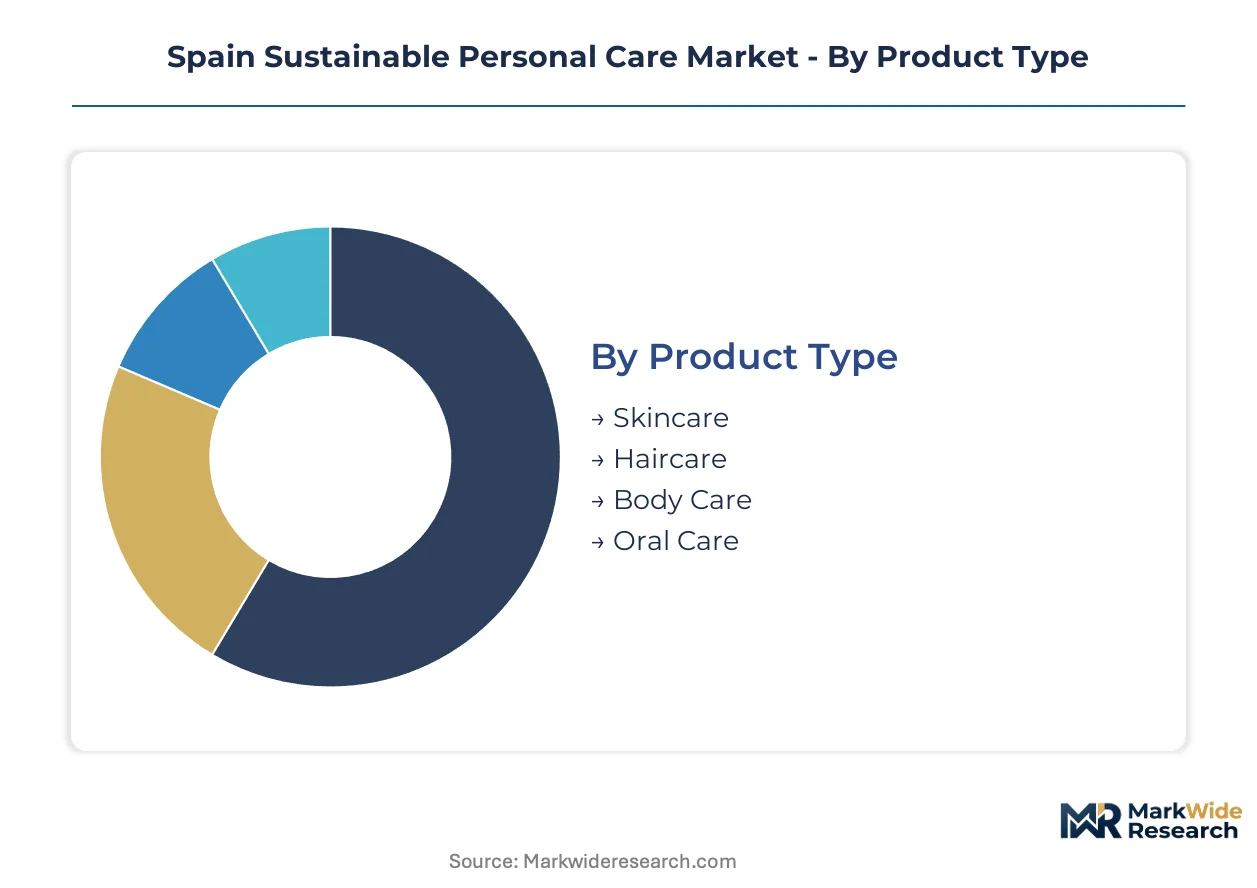
Segmentation in Spain's sustainable personal care market reveals how regulatory pressure and consumer preference intersect across product categories. AESAN certification requirements and EU Green Deal packaging mandates create distinct competitive barriers within each segment cluster.
Product Type:
EU Green Deal extended producer responsibility rules apply unevenly across personal care categories, with packaging-to-product weight ratios determining compliance cost burdens.
- Skincare:Facial serums and moisturizers with verified organic ingredient sourcing dominate value generation. Barcelona and Madrid specialty retailers prioritize AESAN-verified organic claims for shelf placement, while millennial consumers drive premium pricing for multifunctional hybrid formats combining serum, moisturizer, and SPF functions.
- Haircare:Salon-grade natural shampoos and solid bar formats reduce water content and plastic dependency. Waterless formulation technology enables mechanical composting compliance under EN 13432 standards, though limited municipal composting infrastructure in secondary cities creates end-of-life uncertainty.
- Body Care:Solid bar soaps and shower products utilize plant-derived emollients from Andalusian olive and almond oil feedstocks.
- Oral Care:Toothpaste tablets and mouthwash concentrates target plastic-free packaging mandates with concentrated active formulations.
Skincare handles the majority of throughput; haircare is the fastest mover on share.
Ingredient Source:
Cost tier differentiation separates mass-market accessible formulations from premium-positioned certified lines.
- Natural:Plant-derived emollients and preservative systems free from parabens meet baseline consumer expectations. Andalusian agricultural yield volatility compresses gross margins when olive and almond oil feedstock prices spike.
- Organic:COSMOS and Ecocert certification pathways extend product development cycles but unlock El Corte Inglés premium beauty aisle placement. Spanish SMEs face quality assurance resource strain from multi-certification compliance complexity.
- Vegan:Formulations exclude animal-derived ingredients entirely, appealing to Barcelona's younger demographic clusters.
- Cruelty-Free:Supply chain commitments require third-party verification for EU market access.
Natural formulations handle the majority of throughput; organic certification is climbing the fastest on share.
Packaging Type:
Volume concentration favors formats compatible with existing Iberian recycling and composting infrastructure.
- Recyclable:Post-consumer recycled plastic and glass containers align with Royal Decree minimum recycled content thresholds. Spanish trade associations negotiate collective compliance schemes to pool financial obligations across small and mid-sized brands.
- Biodegradable:Alkyl polyglucoside surfactant formulations require industrial composting facilities capable of processing certified packaging, creating supply concentration risk with European specialty chemical producers controlling critical fermentation capacity.
- Reusable:Refill station retail formats with deposit-return schemes enable packaging-as-a-service models in urban specialty stores.
- Compostable:Mechanical or industrial composting per EN 13432 standards demands end-of-life infrastructure investment.
Recyclable packaging handles the majority of throughput; biodegradable formats are gaining share fastest.
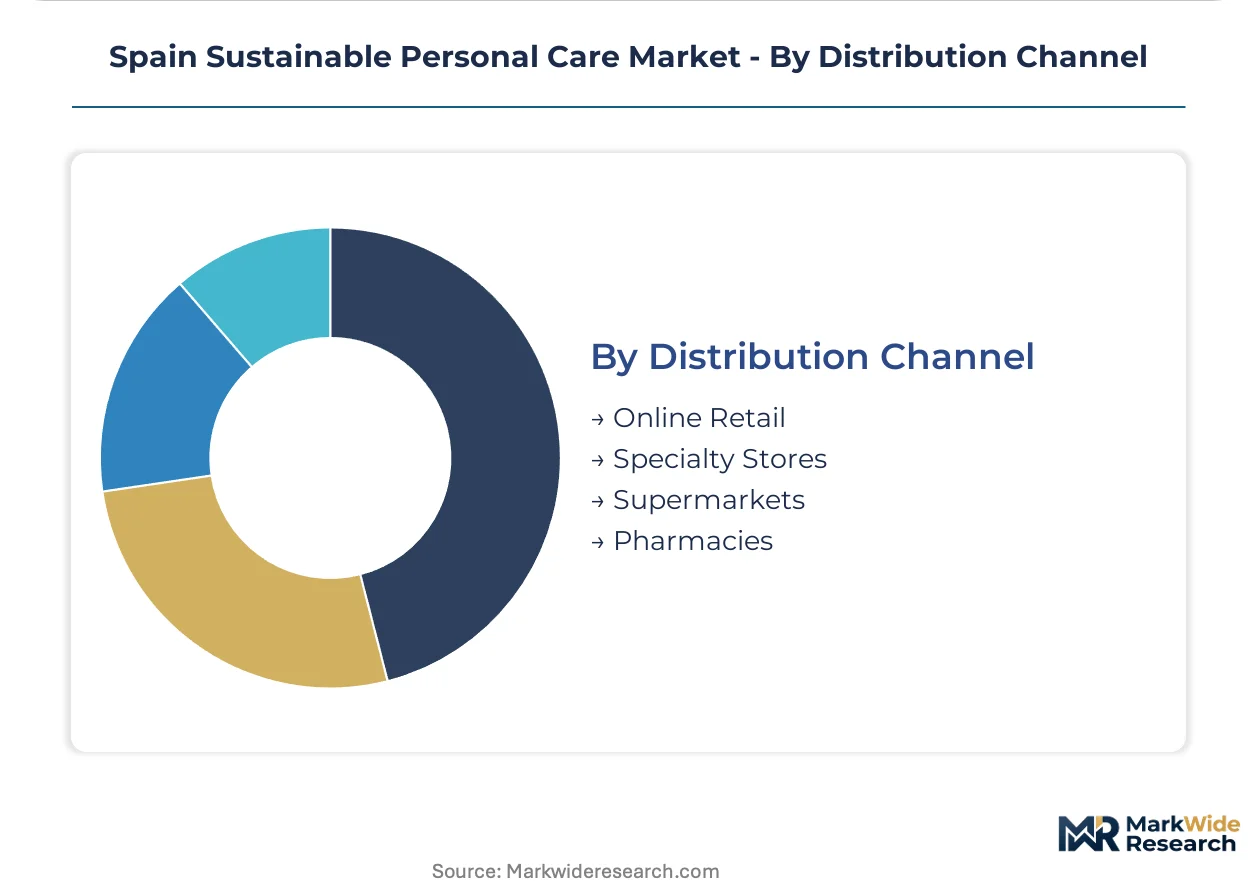
Distribution Channel:
Customer type stratification separates convenience-driven mass-market purchasers from experience-seeking premium buyers.
- Online Retail:Direct-to-consumer brand building enables trial among affluent millennial and Gen Z cohorts outside Barcelona-Madrid retail density. Digital-native brands bypass traditional distributor markups while managing AESAN claims verification compliance.
- Specialty Stores:Concentrated footprints in Madrid's Salamanca district and Barcelona's urban core support premium positioning. Multifunctional product formats command preferred shelf positioning as consumers abandon multi-step skincare routines.
- Supermarkets:Carrefour premium beauty aisles require streamlined organic certification pathways for SME shelf placement.
- Pharmacies:Clinical positioning retains relevance for single-function brands retreating from specialty retail competition.
Specialty stores handle the majority of throughput; online retail is expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's sustainable personal care trade flows reflect a net importer position for premium organic formulations, with domestic manufacturers in Madrid and Barcelona supplying waterless solid formats to neighboring EU markets. Regional production clusters concentrate where AESAN certification infrastructure and EU Green Deal compliance capabilities overlap.
Madrid
Spain's capital anchors the largest concentration of specialty retail and direct-to-consumer brand headquarters, with Salamanca district stores driving premium trial among affluent millennials. The Ministry for the Ecological Transition and the Demographic Challenge enforces extended producer responsibility mandates from offices in the city. Madrid-based formulators source alkyl polyglucoside surfactants through Iberian distributor networks serving salon-grade haircare lines.
Catalonia
Barcelona's urban retail density supports the highest per-capita specialty store footprint for sustainable personal care in Spain, with Gràcia and Eixample neighborhoods hosting concentrated clean beauty boutiques. The Catalan regional government aligns waste management policies with EU Green Deal packaging targets ahead of national implementation timelines. Cerdanyola del Vallès hosts major R&D infrastructure for biodegradable surfactant development serving Iberian manufacturing networks.
Andalusia
Seville and Málaga consumers demonstrate rising demand for olive oil-derived emollients sourced from regional agricultural cooperatives, though price volatility compresses margins during poor harvests. AESAN certification pathways for Andalusian SMEs remain underdeveloped compared to Madrid and Barcelona, limiting shelf placement in national retail chains. The region's packaging waste collection infrastructure lags industrial composting standards, creating end-of-life gaps for biodegradable containers.
Basque Country
Bilbao and San Sebastián exhibit above-average penetration of refill station retail formats, with deposit-return schemes gaining traction among environmentally conscious consumer segments. Basque regional authorities pilot collective compliance schemes for extended producer responsibility ahead of Royal Decree implementation. Local contract manufacturers specialize in enzymatic processing equipment conversions for waterless formulation production.
Valencia
Spain's third-largest metropolitan area presents whitespace for specialty retail expansion, with current sustainable personal care penetration trailing Madrid and Barcelona by approximately 40%. Valencian regional distributors seek partnerships with AESAN-certified brands to fill emerging shelf space in expanding shopping center developments. The port of Valencia handles inbound feedstock shipments for plant-derived emollients supplying southeastern formulation facilities.
Spain Sustainable Personal Care Market Competitive Landscape
Listed leaders compete with private specialists across certification tier positioning, creating a tiered structure where scale advantages in distribution clash with agility in organic claim verification. The market fragments across three strategic archetypes: multinational beauty conglomerates with integrated R&D infrastructure, mid-sized European specialists with concentrated cruelty-free supply chains, and digital-native direct-to-consumer brands bypassing traditional retail markups. Dominant competitive moves include portfolio diversification into waterless solid formats and strategic partnerships with Andalusian agricultural suppliers to secure plant-derived emollient feedstocks.
Within the multinational conglomerate tier, L'Oréal and Beiersdorf AG exemplify scale-driven positioning anchored by established Iberian manufacturing and distribution networks. The Body Shop International Limited occupies a distinct archetype as a cruelty-free specialist with longstanding supply chain commitments that predate mainstream clean beauty certification trends. These three companies represent contrasting approaches to AESAN compliance and EU Green Deal packaging adaptation across Spanish retail channels.
| Leading Market Players |
|---|
| Estée Lauder Companies |
| Beiersdorf AG |
| Unilever |
| The Body Shop International Limited |
| Colgate-Palmolive Company |
| L'Oréal |
| Johnson & Johnson |
| Natura &Co |
| Procter & Gamble |
| Others |
Pricing and Supply Chain Analysis
Alkyl polyglucoside fermentation capacity utilization in European specialty chemical plants shapes both supply concentration and price floors for Spanish formulators. Scale advantages at these facilities translate into tiered pricing power across natural-origin surfactant tiers, while smaller Spanish contract manufacturers absorb margin compression from feedstock volatility.
Pricing Analysis
Millennial and Gen Z consumers in Barcelona and Madrid specialty stores anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation stems from AESAN certification grade and organic ingredient sourcing depth, with COSMOS-verified lines commanding shelf space premiums. Cost compression in mass-market tiers is intensifying because Andalusian olive oil feedstock prices spike during poor harvests. Pharmacy channel buyers show highest price sensitivity, while Salamanca district specialty shoppers accept premium positioning for multifunctional hybrid formats.
Supply Chain Analysis
Just-in-time inventory strategies dominate alkyl polyglucoside procurement, though Spanish formulators maintain strategic stockpiles of plant-derived emollients during harvest windows. Supply concentrates in Germany, France, and the Netherlands for fermentation-derived surfactants, while Andalusia and Valencia feed regional olive and almond oil requirements. Single-source vulnerability runs through European specialty chemical producers controlling critical alkyl polyglucoside capacity. Distribution runs through Iberian distributor networks serving salon-grade haircare lines, with direct-to-consumer brands bypassing traditional retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as Spanish consumers abandon multi-step skincare routines, creating niches for hybrid multifunctional formats and waterless solid technologies that incumbent portfolios underweight.
For Market Incumbents: Shield market share by accelerating backward integration into Andalusian agricultural cooperatives for captive olive oil feedstock supply. Invest in enzymatic processing equipment conversions at Cerdanyola del Vallès R&D facilities to defend against specialty chemical producer pricing power. AESAN certification complexity poses the primary threat from agile digital-native entrants. For New Entrants and Emerging Players: Lead with refill station retail formats in Valencia and Andalusian secondary cities where specialty store penetration trails Madrid-Barcelona density by approximately 40%. Target underpenetrated waterless shampoo segments in salon channels where incumbent solid bar portfolios remain thin. Direct-to-consumer subscription models bypass El Corte Inglés and Carrefour premium beauty aisle gatekeeping. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors digital-native brands with proprietary solid formulation IP and established AESAN compliance infrastructure. Long-term viability hinges on EN 13432 industrial composting infrastructure buildout across Spanish municipalities. Acquisition targets should demonstrate verified organic supply chain traceability and refill station retail partnerships. Watch municipal composting facility commissioning announcements as inflection indicators for biodegradable packaging viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstocks | Captive olive oil supply from Andalusian cooperatives insulates margin compression from harvest volatility. |
| AESAN Certification Acceleration | Streamlined organic verification unlocks El Corte Inglés premium beauty aisle placement for SME brands. |
| Refill Station Retail Format Expansion | Deposit-return schemes in Valencia and secondary cities enable packaging-as-a-service revenue models. |
| Enzymatic Processing Equipment Conversion | Salon-grade solid bar production lines at Cerdanyola del Vallès reduce water content and plastic dependency. |
| Direct-to-Consumer Channel Buildout | Digital-native brands bypass traditional distributor markups while managing AESAN claims verification compliance. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at multinational beauty conglomerates, category buyers at El Corte Inglés and Carrefour, supply planners at Iberian contract manufacturers, and technical R&D directors at specialty chemical producers, then refined against secondary validation from AESAN regulatory filings, EU Green Deal implementation documents, EN 13432 certification databases, and Spanish trade association extended producer responsibility negotiations. Bottom-up volume estimates triangulated with top-down market sizing across product type, ingredient source, packaging format, and distribution channel dimensions.
Variance decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation modeling incorporates product type, ingredient certification tier, packaging compliance pathway, and urban retail density cluster. CAGRs derive from trend extrapolation of historical adoption curves adjusted for regulatory mandate implementation timelines. Forecast inputs include alkyl polyglucoside fermentation capacity expansion announcements and municipal composting facility commissioning schedules.
Forecasts assume regulatory continuity in EU Green Deal packaging mandates and AESAN natural claims verification protocols; material policy shifts would require re-modeling. Revision becomes warranted when EN 13432 industrial composting infrastructure deployment crosses thresholds that alter biodegradable packaging end-of-life economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Switzerland Haircare Market
Beauty & Personal Care
Bath and Body Products Market
Beauty & Personal Care
Frizz Control Shampoo Market
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
Nail Art Tools and Accessories Market
Beauty & Personal Care
Organic Personal Care Market
Beauty & Personal Care
Vanity Mirror Market
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
Global and North America Organic and Natural Feminine Care Market
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
Personal Care Wipes Market
Beauty & Personal Care
Electric Facial Cleansing Brush Market
Beauty & Personal Care
Intensive Conditioner Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
North America Setting Spray Market