
 Global CRISPR and CRISPR-Associated (Cas) Genes Market | 2026-2036
Global CRISPR and CRISPR-Associated (Cas) Genes Market Size, Share, and Industry Trends Forecast 2026-2036
Global CRISPR and CRISPR-Associated (Cas) Genes Market Foresight
China is reconfiguring its biomanufacturing infrastructure around precision genome engineering platforms. Thermo Fisher Scientific leverages its reagent and instrument integration to sustain workflow dominance across clinical and research settings. GenScript anchors Asia-Pacific supply chains through its synthetic biology foundry capacity in Nanjing.
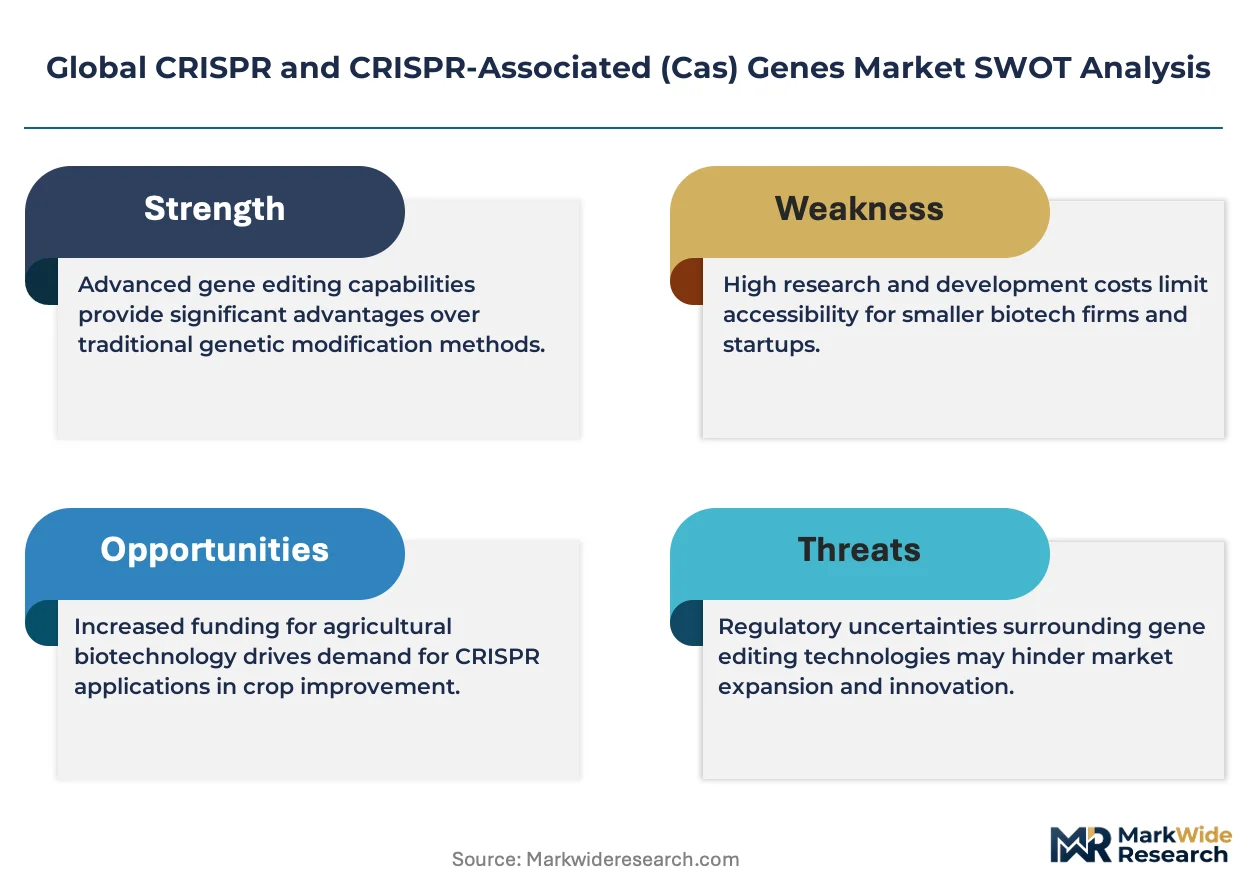
CRISPR and CRISPR-Associated (Cas) genes constitute a family of RNA-guided nuclease systems, with Cas9 requiring a protospacer adjacent motif (PAM) sequence for DNA cleavage and Cas12 enabling collateral single-stranded DNA degradation. These systems enable programmable genome editing for therapeutic correction, agricultural trait modification, and molecular diagnostic signal amplification. Cas9 gene types occupy the largest installed base due to historical protocol standardization, while Cas12 and Cas13 variants capture faster expansion in diagnostic and epigenome editing applications where collateral activity or RNA targeting proves advantageous. Therapeutic development within end-use applications commands premium pricing, though academic research generates the highest volume consumption of plasmid and protein reagents.
The FDA maintains gene therapy guidance frameworks that dictate investigational new drug submission requirements for CRISPR-based candidates, while the EMA's ATMP classification shapes European market access pathways. China's NMPA has issued technical review guidelines for gene editing therapeutics that accelerate domestic trial approvals. Stakeholders must monitor regulatory divergence between jurisdictions as it determines where clinical assets advance first and where manufacturing partnerships concentrate.
Market Dynamics
Precision genome engineering platforms are fragmenting the therapeutic development pipeline, as academic spinouts bypass traditional pharmaceutical partnerships to retain intellectual property control over CRISPR-derived assets.
Growth Catalysts
- Gene therapy guidance frameworks:The FDA's evolving investigational new drug submission requirements for CRISPR-based candidates are clarifying clinical trial pathways and accelerating sponsor confidence in therapeutic development timelines.
- Collateral activity applications:Cas12 and Cas13 variants enable molecular diagnostic signal amplification through collateral single-stranded DNA degradation, opening high-volume testing markets beyond therapeutic editing.
- China:The NMPA's technical review guidelines for gene editing therapeutics compress domestic trial approval timelines, redirecting clinical asset development toward Chinese manufacturing partnerships.
Market Restraints
- Plasmid supply concentration:Foundry capacity for synthetic biology reagents clusters in Nanjing and Boston, creating geographic single-point vulnerabilities for global therapeutic programs.
- PAM sequence dependency:Cas9's requirement for protospacer adjacent motif sequences limits editable genomic loci, constraining therapeutic target selection in certain genetic disorders.
- EMA ATMP classification friction:The European Medicines Agency's advanced therapy medicinal product pathway imposes manufacturing complexity requirements that extend market access timelines for CRISPR developers.
Strategic Opportunities
- Epigenome editing white space:Cas12-based systems without double-strand breaks enable reversible gene modulation, attracting agricultural trait developers seeking regulatory-light modification pathways.
- India:The CDSCO's emerging gene therapy framework and PLI scheme for biopharmaceutical manufacturing create first-mover advantages for reagent suppliers establishing local production.
- Artificial intelligence convergence:Machine learning-guided guide RNA design is collapsing optimization cycles for CRISPR efficiency, enabling bench-scale researchers to compete with institutional bioinformatics cores.
Industry Challenges
- Guide RNA synthesis bottlenecks:Chemically modified RNA manufacturing requires specialized oligonucleotide foundries, and talent scarcity in nucleic acid chemistry constrains capacity expansion at contract manufacturers.
- Cross-jurisdictional regulatory divergence:Sponsors must maintain parallel quality management systems to satisfy FDA gene therapy guidance, EMA ATMP requirements, and NMPA technical standards simultaneously.
- Delivery vector IP thickets:Lipid nanoparticle and viral capsid patent estates surrounding CRISPR cargo transport create licensing complexity that consumes 18-24 months of preclinical development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CRISPR and CRISPR-Associated (Cas) Genes Market |
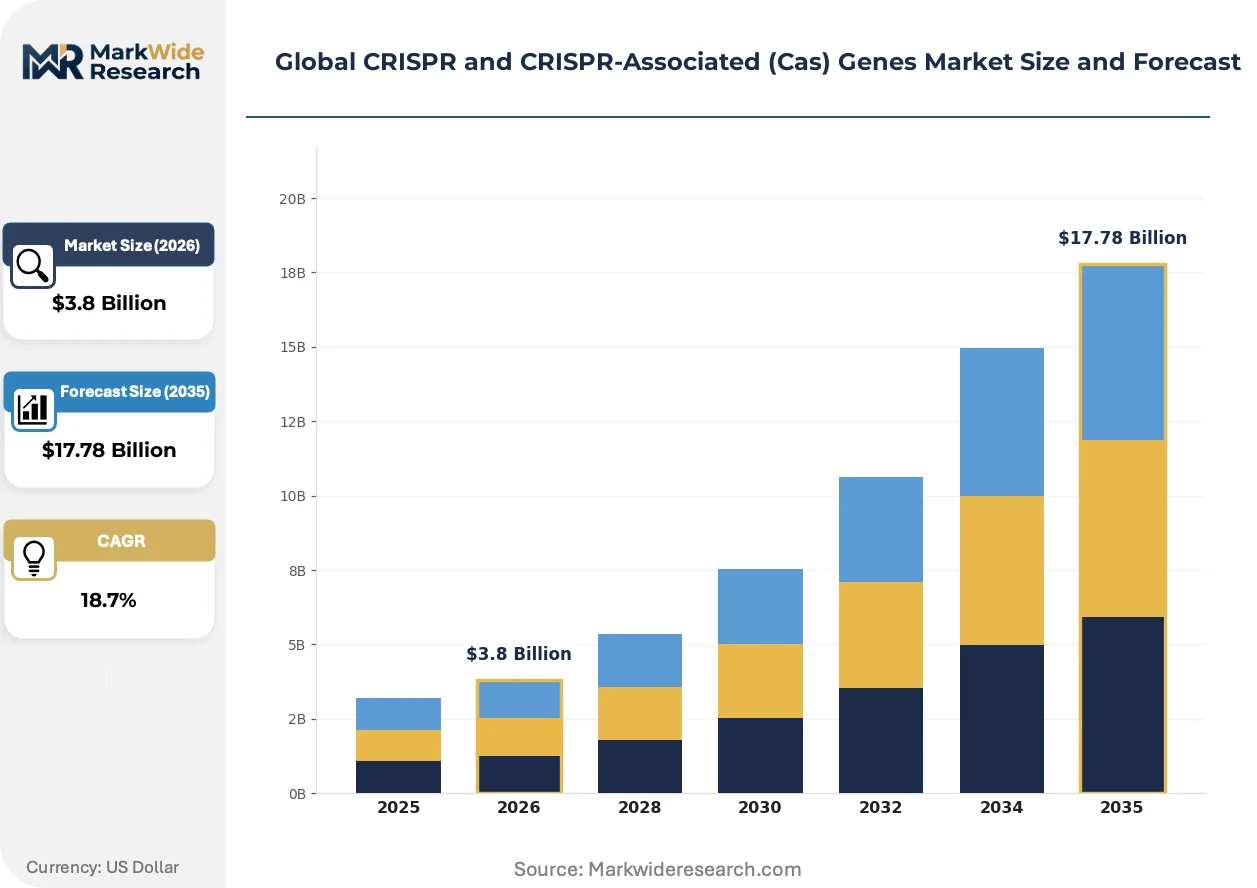
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Gene Type: Cas9, Cas12, Cas13, Cas14, dCas9 End Use Application: Gene Editing, Epigenome Editing, Gene Regulation, Diagnostic Tools, Therapeutic Development Delivery Method: Viral Vectors, Lipid Nanoparticles, Electroporation, Microinjection, Ribonucleoprotein Complexes Industry Sector: Biopharmaceuticals, Agricultural Biotechnology, Industrial Biotechnology, Academic Research, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific, OriGene Technologies, Illumina, Agilent Technologies, Danaher, GenScript, Merck KGaA, Lonza, Synthego, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CRISPR and CRISPR-Associated (Cas) Genes Market Shifts & Advancements
Base editing and prime editing modalities are compressing the therapeutic risk profile by eliminating double-strand break liabilities, redirecting capital toward previously intractable monogenic indications.
Prime editing systems deploy engineered reverse transcriptase fused to nicked Cas9 variants, enabling all 12 types of point mutation correction without donor DNA templates. Academic medical centers in Boston and San Francisco are adopting these platforms for sickle cell and beta-thalassemia programs. The technology is collapsing the distinction between gene correction and gene insertion, as single-protein systems now accomplish what previously required dual-vector delivery.
The EMA's ATMP classification framework now explicitly addresses ex vivo edited cell products, requiring centralized manufacturing facility inspections that extend approval timelines by 8-14 months. European sponsors are responding by segregating clinical trial phases across member states to optimize regulatory parallel processing. Germany's Paul-Ehrlich-Institut and France's ANSM have developed divergent interpretation guidelines for genome stability assessment, fragmenting the European development pathway.
Consolidated buying by multi-site academic consortia is displacing individual laboratory procurement of CRISPR reagents, as shared service cores negotiate enterprise pricing with synthetic biology suppliers. This channel compression concentrates volume with workflow-integrated vendors capable of instrument-reagent bundling. The pattern is most visible in United States research institutions, where NIH funding consolidation has accelerated core facility centralization over the past funding cycle.
Global CRISPR and CRISPR-Associated (Cas) Genes Market Segmentation
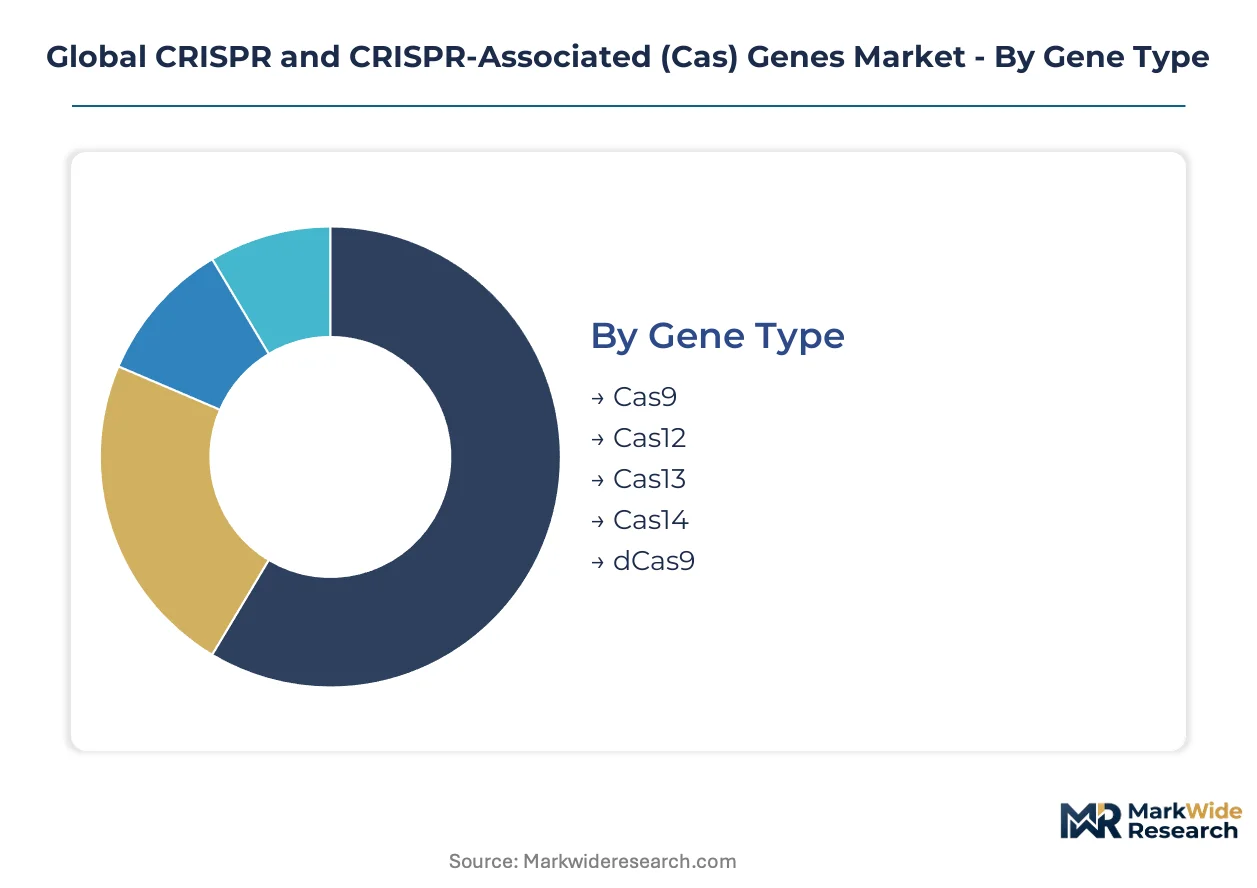
CRISPR market segmentation reveals how technical specifications, delivery constraints, and end-use economics fragment procurement patterns across therapeutic and research workflows. Understanding these dimensions exposes where pricing power concentrates and which technology transitions reshape vendor relationships.
Gene Type:
Cost tier stratification separates established nuclease platforms from emerging variants competing on functional specialization.
- Cas9:The prototypical RNA-guided nuclease requires PAM sequence recognition for DNA cleavage. Demand concentrates in academic research cores at MIT and Stanford where protocol standardization sustains volume purchasing, though PAM dependency limits therapeutic target accessibility in certain monogenic disorders.
- Cas12:Enables collateral single-stranded DNA degradation for molecular diagnostic applications. Adoption is climbing fastest in Shenzhen and Boston bioclusters where CRISPR-based infectious disease testing platforms require signal amplification without qPCR infrastructure.
- Cas13:Targets RNA molecules directly, opening transcriptome editing and mRNA modulation applications. Pharmaceutical sponsors in Basel and Cambridge are evaluating this modality for temporary gene knockdown without permanent genomic alteration.
- Cas14:Ultra-compact nuclease variant derived from archaeal systems. Synthetic biology foundries in Nanjing are integrating this format for viral vector payload minimization.
- dCas9:Catalytically dead variant enabling programmable DNA binding without cleavage. Epigenome editing programs at the Broad Institute and UCSF are deploying this architecture for reversible chromatin modification.
Cas9 holds installed capacity. Cas12 is rotating up the share rankings.
End Use Application:
Application maturity determines whether segments command premium pricing or compete on reagent volume.
- Gene Editing:Permanent genomic alteration through double-strand break repair mechanisms. Therapeutic development pipelines at Editas Medicine and Intellia Therapeutics are driving clinical-grade plasmid demand, though FDA gene therapy guidance extends IND preparation timelines.
- Epigenome Editing:Reversible gene modulation without DNA cleavage using dCas9-effector fusions. Agricultural biotechnology developers in Research Triangle Park are pursuing this pathway to bypass GMO classification regimes in key export markets.
- Gene Regulation:Transcriptional activation or repression via CRISPRa/CRISPRi systems. Academic screening programs generate high-volume sgRNA library consumption.
- Diagnostic Tools:Collateral cleavage-based signal detection for point-of-care testing. SHERLOCK and DETECTR platform licensing is concentrating manufacturing partnerships in specific regulatory jurisdictions.
- Therapeutic Development:Ex vivo and in vivo clinical candidates requiring GMP-compliant reagent supply chains. CDMO selection criteria prioritize nucleic acid chemistry capabilities over geographic proximity.
Gene Editing captures the revenue concentration. Diagnostic Tools are expanding most quickly.
Delivery Method:
Supply concentration in vector manufacturing creates tiered access economics across delivery modalities.
- Viral Vectors:Adeno-associated virus and lentiviral systems dominate ex vivo cell therapy delivery. Capacity constraints at CDMOs in Pennsylvania and North Carolina are extending campaign wait times for CRISPR cargo programs.
- Lipid Nanoparticles:Synthetic lipid formulations enable liver-targeted in vivo editing. Patent thickets around ionizable lipid compositions are forcing 18-month licensing negotiations before preclinical initiation.
- Electroporation:Physical membrane permeabilization for ex vivo cell modification. Manufacturing simplicity attracts academic researchers with limited viral production infrastructure.
- Microinjection:Direct cytoplasmic delivery for embryo editing applications. Agricultural seed developers in St. Louis rely on this precision approach for trait stacking.
- Ribonucleoprotein Complexes:Pre-assembled Cas protein-guide RNA complexes minimize off-target effects. GMP manufacturing of modified RNA guides requires specialized oligonucleotide foundries with limited global capacity.
Viral Vectors hold installed capacity. Lipid Nanoparticles are climbing the fastest.
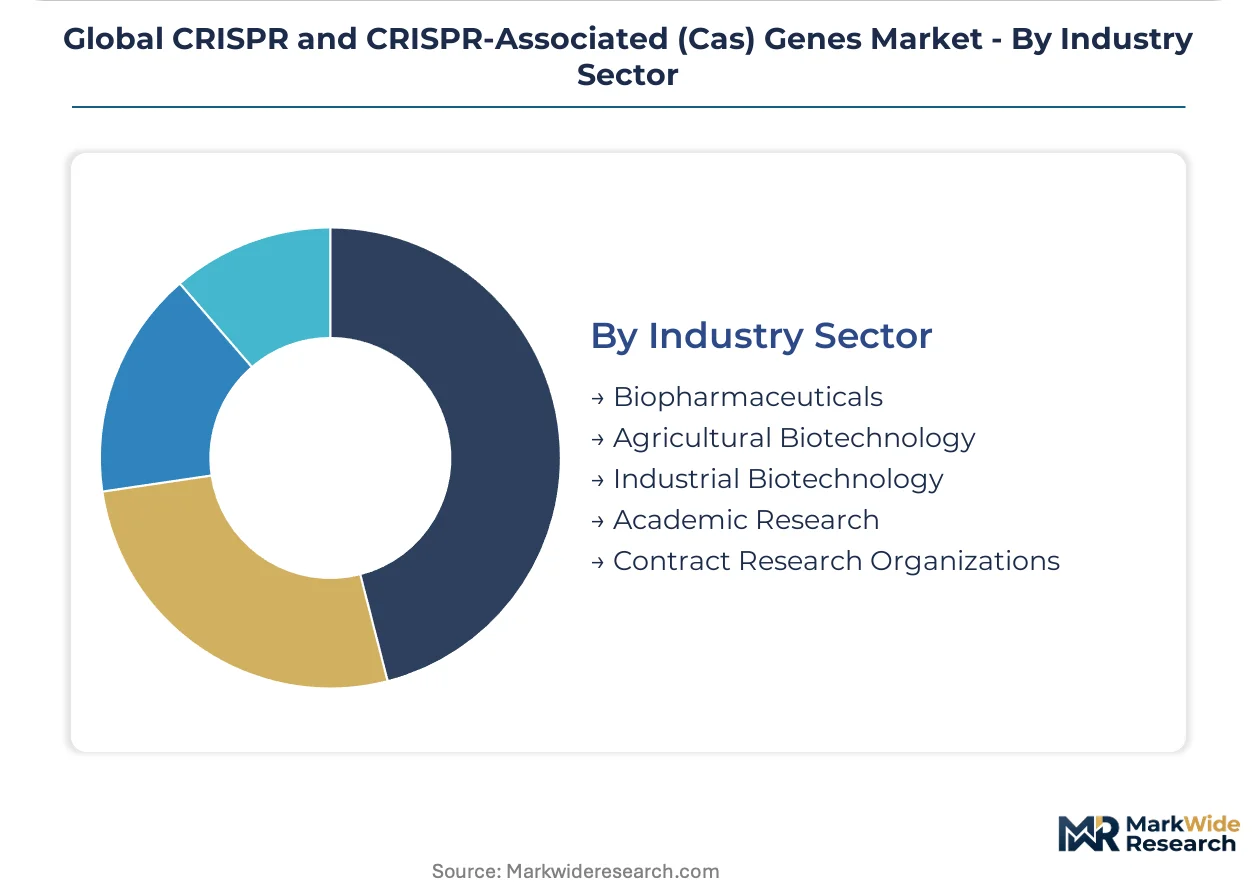
Industry Sector:
Customer type determines procurement scale, specification stringency, and vendor relationship structure.
- Biopharmaceuticals:Sponsored therapeutic programs requiring audit-ready supply chains and regulatory documentation packages. Consolidated buying power at large-cap developers is squeezing margin structures for reagent suppliers.
- Agricultural Biotechnology:Trait development programs navigating divergent GMO regulatory frameworks across export markets. Brazil's CTNBio and Argentina's CONABIA classification decisions determine commercialization pathways for edited crops.
- Industrial Biotechnology:Microbial strain engineering for enzyme and chemical production. Yeast and CHO cell line developers prioritize editing efficiency metrics over therapeutic-grade purity specifications.
- Academic Research:Highest-volume consumption segment with price-sensitive procurement through shared service cores. NIH funding consolidation is accelerating enterprise pricing negotiations with workflow-integrated vendors.
- Contract Research Organizations:Service providers bridging technical execution between platform companies and end users. CDMO selection increasingly weights nucleic acid chemistry capabilities alongside cell processing expertise.
Academic Research holds installed capacity. Biopharmaceuticals is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA gene therapy guidance frameworks anchor the United States as the dominant geography, while regulatory divergence across jurisdictions redirects clinical asset flows and manufacturing partnerships toward specific national pathways.
United States
Boston and San Francisco bioclusters drive platform development through academic medical centers adopting prime editing for sickle cell programs. The FDA's evolving investigational new drug submission requirements clarify clinical trial pathways for CRISPR-based candidates. Massachusetts and California concentrate therapeutic development pipelines, with Editas Medicine and Intellia Therapeutics anchoring clinical-grade plasmid demand.
China
Nanjing synthetic biology foundries supply Asia-Pacific reagent chains through GenScript's manufacturing capacity. The NMPA's technical review guidelines for gene editing therapeutics compress domestic trial approval timelines. Shenzhen bioclusters adopt Cas12-based diagnostic platforms for infectious disease testing without qPCR infrastructure.
Germany
The Paul-Ehrlich-Institut interprets genome stability assessment guidelines divergently from France's ANSM, fragmenting European development pathways. EMA ATMP classification imposes manufacturing complexity requirements extending market access timelines. Berlin-Brandenburg and Bavaria host centralized manufacturing facility inspections that add 8-14 months to approval processes.
India
The CDSCO's emerging gene therapy framework and PLI scheme for biopharmaceutical manufacturing create first-mover advantages for reagent suppliers. CDSCO technical standards for gene editing therapeutics remain under development. Maharashtra and Karnataka bioclusters attract local production investments as sponsors seek regulatory parallel processing outside saturated Western jurisdictions.
Switzerland
Swissmedic's advanced therapy medicinal product pathway offers alternative European market access for sponsors seeking regulatory efficiency. Basel pharmaceutical sponsors evaluate Cas13 modalities for temporary gene knockdown without permanent genomic alteration. The Zurich-Lausanne corridor concentrates epigenome editing research programs seeking reversible chromatin modification pathways.
Global CRISPR and CRISPR-Associated (Cas) Genes Market Competitive Landscape
Capability concentration sits with specialized nucleic acid chemistry foundries; scale advantage sits with workflow-integrated life science conglomerates. The market structures around three tiers: instrument-reagent bundlers sustaining enterprise pricing with academic consortia, synthetic biology foundries anchoring regional supply chains, and precision genome engineering platform companies retaining intellectual property control through academic spinouts. Consolidation pressures favor M&A targeting oligonucleotide manufacturing capabilities, while strategic partnerships concentrate around GMP-compliant guide RNA supply chains.
Among workflow-integrated conglomerates, Thermo Fisher Scientific and Danaher exemplify instrument-reagent bundling strategies that concentrate volume with shared service cores. GenScript represents the synthetic biology foundry archetype anchoring Asia-Pacific supply chains through Nanjing manufacturing capacity. Merck KGaA and Lonza occupy positions bridging CDMO selection criteria toward nucleic acid chemistry capabilities. Synthego sits within the specialized guide RNA synthesis tier where talent scarcity constrains capacity expansion.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| OriGene Technologies |
| Illumina |
| Agilent Technologies |
| Danaher |
| GenScript |
| Merck KGaA |
| Lonza |
| Synthego |
| Others |
Supply & Pricing Matrix
Undercapacity at specialized oligonucleotide foundries in Nanjing and Boston is forcing CRISPR reagent suppliers into allocation decisions that favor enterprise contracts over spot orders, compressing margins for academic buyers while sustaining premium pricing for GMP-grade therapeutic supply.
Pricing Analysis
Price spreads between GMP-compliant guide RNA synthesis and research-grade reagents exceed fivefold across the United States and China markets. Three-tier pricing structure across premium, standard, and economy levels separates audit-ready therapeutic supply from core facility bundles and individual laboratory spot purchases. Cost compression in research-grade plasmids is intensifying because consolidated academic consortia negotiate enterprise discounts with workflow-integrated vendors. Academic shared service cores exhibit highest price sensitivity, while biopharmaceutical sponsors prioritize nucleic acid chemistry capabilities over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for CRISPR reagent suppliers serving dual-hemisphere therapeutic programs. Foundry capacity clusters in China, the United States, and Switzerland, with synthetic biology manufacturing drawing from phosphoramidite chemistries, modified nucleoside feedstocks, and specialized purification resins. Single-source vulnerability concentrates at contract manufacturers with GMP oligonucleotide capabilities. Distribution runs through direct vendor relationships with academic consortia and CDMO partnerships for therapeutic developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CRISPR market is exiting a capital-constrained trough as FDA gene therapy guidance clarity and NMPA accelerated approvals restore sponsor confidence in clinical development timelines.
For Market Incumbents: Harden GMP guide RNA manufacturing capabilities through captive supply of modified nucleoside precursors, insulating against raw material allocation shocks from phosphoramidite suppliers. Deepen backward integration into oligonucleotide chemistry talent pools to offset foundry capacity constraints constraining therapeutic program expansion.
For New Entrants and Emerging Players: Build out Cas12-based diagnostic platform licensing in India and Southeast Asia, where CDSCO emerging frameworks and infectious disease testing infrastructure gaps create first-mover advantages. White-space availability concentrates in point-of-care collateral cleavage applications bypassing qPCR capital requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among synthetic biology foundries with multi-year supply agreements anchoring Asia-Pacific reagent chains. Long-term viability over the next decade rests on nucleic acid chemistry capability scarcity rather than instrument-reagent bundling scale. Acquisition targets should demonstrate GMP guide RNA manufacturing readiness and established relationships with NMPA or FDA regulatory pathways. The signal to monitor is CDSCO technical standard finalization triggering local production investments.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Enables IND submission for CRISPR-based candidates under FDA gene therapy guidance. |
| Regulatory Parallel Processing | Accelerates asset development across NMPA, FDA, and EMA jurisdictions simultaneously. |
| Backward Integration into Oligonucleotide Chemistry | Secures modified RNA guide supply against foundry capacity bottlenecks. |
| Diagnostic Platform Licensing | Opens high-volume testing markets through Cas12 collateral cleavage applications. |
| Prime Editing Pipeline Advancement | Eliminates double-strand break liabilities for sickle cell and beta-thalassemia programs. |
Research Methodology
Operator-level perspectives from CRISPR platform executives, regulatory affairs leads at gene therapy sponsors, GMP manufacturing officers at CDMOs, and procurement managers at academic shared service cores anchored the qualitative base. Primary interviews combined with secondary validation against FDA gene therapy guidance documents, NMPA technical review guidelines, EMA ATMP classification frameworks, ClinicalTrials.gov entry patterns, and SEC filings from publicly traded precision genome engineering companies. Bottom-up reagent volume estimates triangulated against top-down therapeutic pipeline valuations.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling across gene type, end-use application, delivery method, and industry sector dimensions. CAGRs derived from therapeutic development pipeline maturation curves, diagnostic platform adoption rates, and academic research funding consolidation patterns. Forecast inputs incorporated NMPA approval timeline compression effects and EMA ATMP inspection delay assumptions.
Practitioners should monitor regulatory divergence between FDA, EMA, and NMPA jurisdictions for early signals of clinical asset flow redirection. Forecasts reflect assumptions regarding GMP guide RNA manufacturing capacity expansion and patent estate resolution timelines for lipid nanoparticle delivery vectors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
India Gene Editing Market
Gene Editing & CRISPR
Rare NGR1 Fusion Market
Gene Editing & CRISPR
CRISPR Technology Market
Gene Editing & CRISPR
Genome Editing Market
Gene Editing & CRISPR
CAS9 Technology Market
Gene Editing & CRISPR
Mutation Detection Kits in Genome Editing Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
China Gene Editing Market
Gene Editing & CRISPR
Gene Editing Technology Market
Gene Editing & CRISPR
CRISPR Gene Detection and Diagnostic Market
Gene Editing & CRISPR
North America Gene Synthesis Market
Gene Editing & CRISPR
Cloning and Mutagenesis Market
Gene Editing & CRISPR
Cas9 Nuclease Market
Gene Editing & CRISPR
Italy Gene Editing Market
Gene Editing & CRISPR
Global Plant Breeding and CRISPR Plant Market
Gene Editing & CRISPR
Japan Gene Editing Market