
 Intimate Wash Care Products Market | 2026-2036
Intimate Wash Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Intimate Wash Care Products Market Outlook
The capital-intensity divergence between mass-market and clinical-grade intimate wash care producers is unwinding as smaller brands access contract manufacturing networks previously controlled by multinationals. Procter & Gamble Company leverages its global distribution infrastructure to sustain shelf dominance in mainstream retail channels across North America and Western Europe. The Himalaya Drug Company anchors its position through Ayurvedic ingredient positioning that differentiates its portfolio in price-sensitive Asian markets.
Intimate wash care products are pH-balanced topical cleansers formulated within the 3.8 to 4.5 acidity range to preserve vulvar microbiome integrity while removing sweat, sebum, and external residues without stripping protective lipid barriers. Foam formats lead volume sales in developed markets due to dispenser convenience and perceived hygiene, while gel formulations capture faster growth in professional and clinical recommendation channels where viscosity signals concentrated active delivery. Natural ingredient positioning commands premium shelf placement and expanded margin pools, whereas synthetic antibacterial variants face reformulation pressure as regulatory scrutiny tightens on triclosan and chlorhexidine alternatives.
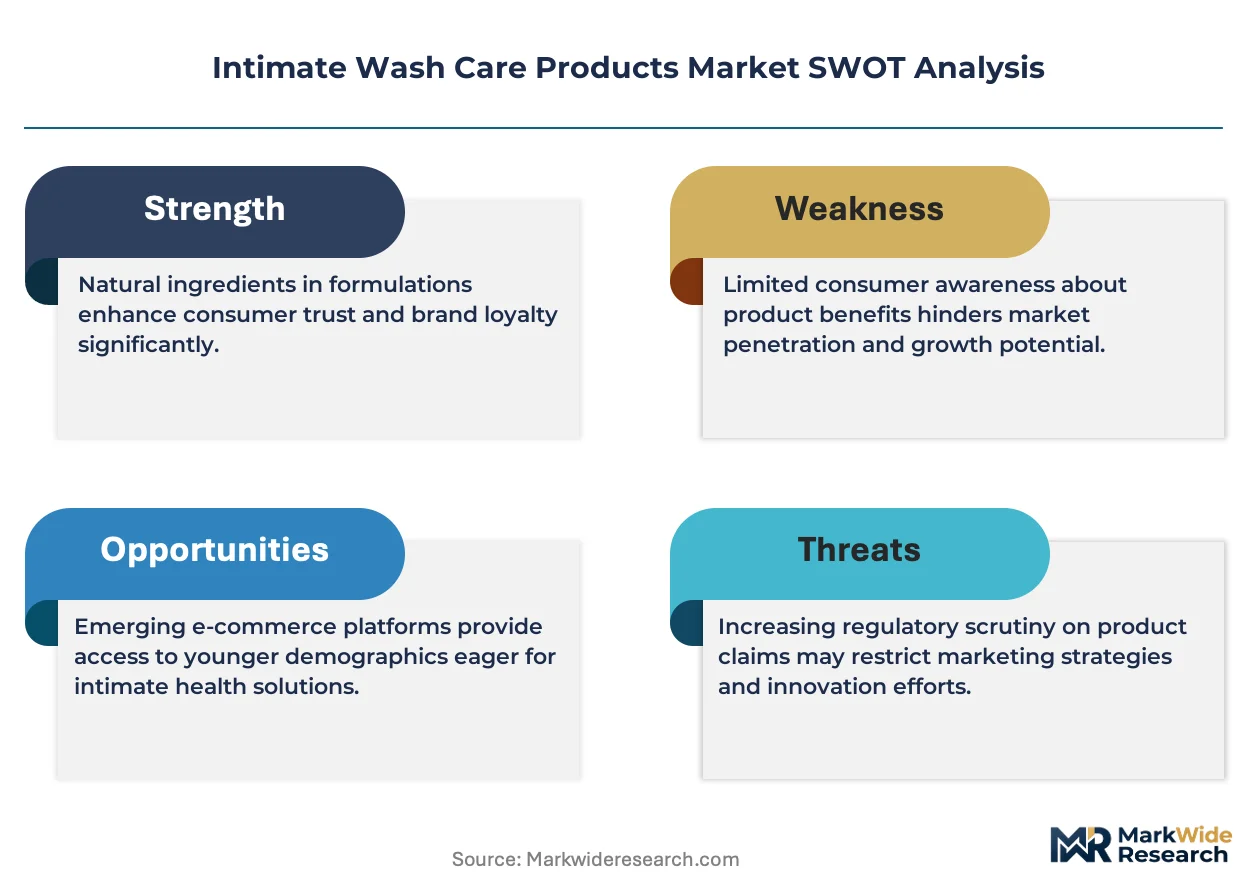
FDA cosmetic labeling requirements and EU REACH chemical safety assessments shape formulation roadmaps and import compliance costs for brands operating across transatlantic markets. India's CDSCO and BIS standards for personal care products increasingly mandate disclosure of herbal claim substantiation, redirecting R&D investment toward clinical validation studies. Stakeholders must monitor evolving microbiome-friendly certification frameworks and state-level ingredient disclosure laws that will determine which formulations retain market access versus face delisting.
Market Dynamics
Dermatologist validation requirements are compressing formulation development cycles as brands race to secure clinical credibility ahead of pharmacy shelf placement decisions. Contract manufacturing access has democratized production capacity, eroding the historical moat between mass-market and clinical-grade positioning.
Growth Catalysts
- Microbiome Certification Frameworks:EU ECHA and emerging state-level ingredient disclosure mandates in the US are creating compliance-driven demand for validated pH-balanced formulations that preserve vulvar microbiome integrity.
- Urban Wellness Routine Integration:Millennial and Gen Z women in Mumbai, São Paulo, and Berlin are expanding intimate wash usage from clinical necessity into daily preventive care, opening volume expansion in pharmacy and direct-to-consumer channels.
- Prebiotic Ingredient Innovation:Lactobacillus-derived ferments and inulin-based prebiotics are replacing synthetic antimicrobials in premium formulations as regulatory scrutiny tightens on triclosan alternatives.
Market Restraints
- Clinical Validation Cost Burden:Double-blind dermatological studies required for CDSCO herbal claim substantiation in India and EU REACH safety dossiers consume 18-24 month development timelines.
- Surfactant Supply Concentration:Mild anionic and amphoteric surfactant production clusters in Germany and China expose formulators to input volatility and import compliance complexity.
- Alkaline Soap Substitution Persistence:Price-sensitive rural consumers across South Asia and Sub-Saharan Africa continue defaulting to traditional soap bars, limiting category penetration in lower-income demographics.
Strategic Opportunities
- Menopausal Segment White Space:Hormonal transition-related dryness and pH disruption in women aged 45-60 remains underserved, with dedicated formulations capturing premium positioning in US and UK pharmacy channels.
- Subscription Model Penetration:Direct-to-consumer replenishment programs bypass retail margin compression while capturing recurring revenue and consumption data for personalized formulation development.
- Ayurvedic Export Positioning:India's BIS-certified herbal standards enable differentiated market entry in Middle Eastern and Southeast Asian markets seeking halal-compliant, plant-derived alternatives.
Industry Challenges
- Formulation Chemist Talent Scarcity:Specialized expertise in vulvar microbiome-compatible surfactant systems and preservative-free stability engineering commands premium compensation and extends R&D team buildout timelines.
- Multi-Jurisdiction Labeling Complexity:Simultaneous compliance with FDA cosmetic labeling, EU INCI disclosure requirements, and India's bilingual mandate fragments packaging runs and inflates SKU management overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intimate Wash Care Products Market |
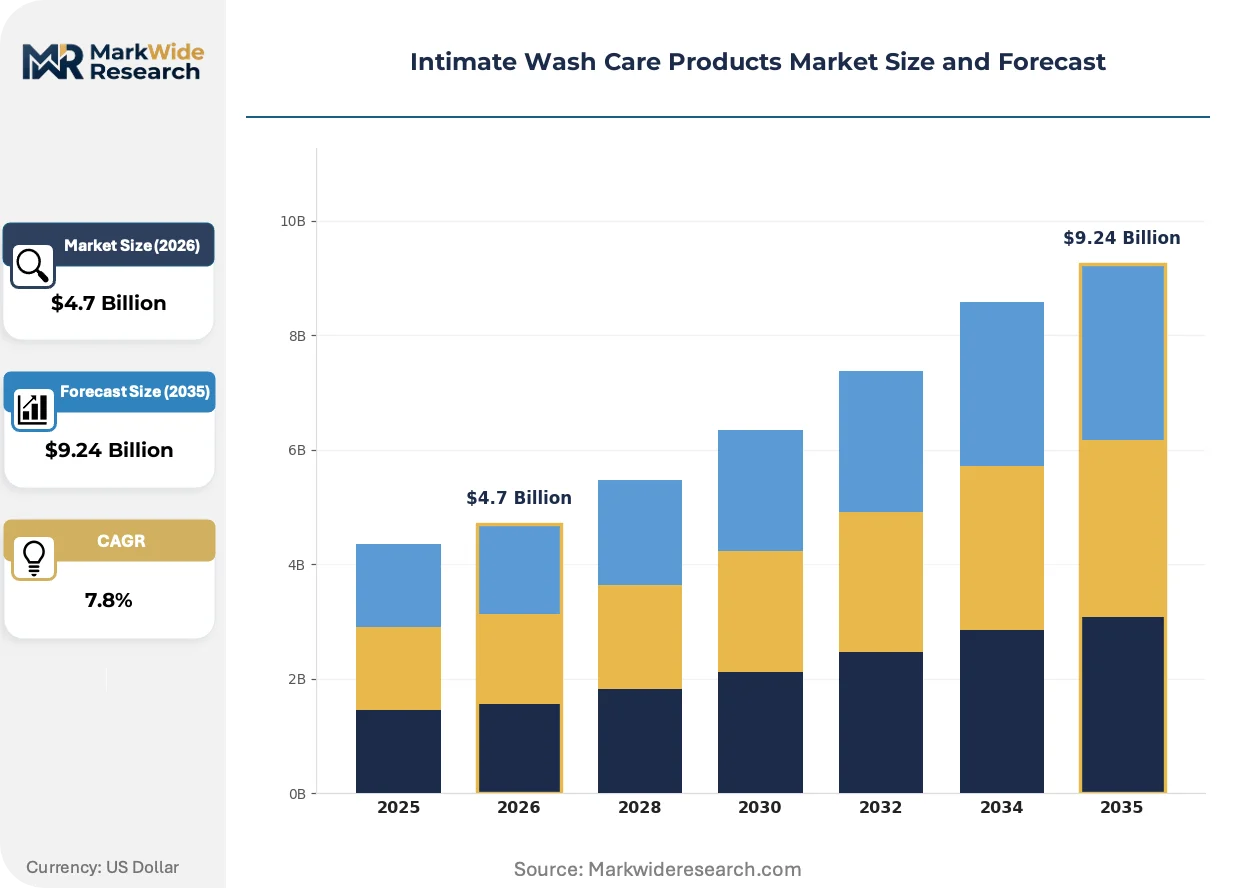
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.24 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Gel, Liquid, Wipes Ingredient Type: Natural, Synthetic, Herbal, Antibacterial Age Group: Adults, Teenagers, Seniors, Children Packaging Type: Tube, Bottle, Pump, Sachet |
| Companies Covered | Unilever Plc, Ontex Group NV, Procter & Gamble Company, Maxim Hygiene, The Himalaya Drug Company, Essity AB, Edgewell Personal Care, Organyc, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intimate Wash Care Products Market Strategic Shifts
Formulation science and distribution architecture are undergoing parallel reinvention as clinical credibility becomes the primary purchase trigger and digital channels erode traditional pharmacy gatekeeping.
Prebiotic-infused wash bases are bifurcating competitive positioning in the premium tier. Lactobacillus crispatus lysates and alpha-glucan oligosaccharides selectively nourish beneficial flora while suppressing pathogenic overgrowth. Dermatology clinics in France and South Korea are recommending these formulations at three times the rate of conventional antibacterial alternatives, compressing margins for legacy synthetic preservative systems.
EU REACH chemical safety assessments are tightening disclosure requirements for fragrance allergens and preservation systems. Manufacturers must now submit full substance dossiers for cumulative exposure scenarios across personal care portfolios. Small and mid-sized brands operating across transatlantic markets face disproportionate compliance cost burdens, accelerating consolidation around contract research organizations with established ECHA submission expertise.
Pharmacy recommendation dependency is fragmenting as telehealth platforms and social media education democratize ingredient literacy. Younger consumers in Brazil and Indonesia now research INCI lists and pH specifications before purchase, displacing traditional pharmacist authority. This behavioral shift favors brands with transparent supply chain communication and clinical study publication strategies over legacy advertising-heavy market presence.
Intimate Wash Care Products Market Segmentation
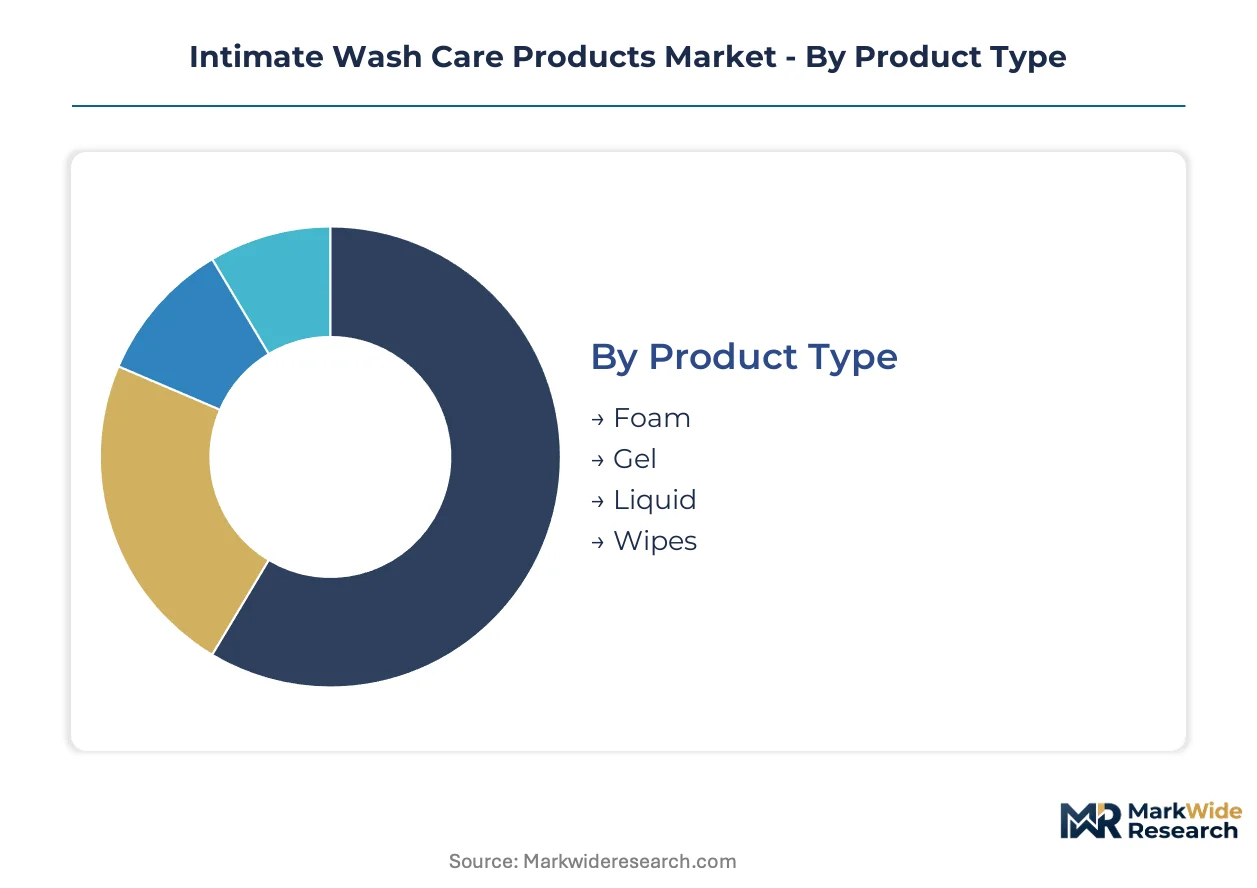
Segmentation in intimate wash care reveals how formulation science, demographic targeting, and channel economics intersect to create distinct margin architectures. Manufacturers optimize R&D allocation and packaging investment by mapping these dimensions against pharmacy, direct-to-consumer, and mass retail channel requirements.
Product Type:
Foam formats command the widest margin pools in developed-market pharmacy channels, while gel formulations attract premium positioning through clinical recommendation networks.
- Foam:Aerosol-dispensed or pump-activated formulations with low-viscosity surfactant systems that expand on contact with skin. Demand concentrates in German and US pharmacy channels where dispenser convenience drives repurchase loyalty among urban professionals with integrated wellness routines.
- Gel:Higher-viscosity aqueous bases with concentrated active delivery and extended skin contact time. Dermatology clinics in France and South Korea recommend gel formats at elevated rates for patients with microbiome sensitivity or post-procedure care requirements.
- Liquid:Traditional pourable formulations with established manufacturing infrastructure and lower per-unit packaging cost.
- Wipes:Single-use impregnated substrates targeting travel and on-the-go usage occasions with convenience premium pricing.
The dominant share belongs to Foam, while Gel is closing the gap fastest through clinical channel penetration.
Ingredient Type:
Natural and herbal positioning captures shelf placement premiums, though synthetic antibacterial variants retain volume in price-sensitive segments facing regulatory transition pressure.
- Natural:Plant-derived surfactants and preservative systems from coconut, sugarcane, or oat sources with INCI transparency. Ayurvedic ingredient sourcing from Indian suppliers with BIS certification enables differentiated entry in Middle Eastern markets seeking halal-compliant alternatives.
- Herbal:Standardized botanical extracts with documented traditional use and emerging clinical validation requirements. CDSCO herbal claim substantiation mandates in India redirect R&D investment toward double-blind studies, extending development timelines for export-focused brands.
- Synthetic:Petrochemical-derived surfactants and preservation systems with cost efficiency and batch consistency advantages.
- Antibacterial:Triclosan, chlorhexidine, or quaternary ammonium-based formulations facing EU REACH and FDA reformulation pressure.
Natural ingredients hold the revenue concentration advantage, though Herbal is expanding most quickly through regulatory-compliant export positioning.
Age Group:
Adult women's preventive care routines generate the deepest recurring revenue pools, while menopausal and teenage segments present white-space opportunities with distinct formulation requirements.
- Adults:Core demographic spanning menstrual, sexual health, and daily hygiene maintenance with established pharmacy and e-commerce purchase patterns.
- Seniors:Hormonal transition-related dryness and pH disruption in women aged 45-60 remains underserved, with dedicated formulations capturing premium positioning in US and UK pharmacy channels.
- Teenagers:First-category-entry segment requiring gentle pH-balanced introduction and educational marketing compliance.
- Children:Pediatric formulations with stringent safety dossier requirements and parental trust-building through dermatologist validation.
Adults maintain the volume base, while Seniors is gaining share fastest through menopausal-specific innovation.
Packaging Type:
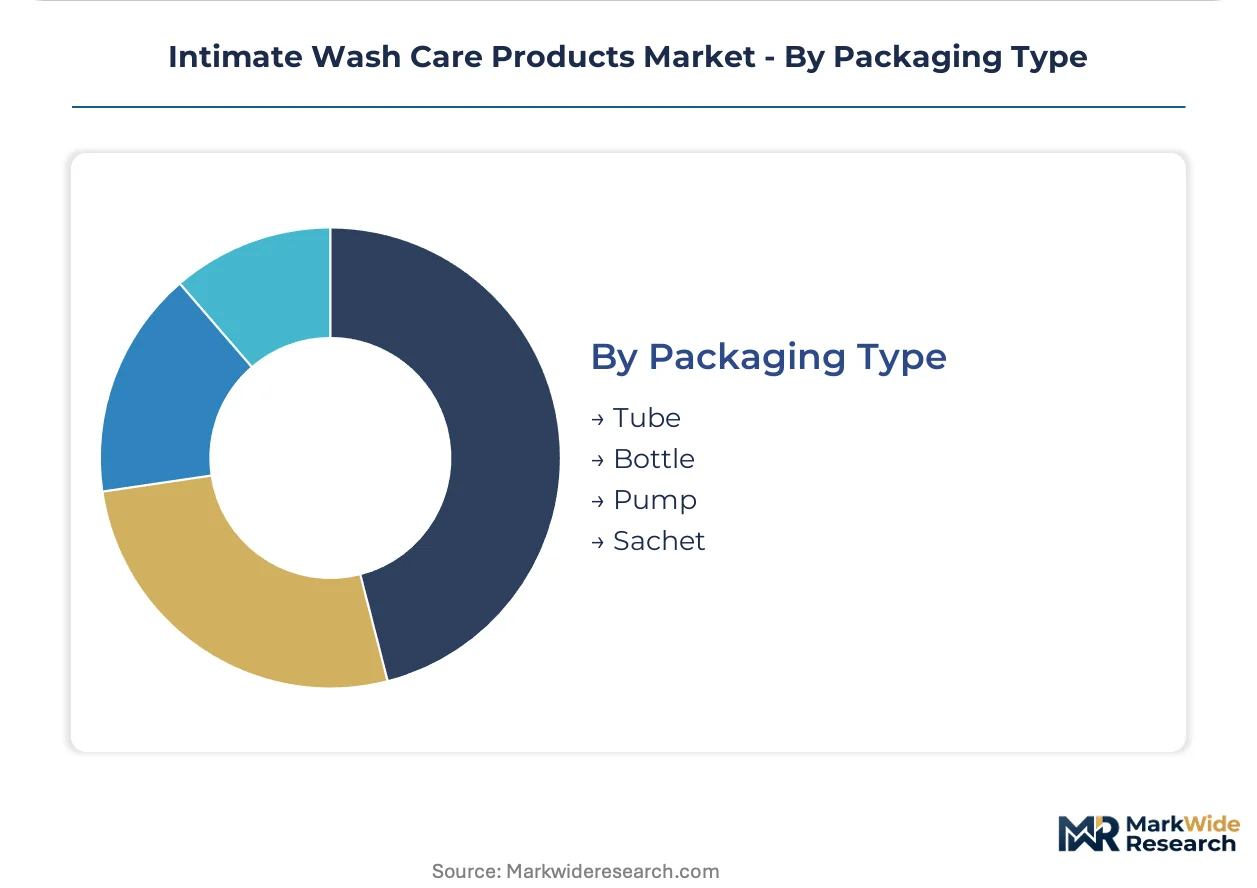
Pump and tube formats dominate margin capture through perceived hygiene and controlled dispensing, while sachet economics enable trial conversion in emerging markets.
- Pump:Airless or standard dispenser systems minimizing contamination risk and enabling precise dosage control for premium positioning.
- Tube:Collapsible aluminum or laminate structures with established filling infrastructure and portability advantages.
- Bottle:Rigid or flexible containers with flip-cap or screw-cap closure systems for economy-tier volume distribution.
- Sachet:Single-serve flexible pouches enabling low-price-point trial and rural market penetration in India and Indonesia.
Pump configurations lead in value contribution, though Sachet is climbing the fastest through emerging-market trial conversion strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Indian and Brazilian consumers exhibit acute price sensitivity, driving sachet-format penetration, while German and US buyers absorb premium pump-dispenser pricing for dermatologist-validated formulations.
United States
Subscription commerce and telehealth integration accelerate direct-to-consumer channel capture among millennial women. FDA cosmetic labeling requirements mandate full fragrance allergen disclosure, elevating compliance costs for imported formulations. Pharmacy chains in California and New York Metro dominate shelf placement decisions for pH-balanced clinical brands.
Germany
EU REACH dossier requirements for surfactant safety assessments concentrate R&D investment among mid-sized domestic formulators. ECHA disclosure mandates on cumulative chemical exposure reshape preservative system selection across personal care portfolios. Manufacturing clusters in North Rhine-Westphalia supply mild amphoteric surfactants to formulators throughout Western Europe.
India
CDSCO herbal claim substantiation mandates redirect export-focused brands toward double-blind clinical validation studies. BIS standards for Ayurvedic ingredient certification enable differentiated positioning in Middle Eastern halal-compliant markets. Maharashtra and Karnataka host contract manufacturing networks serving both domestic pharmacy chains and Gulf export channels.
Brazil
Social media ingredient literacy among Gen Z consumers displaces traditional pharmacist authority in São Paulo and Rio de Janeiro. ANVISA registration requirements for intimate care products extend import approval timelines for Asian manufacturers. Sachet economics dominate rural market penetration strategies in the Northeast and Central-West regions.
South Korea
Dermatology clinic recommendation networks drive gel-format premium positioning in Seoul and Busan. MFDS microbiome-friendly certification frameworks create compliance-driven segmentation between validated and conventional formulations. K-beauty export channels carry prebiotic-infused intimate wash products into Southeast Asian duty-free retail.
Intimate Wash Care Products Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes. Multinational consumer goods conglomerates leverage global distribution infrastructure to sustain shelf dominance in mainstream retail channels, while Ayurvedic specialists and natural-ingredient formulators capture margin premiums through differentiated positioning. The market structure consolidates around three archetypes: mass-market multinationals with pharmacy network control, regional herbal specialists with export certification advantages, and contract-manufacturing-dependent challengers accessing democratized production capacity. Dominant competitive moves include portfolio diversification into menopausal and prebiotic segments and geographic expansion through halal-compliant Ayurvedic export positioning.
Within the mass-market multinational tier, Procter & Gamble Company and Unilever Plc exemplify distribution-scale archetypes with established pharmacy channel relationships across North America and Western Europe. The Himalaya Drug Company occupies a distinct position as an India-based Ayurvedic specialist leveraging BIS-certified herbal standards for Middle Eastern and Southeast Asian market entry.
| Leading Market Players |
|---|
| Unilever Plc |
| Ontex Group NV |
| Procter & Gamble Company |
| Maxim Hygiene |
| The Himalaya Drug Company |
| Essity AB |
| Edgewell Personal Care |
| Organyc |
| Kimberly-Clark Corporation |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month validation timelines for CDSCO herbal claim substantiation compress inventory turns and concentrate pricing power among contract manufacturers with established clinical study networks. This lead-time band forces brands to pre-position formulation capacity before regulatory approval, embedding working capital costs into premium-tier positioning while economy-tier competitors absorb margin erosion from surfactant input volatility.
Pricing Analysis
Subscription replenishment programs drive lifetime value through recurring revenue capture and consumption data monetization. Three-tier pricing structure across premium, standard, and economy levels separates dermatologist-validated pump formats from pharmacy-tier tubes and rural-market sachets. Pricing pressure stems from contract manufacturing access democratization that erodes historical moats between clinical-grade and mass-market positioning. Rural consumers across South Asia exhibit acute price sensitivity, while urban professionals in Germany and the United States absorb premium positioning for microbiome-certified formulations.
Supply Chain Analysis
Germany and China anchor mild anionic and amphoteric surfactant production, with North Rhine-Westphalia clusters supplying formulators throughout Western Europe. Formulation inputs draw from coconut-derived glucosides, sugarcane-based betaines, and Lactobacillus fermentation biomass for prebiotic active delivery. Single-source vulnerability concentrates in German specialty surfactant producers exposed to EU REACH dossier compliance delays. Distribution runs through pharmacy chain procurement committees in developed markets and contract manufacturing networks serving direct-to-consumer brands in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth platform integration with intimate care recommendation engines is reconstituting pharmacist authority into algorithmic curation, creating platform-economics inflection where data-rich subscription operators capture ecosystem rents from legacy shelf-space competitors.
For Market Incumbents: Fortify pharmacy channel control through exclusive dermatologist validation partnerships that preempt contract manufacturing challengers from securing clinical credibility. Deepen backward integration into Ayurvedic ingredient sourcing with BIS-certified Indian suppliers to defend margin position against halal-compliant export competitors. Prioritize menopausal segment formulation R&D before white-space capture by natural-ingredient specialists erodes premium-tier pricing power.
For New Entrants and Emerging Players: Lead with prebiotic-infused gel formats targeting dermatology clinic recommendation networks in South Korea and France where incumbent synthetic preservative portfolios face regulatory displacement. Capture subscription-model first-mover advantage in Brazilian and Indonesian direct-to-consumer channels where social media ingredient literacy displaces traditional pharmacist gatekeeping. Anchor go-to-market strategy around transparent INCI disclosure and published clinical study repositories.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across contract manufacturing-dependent challengers accessing democratized production capacity previously controlled by multinationals. Long-term viability favors acquisition targets with established ECHA submission expertise and microbiome-friendly certification frameworks that retain market access under tightening EU REACH disclosure mandates. Monitor state-level ingredient disclosure law progression in the United States as signal for regulatory-driven consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Prebiotic Formulation Launch | Lactobacillus-derived ferments displace synthetic antimicrobials facing EU REACH reformulation pressure. |
| Subscription Model Penetration | Direct-to-consumer replenishment captures recurring revenue and consumption data for personalization. |
| Ayurvedic Export Certification | BIS-certified herbal standards enable differentiated entry in Middle Eastern halal-compliant markets. |
| Dermatology Clinic Partnership | Clinical recommendation networks in Seoul and Busan drive gel-format premium positioning. |
| Menopausal Segment Development | Hormonal transition formulations capture underserved white space in US and UK pharmacy channels. |
Study Parameters
A spread of perspectives from brand managers at multinational consumer goods conglomerates, category buyers at pharmacy chains, contract manufacturing operations heads, regulatory affairs specialists, and formulation chemists converged on the working assumptions. Primary interview intelligence combined with secondary validation from FDA cosmetic labeling guidance documents, EU ECHA substance dossier repositories, CDSCO herbal claim substantiation mandates, BIS personal care product standards, and customs trade data for surfactant imports. Bottom-up channel volume estimates triangulated against top-down category expenditure models.
Segmentation dimensions modeled span product type, ingredient sourcing, age-group targeting, and packaging format across the analysis window. CAGRs derived from regression analysis of historical pharmacy and direct-to-consumer channel trajectories, adjusted for regulatory compliance cost inflections and subscription-model adoption curves. Forecast inputs incorporated surfactant supply concentration metrics, dermatologist validation study publication rates, and microbiome certification framework adoption thresholds.
Forecasts assume regulatory continuity in EU REACH chemical safety assessments, FDA cosmetic labeling requirements, and India's CDSCO herbal claim substantiation mandates; material policy shifts would require re-modeling. Specific risk factors include fragrance allergen disclosure mandate expansion, triclosan alternative delisting acceleration, and state-level ingredient disclosure law proliferation. Recalibration cycles align with material shifts in microbiome-friendly certification adoption and contract manufacturing network capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Nail Lamps Market
Beauty & Personal Care
Bath and Shower Products Market
Beauty & Personal Care
Electric Facial Cleansing Brush Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
DIY Eyelash Extension Market
Beauty & Personal Care
China Eyelash Serum Market
Beauty & Personal Care
Middle East and Africa Beauty and Personal Care Products Market
Beauty & Personal Care
Hair Removal Creams for Private Parts Market
Beauty & Personal Care
Kids Shampoo Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Cosmetic Wax Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Asia-Pacific Beauty and Personal Care Products Market
Beauty & Personal Care
US Personal Care Products Market
Beauty & Personal Care
Cosmetics and Personal Care Stores Market
Beauty & Personal Care
Stretch Mark Removal Products Market