
 UV Nail Gel Market | 2026-2036
UV Nail Gel Market Size, Share, and Industry Trends Forecast 2026-2036
UV Nail Gel Market Analysis
CE marking under the EU Cosmetics Regulation is bifurcating competitive access between established suppliers and new entrants lacking toxicological dossiers. Gelish leverages its captive photoinitiator supply chain to sustain margin control across European distribution. OPI Products Inc. anchors North American salon channels through professional-only certification programs that lock in technician loyalty.
UV nail gel denotes a photocurable oligomer resin system, typically comprising urethane acrylates and photoinitiators such as TPO or HMPP, that polymerizes under UVA wavelengths to form a durable, high-gloss nail coating. The formulation serves both aesthetic enhancement and structural nail extension in professional and consumer settings. Color gel commands the largest revenue pool within product type segmentation, while builder gel generates superior per-unit margins due to its specialized application training requirements. Nail salons dominate the application dimension, though mobile services are expanding fastest as independent technicians seek lower overhead entry.
REACH compliance in Europe and FDA cosmetic ingredient oversight in the United States impose divergent substance restriction schedules that force dual-formulation strategies. Japan's METI maintains standalone photoinitiator concentration limits that exceed EU thresholds, creating additional certification burdens for Asian market entry. Stakeholders must track regulatory divergence between photoinitiator ban timelines in Brussels and Washington to avoid stranded inventory or reformulation costs.
Market Dynamics
Photoinitiator safety standards are fragmenting formulation chemistry across major economies, forcing manufacturers to maintain parallel product lines and certification dossiers for identical base chemistries.
Growth Catalysts
- Builder gel training standardization:Nail extension protocols in China's tier-one cities are creating certified technician pools that lock in recurring gel purchases from approved suppliers.
- METI-aligned photoinitiator thresholds:Japan's concentration limits above EU baselines are accelerating domestic R&D into alternative initiator compounds with comparable cure speeds.
- Mobile service infrastructure:Independent technicians in South Korea are deploying portable UV-LED curing systems that expand addressable demand beyond fixed salon locations.
Market Restraints
- Photoinitiator supply concentration:TPO and HMPP production clusters in Germany and China expose formulators to input volatility when environmental inspections interrupt chemical plant operations.
- Dual-formulation cost burden:REACH substance restrictions and FDA cosmetic ingredient schedules diverge on ban timelines, forcing inventory segmentation that raises working capital requirements.
- UV-LED substitution pressure:Narrow-wavelength curing systems are displacing traditional UVA lamps in premium segments, stranding equipment investments in legacy bulb supply chains.
Strategic Opportunities
- Underpenetrated tier-two China:Salon chain expansion into Chengdu and Xi'an is standardizing builder gel protocols where technician certification density remains below Shanghai or Beijing levels.
- At-home curing device convergence:Integration of smartphone-controlled exposure timers with compact UV-LED arrays is opening consumer segments previously served only by professional channels.
- EU Green Deal chemical substitution incentives:Biobased urethane acrylate development programs are receiving accelerated ECHA registration pathways for formulations with renewable carbon content above 30 percent.
Industry Challenges
- Photoinitiator toxicological dossier assembly:CE marking under EU Cosmetics Regulation requires substance-level safety data that smaller formulators lack resources to generate independently.
- Cross-regulatory certification timeline compression:Parallel METI, REACH, and FDA submission windows demand specialized regulatory affairs capacity that mid-tier suppliers struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Nail Gel Market |
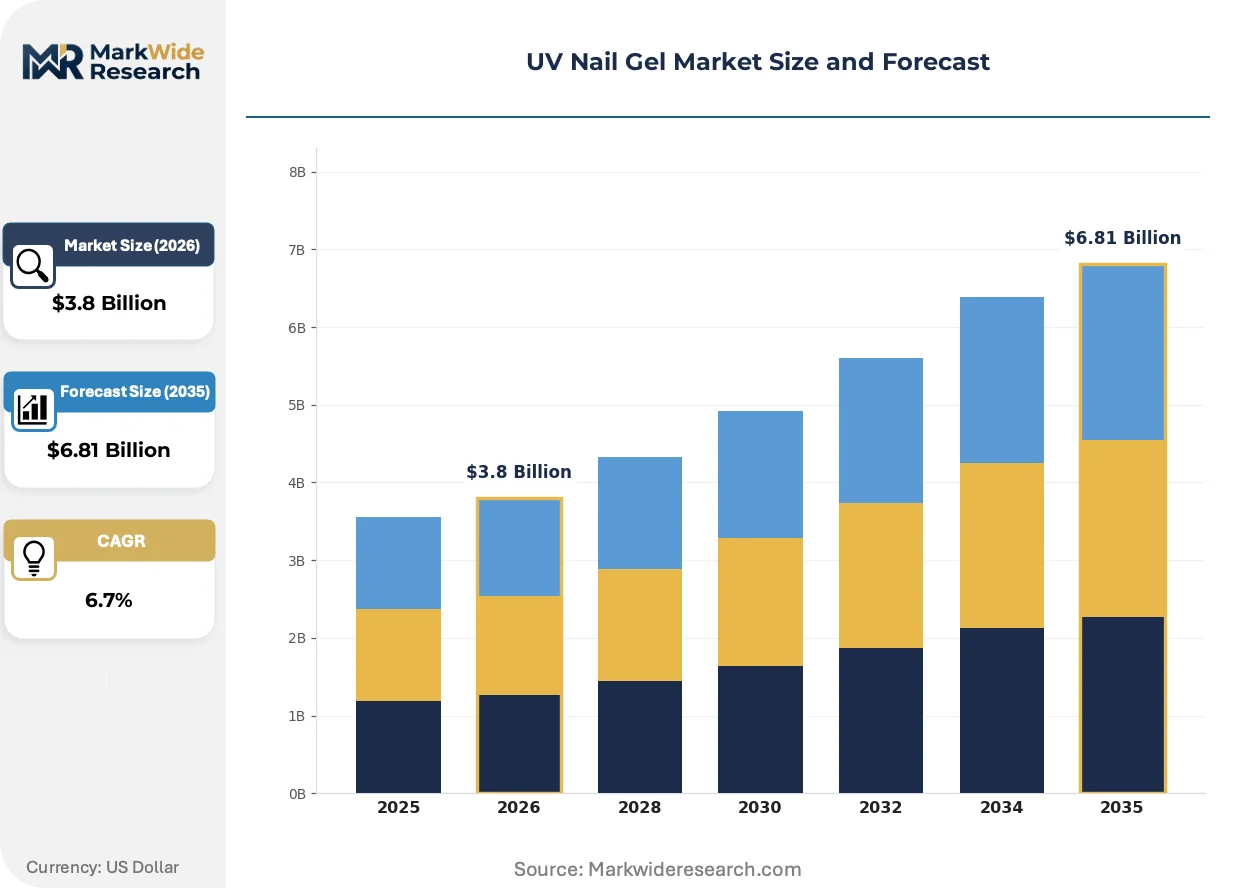
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Coat, Top Coat, Color Gel, Builder Gel Application: Nail Salons, At-Home Use, Mobile Services, Spa Treatments Form: Gel, Bottle, Pod, Pen Customer Type: Professional Technicians, DIY Enthusiasts, Beauty Influencers, Retail Consumers |
| Companies Covered | Gelish, Christian Dior, OPI Products Inc., The GelBottle Inc., Kiara Sky, Creative Nail Design Inc., Sally Hansen, CND, Essie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Nail Gel Market Emerging Trajectories
Formulation chemistry, curing hardware, and service delivery models are diverging simultaneously as regulatory pressure and technician mobility reshape how UV nail gel reaches end users.
Hydroxyacetophenone-derived photoinitiator blends are replacing legacy benzophenone systems in professional-grade color gels to meet tightening dermal exposure thresholds. Korean salon chains are adopting these reformulated products fastest, driven by consumer litigation awareness around photoallergic reactions. The technology is bifurcating supply relationships between initiator-captive multinationals and independent formulators dependent on merchant chemical markets.
REACH substance restriction schedules are advancing faster than FDA cosmetic ingredient reviews, creating a regulatory lag that advantages European early movers with compliant dossiers already filed. Manufacturers serving both markets are prioritizing Brussels-aligned formulations for new product development while maintaining legacy lines for US distribution. Color gel portfolios face the steepest reformulation burden given their higher photoinitiator loadings per unit volume.
Independent technician collectives are consolidating purchasing power through cooperative procurement platforms that bypass traditional distributor markups. These aggregators in South Korea and Japan are extracting volume discounts previously reserved for national salon chains. The channel shift is most visible in builder gel categories where application complexity previously justified hands-on distributor support.
UV Nail Gel Market Segmentation
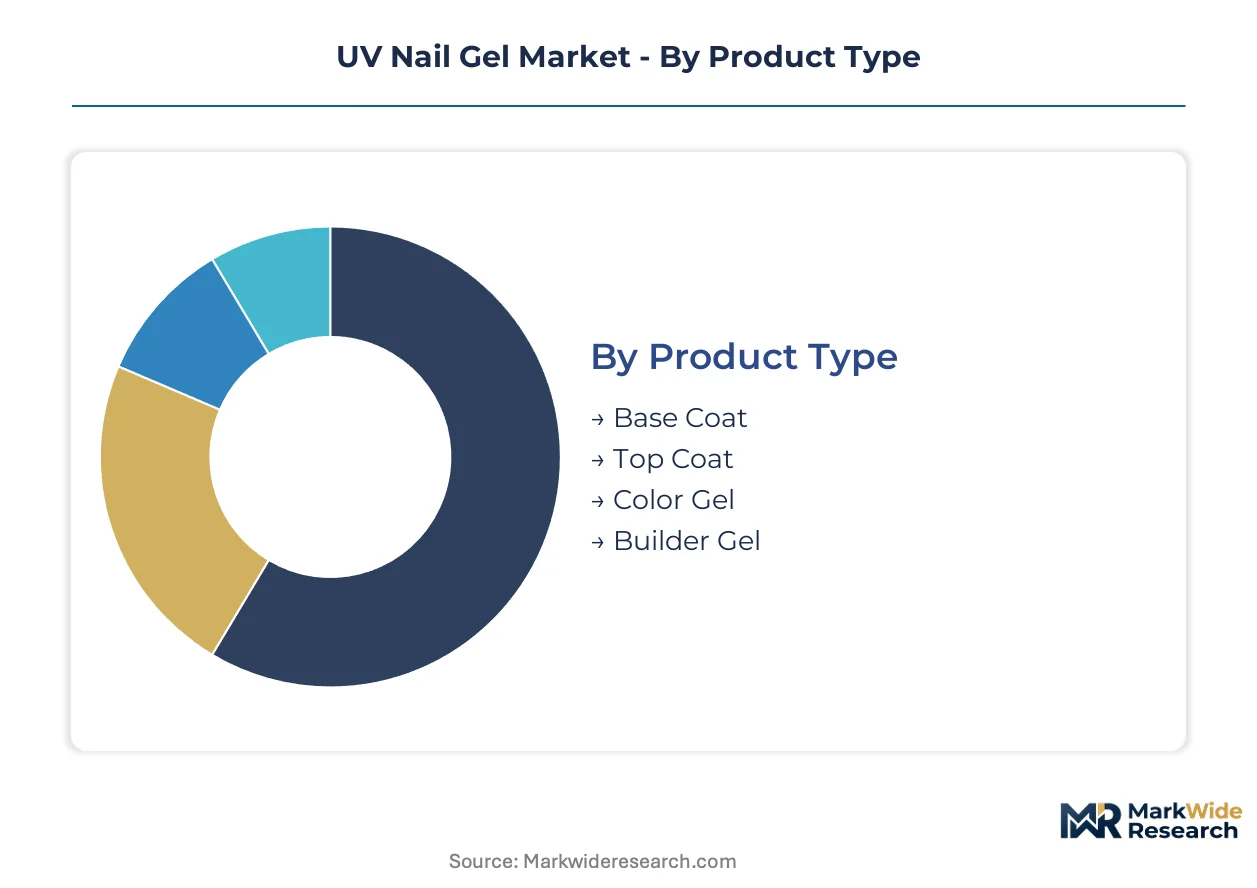
UV nail gel segmentation reveals how formulation complexity and service delivery economics split margin pools across distinct customer workflows. Each dimension carries divergent regulatory burdens and supply chain requirements that reshape competitive positioning.
Product Type:
Builder gel commands the steepest per-unit margins due to specialized technician certification requirements, while color gel generates volume through repeat purchase frequency.
- Color Gel:Pigmented urethane acrylate formulations carry the highest photoinitiator loadings per volume, driving reformulation costs as REACH substance restrictions advance faster than FDA reviews. Demand clusters in China's tier-one cities where salon chains standardize on matching systems for brand consistency.
- Builder Gel:Structural extension gels require thicker viscosity oligomer blends and extended curing protocols that lock technicians into approved supplier ecosystems. South Korean training academies are expanding certification programs that tie product purchases to curriculum completion.
- Base Coat:Adhesion-promoting primers with lower initiator concentrations face less regulatory pressure than pigmented alternatives.
- Top Coat:High-gloss sealants with UV stabilizers compete on durability metrics and scratch resistance benchmarks.
The dominant share belongs to Color Gel, while Builder Gel is closing the gap fastest.
Application:
Channel economics diverge sharply between fixed-location infrastructure and asset-light service models.
- Nail Salons:Professional studios in Seoul and Tokyo anchor bulk purchasing agreements with distributors, leveraging standardized builder gel protocols to reduce per-service material waste. METI-aligned photoinitiator thresholds in Japan are accelerating domestic R&D into alternative initiator compounds.
- Mobile Services:Independent technicians deploy portable UV-LED curing systems that bypass salon overhead, expanding addressable demand into residential and corporate settings across South Korea's dense urban corridors.
- At-Home Use:Consumer-directed kits face stricter labeling requirements under EU Cosmetics Regulation CE marking protocols.
- Spa Treatments:Wellness-integrated nail services command premium pricing through bundled aesthetic protocols.
Nail Salons retain the largest revenue footprint, though Mobile Services are expanding most quickly.
Form:
Packaging format selection tracks application precision requirements and inventory velocity constraints.
- Bottle:Standard pump-dispensed containers dominate professional backbars in Shanghai and Beijing where volume scaling reduces unit procurement costs.
- Pod:Single-use sealed portions eliminate cross-contamination risks in Japanese spas operating under stringent hygiene protocols.
- Gel:Bulk reservoir formats serve high-throughput salon chains with automated dispensing equipment.
- Pen:Brush-integrated applicators target detail work for nail art segments requiring precision control.
Bottle formats lead professional channels, while Pod configurations are gaining traction fastest in premium hygiene-sensitive settings.
Customer Type:
Purchasing behavior splits between credential-dependent professional segments and discretionary consumer tiers.
- Professional Technicians:Licensed practitioners in Chengdu and Xi'an drive builder gel standardization as salon chains expand into underpenetrated tier-two Chinese markets with certification density below coastal benchmarks.
- DIY Enthusiasts:At-home curing device convergence—smartphone-controlled exposure timers paired with compact UV-LED arrays—is opening segments previously served only through professional channels in European markets.
- Beauty Influencers:Content creators drive trial conversion through tutorial-linked affiliate procurement platforms.
- Retail Consumers:Mass-market purchasers respond to seasonal color trends and promotional bundling strategies.
Professional Technicians anchor the revenue base, while DIY Enthusiasts are climbing the fastest as at-home hardware improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CE marking under the EU Cosmetics Regulation is redirecting formulation investment toward Brussels-aligned dossiers, while METI photoinitiator thresholds in Japan and FDA cosmetic ingredient schedules in the United States force parallel compliance tracks. Divergent regulatory timelines are fragmenting product development calendars across major economies.
United States
Professional salon chains in Los Angeles and New York Metro anchor bulk purchasing agreements for builder gel systems. FDA cosmetic ingredient oversight maintains distinct substance restriction schedules from REACH, forcing dual-formulation inventory segmentation. Miami and Dallas-Fort Worth clusters are expanding mobile service infrastructure as independent technicians deploy portable UV-LED curing arrays.
China
Tier-one cities Shanghai and Beijing standardize builder gel protocols through certified technician pools that lock in recurring gel purchases. NMPA cosmetic registration requirements impose parallel safety documentation burdens distinct from export-market REACH dossiers. Chengdu and Xi'an in the Sichuan-Chongqing corridor represent underpenetrated expansion targets where salon chain density trails coastal benchmarks.
South Korea
Seoul Capital Area salon chains are accelerating adoption of hydroxyacetophenone-derived photoinitiator blends amid consumer litigation awareness around photoallergic reactions. MFDS cosmetic safety standards align closely with METI thresholds, streamlining cross-border formulation strategies. Busan-Ulsan manufacturing clusters supply photoinitiator intermediates to domestic formulators seeking captive supply security.
Japan
Tokyo and Osaka professional studios anchor premium color gel demand as METI maintains standalone photoinitiator concentration limits exceeding EU baselines. Domestic R&D into alternative initiator compounds with comparable cure speeds is accelerating in Kansai chemical corridors. PMDA cosmetic consultation pathways are compressing certification timelines for reformulated professional-grade products.
Germany
Bavaria and North Rhine-Westphalia chemical production clusters concentrate TPO and HMPP photoinitiator supply, exposing formulators to input volatility during environmental inspection cycles. REACH substance restriction schedules are advancing faster than FDA reviews, advantaging European early movers with compliant dossiers. Berlin-Brandenburg distribution hubs are consolidating cross-border logistics for CE-marked gel exports.
UV Nail Gel Market Vendor Landscape
Player mix skews toward multinational beauty conglomerates with captive photoinitiator supply chains and specialized professional-only certification programs. Market structure concentrates around three tiers: initiator-captive multinationals, distributor-dependent mid-tier formulators, and mobile-service-aligned niche suppliers. Strategic archetypes include supply-integrated chemistry specialists, salon-channel loyalty builders, and hardware-convergence enablers. Dominant competitive moves center on technician certification lock-in and at-home curing device integration.
Among initiator-captive multinationals, Gelish and OPI Products Inc. exemplify supply-integrated positioning through controlled photoinitiator access and professional-only distribution channels. The GelBottle Inc. occupies a specialist tier focused on builder gel certification ecosystems. These three entities represent divergent strategic bets on channel control versus formulation complexity versus technician education infrastructure.
| Leading Market Players |
|---|
| Gelish |
| Christian Dior |
| OPI Products Inc. |
| The GelBottle Inc. |
| Kiara Sky |
| Creative Nail Design Inc. |
| Sally Hansen |
| CND |
| Essie |
| Others |
Supply Flow & Price Mechanics
Hydroxyacetophenone-derived photoinitiator substitution for legacy benzophenone systems is redrawing supply geography toward Korean and Japanese chemical corridors while compressing formulation economics for European REACH-compliant tiers.
Pricing Analysis
Certification level (REACH/CE-grade versus FDA-grade) creates the primary spread between premium professional lines and mass-market consumer kits. Three-tier pricing structure across premium, standard, and economy levels tracks photoinitiator loading density and technician certification bundling. Price differentiation stems from toxicological dossier completeness and captive supply chain control. Professional technicians show lowest price sensitivity due to lock-in effects from training academy supplier partnerships, while DIY enthusiasts drive cost compression through cooperative procurement platforms.
Supply Chain Analysis
Strategic stockpiling of TPO and HMPP photoinitiators dominates inventory strategy among German and Chinese formulators facing environmental inspection volatility. Raw material dependencies rest on urethane acrylate oligomers from Bavaria, photoinitiator intermediates from Busan-Ulsan clusters, and specialty pigments from Guangdong chemical parks. Single-source vulnerability concentrates in German TPO production exposed to REACH substance restriction acceleration. Distribution runs through Seoul-Tokyo-Berlin distributor hubs serving certified salon chains with approved supplier status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Builder gel standardization in China's tier-two cities signals early-cycle expansion with technician certification density trailing coastal benchmarks by substantial margins.
For Market Incumbents: Compound technician certification lock-in through exclusive academy partnerships in Chengdu and Xi'an before salon chain density catches coastal levels. Deepen backward integration into hydroxyacetophenone-derived photoinitiator production to offset REACH substance restriction cost compression. Prioritize METI-aligned formulation dossiers to defend Japanese premium positioning against domestic R&D accelerants.
For New Entrants and Emerging Players: Lead with mobile service infrastructure partnerships targeting South Korea's independent technician collectives bypassing traditional distributor markups. White-space concentrates in at-home curing device convergence where smartphone-controlled UV-LED arrays open consumer segments previously served only through professional channels. Go-to-market angle: cooperative procurement platforms extracting volume discounts through aggregated purchasing power.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed distributor-dependent mid-tier formulators lacking captive photoinitiator supply chains. Long-term viability favors initiator-captive multinationals with Brussels-aligned dossiers filed before regulatory lag advantages dissipate. Signal to watch: compression in cross-regulatory certification timeline windows as METI, REACH, and FDA submission demands converge.
| Strategic Initiative | Industry Significance |
|---|---|
| Photoinitiator Supply Integration | Captive TPO/HMPP production insulates margin control from German environmental inspection cycles. |
| Technician Certification Ecosystem | Exclusive academy partnerships in tier-two China lock recurring gel purchases to curriculum completion. |
| Mobile Service Infrastructure | Portable UV-LED curing arrays expand addressable demand beyond fixed Seoul salon locations. |
| REACH-Aligned Formulation Pipeline | Brussels-first dossier strategy exploits regulatory lag before FDA substance reviews accelerate. |
| At-Home Hardware Convergence | Smartphone-controlled exposure timers open European consumer segments previously professional-only. |
Methodological Framework
Desk research of customs trade flows, ECHA registration databases, and MFDS cosmetic safety filings preceded structured interviews with nail salon chain procurement directors, photoinitiator plant managers in Bavaria and Busan-Ulsan, independent technician collective organizers, and distributor channel partners across Seoul-Tokyo-Berlin corridors. Bottom-up technician certification density modeling triangulated against top-down gel volume flows through Shanghai and Beijing customs ports.
Variance decomposition across product type, application channel, and regional regulatory cluster dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from technician pool expansion rates in tier-two Chinese cities, photoinitiator substitution velocity in Korean salon chains, and mobile service penetration curves in dense urban corridors. Industry-specific inputs included REACH substance restriction timeline probability weights and METI threshold compliance cost curves.
Underlying assumptions cover sustained salon chain standardization in China, photoinitiator supply continuity through German environmental cycles, and UV-LED hardware cost decline curves, with deviation risk concentrated in cross-regulatory certification timeline compression. Revision becomes warranted when METI-aligned photoinitiator thresholds diverge further from EU baselines or when cooperative procurement platforms capture majority share in builder gel categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Brazil Cosmetics Market
Beauty & Personal Care
Global Probiotic Cosmetic Products Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Luxury Personal Care and Cosmetics Market
Beauty & Personal Care
US Skincare Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Shower Gel Market
Beauty & Personal Care
Malaysia Aromatherapy Products Market
Beauty & Personal Care
Magnetic Eyelashes Market
Beauty & Personal Care
Bangladesh Shampoo Market
Beauty & Personal Care
Hair Conditioner Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Luxury Hair Care Market
Beauty & Personal Care
Switzerland Haircare Market
Beauty & Personal Care
Australia Beauty and Personal Care Products Market