
 Banking ERP Software Market | 2026-2036
Banking ERP Software Market Size, Share, and Industry Trends Forecast 2026-2036
Banking ERP Software Market Analysis
The banking ERP software market is restructuring around a sharp divergence between premium cloud-native suites and commodity on-premises legacy systems. SAP S/4HANA leverages deep vertical integration with banking-specific modules to dominate Tier 1 institution deployments. Oracle ERP Cloud anchors its position through extensive regulatory compliance pre-configuration across multiple jurisdictions. Temenos differentiates via specialization in emerging-market banking architectures with leaner implementation footprints.
Banking ERP software comprises integrated enterprise resource planning systems architected for financial institutions, typically featuring real-time general ledger consolidation, multi-entity accounting engines, and Basel III capital adequacy calculation modules. These platforms centralize transaction processing, regulatory reporting, and risk-weighted asset computation across branch networks and digital channels. Cloud-based deployment is outpacing on-premises installations as margin pools shift toward subscription revenue models with embedded compliance updates. Core banking functionality retains the largest addressable base, while risk management modules capture premium pricing from stress-testing automation requirements.
The European Banking Authority, the US Federal Reserve's SR 11-7 guidance on model risk management, and India's RBI cybersecurity framework collectively elevate compliance management modules from optional add-ons to mandatory procurement criteria. Vendors must now pre-certify systems against jurisdiction-specific data residency and algorithmic auditability standards before market access. Stakeholders should monitor how central bank digital currency integration requirements reshape core banking architecture roadmaps.
Market Dynamics
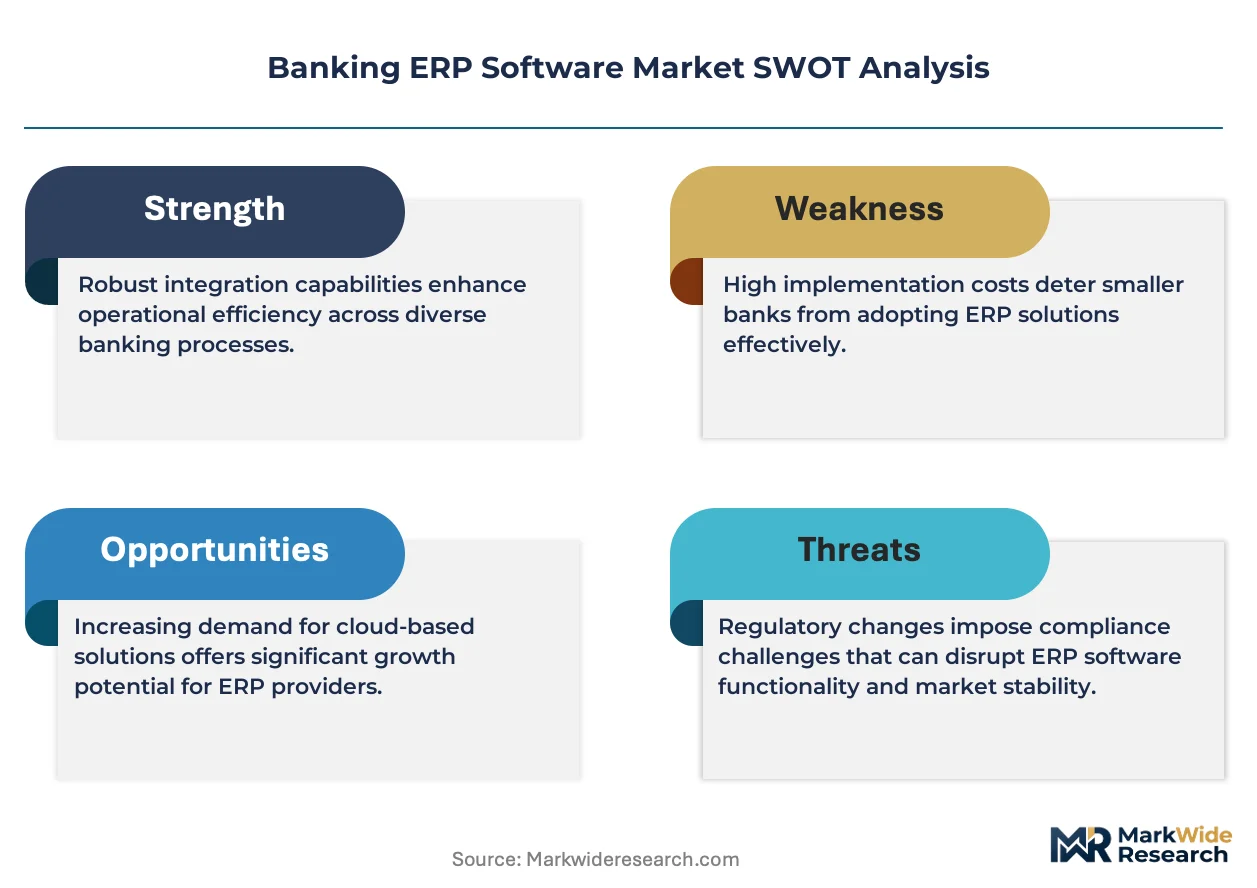
Cloud migration mandates from the EU AI Act and DORA framework are forcing Tier 1 and regional banks to replace legacy core systems with API-first architectures that embed real-time compliance updates.
Growth Catalysts
- EU AI Act operational risk requirements:Banks in Germany and France must deploy algorithmic auditability modules by 2026, accelerating replacement of black-box legacy systems.
- Real-time payment infrastructure:India's UPI 2.0 and FedNow in the United States demand sub-second ledger consolidation that only cloud-native ERP cores can deliver.
- Basel III endgame capital rules:Stress-testing automation requirements from the US Federal Reserve and European Banking Authority expand addressable market for risk-weighted asset calculation engines.
Market Restraints
- Implementation cost concentration:Core banking ERP deployments require 18-36 month timelines with specialized system integrators, freezing mid-tier bank budgets.
- Data residency fragmentation:Divergent national cloud sovereignty laws in Germany, India, and Saudi Arabia force vendors to maintain jurisdiction-specific instances.
- Legacy COBOL dependency:Critical transaction processing modules in US and European institutions remain tethered to retiring developer talent pools.
Strategic Opportunities
- Central bank digital currency integration:The European Central Bank's digital euro pilot and India's e-rupee roadmap create demand for programmable ledger architectures.
- Embedded finance convergence:Non-bank platforms in the United States and United Kingdom require white-label core banking ERP stacks for lending-as-a-service deployment.
- Regulatory sandbox participation:Singapore's MAS and the UK's FCA frameworks allow vendors to pre-certify compliance modules before full market rollout.
Industry Challenges
- Cloud security certification timelines:SOC 2 Type II and ISO 27001 audits for banking ERP platforms extend sales cycles by 9-14 months.
- API standardization gaps:Fragmented open banking protocols across US, EU, and Indian jurisdictions force redundant integration engineering.
- Domain expertise scarcity:Implementation teams require simultaneous fluency in Basel regulatory frameworks and Kubernetes container orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking ERP Software Market |
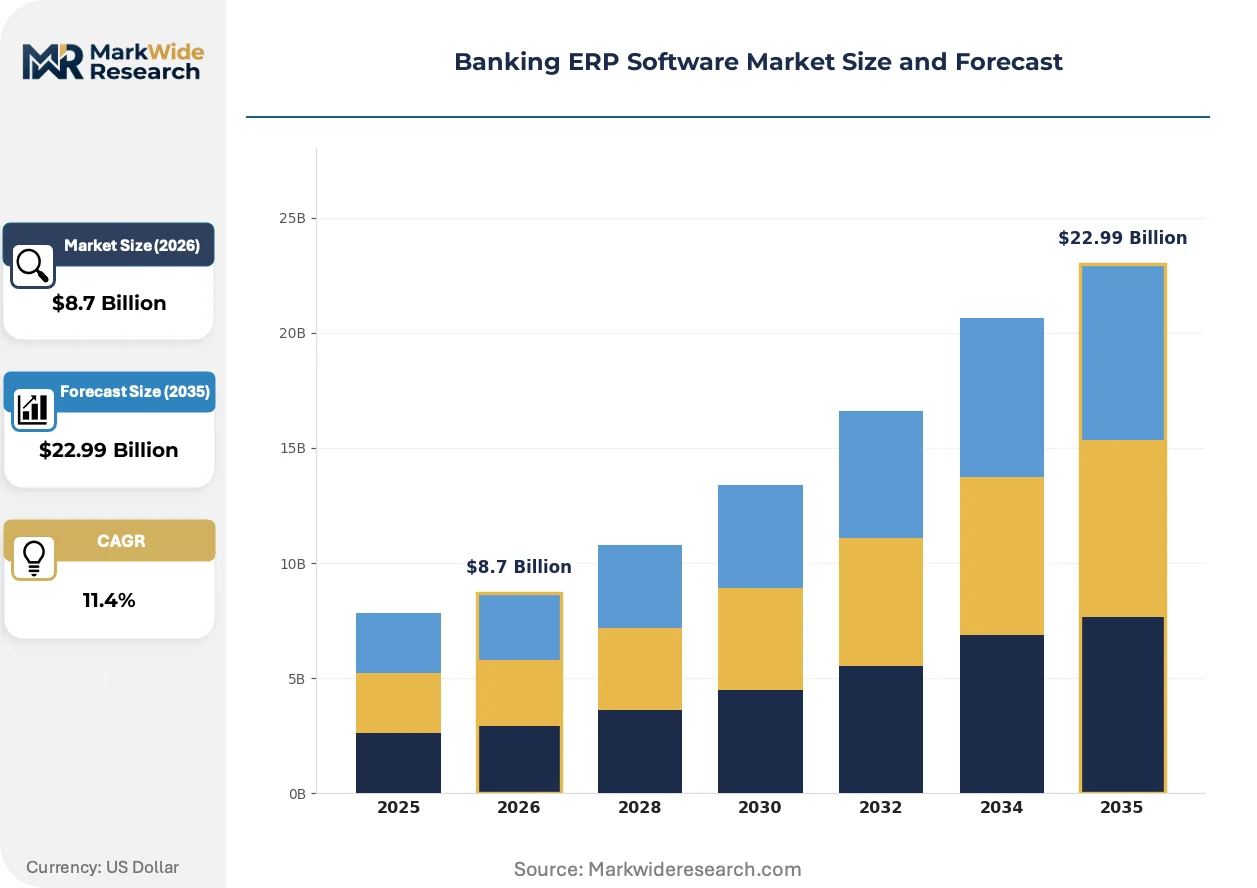
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Banking, Loan Management, Risk Management, Compliance Management Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Commercial Banks, Investment Banks, Credit Unions, Microfinance Institutions Feature: Automated Reporting, Data Analytics, Customer Relationship Management, Fraud Detection |
| Companies Covered | Rise with SAP, ServiceNow ITSM, SAP S/4HANA, Microsoft Dynamics 365 Finance, Oracle NetSuite ERP, Oracle ERP Cloud, FinancialForce, Temenos, Workday, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking ERP Software Market Emerging Trajectories
Distributed ledger interoperability and AI-powered regulatory reporting are compressing implementation timelines while expanding the functional perimeter of core banking platforms beyond traditional general ledger consolidation.
Embedded machine learning for real-time fraud detection is absorbing transaction monitoring workloads previously handled by standalone AML systems. Tier 1 institutions in Germany and the United States are deploying these modules at scale, with regional banks in India following within 18-24 month lag cycles. The technology is absorbing point-solution budgets into consolidated ERP procurement decisions.
The EU AI Act's algorithmic impact assessment requirements are mandating explainability layers for all automated credit decisioning. Vendors must now pre-certify model documentation standards before deployment in French and Dutch institutions. Risk management modules capture premium pricing as banks prioritize audit-ready stress-testing pipelines over generic analytics tools.
Subscription-based deployment models are displacing perpetual license structures across mid-tier banking segments. German Sparkassen and US community banks now demand consumption-aligned pricing with embedded regulatory update subscriptions. This shift is most visible in cloud-native vendor selection criteria, where total cost of ownership calculations now dominate feature-comparison matrices.
Banking ERP Software Market Segmentation
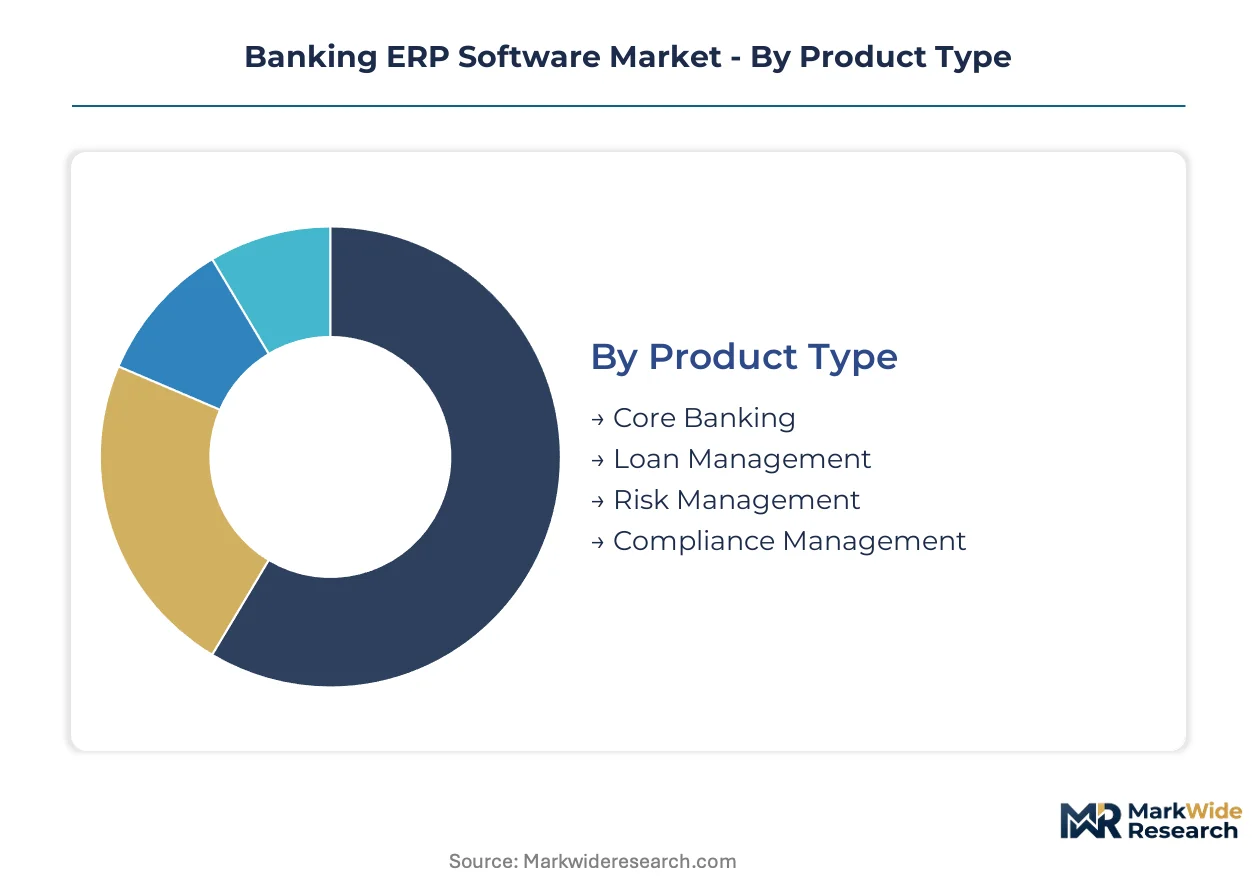
Banking ERP procurement decisions follow distinct upgrade cycles across product categories, deployment architectures, and institutional user types. Segment-level dynamics reveal where compliance mandates and infrastructure modernization budgets concentrate replacement demand.
Product Type:
Replacement cycles diverge sharply between mandatory regulatory modules and discretionary operational tools, with Basel III deadlines compressing timelines for risk and compliance functions.
- Core Banking:Real-time general ledger consolidation engines process transaction streams across branch networks and digital channels. German Sparkassen and US regional banks anchor volume as legacy COBOL systems approach end-of-life, driven by FedNow and instant payment infrastructure requirements.
- Risk Management:Stress-testing automation modules calculate risk-weighted assets and capital adequacy ratios under Basel III endgame rules. Demand concentrates among Tier 1 institutions in France and the United States, compelled by SR 11-7 model risk management guidance and EBA technical standards.
- Loan Management:End-to-end credit origination and servicing platforms with embedded scoring engines.
- Compliance Management:Regulatory reporting engines with jurisdiction-specific templates for RBI, ECB, and Federal Reserve filings.
Volume placements concentrate in Core Banking; the faster expansion belongs to Risk Management.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises installations from consumption-aligned cloud subscriptions, with hybrid architectures capturing mid-tier banks seeking staged migration paths.
- Cloud-Based:API-first architectures with embedded compliance updates and auto-scaling infrastructure. Indian private banks and UK challenger banks dominate adoption, responding to RBI cybersecurity framework mandates and FCA operational resilience requirements.
- SaaS:Multi-tenant platforms with pre-configured regulatory templates and subscription pricing. US community banks and German cooperative institutions drive volume, prioritizing total cost of ownership over customization depth.
- On-Premises:Single-tenant installations with full data sovereignty control for sensitive jurisdictions.
- Hybrid:Split deployments retaining core transaction processing on-premises while migrating analytics to cloud tiers.
Cloud-Based deployments capture the largest addressable base; SaaS models are climbing the fastest as margin-constrained institutions prioritize operating expenditure structures.
End User:
Customer type determines functional complexity requirements and procurement authority structures, with commercial banks commanding the deepest integration scopes.
- Commercial Banks:Full-suite ERP deployments spanning retail, corporate, and treasury functions with multi-entity consolidation. Tier 1 institutions in Germany, the United States, and India anchor demand, modernizing legacy infrastructure under DORA and EU AI Act operational risk mandates.
- Credit Unions:Leaner implementations emphasizing member-facing digital channels and simplified regulatory reporting. US state-chartered credit unions drive volume, constrained by limited IT budgets and volunteer board governance structures.
- Investment Banks:Specialized modules for trading book valuation, counterparty credit risk, and securities financing.
- Microfinance Institutions:Lightweight core banking with mobile-first origination and group lending workflows.
Commercial Banks absorb the majority of implementation spend; Credit Unions represent the steepest expansion trajectory as cloud-native vendors target underserved community segments.
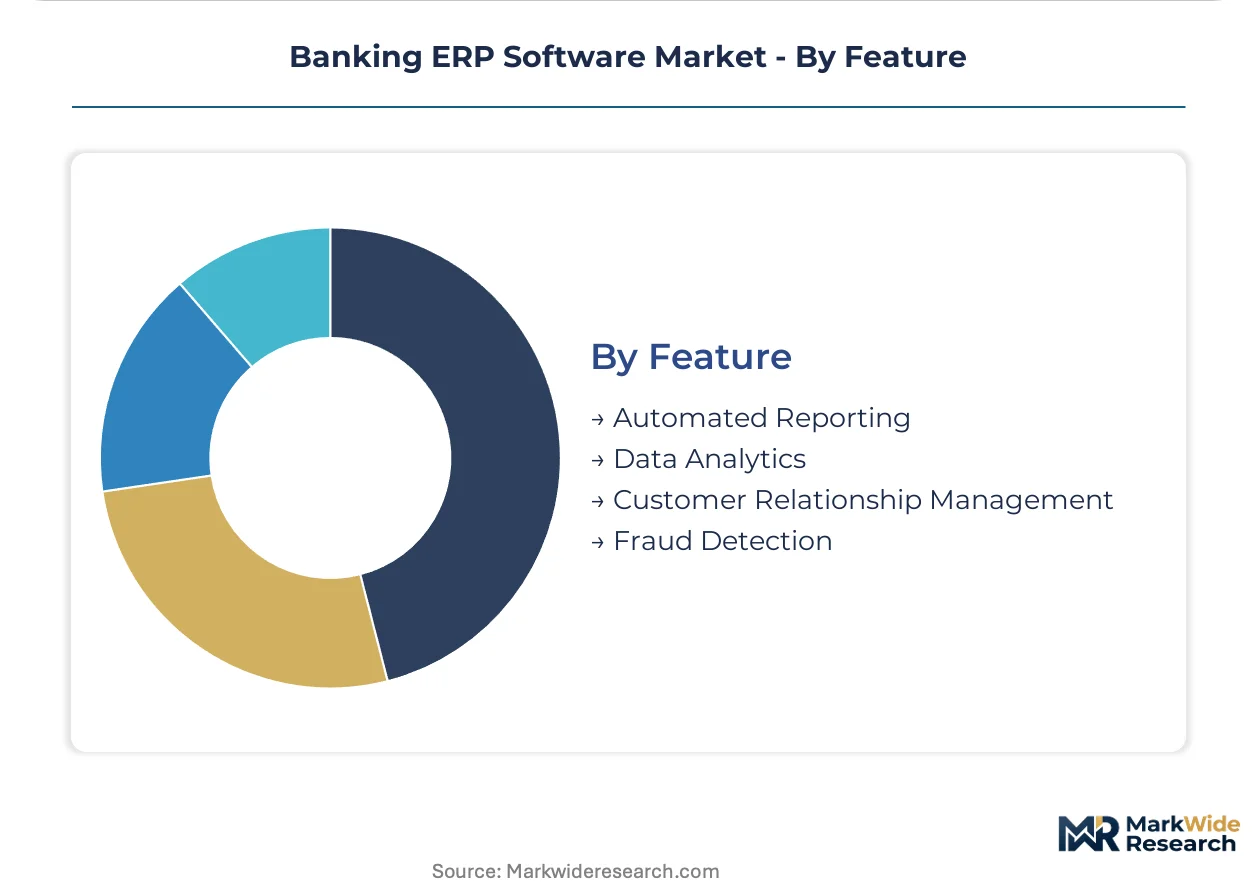
Feature:
Application maturity separates table-stakes functionality from premium-priced modules, with AI-powered features commanding implementation priority in current procurement cycles.
- Fraud Detection:Embedded machine learning models analyzing transaction patterns in real time for AML and sanctions screening. German and US Tier 1 institutions deploy at scale, absorbing budgets previously allocated to standalone point solutions.
- Data Analytics:Predictive engines for customer segmentation, credit scoring, and portfolio optimization. Indian banks and US regional institutions concentrate demand, leveraging alternative data sources for financial inclusion lending.
- Automated Reporting:Regulatory filing generators with jurisdiction-specific templates and audit trails.
- Customer Relationship Management:Integrated sales force automation and service desk modules for relationship banking.
Automated Reporting retains the broadest installed base; Fraud Detection features are gaining share fastest as algorithmic auditability requirements elevate procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's financial district anchors European banking ERP procurement as German institutions accelerate cloud migration under DORA deadlines. The United States and India follow as FedNow and UPI 2.0 infrastructure demands reshape core banking architectures.
United States
New York-based money center banks and San Francisco fintechs drive demand for real-time ledger consolidation. The Federal Reserve's SR 11-7 model risk management guidance compels stress-testing automation investments. Dallas-Fort Worth regional banks now prioritize SaaS deployment models to compress implementation timelines.
Germany
Sparkassen and cooperative banking networks in Bavaria and North Rhine-Westphalia modernize legacy COBOL cores. The EU AI Act's algorithmic auditability requirements mandate explainable credit decisioning modules by 2026. Frankfurt's concentration of ECB-supervised institutions creates clustered demand for Basel III endgame compliance engines.
India
Mumbai's private banks and Bengaluru's digital challengers deploy API-first architectures for UPI 2.0 integration. The RBI cybersecurity framework mandates cloud data residency controls that favor domestic vendor partnerships. Hyderabad's technology corridor hosts implementation centers serving Southeast Asian expansion.
United Kingdom
London's Tier 1 institutions and Manchester's building societies pursue hybrid cloud strategies under FCA operational resilience rules. The FCA's regulatory sandbox framework allows pre-certification of compliance modules. Edinburgh's banking cluster concentrates procurement for Scottish-licensed institutions.
France
Paris-based global systemically important banks invest in risk-weighted asset calculation engines. The CNIL's GDPR enforcement and EU AI Act implementation timelines compress vendor selection cycles. Lyon and Toulouse regional banks adopt subscription pricing models to preserve capital ratios.
Banking ERP Software Market Vendor Landscape
Premium-margin players sit above commodity-margin players across deployment architecture sophistication and regulatory pre-certification depth. The vendor base organizes into three tiers: cloud-native specialists with embedded compliance automation, legacy suite providers with vertical banking modules, and emerging-market focused platforms with lean implementation footprints. Consolidation pressure intensifies as Tier 1 institutions demand end-to-end integration. Strategic moves concentrate on API ecosystem partnerships and jurisdiction-specific data residency certifications.
Within the cloud-native tier, SAP S/4HANA and Oracle ERP Cloud anchor premium positioning through deep regulatory pre-configuration across multiple jurisdictions. Temenos occupies a distinct archetype serving emerging-market banking architectures with compressed deployment timelines. ServiceNow ITSM represents the adjacent workflow automation vector that banking ERP suites increasingly absorb. These three exemplify how vendor selection now hinges on compliance certification velocity rather than feature breadth alone.
| Leading Market Players |
|---|
| Rise with SAP |
| ServiceNow ITSM |
| SAP S/4HANA |
| Microsoft Dynamics 365 Finance |
| Oracle NetSuite ERP |
| Oracle ERP Cloud |
| FinancialForce |
| Temenos |
| Workday |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up system integrators now dominate implementation capacity, tightening vendor pricing discipline while compressing mid-tier bank procurement timelines through bundled compliance certification packages.
Pricing Analysis
Outcome-based pricing tied to regulatory audit pass rates anchors vendor value propositions, with Tier 1 institutions paying premiums for pre-certified Basel III and EU AI Act compliance modules. Three-tier pricing structure across premium, standard, and economy levels separates cloud-native suites with embedded updates from legacy lift-and-shift migrations and bare-bones SaaS configurations. Pricing pressure stems from subscription fatigue among regional banks comparing total cost of ownership across 36-month horizons. Credit unions exhibit acute price sensitivity; Tier 1 commercial banks prioritize compliance velocity over unit cost.
Supply Chain Analysis
Freight costs for hardware-dependent on-premises deployments have risen as a share of total implementation spend, pushing Indian and German banks toward cloud-native delivery models. Software development concentrates in India, Germany, and the United States, with implementation services drawing from specialized system integrator networks in the United Kingdom and Singapore. Critical dependencies include Kubernetes container orchestration talent, jurisdiction-specific data residency infrastructure, and pre-certified regulatory template libraries. Single-source vulnerability persists around COBOL modernization specialists. Distribution runs through direct vendor sales for Tier 1 institutions and channel partners for mid-tier segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where the EU AI Act's algorithmic auditability mandates erect formidable barrier-to-entry moats favoring vendors with pre-certified regulatory modules.
For Market Incumbents: Anticipate margin compression from cloud-native challengers by accelerating API ecosystem partnerships and embedding real-time compliance updates as standard features. Threat substitution from lean-implementation specialists in emerging markets demands defensive certification investments in India's RBI cybersecurity framework and Saudi Arabia's SAMA operational resilience standards. Backward integration into specialized system integrator networks preserves implementation quality control. For New Entrants and Emerging Players: The EU AI Act in Germany and France opens a window for algorithmic explainability modules targeting 2026 deployment deadlines. White-space concentrates in US community banks seeking FedNow-compatible SaaS cores and Indian regional banks under RBI cloud data residency mandates. A white-label embedded finance play for UK fintechs offers the most penetrable go-to-market angle with compressed sales cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed legacy modernization specialists in the United States with stranded COBOL expertise and regulatory pre-certification assets. Long-term viability hinges on recurring revenue concentration and compliance update subscription attach rates. Watch central bank digital currency pilot announcements from the ECB and RBI as inflection signals for programmable ledger architecture demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | EU AI Act compliance modules accelerate German and French procurement decisions. |
| API Ecosystem Partnership | Open banking protocol alignment reduces integration engineering redundancy across jurisdictions. |
| Cloud Data Residency Expansion | India's RBI framework and Saudi SAMA rules require jurisdiction-specific instance deployment. |
| Embedded Finance White-Label Launch | UK and US non-bank platforms demand lending-as-a-service core banking stacks. |
| Central Bank Digital Currency Integration | ECB digital euro and India e-rupee pilots create programmable ledger architecture demand. |
Methodological Framework
Independent corroboration across vendor product documentation, regulatory filing databases, and system integrator implementation records underwrites the qualitative findings. Primary interviews with banking CIOs, ERP procurement officers, regulatory compliance leads, and cloud platform architects combined with secondary validation from ECB technical standards, Federal Reserve SR guidance documents, and RBI circulars. Bottom-up deployment sizing and top-down market aggregation triangulate volume estimates.
Rate-of-change decomposition separates baseline replacement demand from regulatory-mandated acceleration and technology-displacement effects across the analysis window. Segmentation dimensions span deployment architecture, institution tier, functional module priority, and regional regulatory cluster. CAGRs derive from logistic adoption curves fitted to cloud migration penetration data and compliance deadline clustering. Forecast inputs include DORA implementation timelines and instant payment infrastructure rollout schedules.
The model assumes a particular technology adoption path; alternative pathways for distributed ledger interoperability would alter the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and cloud security certification velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Asia-Pacific Machine Learning in Banking Market
Banking
Asia-Pacific Challenger Banks Market
Banking
Latin America Data Analytics in Banking Market
Banking
Latin America Neo Banking Services Market
Banking
Latin America Banking As a Service Market
Banking
Virtual Teller Machine (VTM) Market
Banking
Europe Neobanking Market
Banking
Europe Data Analytics in Banking Market
Banking
Internet of Things (IoT) in Banking Market
Banking
US Commercial Banking Market
Banking
Onsite and Offsite Atms Market
Banking
Saudi Arabia Retail Banking Market
Banking
Corporate Banking Market
Banking
Mobile Banking Market
Banking
Singapore Neobanking Market
Banking
E-Banking Market