
 Asia-Pacific Machine Learning in Banking Market | 2026-2036
Asia-Pacific Machine Learning in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Machine Learning in Banking Market Analytics
Buyer concentration among Asia-Pacific retail banks is decoupling from traditional tier-one money-center institutions as mid-size lenders in Indonesia, Vietnam, and the Philippines adopt cloud-native fraud detection suites. DBS Bank leverages its Singapore headquarters to sustain regional technology leadership in supervised learning deployments for wealth management. ICICI Bank anchors Indian market development through proprietary risk management algorithms serving both retail and corporate segments. Amazon Web Services competes aggressively on infrastructure cost, while Mitsubishi UFJ Financial Group dominates Japan's on-premise legacy transformation segment.
Asia-Pacific machine learning in banking encompasses algorithmic systems that process transactional, behavioral, and alternative data streams through neural network architectures to automate credit decisions, detect anomalous patterns, and personalize financial product recommendations. These systems typically operate on latency thresholds below 200 milliseconds for real-time fraud interception and require structured training datasets exceeding ten million labeled observations for production-grade accuracy. Fraud detection and risk management applications currently capture the largest margin pools due to regulatory capital relief and direct loss prevention. Cloud-based deployment is accelerating fastest among neobanks and digital lenders, though hybrid architectures persist among established players managing sovereign data requirements.
India's RBI digital lending guidelines, China's SAMR algorithmic recommendation provisions, and Australia's APRA CPS 234 cybersecurity standard collectively shape product certification requirements and vendor qualification pathways across the region. BIS interoperability standards and Japan's METI AI governance framework further constrain cross-border model deployment architectures. Stakeholders must monitor evolving data localization mandates and model explainability thresholds as procurement criteria harden across national regulators.
Market Dynamics
Asia-Pacific retail banks face intensifying pressure from RBI digital lending guidelines and China's SAMR algorithmic recommendation provisions, which mandate explainable model architectures and audit trails for automated credit decisions. These regulatory frameworks are forcing institutions to rebuild core infrastructure rather than retrofit legacy systems.
Growth Catalysts
- Cloud infrastructure maturation:Australia's APRA CPS 234 cybersecurity standard has validated cloud-first deployment for algorithmic risk scoring, accelerating procurement cycles among ASEAN neobanks.
- Alternative data integration:Behavioral biometrics and transaction pattern analysis enable real-time fraud interception with latency below 200 milliseconds across Southeast Asian digital lenders.
- Regulatory sandbox expansion:South Korea's Financial Services Commission permits live testing of unsupervised learning models for wealth management personalization without full licensing requirements.
Market Restraints
- Data localization mandates:China's cybersecurity law and India's draft data protection bill require sovereign storage of training datasets, fragmenting model deployment architectures.
- GPU supply concentration:NVIDIA's dominance in training hardware creates procurement bottlenecks for mid-size Indonesian and Vietnamese banks seeking on-premise neural network infrastructure.
- Model interpretability thresholds:Japan's METI AI governance framework mandates human-readable decision trees for credit denials, constraining deep learning adoption in retail lending.
Strategic Opportunities
- Philippines rural banking penetration:Algorithmic micro-lending platforms using satellite imagery and mobile wallet data address the 70% unbanked population outside Metro Manila.
- Cross-border payment intelligence:BIS interoperability standards enable ASEAN-wide anomaly detection networks linking Singapore, Thailand, and Malaysia clearing systems.
- Carbon-linked credit pricing:China's dual carbon goals incentivize ML models that incorporate emissions data into corporate loan risk assessments for state-owned enterprises.
Industry Challenges
- Production-grade dataset assembly:Vietnam and Indonesia lack centralized credit bureaus with sufficient labeled observations for supervised learning accuracy thresholds.
- Legacy core banking integration:Japanese megabanks and Australian mutual banks face 18-24 month timelines to connect real-time ML inference engines to 1980s-era COBOL transaction processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Machine Learning in Banking Market |
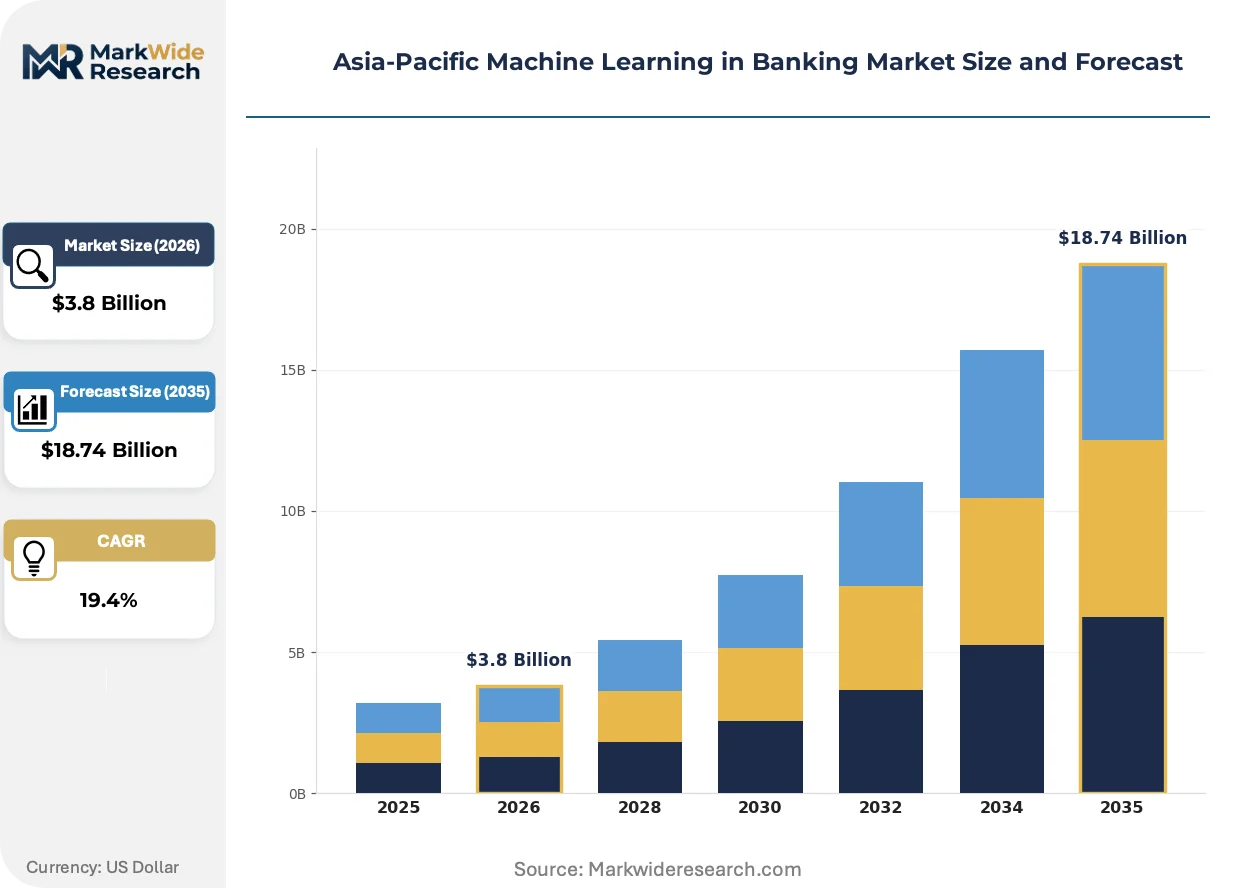
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Risk Management, Customer Service, Credit Scoring Customer Type: Retail Banking, Corporate Banking, Investment Banking, Wealth Management Technology: Supervised Learning, Unsupervised Learning, Neural Networks, Deep Learning Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | DBS Bank, HSBC, Standard Chartered, Bank of China, ICICI Bank, Mitsubishi UFJ Financial Group, Commonwealth Bank of Australia, IBM Corporation, Amazon Web Services, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Machine Learning in Banking Market Evolving Landscape
Federated learning architectures and explainable AI frameworks are redefining how Asia-Pacific banks balance model performance with regulatory compliance. Deployment patterns increasingly favor hybrid infrastructures that process sensitive data on-premise while leveraging cloud compute for non-critical workloads.
Edge computing for real-time fraud detection is decentralizing transaction processing away from centralized data centers. DBS Bank and regional neobanks in Indonesia deploy micro-models directly on payment terminals and mobile banking applications. This architecture reduces round-trip latency for anomaly scoring while satisfying Singapore's MAS and Indonesia's OJK data residency requirements for cross-border transaction monitoring.
China's SAMR algorithmic recommendation provisions now require disclosure of training data sources and model update frequencies for credit-scoring systems. Financial institutions must maintain version-controlled audit trails spanning the full model lifecycle. The provisions disproportionately impact fintech platforms using ensemble methods, forcing simplification of neural network architectures in favor of interpretable gradient-boosted decision trees for consumer lending products.
Subscription-based ML infrastructure procurement is displacing perpetual license models among mid-tier ASEAN banks. Vietnam's TPBank and Philippines' UnionDigital now procure fraud detection capabilities as metered services tied to transaction volumes rather than fixed capex deployments. This shift concentrates vendor relationships with cloud-native providers capable of elastic scaling during seasonal lending peaks, particularly visible in India's festive season credit surges and China's Singles' Day transaction spikes.
Asia-Pacific Machine Learning in Banking Market Segmentation
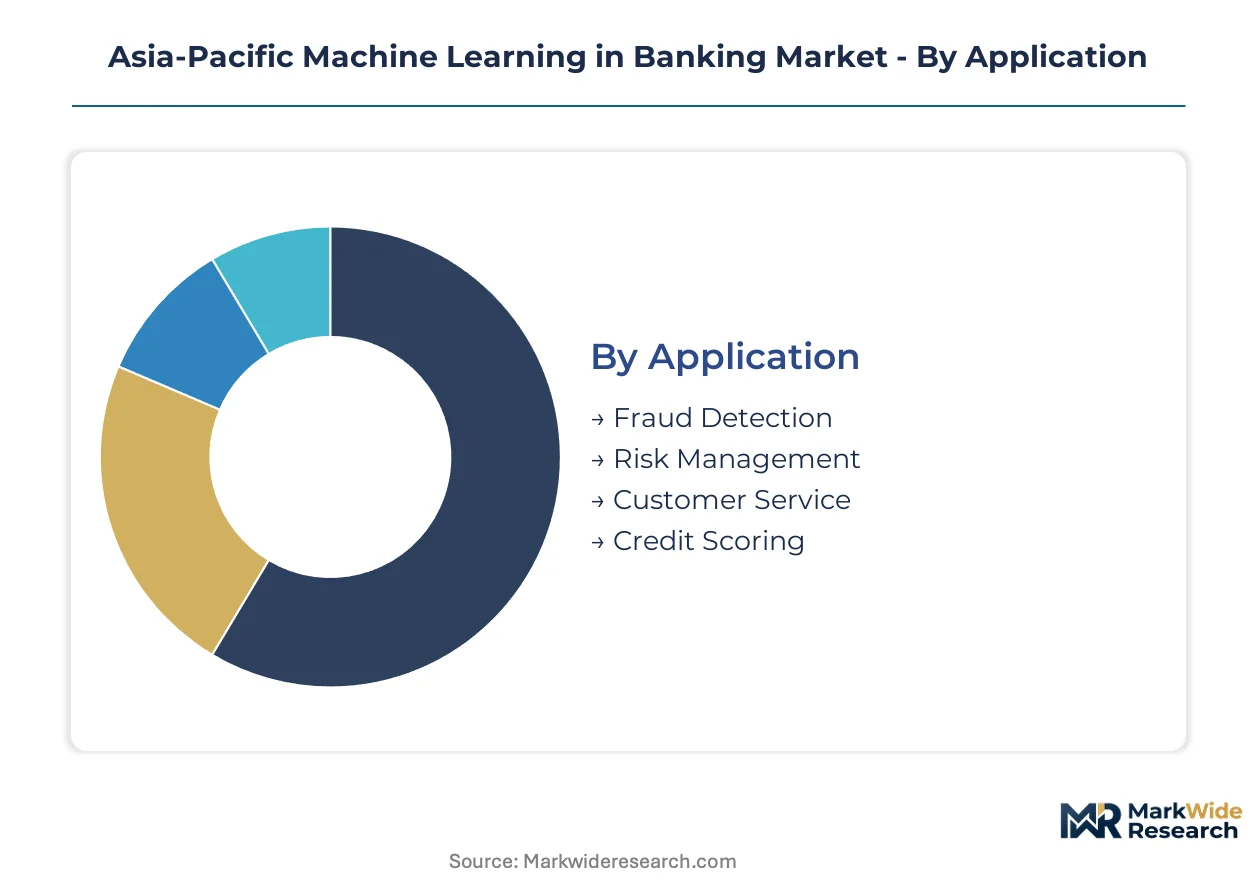
Machine learning deployments across Asia-Pacific banking exhibit stark architectural fragmentation. Integration depth varies dramatically—from standalone fraud detection modules to deeply embedded risk engines within core banking platforms—shaping procurement patterns and vendor relationships across the region.
Application:
Fraud detection and risk management systems typically embed directly into transaction processing pipelines, while customer-facing applications often operate as standalone service layers.
- Fraud Detection:Real-time anomaly scoring engines process transactional streams through gradient-boosted trees and neural network classifiers. Australian neobanks and Singaporean digital lenders concentrate procurement here, driven by APRA CPS 234 cybersecurity mandates and MAS technology risk management requirements that mandate sub-200 millisecond interception latency.
- Risk Management:Portfolio-level credit risk models integrate with regulatory capital calculation engines, processing macroeconomic scenarios and borrower behavioral data. India's RBI digital lending guidelines and China's SAMR algorithmic recommendation provisions are forcing banks to rebuild these systems with full audit trail capabilities rather than retrofit legacy infrastructure.
- Customer Service:Conversational AI and predictive intent classification systems handle query routing and product recommendations.
- Credit Scoring:Algorithmic underwriting models leverage alternative data streams including mobile wallet patterns and satellite-derived economic indicators.
Volume placements concentrate in Fraud Detection; the faster expansion belongs to Credit Scoring.
Customer Type:
Cost tier differentiation separates high-complexity institutional deployments from standardized retail automation suites.
- Retail Banking:Mass-market personalization engines and automated lending platforms serve individual depositors and borrowers. Indonesian, Vietnamese, and Philippine mid-size lenders drive demand here, procuring cloud-native fraud detection suites as metered services tied to transaction volumes rather than fixed capital deployments.
- Corporate Banking:Supply chain finance analytics and dynamic credit limit management systems process trade documentation and cash flow forecasts. China's dual carbon goals are accelerating procurement of emissions-integrated risk models for state-owned enterprise lending portfolios.
- Investment Banking:Algorithmic trading surveillance and market abuse detection systems monitor compliance across trading floors.
- Wealth Management:Portfolio optimization and client risk profiling tools automate advisory workflows. South Korea's Financial Services Commission regulatory sandbox permits live testing of unsupervised learning personalization models without full licensing requirements, stimulating innovation here.
Margin concentration favors Corporate Banking; Retail Banking claims the steepest expansion trajectory.
Technology:
Maturity gradients separate production-hardened supervised methods from experimental deep learning architectures still navigating explainability constraints.
- Supervised Learning:Production-grade classification and regression models trained on structured, labeled datasets exceeding ten million observations. DBS Bank leverages Singapore's data infrastructure leadership to deploy these systems across regional wealth management operations.
- Deep Learning:Multi-layer neural architectures for unstructured data processing including document analysis and voice biometrics. Japan's METI AI governance framework mandates human-readable decision trees for credit denials, constraining deployment in consumer lending despite superior predictive performance.
- Unsupervised Learning:Clustering and anomaly detection methods identify emergent patterns without pre-labeled training data.
- Neural Networks:Feedforward and recurrent architectures for time-series forecasting and sequential pattern recognition.
Production volume concentrates in Supervised Learning; Deep Learning is climbing the fastest despite regulatory headwinds.
Deployment:
Supply concentration in cloud infrastructure is displacing traditional on-premise procurement among ASEAN neobanks while hybrid architectures persist for sovereign data compliance.
- Cloud-Based:Elastic compute environments enabling metered scaling during seasonal transaction peaks. Vietnam's TPBank and Philippines' UnionDigital exemplify this shift, procuring fraud detection as operational expenditure tied to India's festive season credit surges and China's Singles' Day transaction spikes.
- Hybrid:Architectures processing sensitive training data on-premise while leveraging cloud compute for non-critical workloads. China's cybersecurity law and India's draft data protection bill mandate sovereign storage of training datasets, fragmenting model deployment architectures and sustaining hybrid demand.
- On-Premise:Dedicated hardware installations for latency-critical or compliance-constrained workloads.
- Edge Computing:Micro-models deployed directly on payment terminals and mobile banking applications. DBS Bank and Indonesian neobanks use this architecture to reduce round-trip latency while satisfying Singapore's MAS and Indonesia's OJK data residency requirements for cross-border transaction monitoring.
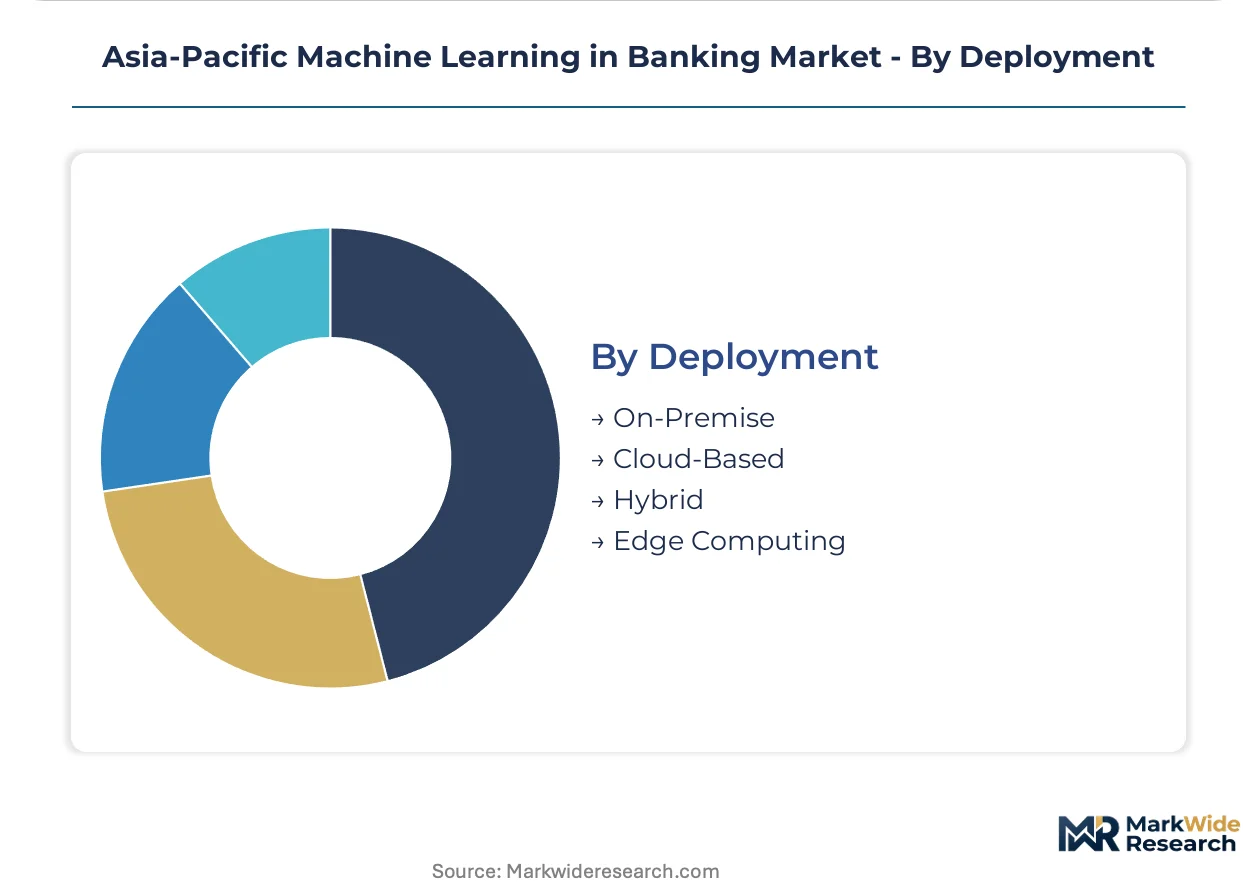
Current volume concentrates in Hybrid deployments; Cloud-Based infrastructure is gaining share fastest among new market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Australia's mature cloud-first banking sector and South Korea's regulatory sandbox environments, with mid-size lenders in Indonesia, Vietnam, and the Philippines driving the steepest procurement acceleration.
Australia
APRA CPS 234 cybersecurity mandates validate cloud-first algorithmic risk scoring, compressing procurement cycles among neobanks. The prudential standard requires sub-200 millisecond fraud interception latency. Sydney anchors regional technology leadership with DBS Bank leveraging its Singapore headquarters for supervised learning deployments serving wealth management operations across the Tasman.
China
SAMR algorithmic recommendation provisions force disclosure of training data sources and model update frequencies for credit-scoring systems. The cybersecurity law mandates sovereign storage of training datasets, fragmenting deployment architectures. Shanghai and Beijing clusters concentrate emissions-integrated risk model development for state-owned enterprise lending portfolios aligned with dual carbon goals.
India
RBI digital lending guidelines mandate explainable model architectures and audit trails for automated credit decisions, forcing core infrastructure rebuilds rather than retrofits. ICICI Bank anchors market development through proprietary risk management algorithms. Mumbai and Bangalore drive procurement concentration among mid-size lenders adopting cloud-native fraud detection suites.
South Korea
The Financial Services Commission regulatory sandbox permits live testing of unsupervised learning models for wealth management personalization without full licensing requirements. Seoul concentrates demand for experimental deep learning architectures navigating explainability constraints. Samsung Life and regional neobanks test federated learning deployments across the capital region.
Singapore
MAS technology risk management requirements drive edge computing adoption for real-time fraud detection with data residency compliance. DBS Bank deploys micro-models directly on payment terminals to reduce round-trip latency. The city-state functions as regional headquarters for supervised learning operations spanning Southeast Asian digital lending markets.
Asia-Pacific Machine Learning in Banking Market Competitive Landscape
Singapore-based institutions anchor one tier; Japanese and Australian specialists hold differentiated positions in legacy transformation and cloud infrastructure respectively. Market structure exhibits moderate consolidation around financial services conglomerates with captive technology capabilities, complemented by infrastructure vendors competing on elastic scaling economics. Three archetypes dominate: incumbent banks with proprietary algorithm development, hyperscale cloud providers offering metered ML infrastructure, and legacy core banking integrators managing hybrid deployment timelines. Competitive moves concentrate on strategic partnerships between neobanks and cloud-native vendors, plus backward integration into training data assembly capabilities.
Within the incumbent bank tier, DBS Bank and ICICI Bank exemplify institutions that have developed captive algorithmic capabilities spanning regional operations. Mitsubishi UFJ Financial Group occupies a distinct position in Japan's on-premise legacy transformation segment, managing extended integration timelines for COBOL-era transaction processors. Among infrastructure providers, Amazon Web Services represents the cloud-native archetype competing aggressively on operational expenditure models tied to transaction volumes.
| Leading Market Players |
|---|
| DBS Bank |
| HSBC |
| Standard Chartered |
| Bank of China |
| ICICI Bank |
| Mitsubishi UFJ Financial Group |
| Commonwealth Bank of Australia |
| IBM Corporation |
| Amazon Web Services |
| Others |
Value Network & Pricing Analysis
Hyperscale cloud providers with sovereign-backed data center investments in Singapore and Australia anchor supply-side pricing power, translating infrastructure concentration into metered-service pricing discipline that fragments procurement economics across ASEAN neobanks and established Japanese institutions.
Pricing Analysis
High-volume transactional scoring runs on thin margins while bespoke risk model development commands premium pricing. Subscription-based SaaS tiers dominate among Vietnam's TPBank and Philippines' UnionDigital, with price differentiation hinging on latency guarantees and explainability certification levels. Cost compression in standardized fraud detection is intensifying because AWS and regional hyperscalers compete on elastic scaling economics. Mid-size Indonesian lenders exhibit the sharpest price sensitivity; DBS Bank and Australian neobanks show minimal elasticity for sub-200 millisecond latency assurances.
Supply Chain Analysis
Regional distribution centers in Singapore and Sydney coordinate GPU hardware provisioning and model deployment pipelines across the Asia-Pacific banking corridor. Training hardware concentrates in Taiwan, South Korea, and USA fabrication networks; cloud compute infrastructure rests on submarine cable capacity linking Tokyo, Hong Kong, and Sydney nodes. Single-source vulnerability in NVIDIA accelerator supply creates procurement bottlenecks for Indonesian and Vietnamese banks seeking on-premise neural network infrastructure. Distribution runs through sovereign-compliant hybrid architectures that process sensitive data locally while leveraging cross-border cloud orchestration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
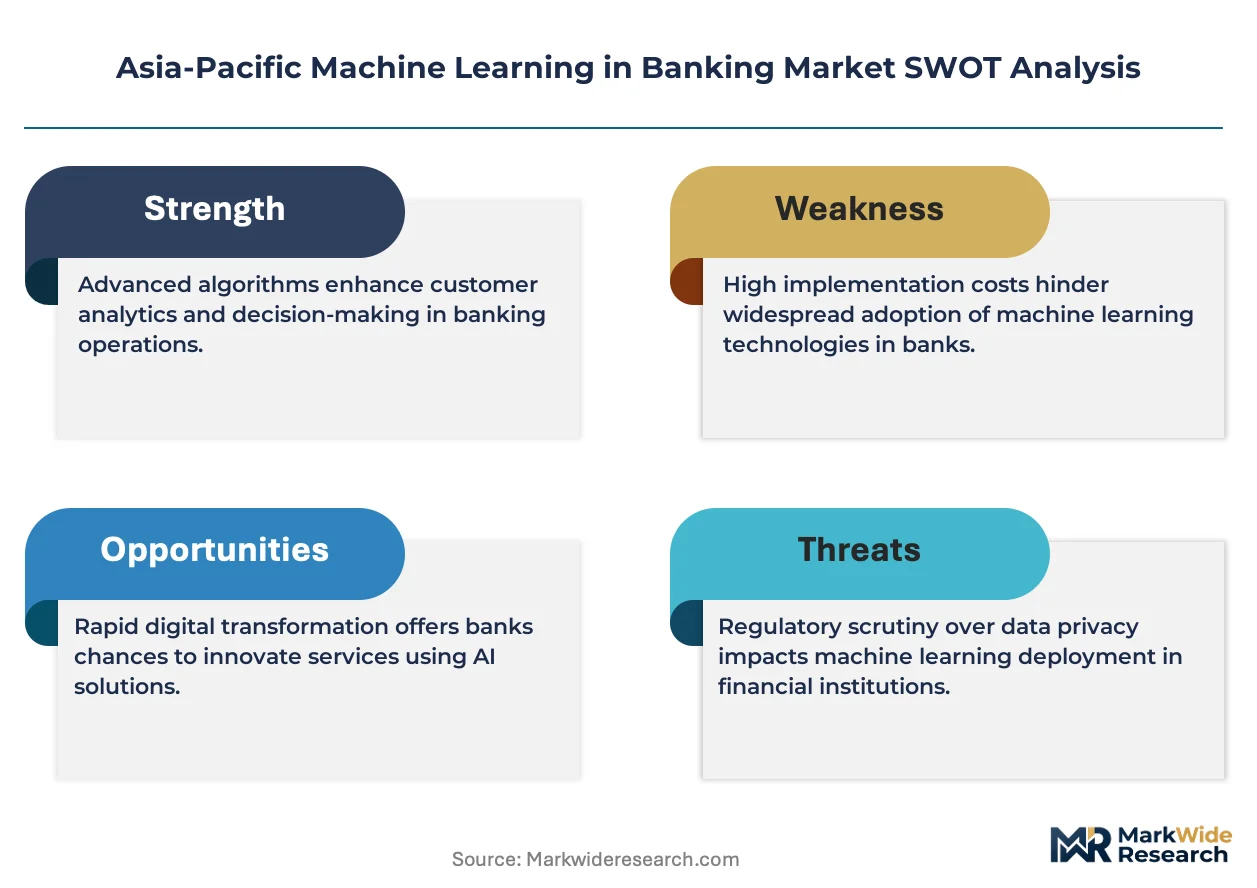
This market reads as a cost-of-compliance story where India's RBI digital lending guidelines and China's SAMR algorithmic recommendation provisions erect barrier-to-entry moats favoring institutions with captive audit-trail capabilities and explainable model architectures.
For Market Incumbents: Anticipate regulatory fragmentation forcing redundant infrastructure investments across multiple national jurisdictions. DBS Bank and ICICI Bank should deepen backward integration into training data assembly capabilities to defend against cloud-native challengers eroding margin in standardized fraud detection. Priority investment in federated learning architectures addresses emerging data localization mandates without sacrificing model performance across regional operations. For New Entrants and Emerging Players: Cloud-native vendors with metered-service platforms represent the most viable channel partner type for penetrating mid-tier ASEAN banks. White-space concentrates in Philippines rural algorithmic micro-lending and Vietnam's credit-scoring gap where centralized bureau data remains insufficient. Target South Korea's regulatory sandbox environment for unsupervised learning personalization pilots that bypass full licensing requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialist explainable-AI tooling vendors in Singapore and Sydney facing working capital pressure from extended enterprise sales cycles. Long-term viability hinges on regulatory certification breadth across RBI, SAMR, and APRA frameworks. Watch for BIS interoperability standard finalization as inflection signal triggering cross-border payment intelligence procurement waves.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Entry | South Korea's FSC permits live unsupervised learning testing without full licensing requirements. |
| Hybrid Cloud Certification | APRA CPS 234 validation accelerates procurement cycles among Australian neobanks. |
| Alternative Data Partnership | Satellite imagery and mobile wallet integrations address Philippines' 70% unbanked population. |
| Edge Computing Deployment | DBS Bank micro-models on payment terminals satisfy Singapore MAS data residency mandates. |
| Carbon-Linked Model Development | China's dual carbon goals incentivize emissions-integrated risk scoring for SOE lending portfolios. |
Research Methodology
Central bank regulatory filings, hyperscaler infrastructure capex disclosures, and ASEAN fintech licensing databases formed the secondary backbone, supplemented by primary interviews with chief risk officers, cloud procurement leads, and regulatory technology specialists. Bottom-up triangulation against top-down market sizing validated deployment volume estimates across supervised learning, deep learning, and neural network segments.
Historical trendline analysis of algorithmic credit decision adoption rates informed projection frameworks across the analysis window, with segmentation modeling by application, customer type, technology maturity, and deployment architecture. CAGRs derived from elasticity-adjusted penetration curves incorporating RBI guideline implementation timelines and China's SAMR enforcement phases. Forecast inputs included GPU supply constraints and sovereign data localization mandate progression patterns.
Several conditions sit outside the modeled scope, including potential BIS interoperability standard revisions and unannounced national data protection legislation. Forecasts reflect documented assumptions around regulatory enforcement consistency and cloud infrastructure cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
E-Banking Market
Banking
Letter of Credit Confirmation Market
Banking
Global IoT in Banking and Financial Services Market
Banking
Global Certificate of Deposit Market
Banking
Bank Management Software Market
Banking
Banking As a Service (BAAS) Market
Banking
Global Neobanking Market
Banking
Open Banking Market
Banking
In Vitro Fertilization Banking Services Market
Banking
Predictive Analytics in Banking Market
Banking
North America Challenger Banks Market
Banking
Latin America Banking As a Service Market
Banking
Germany Data Analytics in Banking Market
Banking
Bank Kiosk Market
Banking
Asia-Pacific Islamic Finance Market
Banking
Machine Learning in Banking Market