
 US Commercial Banking Market | 2026-2036
US Commercial Banking Market Size, Share, and Industry Trends Forecast 2026-2036
US Commercial Banking Market Analytics
The Basel III endgame proposal is decoupling capital adequacy thresholds from legacy tier-based classifications, forcing regional lenders to rebuild balance sheet efficiency from first principles. JPMorgan Chase anchors its commercial banking dominance through scale advantages in transaction banking and cash management infrastructure. Wells Fargo navigates regulatory consent-order constraints while competing for middle-market share in specialized lending verticals. Truist positions its commercial franchise around integrated wealth and business banking delivery across Southeastern metropolitan corridors.
US commercial banking encompasses deposit-taking, credit intermediation, treasury services, and payment facilitation for business entities, operating through fractional-reserve mechanics where institutions hold capital reserves against risk-weighted assets while deploying remaindered funds into productive loans. The sector's primary commercial purpose channels household and institutional savings into corporate capital formation, trade finance, and liquidity management instruments. Business banking services generate the deepest margin pools among service-type segments, reflecting sticky operating account relationships and cross-sell density in treasury management. Online and mobile channels are displacing branch-dependent acquisition models for small enterprises, though corporations still demand dedicated relationship coverage. Loans remain the dominant product-type revenue engine, with commercial real estate and commercial-and-industrial credit lines commanding pricing power in rate-elevated environments.
The Federal Reserve, OCC, and FDIC collectively shape US commercial banking through capital standards, examination intensity, and resolution planning mandates that determine which institutions can absorb balance sheet complexity. The Federal Reserve's stress-testing regime and the SEC's disclosure requirements for public bank holding companies create compliance architectures that favor institutions with dedicated regulatory technology infrastructure. Stakeholders must monitor how the interplay between Basel implementation timelines and regional bank liquidity stress reshapes competitive viability for non-systemic institutions.
Market Dynamics
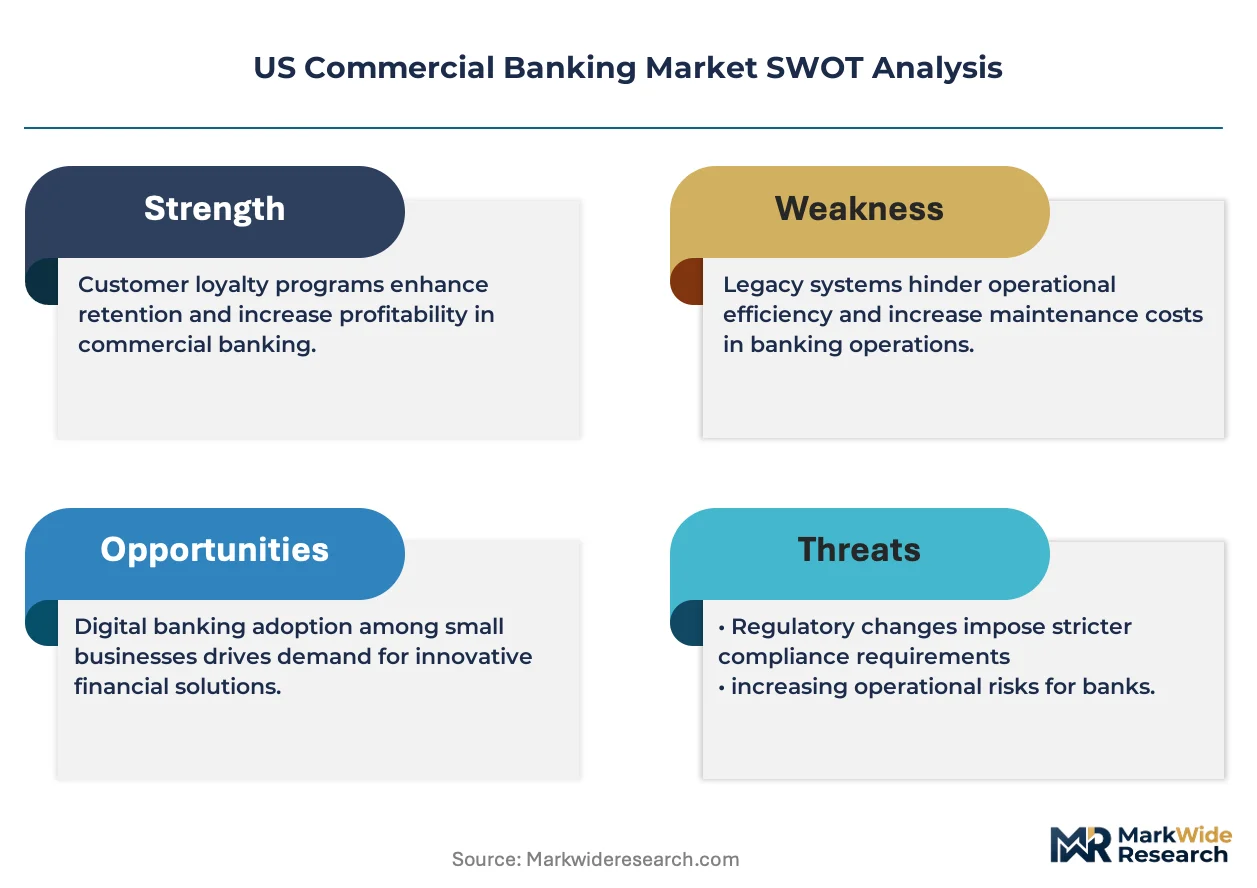
The Federal Reserve's Basel III endgame recalibration is compressing net interest margin flexibility for regional banks while migration-driven deposit concentration in Sun Belt states reshapes branch network economics.
Growth Catalysts
- Texas and Florida deposit migration:Corporate relocations and population inflows are expanding commercial loan demand and treasury service adoption in Dallas-Fort Worth and Miami-Dade corridors.
- Real-Time Payments network expansion:The Federal Reserve's FedNow infrastructure is accelerating transaction velocity for small enterprises seeking instant settlement.
- Commercial real estate repricing:Distressed office asset valuations are creating acquisition financing opportunities for specialized lenders with workout expertise.
Market Restraints
- Basel III endgame capital requirements:The Federal Reserve's proposed risk-weighting adjustments are elevating compliance costs for mid-tier institutions below systemic thresholds.
- Office commercial real estate exposure:Hybrid work permanence is eroding collateral values in legacy central business districts, constraining loan-to-value ratios.
- Treasury management fee compression:Fintech payment rails are undercutting traditional wire and ACH pricing for small enterprise accounts.
Strategic Opportunities
- Embedded finance integration:Banking-as-a-Service APIs are enabling white-label deposit and lending products for vertical SaaS platforms serving niche industries.
- Southeastern wealth-commercial convergence:Truist and comparable regionals are bundling business banking with personal wealth management for entrepreneur households in Atlanta and Charlotte.
- Climate risk underwriting tools:Physical asset stress modeling is creating differentiation in commercial real estate lending for flood and wildfire exposure zones.
Industry Challenges
- Core system modernization debt:Legacy mainframe architectures are impeding real-time data integration for AI-driven credit decisioning.
- Commercial banker talent scarcity:Relationship manager retirements are outpacing apprenticeship pipelines in middle-market specialized lending.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Commercial Banking Market |
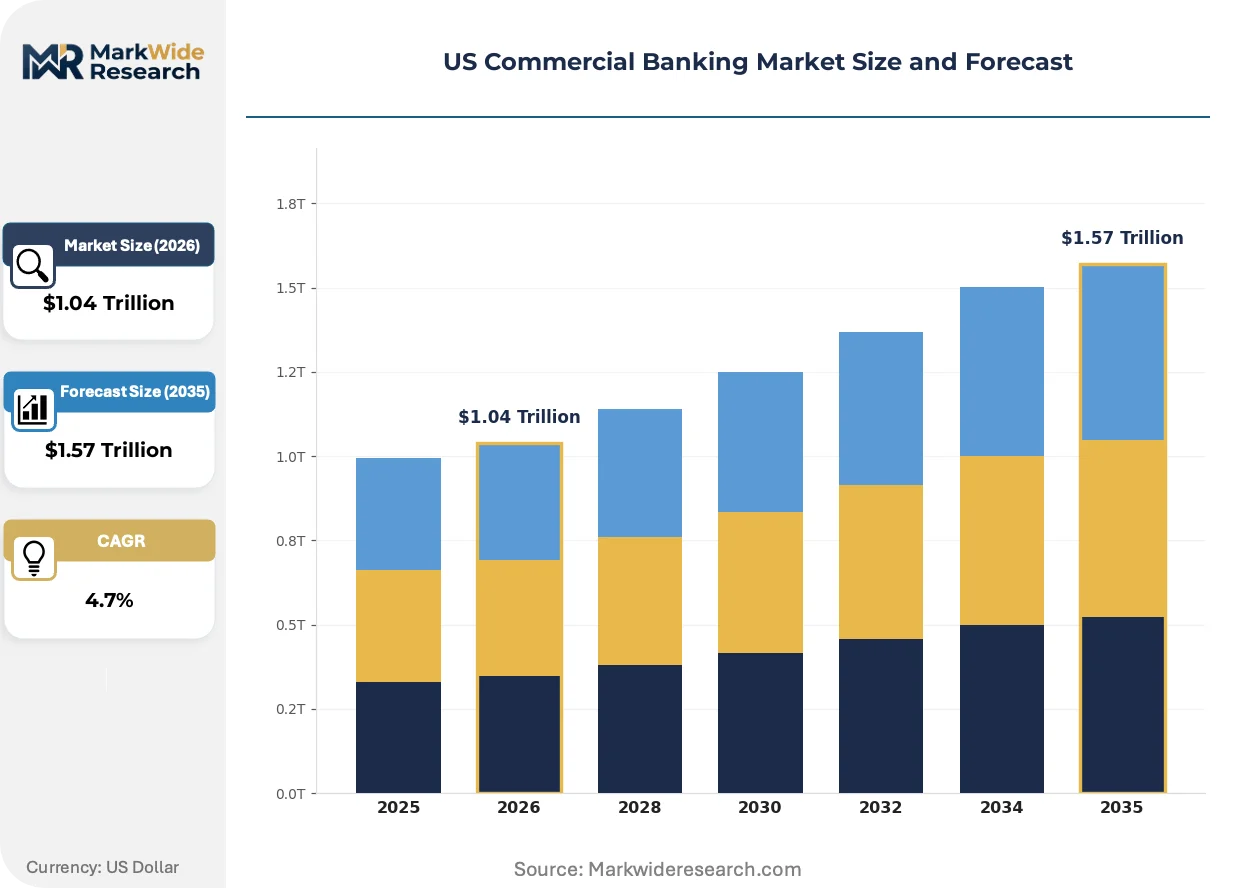
| Market Size in 2026 | $1.04 Trillion |
| Market Size in 2035 | $1.57 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Banking, Business Banking, Investment Services, Wealth Management Customer Type: Individuals, Small Enterprises, Corporations, Non-Profits Channel: Online, Mobile, Branch, ATM Product Type: Loans, Deposits, Credit Cards, Mortgages |
| Companies Covered | Citigroup, Capital One, JPMorgan Chase, Goldman Sachs, PNC Financial Services, Bank of America, U.S. Bancorp, Truist, Wells Fargo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Commercial Banking Market Evolving Landscape
Distributed ledger infrastructure and open banking protocols are eroding proprietary payment network advantages while regulatory stress-testing intensifies.
Blockchain-based trade finance platforms are decentralizing correspondent banking relationships for cross-border receivables financing. Mid-market exporters in manufacturing verticals are piloting smart contract settlement to compress documentary credit timelines from weeks to hours. This disintermediation is decentralizing the correspondent fee pools that historically anchored international banking revenue.
The Federal Reserve's Basel III endgame proposal is forcing regional institutions to restructure balance sheet efficiency through risk-weighting optimization. Mid-tier banks are shedding commercial real estate concentrations and rebuilding capital ratios through retained earnings compression. Southeastern and Southwestern institutions with lighter legacy asset burdens are adapting faster than Northeastern peers with denser office exposure.
Small enterprise banking relationships are fragmenting across channel-specific providers rather than consolidating at single institutions. Fintech payroll and accounting platforms are capturing primary operating account status while traditional banks retain credit-only relationships. This unbundling is most pronounced in Texas and Florida markets where venture-backed neobanks have established physical presence.
US Commercial Banking Market Segmentation
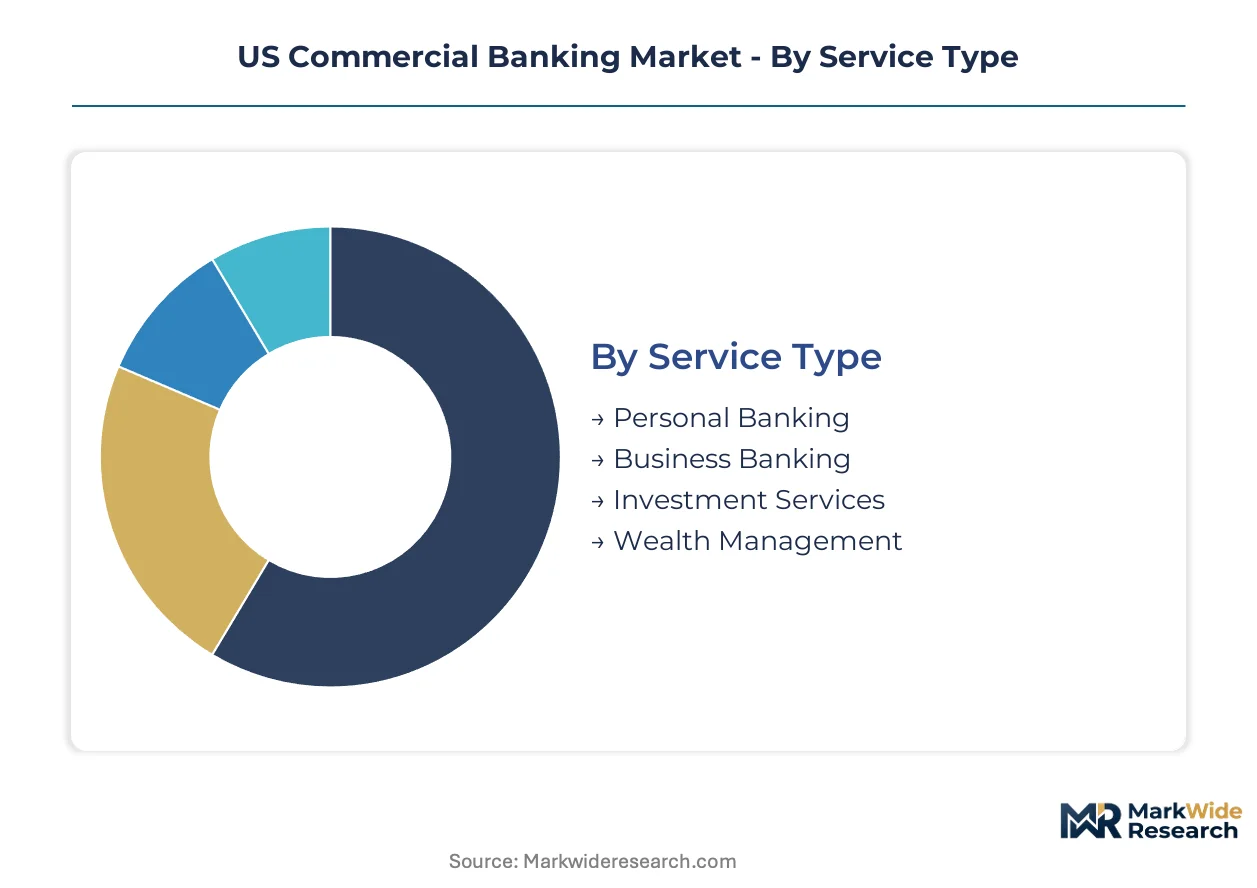
Segmentation reveals how US commercial banking revenue pools fragment across service lines and delivery modes. Understanding these divisions exposes where margin compression hits hardest and which relationship types retain pricing power.
Service Type:
Upgrade cycles in digital treasury platforms are accelerating service line substitution as enterprises replace legacy cash management systems.
- Personal Banking:Individual deposit accounts and consumer lending products generate stable funding bases through core checking relationships. Demand concentrates in Sun Belt metropolitan corridors where migration inflows expand household formation; regulatory scrutiny of overdraft fee structures is compressing non-interest income.
- Business Banking:Commercial deposit accounts, treasury management, and working capital facilities command the deepest cross-sell density among service types. Small enterprises in Dallas-Fort Worth and Miami-Dade are expanding adoption of integrated payables and receivables automation; FedNow real-time settlement infrastructure is displacing legacy wire transfer volume.
- Investment Services:Institutional custody, securities lending, and capital markets execution for corporate treasuries.
- Wealth Management:High-net-worth advisory and fiduciary services bundled with commercial relationships for entrepreneur households.
Volume placements concentrate in Business Banking; the faster expansion belongs to Wealth Management.
Customer Type:
Cost tier differentiation separates mass-market acquisition economics from relationship-managed corporate mandates.
- Individuals:Mass-market consumers and affluent households seeking deposit products and consumer credit. Branch network rationalization is pushing these relationships toward mobile-first servicing models; neobank competition in Texas and Florida is eroding primary account status.
- Small Enterprises:Businesses with annual revenues below $25 million requiring operating credit and treasury services. Embedded finance APIs from vertical SaaS platforms are fragmenting deposit relationships; specialized lenders with workout expertise are capturing distressed commercial real estate financing opportunities.
- Corporations:Middle-market and large enterprises demanding dedicated relationship coverage and customized liquidity structures. Migration-driven deposit concentration in Southeastern and Southwestern corridors is reshaping coverage model economics; Basel III endgame capital requirements are elevating compliance costs for bilateral credit commitments.
- Non-Profits:Charitable organizations and educational institutions requiring endowment management and mission-aligned lending.
Corporations anchor current volume; small enterprises are climbing the fastest as fintech partnerships expand addressable reach.
Channel:
Application-specific delivery modes now determine acquisition cost and relationship stickiness across customer lifecycle stages.
- Online:Browser-based banking portals for complex treasury workflows and commercial account administration. Corporate clients in rate-elevated environments demand real-time balance visibility and automated sweep structures; legacy core system architectures impede API integration for AI-driven cash forecasting.
- Mobile:Smartphone applications displacing branch-dependent models for small enterprise onboarding and routine transactions. Florida and Texas markets show highest mobile adoption velocity among entrepreneur segments; biometric authentication requirements from the OCC are elevating development spend.
- Branch:Physical locations retaining importance for middle-market relationship origination and complex credit structuring.
- ATM:Cash access infrastructure sustaining relevance for retail-heavy small businesses and construction verticals.
Branch infrastructure still dominates commercial origination volume; mobile channels are gaining share fastest among sub-$5M revenue enterprises.
Product Type:
Margin structure varies sharply across product categories, with secured lending commanding risk-adjusted premium over commoditized deposit gathering.
- Loans:Commercial-and-industrial credit lines and commercial real estate term facilities remain the dominant revenue engine. Office collateral repricing in legacy Northeast central business districts is constraining loan-to-value ratios; specialized lenders with physical asset stress modeling are differentiating flood and wildfire zone underwriting.
- Deposits:Non-interest-bearing demand accounts and interest-bearing money market instruments providing low-cost funding. Migration-driven inflows to Texas and Florida institutions are compressing pricing power; Basel III endgame recalibration is forcing balance sheet efficiency rebuilds through risk-weighting optimization.
- Credit Cards:Commercial card programs for travel, procurement, and fleet management spend.
- Mortgages:Residential and commercial real estate term financing, increasingly bifurcated from core banking relationships.
Loans retain the steepest expansion trajectory among product types; deposit gathering faces sustained margin pressure from rate competition and regulatory capital treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deposit migration patterns concentrate commercial banking demand in Sun Belt metropolitan corridors, while legacy Northeast markets face branch network rationalization pressures from hybrid work permanence.
Texas
Corporate relocations from California and New York are expanding commercial loan demand and treasury service adoption in Dallas-Fort Worth and Austin. The Texas Department of Banking maintains state-chartered oversight alongside federal regulation. Houston's energy finance cluster is attracting specialized lenders with hydrocarbon transition expertise.
Florida
Population inflows from high-tax states are driving deposit growth that outpaces legacy Northeast corridors, particularly in Miami-Dade and Tampa Bay. The Florida Office of Financial Regulation supervises state-chartered institutions under dual federal-state framework. Miami's international banking hub is capturing Latin American corporate treasury business fleeing regional instability.
California
Technology sector consolidation is compressing middle-market lending opportunities while venture capital deployment shifts toward climate infrastructure. The California Department of Financial Protection and Innovation enforces consumer protection mandates affecting small enterprise account pricing. San Francisco's fintech corridor is spawning neobank competitors targeting commercial deposit relationships.
New York
Legacy central business district office exposure is eroding commercial real estate collateral values and constraining loan-to-value ratios for regional lenders. The New York State Department of Financial Services maintains stringent examination protocols for money transmitter licensing. Manhattan's financial district retains dominance in investment banking and capital markets execution despite commercial banking migration.
Illinois
Manufacturing supply chain reshoring is reviving commercial-and-industrial credit demand in Chicago metropolitan industrial corridors. The Illinois Department of Financial and Professional Regulation coordinates with the Federal Reserve on state-chartered bank supervision. Chicago's commodity trading infrastructure sustains specialized agricultural and metals financing expertise.
US Commercial Banking Market Competitive Landscape
Money center banks anchor the top tier; regional specialists hold middle-market positioning through relationship density. The sector exhibits tiered consolidation with systemic institutions commanding scale advantages in transaction banking infrastructure. Three archetypes dominate: universal banks with integrated investment banking, super-regionals with geographic concentration, and specialized lenders with vertical expertise. Competitive moves center on technology platform modernization and selective geographic expansion into high-migration corridors.
Among the universal banking tier, JPMorgan Chase, Bank of America, and Wells Fargo exemplify scale-driven positioning across commercial deposit, lending, and treasury service segments. These institutions occupy positions defined by balance sheet capacity and regulatory technology infrastructure investment. Regional competitors including Truist and PNC Financial Services represent the super-regional archetype with integrated wealth-commercial convergence strategies. Specialized positioning appears in institutions like Capital One with technology-forward small enterprise acquisition models and U.S. Bancorp with payments infrastructure depth.
| Leading Market Players |
|---|
| Citigroup |
| Capital One |
| JPMorgan Chase |
| Goldman Sachs |
| PNC Financial Services |
| Bank of America |
| U.S. Bancorp |
| Truist |
| Wells Fargo |
| Others |
Value Network & Pricing Analysis
Systemic-non-systemic bank divergence manifests in divergent cost-of-funding spreads and regulatory technology infrastructure requirements, with money center institutions commanding 40-60 basis point advantages in wholesale funding while mid-tier competitors absorb disproportionate compliance overhead. This bifurcation concentrates pricing power in institutions with dedicated stress-testing architectures and fragments margin pools across regional lenders rebuilding balance sheet efficiency.
Pricing Analysis
Volume concentrates in relationship-managed corporate mandates while margin pools concentrate in specialized lending verticals and treasury management services. Three-tier pricing structure across premium relationship, standard facility, and economy transactional tiers reflects cross-sell density and capital intensity differentials. Pricing pressure stems from fintech payment rails undercutting traditional wire and ACH pricing for small enterprise accounts. Small enterprises show highest price sensitivity; corporations with dedicated coverage show lowest.
Supply Chain Analysis
Domestic-content mandates in critical infrastructure lending and defense-linked credit facilities are reshaping collateral valuation methodologies and correspondent banking relationships. Core banking technology draws from India, Ireland, and domestic US development centers; specialized lending expertise rests on Chicago, Charlotte, and Dallas talent clusters. Single-source vulnerability concentrates in legacy mainframe architectures. Distribution runs through branch networks for middle-market origination and API-integrated platforms for small enterprise acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US commercial banking market operates as a cost-of-compliance story where the Federal Reserve's Basel III endgame proposal erects barrier-to-entry moats favoring institutions with dedicated regulatory technology infrastructure and stress-testing capabilities.
For Market Incumbents: Deploy regulatory technology infrastructure as the primary defensive lever. Accelerate core system modernization to enable real-time data integration for AI-driven credit decisioning, countering fintech payment rail encroachment. Consolidate middle-market share through selective geographic expansion into Dallas-Fort Worth and Miami-Dade corridors where migration-driven deposit growth outpaces legacy Northeast markets.
For New Entrants and Emerging Players: Enter via embedded finance APIs targeting vertical SaaS platforms serving niche industries in Texas and Florida. Capture white-space in small enterprise treasury management where neobank competition has established physical presence but relationship depth remains shallow. Pursue white-label deposit and lending products for construction and logistics software platforms.
For Investors and Strategic Acquirers: Exit pathways concentrate in super-regional acquisition by money center banks seeking geographic density in Sun Belt corridors. Long-term viability favors institutions with lighter legacy commercial real estate burdens and faster adaptation to risk-weighting optimization. Watch the interplay between Basel implementation timelines and regional bank liquidity stress as the inflection indicator for non-systemic institution competitive viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Core System Modernization | Legacy mainframe replacement enables real-time data integration for AI-driven credit decisioning against fintech competitors. |
| Sun Belt Geographic Expansion | Branch network investment in Dallas-Fort Worth and Miami-Dade captures migration-driven deposit inflows outpacing Northeast corridors. |
| Regulatory Technology Infrastructure | Dedicated stress-testing architectures reduce Basel III endgame compliance costs and accelerate capital ratio optimization. |
| Embedded Finance Integration | Banking-as-a-Service APIs penetrate small enterprise segments through vertical SaaS platform partnerships in Texas and Florida. |
| Climate Risk Underwriting Tools | Physical asset stress modeling differentiates commercial real estate lending for flood and wildfire exposure zones. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with commercial banking executives, regulatory affairs officers, treasury management specialists, and middle-market relationship managers. Federal Reserve stress-testing disclosures, OCC examination reports, FDIC call reports, and SEC 10-K filings provided institutional-level validation. Bottom-up loan origination volume estimates and top-down deposit migration patterns were triangulated against macroeconomic indicators.
Data-stream reconciliation across primary fieldwork and secondary validation informed the analytical framework. Segmentation dimensions modeled include service type, customer tier, delivery channel, and product category across the projection horizon. CAGRs were derived from trend-line extrapolation of deposit migration patterns, capital requirement phase-in schedules, and technology adoption curves in treasury management platforms. Commercial real estate exposure concentrations and FedNow payment velocity served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated Basel III implementation or deeper commercial real estate repricing than baseline assumptions. Forecasts reflect documented assumptions regarding regulatory timeline adherence, migration pattern persistence, and fintech competitive intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
India Data Analytics in Banking Market
Banking
Latin America Neo Banking Services Market
Banking
Cloud Billing in Banking Market
Banking
Germany Data Analytics in Banking Market
Banking
Corporate Banking Market
Banking
Cloud Computing Banking Market
Banking
Global Certificate of Deposit Market
Banking
Banking As a Service (BAAS) Market
Banking
Automated Teller Machine (ATM) Market
Banking
North America Challenger Banks Market
Banking
Letter of Credit Confirmation Market
Banking
Third-Party Banking Software Market
Banking
Southeast Asia Commercial Banking Market
Banking
Asia-Pacific Islamic Finance Market
Banking
Video Banking Service Market
Banking
Banking Wearable Devices Market