
 Onsite and Offsite Atms Market | 2026-2036
Onsite and Offsite Atms Market Size, Share, and Industry Trends Forecast 2026-2036
Onsite and Offsite Atms Market Insights
Metal chassis assemblies are consolidating around recycled aluminum and composite polymers that cut unit weight and shipping costs. Diebold Nixdorf leverages its North American manufacturing footprint to control component sourcing. NCR Atleos anchors its position through software-integrated service contracts that extend hardware lifecycles. GRG Banking Equipment dominates Asian supply chains with region-specific cash-handling modules.
Onsite and offsite ATMs are self-service terminals engineered to authenticate users, execute cash transactions, and interface with core banking networks through encrypted protocols; units typically operate on 110-240V AC power with environmental ratings from NEMA 4 to IP54 for outdoor durability. Offsite deployments in retail corridors and transit hubs represent the fastest-growing deployment segment as banks reduce branch footprints. Contactless technology and biometric authentication segments capture expanding margin pools where hardware suppliers bundle subscription-based security updates.
The US Federal Reserve's cash access policies, the EU's PSD2 strong-customer-authentication framework, and India's RBI financial-inclusion directives collectively shape hardware specifications and network interoperability requirements across their respective jurisdictions. Stakeholders must monitor central bank digital currency pilots that could recast ATM functionality from cash dispensing to hybrid digital-physical transaction terminals.
Market Dynamics
PCI DSS compliance mandates and contactless technology migration are compressing hardware refresh cycles across ATM networks, forcing manufacturers to reconfigure supply chains around biometric modules and recycled aluminum chassis assemblies.
Growth Catalysts
- RBI Financial Inclusion Directives:India's rural banking mandates accelerate offsite ATM deployment in unbanked districts, creating sustained hardware demand from public sector banks.
- Retail Cash-Handling Cost Reduction:Supermarket and convenience store chains in Brazil and Indonesia deploy offsite units to eliminate armored transport expenses and vault management overhead.
- Contactless NFC Migration:Tap-to-withdraw protocols reduce card-skimming fraud exposure while extending terminal lifecycles through software-defined security updates.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea fabs control 78% of industrial-grade processor supply, exposing ATM manufacturers to allocation delays and spot-price volatility.
- EU PSD2 Strong Authentication Friction:Multi-factor biometric requirements extend certification timelines and increase per-unit compliance costs for European deployments.
- Mobile Payment Substitution:Real-time retail payment apps in China and Kenya reduce cash withdrawal frequency, compressing transaction revenue per terminal.
Strategic Opportunities
- Central Bank Digital Currency Hybrid Terminals:Pilot programs in Nigeria and Sweden recast ATMs as physical-digital transaction bridges, enabling CBDC-to-cash conversion and vice versa.
- Transit Hub Micro-Branch Networks:Railway stations and airport corridors in Vietnam and Mexico present unserved locations for compact offsite units with foreign exchange functionality.
- EU Green Deal Hardware Incentives:Subsidies for energy-efficient terminal retrofits accelerate replacement of 1990s-era machines across German and French postal banking networks.
Industry Challenges
- Embedded Systems Cybersecurity Talent Scarcity:Firmware hardening against side-channel attacks requires specialized penetration-testing capabilities that ATM OEMs struggle to recruit.
- Legacy Core Banking Integration Complexity:ISO 8583 protocol variants across regional processors force custom middleware development for each national deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Onsite and Offsite Atms Market |
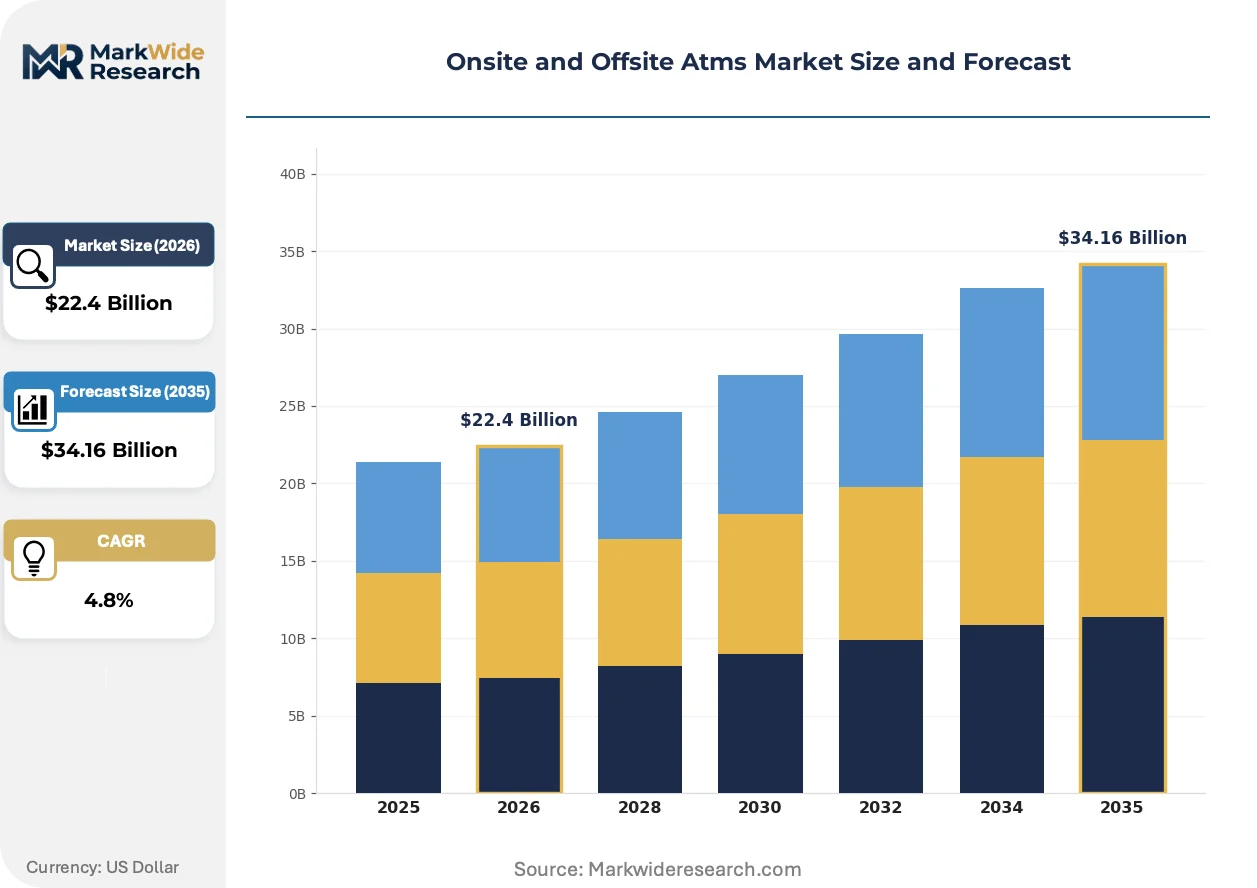
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $34.16 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Onsite, Offsite, Mobile, Drive-Through Technology: Card Reader, Contactless, Cash Recycling, Biometric Authentication, QR Code End User: Commercial Banks, Credit Unions, Payment Processors, Retail Chains, Hospitality Providers Service Type: Cash Withdrawal, Balance Enquiry, Fund Transfer, Bill Payment, Deposit Acceptance |
| Companies Covered | Diebold Nixdorf, NCR Atleos, Hitachi-Omron Terminal Solutions, GRG Banking Equipment, Triton Systems, Fujitsu, Wincor Nixdorf, Nautilus Hyosung, HESS Cash Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Onsite and Offsite Atms Market Trends and Innovations
Hardware architectures are converging around modular designs that separate cash-handling mechanics from digital authentication stacks, enabling field-upgradable security without full terminal replacement.
Biometric iris and palm-vein authentication is expanding into ATM networks as primary verification methods, replacing PIN entry in high-fraud markets. Nigerian and Saudi Arabian banks deploy these systems at pace to satisfy central bank anti-fraud mandates. The technology is expanding into premium service tiers that justify higher hardware costs through reduced card-replacement liability.
EU PSD2 strong-customer-authentication frameworks now mandate dynamic linking of transaction amount to authentication credentials. ATM manufacturers must embed cryptographic modules that generate transaction-specific signatures. German and Italian banks face the steepest compliance curves as they retrofit installed bases ahead of enforcement deadlines.
Retail chains now specify outcome-based service contracts that penalize downtime rather than paying fixed maintenance fees. Convenience store operators in India and Brazil lead this shift, unbundling hardware purchase from multi-year uptime guarantees. The model concentrates vendor risk while transferring operational accountability to manufacturers with regional spare-part inventories.
Onsite and Offsite Atms Market Segmentation
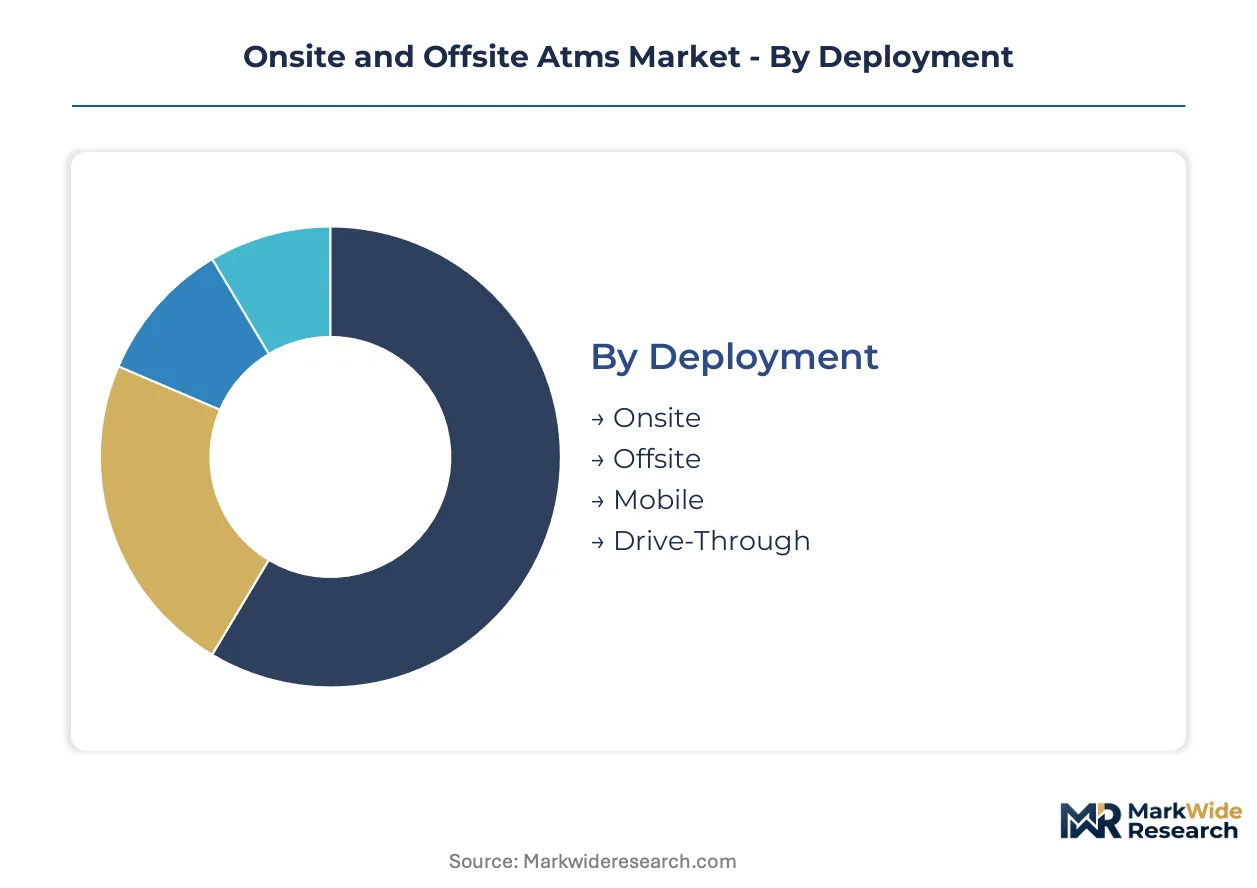
ATM manufacturers configure hardware specifications around deployment density, authentication protocols, and service monetization models. Segment boundaries determine component sourcing strategies and regional manufacturing footprints.
Deployment:
Buyers differentiate by real estate control, security overhead, and cash logistics complexity rather than transaction volume alone.
- Onsite:Branch-integrated terminals operate under direct bank security protocols with dedicated cash replenishment schedules. Indian public sector banks concentrate procurement here to satisfy RBI branch-mandate requirements while managing rural staffing costs.
- Offsite:Retail corridor and transit hub installations run on armored-car contracts and remote monitoring systems. Brazilian supermarket chains deploy these units to eliminate vault management overhead while capturing foot traffic revenue.
- Mobile:Vehicle-mounted terminals serve temporary event locations and disaster relief zones. These units trade durability for deployment flexibility.
- Drive-Through:Weather-hardened lanes with pneumatic tube systems dominate North American suburban banking. Unit costs run higher due to NEMA 4 environmental ratings.
Volume sits with Onsite; growth tilts toward Offsite.
Technology:
Hardware refresh decisions hinge on fraud exposure, certification timelines, and software-defined upgrade paths.
- Contactless:NFC-enabled tap-to-withdraw protocols reduce card-skimming attack surfaces while extending terminal lifecycles through over-the-air security patches. EU PSD2 strong-authentication mandates accelerate replacement of mag-stripe infrastructure.
- Biometric Authentication:Iris and palm-vein scanners satisfy central bank anti-fraud directives in Nigeria and Saudi Arabia. Premium service tiers justify hardware costs through reduced card-replacement liability.
- Card Reader:EMV chip-and-PIN modules remain baseline specifications for emerging market deployments. Certification delays constrain supplier selection.
- Cash Recycling:Deposit-to-withdrawal loop systems cut cash-in-transit frequency for high-volume retail locations. German postal banking networks prioritize these for labor cost reduction.
- QR Code:Camera-based transaction initiation bridges mobile wallet and physical cash access. Chinese payment processor specifications drive module integration.
Revenue concentrates in Card Reader; margin expansion tracks Biometric Authentication.
End User:
Procurement authority splits between regulated financial institutions and retail operators seeking operational cost reduction.
- Commercial Banks:Tier-1 institutions specify modular architectures with field-upgradable security stacks. RBI financial-inclusion mandates drive rural offsite procurement schedules.
- Retail Chains:Convenience store operators in India and Brazil unbundle hardware purchase from outcome-based uptime contracts. These buyers penalize downtime rather than paying fixed maintenance fees.
- Credit Unions:Member-owned institutions prioritize shared network interoperability over proprietary feature sets. Smaller deployment volumes limit supplier negotiation leverage.
- Payment Processors:Independent ATM deployers optimize for transaction revenue share and brand placement flexibility. These operators drive compact offsite form factor demand.
- Hospitality Providers:Hotel and casino operators specify foreign exchange and high-denomination cash handling for tourist corridors. Vietnam railway stations present unserved locations for these configurations.
Commercial Banks anchor procurement volume; Retail Chains are expanding most quickly.
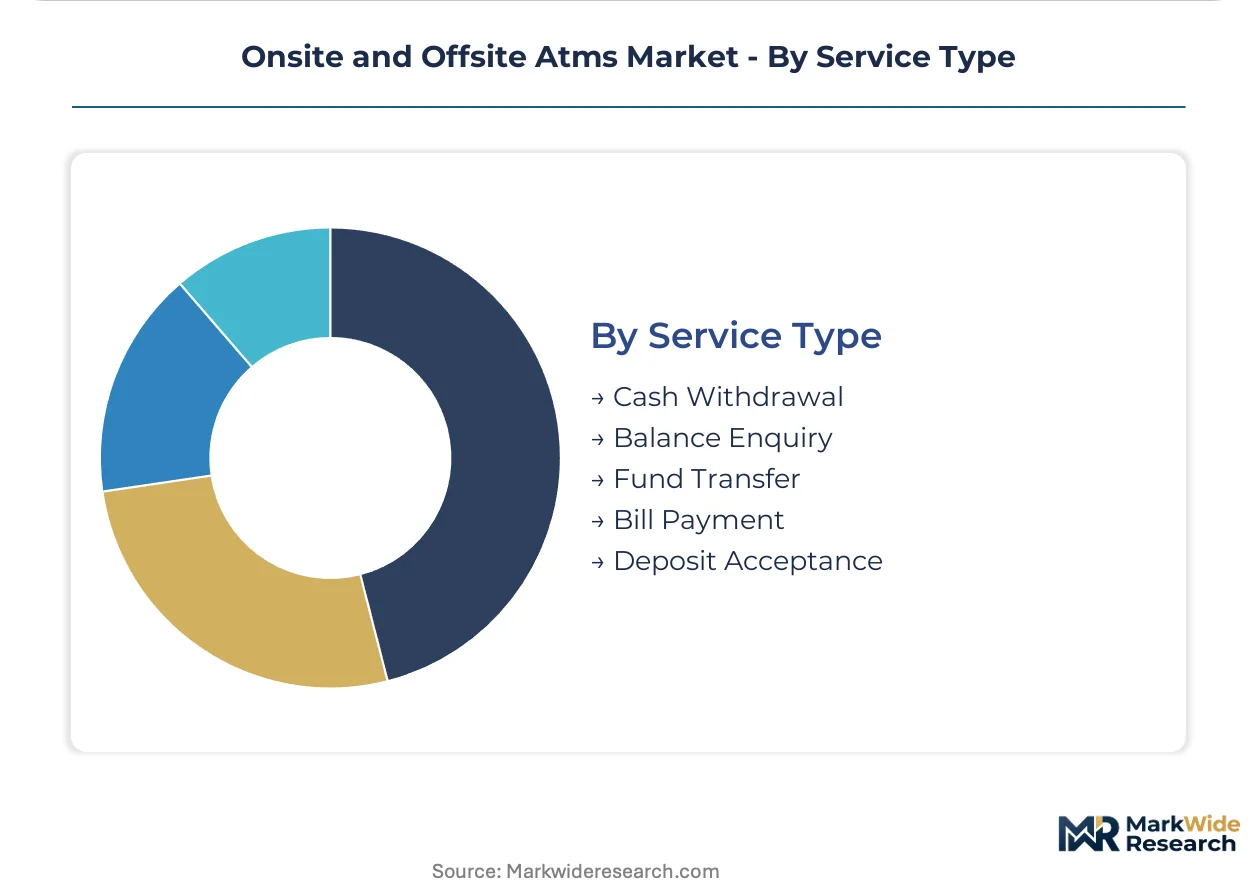
Service Type:
Transaction mix determines cash handling mechanics, vault sizing, and revenue per terminal.
- Cash Withdrawal:Core dispensing functionality with cassette-based denomination management. Mobile payment substitution in China and Kenya compresses transaction frequency per terminal.
- Deposit Acceptance:Envelope-free cash and check scanning with image capture for provisional credit. Cash recycling modules enable same-day fund availability.
- Balance Enquiry:Zero-revenue touchpoint that drives network traffic and cross-sell opportunities. Contactless migration reduces card wear costs.
- Fund Transfer:Interbank and cross-border remittance capabilities with dynamic currency conversion. CBDC pilot programs in Nigeria recast these as physical-digital bridges.
- Bill Payment:Utility and tax settlement with integrated receipt printing. Brazilian convenience stores leverage these to drive foot traffic.
Cash Withdrawal dominates transaction volume; Deposit Acceptance climbs fastest on cash recycling adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates hardware procurement through RBI-mandated rural financial inclusion programs. Brazil and Indonesia drive offsite deployment through retail cash-handling cost reduction. German and US markets focus on compliance-driven hardware refresh cycles.
India
Public sector banks expand offsite ATM footprints to satisfy RBI branch-mandate requirements in unbanked districts. The central bank's financial inclusion directives sustain procurement schedules from state-owned lenders. Mumbai and Delhi-NCR host deployment coordination centers for pan-India logistics.
Brazil
Supermarket and convenience store chains deploy offsite units to eliminate armored transport expenses and vault management overhead. The country's national banking regulator enforces biometric authentication standards for fraud reduction. São Paulo anchors manufacturing partnerships for Portuguese-language interface modules.
Germany
Postal banking networks prioritize cash recycling modules to reduce labor costs in high-volume retail locations. EU PSD2 strong-customer-authentication frameworks mandate cryptographic modules for transaction-specific signatures. Bavaria concentrates retrofit programs for 1990s-era terminal replacement.
United States
Drive-through lanes with pneumatic tube systems dominate suburban banking with weather-hardened NEMA 4 environmental ratings. The Federal Reserve's cash access policies shape hardware specifications for network interoperability. Texas and Florida lead deployment density for sunbelt population migration.
Indonesia
Retail corridor installations run on armored-car contracts and remote monitoring systems as banks reduce branch footprints. The central bank's payment system modernization directives accelerate contactless NFC migration. Jakarta and Surabaya concentrate procurement for archipelago-wide distribution logistics.
Onsite and Offsite Atms Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated hardware-software providers commanding premium positioning in developed markets while regional fabricators capture emerging market volume through cost-optimized chassis assemblies. The vendor base organizes around three archetypes: full-stack platform providers with captive service networks, component specialists focused on cash-handling mechanics, and white-label assemblers serving independent ATM deployers. Consolidation pressure intensifies as PCI DSS compliance mandates force smaller players toward partnership or exit. Geographic expansion and technology licensing represent the dominant competitive vectors.
Among North American integrated providers, Diebold Nixdorf and NCR Atleos exemplify the full-stack archetype through software-anchored service contracts that extend hardware lifecycles. GRG Banking Equipment occupies a position within the Asia-centric component specialist tier, leveraging region-specific manufacturing footprints for cash-handling module supply. These three entities represent contrasting strategic postures: North American platform integration, Asia-Pacific supply chain density, and service-contract monetization models.
| Leading Market Players |
|---|
| Diebold Nixdorf |
| NCR Atleos |
| Hitachi-Omron Terminal Solutions |
| GRG Banking Equipment |
| Triton Systems |
| Fujitsu |
| Wincor Nixdorf |
| Nautilus Hyosung |
| HESS Cash Systems |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up ATM service specialists have consolidated regional maintenance networks, compressing field-service pricing while locking component supply through multi-year chassis contracts with Asian fabricators. This ownership pattern concentrates procurement leverage among three integrated platforms, forcing smaller deployers into spot-market component purchases at 15-20% premiums.
Pricing Analysis
Volume concentrates in standard EMV card-reader configurations where Indian and Brazilian public-sector tenders drive pricing toward cost-plus structures; margin expansion sits with biometric-authentication tiers that command 40-60% hardware premiums through reduced fraud-liability value propositions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EU PSD2-compliant cryptographic modules carrying material uplifts over baseline mag-stripe replacements. Cost compression in standard-tier units is intensifying because semiconductor allocation delays force expedited component sourcing. Retail chains in emerging markets exhibit highest price sensitivity, while German postal banking networks prioritize total-cost-of-ownership metrics over unit acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea fabs that control 78% of industrial-grade processor supply for ATM controller boards, exposing manufacturers to allocation delays and spot-price volatility. Die-cast aluminum chassis assemblies draw from Chinese and Vietnamese metalworking clusters, while cash-handling mechanics hinge on precision-machined components from German and Japanese tool-and-die specialists. Tariff exposure runs through US-China component flows, particularly for recycled-aluminum enclosures subject to Section 301 duties. Distribution runs through regional integration centers in Mumbai, São Paulo, and Frankfurt that coordinate last-mile logistics to bank vaults and retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around PCI DSS compliance mandates that force smaller OEMs toward partnership or exit as certification costs escalate beyond $2 million per platform refresh.
For Market Incumbents: Hedge biometric-authentication commoditization by deepening software-integrated service contracts that transfer operational risk to manufacturers while capturing recurring revenue streams. Lock Taiwanese fab allocation through 36-month purchase commitments before spot-price volatility accelerates. Defend against white-label assemblers by controlling spare-part inventories in Indian and Brazilian regional hubs. For New Entrants and Emerging Players: Contactless NFC retrofit kits for 1990s-era terminals represent the most penetrable wedge, targeting German and French postal banking networks facing EU Green Deal replacement deadlines. Transit hub micro-branch networks in Vietnam and Mexico present unserved white space with foreign-exchange functionality gaps. Pursue outcome-based uptime contracts with Brazilian supermarket chains that penalize downtime rather than rewarding fixed maintenance fees. For Investors and Strategic Acquirers: RBI rural financial-inclusion directive acceleration is the leading indicator that Indian offsite deployment schedules will sustain hardware demand through public-sector bank procurement. The 5-10 year viability window favors integrated hardware-software platforms with captive service networks over component specialists facing margin compression. Target acquisition archetype: regional cash-handling module fabricators with BIS certification and existing GRG Banking Equipment supply relationships. Watch for central bank digital currency pilot expansions in Nigeria and Sweden as signals of terminal functionality pivot toward hybrid physical-digital bridges.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Module Integration | Iris and palm-vein authentication satisfies Nigerian and Saudi Arabian central bank anti-fraud mandates. |
| Contactless NFC Retrofit Programs | Tap-to-withdraw protocols extend terminal lifecycles through over-the-air security patches per EU PSD2. |
| Cash Recycling Module Deployment | Deposit-to-withdrawal loops cut armored-car frequency for German postal banking high-volume locations. |
| Regional Spare-Part Inventory Buildout | Mumbai and São Paulo hubs enable outcome-based uptime guarantees for Indian and Brazilian retail chains. |
| CBDC Hybrid Terminal Development | Pilot programs in Nigeria recast ATMs as physical-digital transaction bridges for currency conversion. |
Research Methodology
Document review covered SEC 10-K filings from Diebold Nixdorf and NCR Atleos, RBI financial-inclusion directive texts, EU PSD2 implementation guidelines, and Brazilian central bank biometric authentication standards, complemented by interviews with ATM OEM product managers, retail chain procurement directors, armored-car logistics operators, and core banking integration specialists. Secondary validation drew from customs trade data on ATM component flows, Taiwan Semiconductor Industry Association fab utilization reports, and Indian Banks' Association deployment statistics. Bottom-up terminal shipment estimates triangulated against top-down banking sector capex disclosures.
Installed base projections by deployment type, authentication protocol, and service monetization model across the analysis window fed into segment-specific ASP trajectories. CAGRs derived from polynomial trend fitting of historical procurement cycles adjusted for regulatory mandate enforcement timelines. Industry-specific forecast inputs included RBI branch-mandate saturation curves and EU Green Deal hardware retrofit subsidy allocation rates.
Several conditions sit outside the modeled scope, including central bank digital currency pilot program cancellations, Taiwan semiconductor export restriction escalations, and mobile payment substitution acceleration in sub-Saharan African markets. Deviation in PCI DSS compliance deadline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Bank Kiosk Market
Banking
Banking Credit Analytics Market
Banking
Credit Intermediation Market
Banking
APAC Banking-As-A-Service Market
Banking
Germany Neobanking Market
Banking
Cloud Computing Banking Market
Banking
Banking Smart Cards Market
Banking
Bank Guarantee Market
Banking
Global Big Data Analytics in Banking Market
Banking
Australia Neobanking Market
Banking
Europe Machine Learning in Banking Market
Banking
Contactless Smart Cards in Banking Sales Market
Banking
US Retail Banking Market
Banking
Video Banking Service Market
Banking
US Commercial Banking Market
Banking
Biometrics for Banking and Financial Services Market