
 Latin America Neo Banking Services Market | 2026-2036
Latin America Neo Banking Services Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Neo Banking Services Market Insights
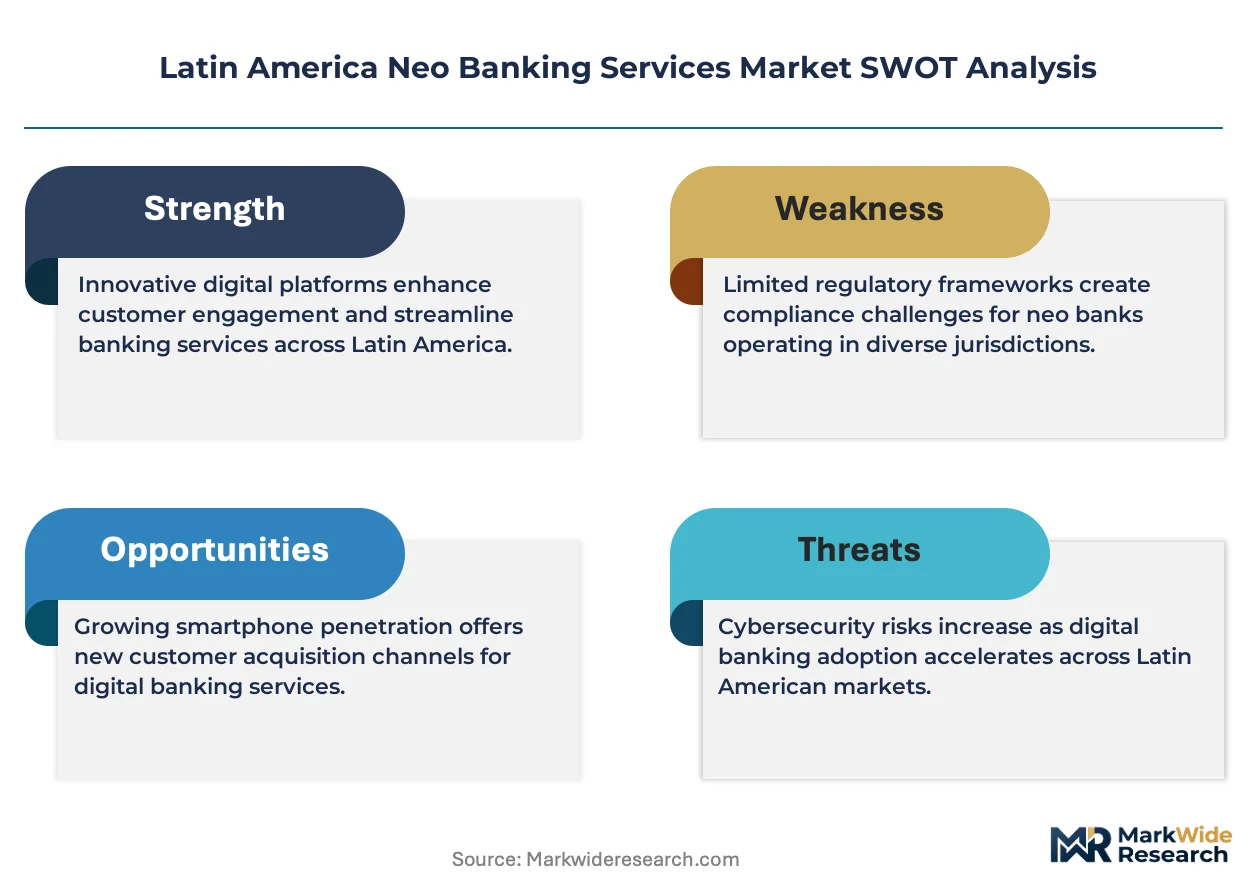
The gap between premium wealth-management tiers and basic transactional accounts is broadening across Latin American neo-banking. Nubank leverages its scale to dominate mass-market credit cards and savings products. Albo sustains a specialized position among freelancers seeking streamlined cross-border payments. Klar differentiates through salary-advance and buy-now-pay-later tools for Mexico's urban workforce.
Neo banking services encompass digitally native financial offerings delivered without physical branch infrastructure, relying on cloud-based core banking systems, real-time payment rails, and API-driven third-party integrations to execute deposits, transfers, lending, and investment functions. The primary commercial purpose is reducing customer acquisition costs while expanding financial inclusion for populations underserved by legacy banking networks. Digital wallet and peer-to-peer payment segments lead transaction volume but generate thinner margins, while investment services and credit solutions concentrate profitability through interest spreads and fee-based advisory. Mobile app platforms anchor user engagement, though hybrid solutions incorporating web portals capture small-business clients requiring multi-user dashboard access.
Brazil's Central Bank open banking mandates and Mexico's Fintech Law establish interoperability standards that shape product design and data-sharing protocols across the region. Argentina's national securities regulator and Chile's financial market commission impose capital requirements and consumer protection rules that filter market access for new entrants. Stakeholders must monitor how evolving central bank digital currency pilots and cross-border payment integration initiatives redraw competitive boundaries.
Market Dynamics
Open banking mandates across Brazil and Mexico are compressing interoperability timelines and forcing incumbent banks to expose customer data through standardized APIs. This regulatory pressure is reshaping product roadmaps and partnership strategies for digital-native challengers.
Growth Catalysts
- Pix instant payment rails:Brazil's Central Bank real-time settlement infrastructure has slashed transaction costs for peer-to-peer transfers. Micro-merchants now process payments without card network fees.
- Fintech Law data portability:Mexico's regulatory framework mandates customer data sharing between institutions. Challenger banks leverage this to accelerate onboarding and credit scoring accuracy.
- Smartphone penetration corridors:Urban concentration in São Paulo, Mexico City, and Bogotá creates dense addressable markets for app-only distribution models.
Market Restraints
- Core banking system concentration:Cloud infrastructure dependencies on AWS and Azure create single-point vulnerabilities for regional neo-banks.
- Foreign exchange volatility:Argentine peso and Colombian peso fluctuations erode deposit value and complicate cross-border treasury operations.
- Legacy correspondent banking:Dollar clearing access restrictions through US-regulated intermediaries limit international transfer capabilities.
Strategic Opportunities
- Central bank digital currency pilots:Brazil's Drex tokenized deposits initiative opens programmable money use cases for automated escrow and conditional payments.
- Cross-border remittance corridors:Mexico-US and Colombia-US payment flows remain underserved by low-cost digital channels.
- Embedded finance convergence:API partnerships with e-commerce platforms and gig-economy apps enable banking-as-a-service distribution.
Industry Challenges
- Cloud infrastructure talent scarcity:DevOps and cybersecurity specialists command premium compensation in São Paulo and Mexico City labor markets.
- Biometric authentication standardization:Fragmented facial recognition and liveness detection protocols across national regulators complicate pan-regional platform deployment.
- Legacy core migration friction:Institutions attempting hybrid architectures face data synchronization failures between cloud-native and on-premise systems.
Report Scope
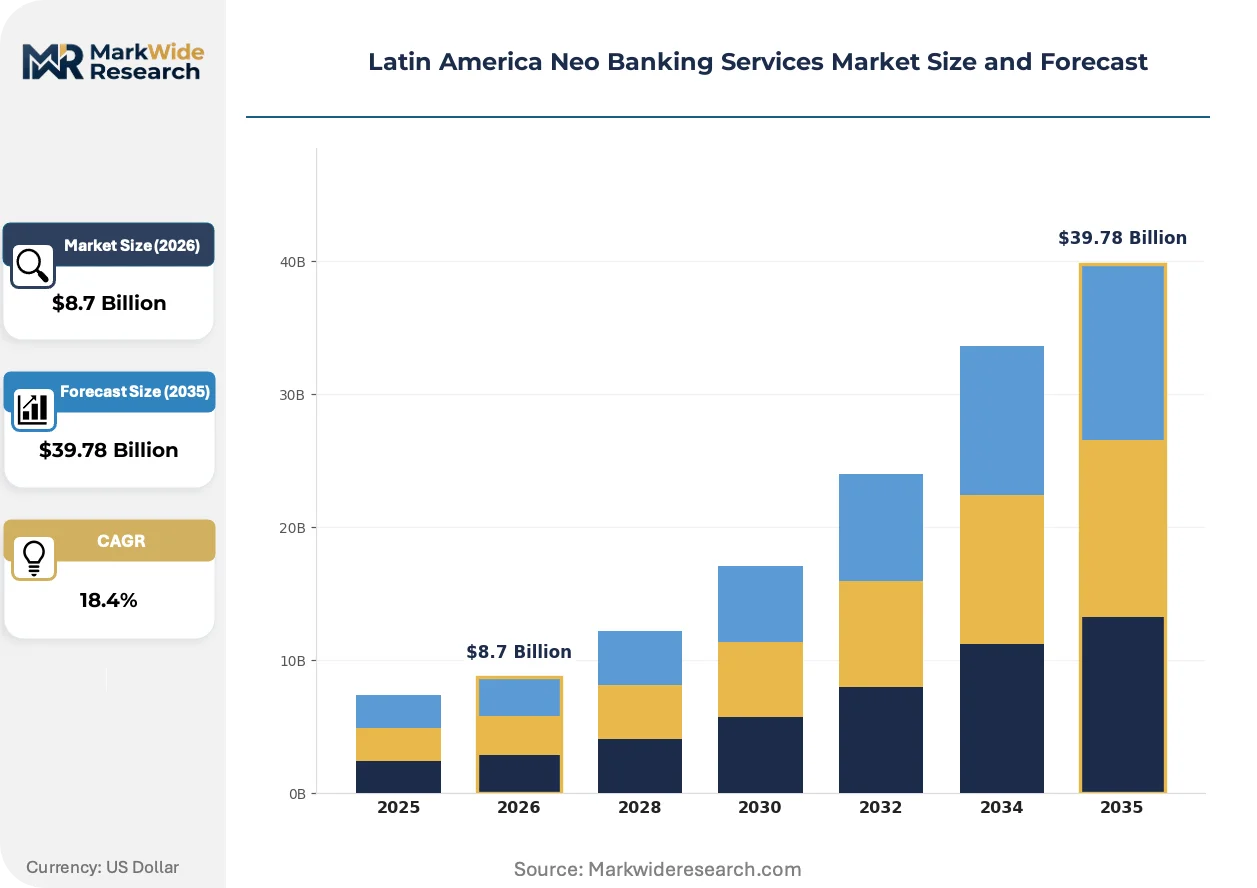
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Neo Banking Services Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Digital Wallet, Peer-to-Peer Payments, Investment Services, Credit Solutions Target Customers: Small Businesses, Freelancers, Millennials, Unbanked Individuals Platform: Mobile App, Web Portal, Hybrid Solutions, APIs Payment Method: Bank Transfer, Credit Card, Cryptocurrency, QR Code |
| Companies Covered | Nubank, Uala, Albo, Banco Original, Klar, Neon, RappiPay, Banco Inter, Mercado Pago, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Neo Banking Services Market Trends and Innovations
Real-time payment infrastructure and embedded finance architectures are compressing the boundary between banking services and non-financial platforms. These shifts favor technology-forward challengers over branch-dependent incumbents.
Banking-as-a-Service middleware is unifying core ledger functions, KYC orchestration, and compliance engines into single API layers. E-commerce marketplaces and payroll software vendors embed these stacks to offer branded accounts and cards. This unification collapses time-to-market for non-bank financial products from years to months.
Brazil's Central Bank open finance roadmap mandates graduated data-sharing phases through 2025. Phase four requirements will force transactional data reciprocity between neo-banks and incumbents. Credit underwriting models across the sector will incorporate rent, utility, and telecom payment histories previously invisible to traditional scoring.
Freelancers and informal workers are consolidating financial activity into single-platform dashboards. Neo-banks respond by bundling invoicing, tax withholding, and multi-currency receipts. Mexico's contingent workforce segment exhibits the strongest concentration of this behavior, with platform switching costs rising as embedded service depth increases.
Latin America Neo Banking Services Market Segmentation
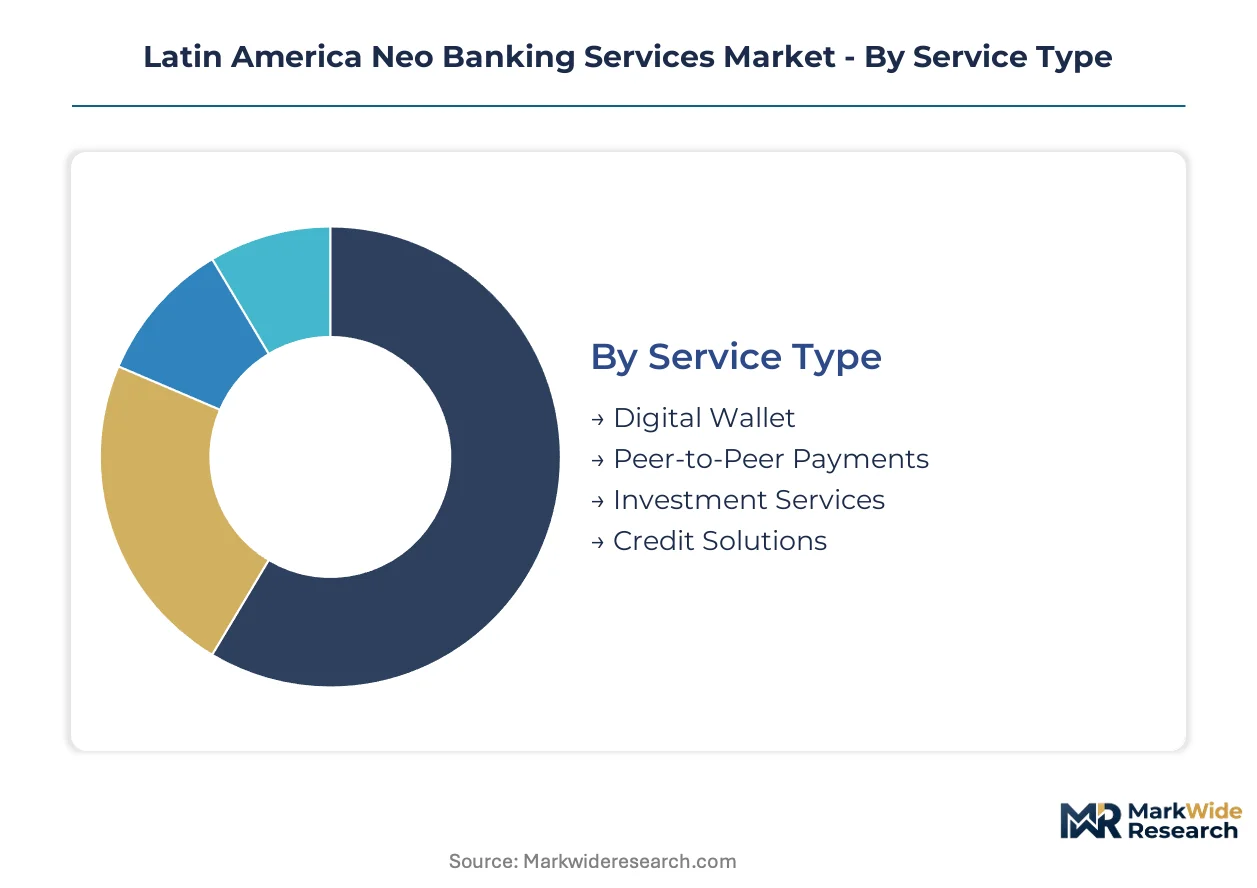
Neo-banking service segmentation in Latin America reflects divergent monetization models and infrastructure requirements. Platform architecture and customer acquisition economics vary dramatically across service types and target demographics.
Service Type:
Customer willingness to pay determines service prioritization on product roadmaps.
- Digital Wallet:Cloud-native storage of fiat and tokenized balances enables instant settlement through Pix and SPEI rails. Brazil's metropolitan corridors concentrate demand, driven by micro-merchant adoption seeking zero-acquirer-fee alternatives to card networks.
- Credit Solutions:Algorithmic underwriting of unsecured personal and working-capital loans generates interest spread revenue. Mexico's urban workforce clusters show strongest uptake, propelled by salary-advance products addressing cash-flow timing gaps.
- Peer-to-Peer Payments:Real-time transfers between individual accounts leverage open banking APIs for instant settlement.
- Investment Services:Fractional equity and fixed-income products embedded within transactional platforms.
Volume sits with Digital Wallet; growth tilts toward Credit Solutions.
Target Customers:
Regulatory compliance intensity scales with customer formalization status.
- Small Businesses:Multi-user account structures with invoicing, tax withholding, and payroll integration. São Paulo and Mexico City corridors show densest concentration, driven by platform switching costs rising with embedded service depth.
- Unbanked Individuals:Simplified KYC tiers using biometric authentication and alternative data scoring. Colombia's peripheral urban zones exhibit strongest demand concentration, propelled by legacy branch network gaps in lower-income districts.
- Freelancers:Cross-border payment corridors with multi-currency receipt and tax automation.
- Millennials:Mobile-native engagement with gamified savings and investment features.
Transaction volume concentrates among Small Businesses; steepest expansion trajectory emerges from Unbanked Individuals.
Platform:
Development cost structures and time-to-market differentiate deployment choices.
- Mobile App:Native iOS and Android applications anchor user engagement through push notifications and biometric login. Brazil leads deployment density, driven by smartphone-first population segments and Pix instant payment integration.
- Hybrid Solutions:Synchronized mobile and web interfaces serving multi-stakeholder business accounts. Mexico's small-business segment shows strongest adoption, propelled by finance-team requirements for dashboard access and approval workflows.
- Web Portal:Browser-based platforms for enterprise treasury and accounting integrations.
- APIs:Headless banking infrastructure embedded within third-party applications.
User engagement centers on Mobile App; revenue per customer climbs fastest through Hybrid Solutions.
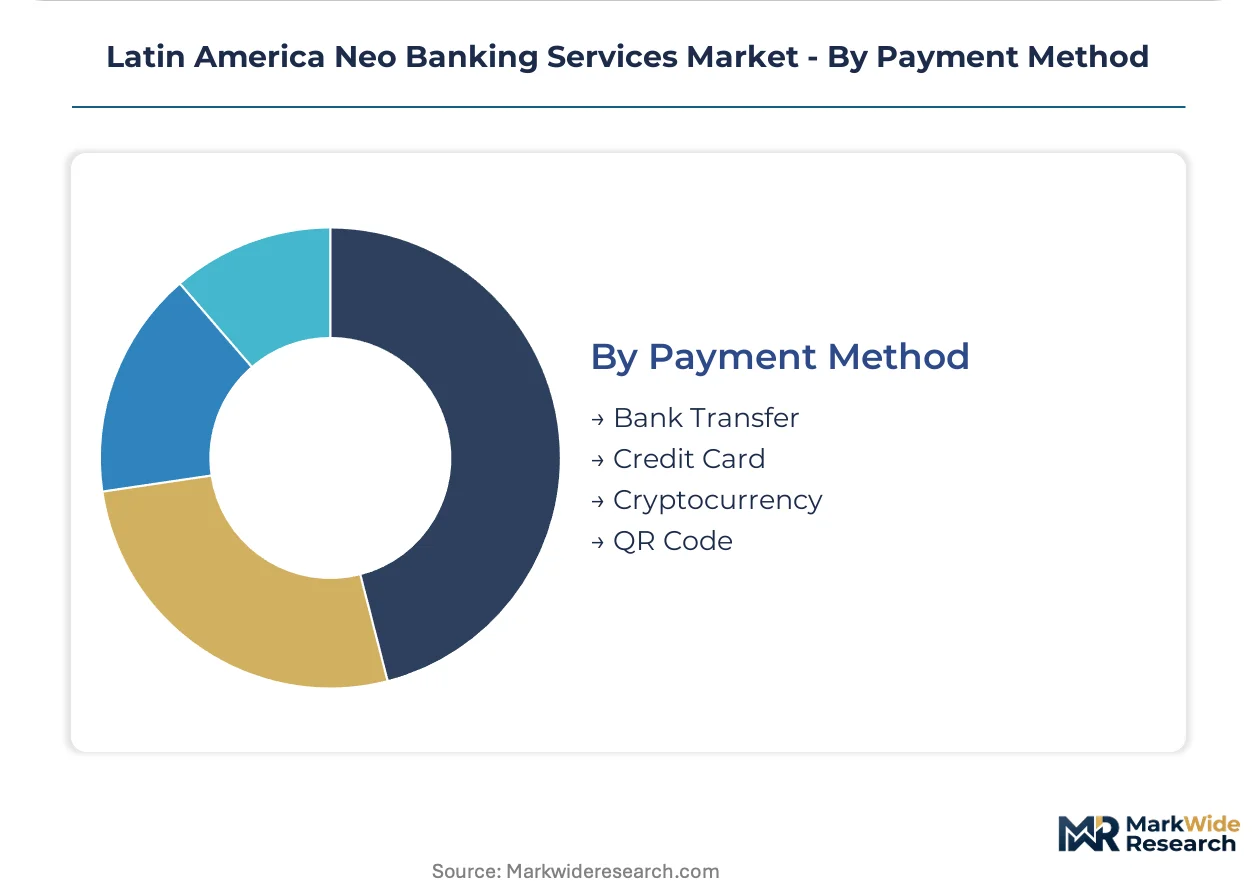
Payment Method:
Settlement speed and cost structure determine merchant preference hierarchies.
- QR Code:Pix-powered static and dynamic codes eliminate interchange fees for micro-merchants. Brazil's street commerce and informal retail corridors concentrate demand, driven by Central Bank real-time settlement infrastructure.
- Bank Transfer:Account-to-account rails through SPEI, TEF, and PSE systems. Colombia and Mexico urban centers show densest usage, propelled by payroll and supplier payment automation in formal enterprises.
- Credit Card:Card-not-present and tokenized in-app transactions.
- Cryptocurrency:Stablecoin and tokenized settlement for cross-border remittance.
Transaction frequency peaks with QR Code; average ticket size runs highest through Bank Transfer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's metropolitan corridor concentrates Latin American neo-banking activity, hosting the densest cluster of digital-native financial institutions and venture capital deployment. Brazil's Central Bank regulatory leadership through Pix instant settlement infrastructure establishes the regional template for real-time payment adoption.
Brazil
Pix instant payment rails and open banking mandates drive mass-market financial inclusion across Brazil's urban centers. Brazil's Central Bank enforces graduated data-sharing phases through 2025, forcing transactional reciprocity between neo-banks and incumbents. São Paulo anchors deployment density, with micro-merchants adopting QR code payments to eliminate card network fees.
Mexico
Salary-advance products and cross-border payment corridors attract Mexico's urban workforce and freelancer segments. Mexico's Fintech Law mandates customer data portability between institutions, accelerating onboarding velocity for challengers. Mexico City concentrates platform adoption, driven by finance-team requirements for multi-user dashboard access in small businesses.
Argentina
Currency volatility and informal labor markets create demand for dollar-denominated savings and multi-currency receipts. Argentina's national securities regulator imposes capital requirements that filter market access for new entrants. Buenos Aires exhibits strongest demand concentration among freelancers consolidating invoicing, tax withholding, and cross-border payment activity into single-platform dashboards.
Colombia
Legacy branch network gaps in lower-income districts propel unbanked individual adoption of simplified KYC tiers. Colombia's financial market commission establishes consumer protection rules shaping biometric authentication and alternative data scoring protocols. Bogotá's peripheral urban zones show densest demand concentration, driven by smartphone-first population segments seeking zero-branch financial access.
Chile
Fractional investment products and embedded finance partnerships attract Chile's formally employed millennials. Chile's financial market commission imposes capital requirements and operational standards for digital-native entrants. Santiago's metropolitan corridor concentrates adoption of mobile-native engagement with gamified savings features and real-time portfolio tracking.
Latin America Neo Banking Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across credit underwriting sophistication and customer lifetime value metrics. The market structure exhibits tiered consolidation, with scale-driven challengers dominating mass-market segments while specialized operators capture niche verticals. Three archetypes prevail: full-stack digital banks owning core banking infrastructure, wallet-first platforms monetizing through payment float, and embedded finance providers distributing through third-party ecosystems. Dominant competitive moves include strategic partnerships with e-commerce marketplaces and API-based banking-as-a-service licensing.
Among Brazil-based digital-native institutions, Nubank and Banco Inter exemplify the scale-driven full-stack archetype, while Mexico-based Klar occupies a specialized position within the salary-advance and buy-now-pay-later segment. These entities anchor regional competitive dynamics through divergent monetization models: mass-market credit card interest spreads versus targeted working-capital solutions.
| Leading Market Players |
|---|
| Nubank |
| Uala |
| Albo |
| Banco Original |
| Klar |
| Neon |
| RappiPay |
| Banco Inter |
| Mercado Pago |
| Others |
Pricing and Supply Chain Analysis
Cloud-native core banking migrations are compressing infrastructure costs while concentrating vendor power among hyperscale providers, simultaneously reshaping unit economics and supply dependencies across Latin American neo-banking. This technological shift feeds directly into pricing architectures and procurement vulnerabilities that define competitive positioning.
Pricing Analysis
Transaction volume-based pricing anchors revenue models, with fees scaling to payment throughput and account activity levels. Price differentiation hinges on API call volume tiers and embedded service depth, with premium tiers commanding spreads for real-time settlement and advanced analytics. Pricing pressure stems from Pix instant payment rails eliminating interchange revenue for basic transfers. Micro-merchants exhibit highest price sensitivity; enterprise treasury clients show lowest.
Supply Chain Analysis
Regional data center distribution in São Paulo, Mexico City, and Bogotá shapes latency-sensitive service delivery for core banking workloads. Cloud infrastructure draws from AWS, Azure, and Google Cloud regions, with biometric authentication SDKs and payment rail gateways as critical software inputs. Single-source vulnerability concentrates in core banking system providers. Distribution runs through API-first partnerships with e-commerce and payroll platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proprietary payment rails and captive data infrastructure is accelerating as challengers seek margin control and regulatory autonomy. Players are pursuing upstream leverage through direct central bank connectivity and downstream control via embedded finance distribution.
For Market Incumbents: To counter Nubank's scale-driven customer acquisition cost advantages, legacy institutions must accelerate open banking API reciprocity and invest in modular core banking replacements. Defensive consolidation through acquisition of specialized credit-scoring fintechs in Mexico and Brazil preserves underwriting sophistication. Channel control through exclusive payroll distribution partnerships anchors retention.
For New Entrants and Emerging Players: Informal workers in Colombia's peripheral urban zones represent the most penetrable buyer archetype, with legacy branch gaps creating immediate addressable demand. White-space targets include dollar-denominated savings for Argentine freelancers and automated tax withholding for Mexico's contingent workforce. Go-to-market execution should prioritize gig-economy platform embeds over direct consumer acquisition.
For Investors and Strategic Acquirers: Exit pathways concentrate in full-stack digital bank acquisitions by regional incumbents and global fintech platforms. Long-term viability favors entities with proprietary payment rail access and diversified revenue beyond interchange. The signal to watch is central bank digital currency pilot participation as an inflection indicator for programmable money readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Pix Instant Payment Integration | Brazil's Central Bank rails eliminate card network dependencies for micro-merchant settlement. |
| Open Banking API Reciprocity | Phase four mandates force transactional data sharing between neo-banks and incumbents. |
| Embedded Finance Partnership | E-commerce marketplace integrations collapse customer acquisition costs through contextual distribution. |
| Proprietary Core Banking Migration | Cloud-native ledger systems reduce vendor lock-in to AWS and Azure infrastructure. |
| Cross-Border Remittance Corridor | Colombia-US and Mexico-US payment flows remain underserved by low-cost digital channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with neo-bank product executives, central bank fintech liaison officers, and payroll platform integration specialists combined with secondary validation from Brazil's Central Bank open finance disclosures, Mexico's CNBV fintech registry data, and SPEI transaction volume reports. Bottom-up service-type segmentation and top-down macroeconomic sizing were triangulated to derive market estimates.
Data-stream reconciliation across payment rail transaction volumes, account origination filings, and venture capital deployment patterns informed the analytical framework. Segmentation dimensions modeled include service type, target customer formalization status, platform deployment architecture, and payment settlement method across the analysis window. CAGRs were derived from fitted growth curves incorporating smartphone penetration trajectories and regulatory phase-in timelines. Industry-specific inputs included Pix adoption velocity and Fintech Law implementation progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to central bank digital currency issuance timelines and correspondent banking access restrictions. Outputs reflect documented assumptions regarding open banking phase adherence and cloud infrastructure cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Global Retail Core Banking Systems Market
Banking
Merchant Banking Services Market
Banking
Investment Banking and Trading Services Market
Banking
Australia Neobanking Market
Banking
Core Banking Solutions Market
Banking
Digital Banking Market
Banking
North America Data Analytics in Banking Market
Banking
UK Banking as a Service Market
Banking
Latin America Banking As a Service Market
Banking
Armenia Banking Market
Banking
United Kingdom Data Analytics in Banking Market
Banking
Russia Data Analytics in Banking Market
Banking
Disaster Recovery in Banking Market
Banking
Embedded Banking Market
Banking
Retail Banking Market
Banking
Europe Data Analytics in Banking Market