
 Global Continuous Integration Tools Market | 2026-2036
Global Continuous Integration Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Continuous Integration Tools Market Intelligence
The shift toward AI-powered pipeline optimization is redrawing the boundaries of conventional build and test automation. Microsoft Corporation leverages its Azure DevOps platform to offer deeply integrated solutions for enterprise clients. Atlassian Corporation Plc sustains its market presence through the extensive plugin ecosystem for its Bamboo and Bitbucket products. GitLab Inc competes with a single-application approach that covers the entire modern DevOps lifecycle.
Continuous integration tools automate the process of merging developer code changes into a central software repository. These platforms execute automated builds and unit tests, often triggered by every code commit, to detect integration errors quickly. Cloud-based deployment models now dominate new installations due to their scalability and reduced infrastructure management overhead. While open-source solutions command a large user base, commercial SaaS platforms represent the fastest-growing revenue stream.
Software supply chain security mandates, influenced by frameworks from the US National Institute of Standards and Technology (NIST), compel organizations to adopt tools with greater transparency. In parallel, Europe's GDPR requirements push for development practices that ensure data privacy by design. Vendors and end users must now prioritize toolchains that provide verifiable build provenance and robust, integrated security scanning capabilities.
Market Dynamics
The imperative for verifiable software supply chain security is the central force shaping the continuous integration tools market. This pressure, originating from both regulatory mandates and enterprise risk management policies, compels organizations to abandon opaque build processes in favor of auditable, transparent, and secure CI pipelines.
Growth Catalysts
- DevSecOps Adoption:The industry-wide pivot to DevSecOps integrates security testing directly into the CI pipeline, requiring tools that can automate security scans, policy enforcement, and compliance checks on every code commit.
- Cloud-Native Development:Proliferation of containerization with Docker and orchestration with Kubernetes creates demand for CI tools that natively support building, testing, and deploying microservices in cloud environments.
- Regulatory Compliance:Mandates like the US NIST Secure Software Development Framework (SSDF) and Europe's GDPR necessitate CI/CD pipelines that provide auditable logs and ensure data privacy by design.
Market Restraints
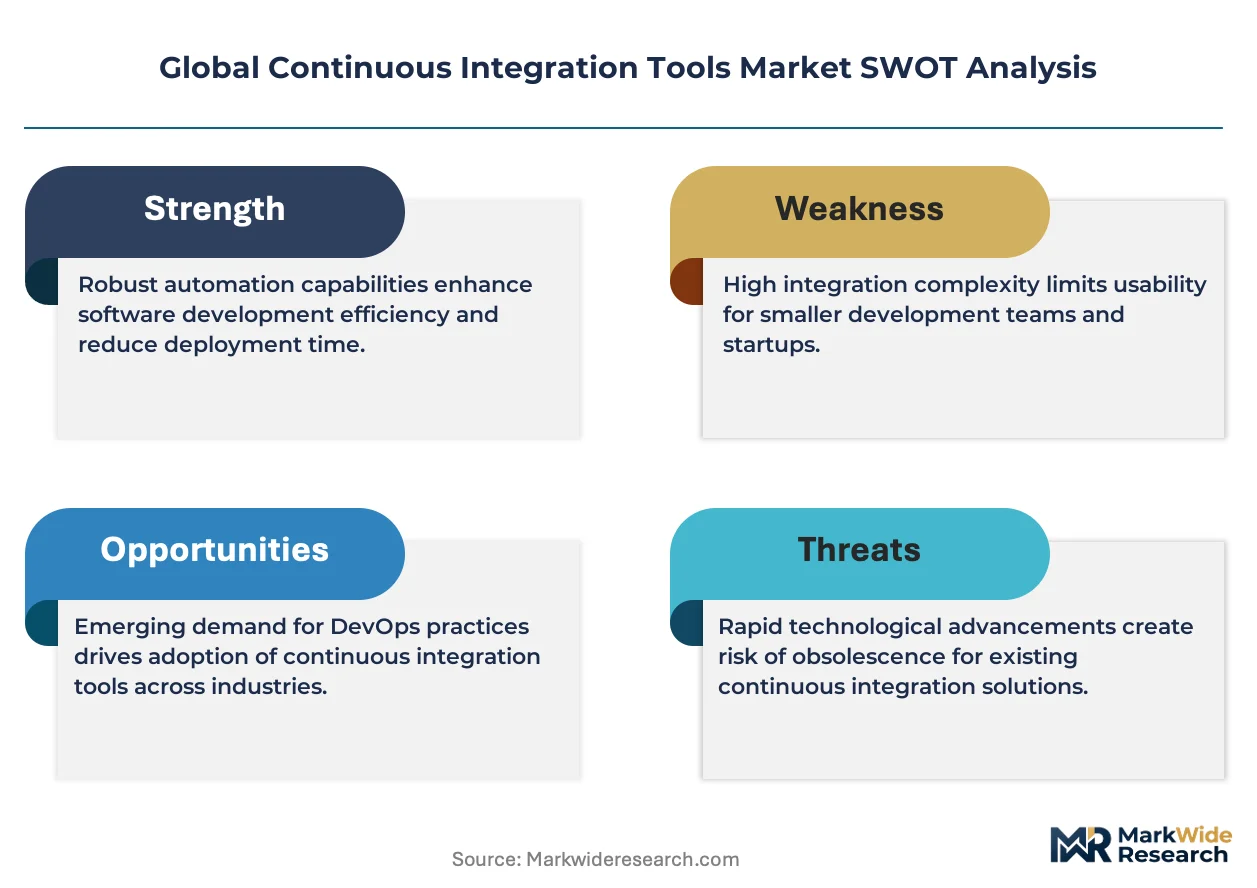
- Integration Complexity:Significant technical challenges exist in integrating diverse open-source and commercial tools for security scanning, testing, and artifact management into a cohesive, functional CI/CD pipeline.
- Legacy System Inertia:Large enterprises with substantial investments in monolithic applications and legacy infrastructure face high costs and operational friction when migrating to modern, cloud-native CI workflows.
- Open-Source Management Overhead:While open-source tools like Jenkins offer flexibility, they require significant in-house expertise to configure, secure, and maintain, creating a high total cost of ownership for many organizations.
Strategic Opportunities
- CI for AI and MLOps:A nascent opportunity exists in providing specialized CI tools for machine learning workflows (MLOps), addressing unique needs like data versioning, model training validation, and experiment tracking.
- Emerging Market Modernization:Technology sectors in India and Brazil are rapidly modernizing, creating greenfield opportunities for cloud-based CI platform adoption without the burden of legacy system migration.
- Vertical-Specific Solutions:Developing CI toolchains pre-configured for compliance with industry-specific regulations, such as HIPAA for healthcare or PCI DSS for finance, offers a path to market differentiation.
Industry Challenges
- DevOps Talent Scarcity:A persistent shortage of skilled DevOps and platform engineers who can design, build, and maintain sophisticated, automated CI/CD infrastructure limits the pace of adoption for advanced tooling.
- Toolchain Sprawl:Organizations often accumulate a complex and fragmented set of CI and CD tools, leading to duplicated effort, inconsistent security practices, and increased maintenance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Continuous Integration Tools Market |
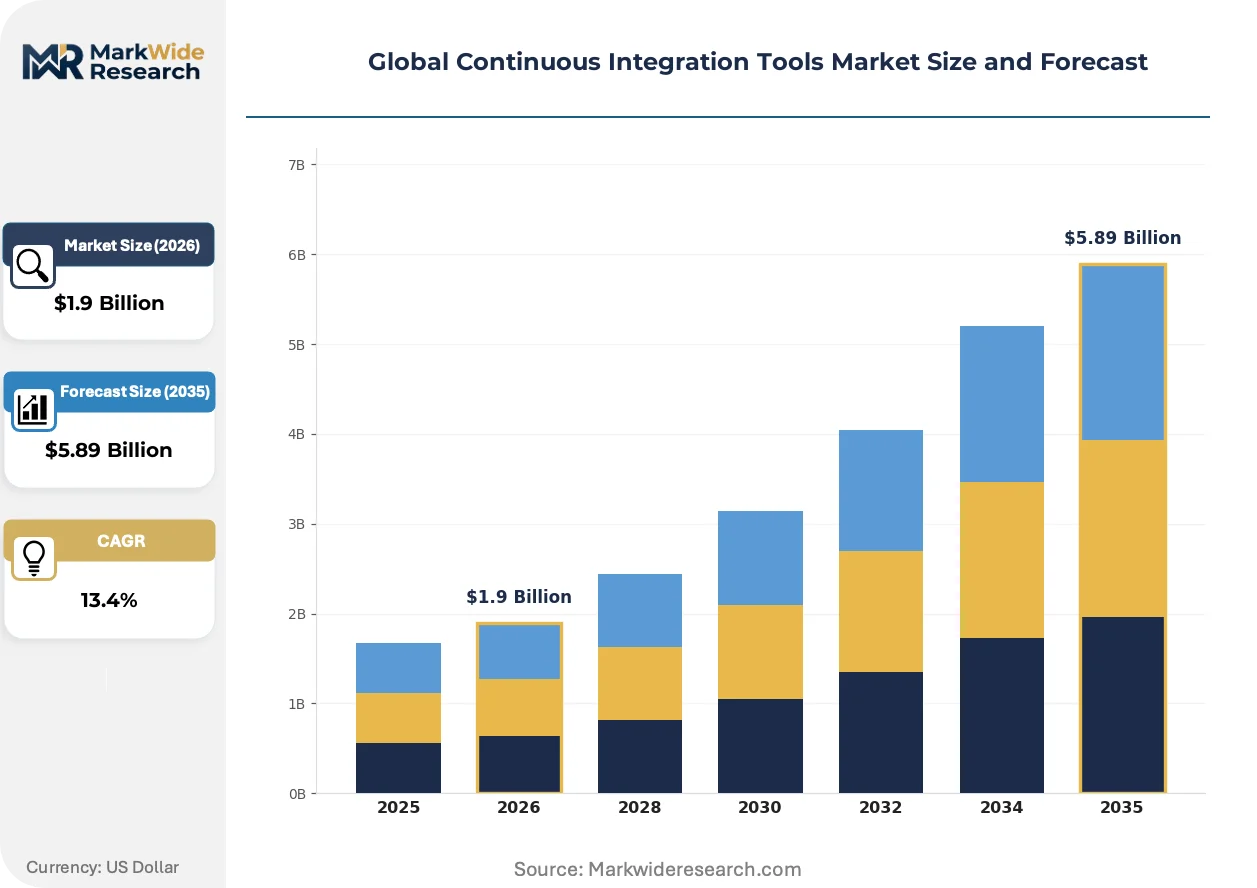
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Mode: Cloud-Based, On-Premises, Hybrid, Containerized, Edge Computing Tool Type: Open Source, Commercial, Enterprise, SaaS, Self-Hosted Application: Software Development, Quality Assurance, Automation Testing, DevOps Integration, Release Management End User: IT Service Providers, Software Vendors, System Integrators, Digital Agencies, Technology Startups |
| Companies Covered | Atlassian Corporation Plc, CircleCI Inc, Microsoft Corporation, Oracle Corporation, CloudBees Inc, Amazon Web Services Inc, GitLab Inc, JetBrains s.r.o, International Business Machines Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Continuous Integration Tools Market Strategic Shifts & Innovations
Automation of the automation process itself defines the current competitive frontier. Intelligence is being embedded into the toolchain to optimize pipelines, while security shifts from a separate stage to an intrinsic, code-defined attribute of the development lifecycle, driven by new regulatory pressures.
AI-powered pipeline intelligence analyzes build histories and test outcomes to predict failures and optimize resource usage. Enterprise software teams adopt this capability to shorten developer feedback cycles and reduce cloud compute expenditures. This intelligent automation is decomposing the monolithic, manually-configured CI pipeline into a dynamic, self-optimizing system that allocates resources based on real-time analysis of code changes.
Software supply chain security mandates, influenced by frameworks from the US National Institute of Standards and Technology, compel organizations to adopt tools with greater transparency. This requirement, particularly for generating a Software Bill of Materials (SBOM), forces vendors to embed provenance tracking and vulnerability reporting directly within the build process. The government and defense sectors are most affected, driving investment in auditable CI platforms.
Enterprise procurement models are consolidating around single-vendor DevOps platforms over portfolios of single-point solutions. This buyer behavior simplifies vendor management and ensures tighter integration across the software development lifecycle, from planning to monitoring. This trend is most visible within large, regulated industries like financial services and telecommunications, where toolchain standardization is a key architectural goal.
Global Continuous Integration Tools Market Segmentation
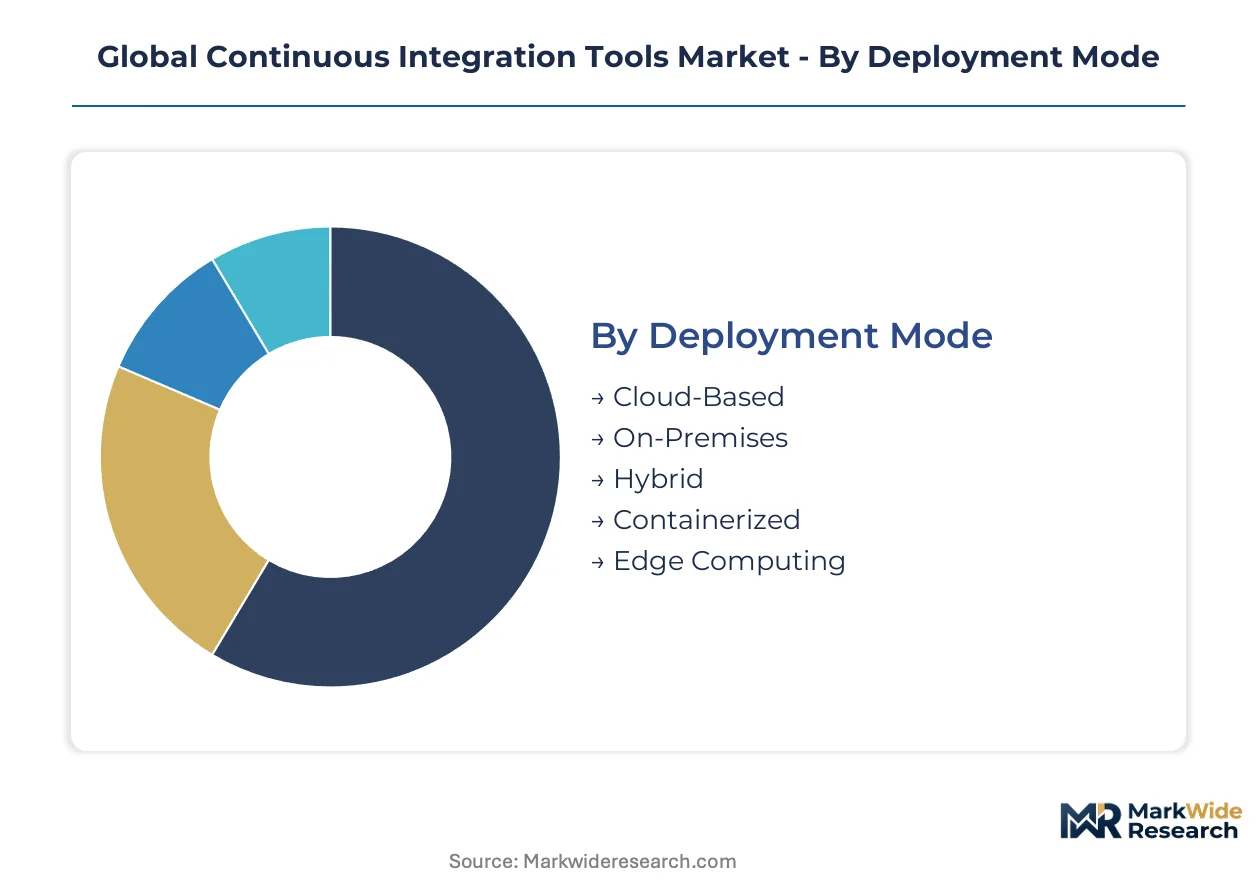
The continuous integration tools market is segmented to reveal distinct value propositions and adoption patterns across diverse operational environments and user needs. Understanding these distinctions helps vendors tailor their offerings and allows enterprises to select solutions that align with their specific development workflows and infrastructure strategies.
Deployment Mode:
Margin pools within the deployment mode category often concentrate around the operational efficiencies and managed services associated with cloud-native offerings.
- Cloud-Based:These platforms are hosted and managed by a third-party provider, offering high scalability, reduced infrastructure overhead, and pay-as-you-go pricing models. Demand concentrates in technology startups and mid-sized enterprises seeking rapid deployment and minimal operational burden.
- Containerized:CI tools delivered as Docker containers or orchestrated with Kubernetes provide environment consistency and portability across various cloud and on-premises infrastructures. The proliferation of microservices architectures drives demand for these flexible deployment options.
- On-Premises:Solutions installed and managed directly within an organization's private data center provide maximum control over data security and compliance.
- Hybrid:This model combines elements of both on-premises and cloud deployments, allowing organizations to leverage existing infrastructure while selectively utilizing cloud resources.
- Edge Computing:CI tools deployed closer to data sources at the network edge support low-latency requirements for specific IoT and real-time processing applications.
The dominant share belongs to Cloud-Based solutions, while Containerized deployments are closing the gap fastest.
Tool Type:
Procurement patterns for continuous integration tools frequently diverge based on an organization's existing technology stack and internal resource capabilities.
- SaaS:Software-as-a-Service CI platforms offer fully managed services, eliminating the need for installation, maintenance, and upgrades by the end-user. This model represents the fastest-growing revenue stream due to its convenience and scalability.
- Open Source:These tools, such as Jenkins, provide source code access for customization and benefit from large community support, appealing to organizations with in-house technical expertise. Open-source solutions maintain a substantial user base, particularly in smaller development teams.
- Commercial:Proprietary software licenses for CI tools offer dedicated vendor support, guaranteed service level agreements, and often more integrated feature sets.
- Enterprise:Tailored CI solutions designed for large organizations typically include advanced security features, extensive compliance reporting, and deep integration with existing enterprise systems.
- Self-Hosted:Organizations deploy and manage these tools on their own servers, providing complete control over the environment and data.
SaaS platforms are showing significant momentum, while open-source tools continue to hold a substantial market presence.
Application:
Demand concentration within the application category highlights the critical role CI tools play across the entire software development lifecycle.
- DevOps Integration:CI tools are foundational to DevOps workflows, automating the merging, building, and testing of code to streamline the software delivery pipeline. The industry-wide pivot to DevSecOps integrates security testing directly into these pipelines.
- Automation Testing:These applications focus on automatically executing various tests, including unit, integration, and functional tests, immediately after code commits. This rapid feedback loop detects integration errors quickly, improving code quality.
- Software Development:Core CI functionalities support developers by automating repetitive tasks, ensuring code consistency, and facilitating collaborative coding efforts.
- Quality Assurance:CI tools enable continuous quality checks throughout the development process, reducing the time and cost associated with late-stage defect detection.
- Release Management:Integrating CI with release management systems automates the deployment of tested code to various environments, from staging to production.
DevOps Integration applications command the largest share, with Automation Testing demonstrating rapid expansion.
End User:
The maturity of CI tool adoption varies significantly among different end-user segments, reflecting diverse operational scales and technical capabilities.
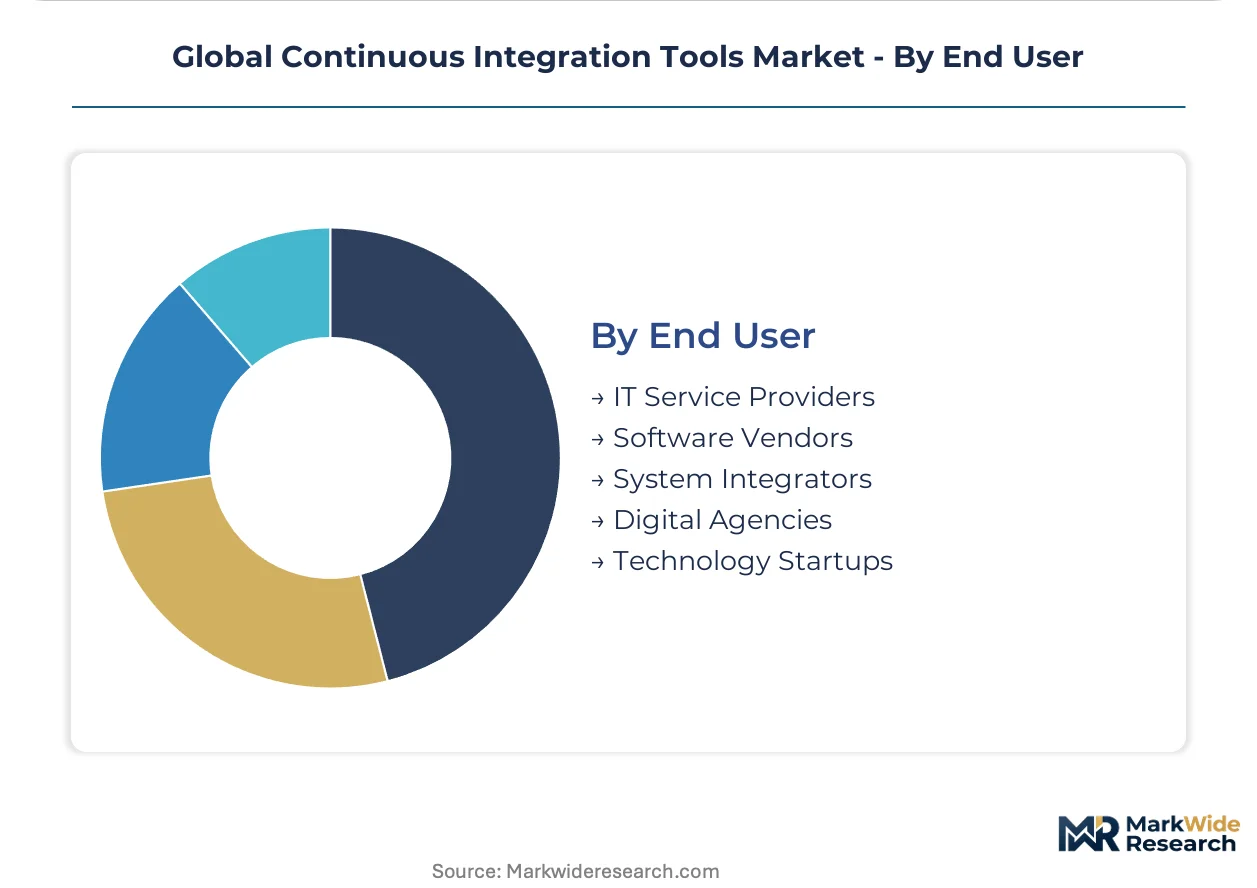
- Software Vendors:Companies primarily engaged in creating and selling software products extensively use CI tools to accelerate their product development cycles and maintain high code quality. These vendors often require sophisticated, auditable tooling for their commercial offerings.
- IT Service Providers:Organizations offering IT consulting, managed services, and custom software development leverage CI tools to deliver efficient and reliable solutions to their clients. Their demand often spans across various deployment models.
- System Integrators:These firms specialize in combining disparate computing systems and software applications, relying on CI tools to ensure seamless integration and functionality.
- Digital Agencies:Agencies focused on web development, mobile app creation, and digital marketing use CI to manage multiple client projects, ensuring consistent delivery and quality.
- Technology Startups:New companies in the technology sector often adopt cloud-native CI solutions to achieve agility, rapid iteration, and cost-effectiveness in their product development.
Software Vendors represent a mature segment, while Technology Startups exhibit the steepest expansion trajectory in CI tool adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global continuous integration tools market exhibits a nuanced demand landscape, with major technology hubs driving both development and consumption. Software supply chain security mandates are reshaping procurement decisions across various geographies. Enterprises prioritize tools offering verifiable build provenance and integrated security scanning capabilities.
United States
Demand for continuous integration tools in the United States is propelled by extensive software vendor activity and a thriving technology startup ecosystem. The NIST Secure Software Development Framework (SSDF) compels organizations to adopt auditable CI/CD pipelines. Silicon Valley and Austin, Texas, see intense competition among vendors offering advanced AI-powered pipeline optimization.
Germany
German enterprises increasingly adopt continuous integration tools to support advanced manufacturing and automotive software development. Europe's GDPR requirements influence tool selection, emphasizing data privacy by design in development practices. Munich and Berlin are centers for cloud-native development, fostering demand for containerized CI solutions integrating Kubernetes.
United Kingdom
The United Kingdom's financial services and government sectors drive significant demand for secure and compliant continuous integration platforms. Mandates from the National Cyber Security Centre (NCSC) encourage the use of tools with strong software supply chain security features. London's vibrant FinTech scene and technology clusters require scalable CI solutions for rapid product iteration.
India
India's burgeoning IT services sector and technology startup ecosystem create substantial greenfield opportunities for cloud-based CI platform adoption. Digital transformation initiatives and data security emphasis influence tool procurement. Bengaluru and Hyderabad emerge as key hubs, with companies investing in CI tools to support large-scale enterprise application development.
China
China's rapid digital economy expansion and government-backed initiatives for advanced software development fuel the adoption of continuous integration tools. GB standards and data sovereignty laws necessitate on-premises or localized cloud CI solutions. Shanghai and Shenzhen are at the forefront, driving innovation in CI tools tailored for large-scale e-commerce and AI applications.
Global Continuous Integration Tools Market Key Industry Players
Concentration sits with established technology conglomerates and specialized SaaS providers within the continuous integration tools market. The market exhibits a tiered structure, with a few dominant platforms alongside numerous niche offerings catering to specific development paradigms. Strategic archetypes include comprehensive DevOps suite providers, open-source ecosystem contributors, and cloud-native specialist vendors. Portfolio diversification into adjacent DevOps areas and strategic partnerships represent dominant competitive moves among these players.
Within the comprehensive DevOps suite tier, Microsoft Corporation exemplifies a vendor leveraging its extensive Azure cloud infrastructure to offer deeply integrated solutions for enterprise clients. Atlassian Corporation Plc anchors its market presence through a robust plugin ecosystem, sustaining its Bamboo and Bitbucket products for diverse development needs. GitLab Inc. represents the single-application approach, providing a unified platform that covers the entire modern DevOps lifecycle, attracting users seeking streamlined and consolidated toolchains.
| Leading Market Players |
|---|
| Atlassian Corporation Plc |
| CircleCI Inc |
| Microsoft Corporation |
| Oracle Corporation |
| CloudBees Inc |
| Amazon Web Services Inc |
| GitLab Inc |
| JetBrains s.r.o |
| International Business Machines Corporation |
| Others |
Cost & Logistics Intelligence
The US National Institute of Standards and Technology (NIST) Secure Software Development Framework (SSDF) gates both supply qualification and price differentiation for continuous integration tools. This regulatory influence ensures that vendors meeting stringent security and auditable provenance requirements can command premium pricing, while those lacking such features face diminished market access and competitive pressure.
Pricing Analysis
Enterprise software teams anchor the pricing structure for continuous integration tools. SaaS-tiered subscription models dominate, offering flexibility based on user count, feature sets, and build minutes. Price differentiation stems from advanced security certifications and deep integration capabilities with existing enterprise systems. Pricing pressure stems from the proliferation of robust open-source alternatives, compelling commercial vendors to continuously innovate. Technology startups exhibit higher price sensitivity compared to large, regulated financial services organizations.
Supply Chain Analysis
Cloud infrastructure provisioning costs represent a significant component in the continuous integration tool supply chain. Key development and talent hubs in the United States, India, and Germany concentrate much of the intellectual property. The supply chain relies on specialized DevOps engineering talent and access to high-performance cloud computing resources. Talent scarcity represents a structural risk, impacting development timelines and operational costs for tool providers. Direct-to-customer SaaS models primarily define the downstream distribution structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global continuous integration tools market is entering a cyclical recovery phase, driven by renewed enterprise IT investment cycles and a heightened focus on software supply chain security.
For Market Incumbents: Secure leadership by deepening platform integrations within existing enterprise ecosystems. Acquire niche AI-powered testing and optimization startups to bolster intelligent automation capabilities. Invest heavily in compliance certifications, such as NIST SSDF and GDPR, to mitigate the threat from less regulated open-source solutions. Expand managed service offerings to address the DevOps talent scarcity among end-users.
For New Entrants and Emerging Players: Specialized compliance tooling for specific industries represents an underserved service layer. Target greenfield opportunities in emerging markets like India and Brazil, which lack legacy system inertia. Focus on delivering cloud-native, API-first solutions with strong community engagement. MLOps CI solutions for data versioning and model validation offer a distinct white-space target for agile players.
For Investors and Strategic Acquirers: NIST SSDF mandates reshape the acquisition landscape, emphasizing tools with verifiable build provenance. Focus on long-term viability, as software supply chain security will remain a strategic imperative over the next decade. Target specialized security scanning providers or AI-powered pipeline optimization firms. Increased enterprise adoption of Software Bill of Materials (SBOM) generation tools is a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Platform Integration | Enhances stickiness and reduces friction for large enterprise clients with diverse toolchains. |
| AI/MLOps Specialization | Addresses the unique and complex CI/CD requirements of machine learning development workflows. |
| Compliance Certification Investment | Positions vendors favorably for procurement by regulated industries and government sectors. |
| Geographic Expansion into Emerging Markets | Captures new customer segments without legacy infrastructure in rapidly digitalizing economies. |
| Enhance Managed Service Offerings | Alleviates internal talent scarcity for end-users, simplifying CI/CD adoption and maintenance. |
Research Approach
A standing panel of CTOs, DevOps engineers, security architects, and IT procurement officers provided ongoing calibration throughout this study. This primary research was rigorously cross-referenced with secondary data from vendor whitepapers, enterprise IT spending reports, industry association publications, and regulatory compliance documents. Both bottom-up and top-down triangulation methods were employed to ensure robust data validation.
Output values were checked for consistency against external benchmarks and macro-economic indicators across the analysis window. The analytical framework modeled segmentation dimensions including deployment mode, tool type, application, end-user, and regional adoption patterns. Compound annual growth rates were derived from historical data and projected market growth drivers, incorporating inputs such as enterprise software development budgets and cloud infrastructure spending.
Forecasts assume regulatory continuity in US NIST and Europe's GDPR regimes; material policy shifts would require re-modeling. Unforeseen geopolitical events, rapid technological disruption in AI, or significant economic downturns affecting IT spending represent key risk factors for this market. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Directory Software Market
Software & Services
Office Productivity Software Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Sales Platforms Software Market
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
Global Driving School Software Market
Software & Services
Curriculum Mapping Software Market
Software & Services
Global Technical Illustration Software Market
Software & Services
Open Stack Service Market
Software & Services
Queue Manager Market
Software & Services
Global Note Taking App Market
Software & Services
Design Engineering Software Market
Software & Services
Online Paint Editor App Market
Software & Services
Global Presentation Software Market