
 Volleyball Shoes Market | 2026-2036
Volleyball Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Volleyball Shoes Market Analytics
Subscription-based digital fitting services and maintenance plans for professional-grade volleyball footwear is broadening how brands monetize athlete relationships. ASICS leverages its heritage in indoor court sports to sustain premium positioning among Japanese school clubs and professional leagues. Nike competes through deep investment in software-defined cushioning platforms that extend product lifecycles for elite athletes. Mizuno anchors its market presence through specialized manufacturing scale in Osaka, where it controls domestic distribution for volleyball-specific product lines.
Volleyball shoes are engineered athletic footwear designed for rapid lateral movement, vertical jumping, and impact absorption on hardwood or synthetic court surfaces, typically incorporating gum rubber outsoles with herringbone traction patterns, reinforced midfoot shanks, and responsive EVA or gel-based cushioning systems. Their primary commercial purpose is to reduce ankle rollover and knee stress during repetitive jump-land sequences in competitive and recreational play. Indoor shoes dominate volume sales due to the sport's standardized court specifications, while lightweight shoes represent the fastest-growing structural category as professional athletes prioritize reduced energy expenditure during extended tournaments. The premium price tier captures disproportionate margin pools through athlete endorsement contracts and limited-edition colorways, whereas budget positioning serves mass amateur participation in emerging volleyball markets.
ISO standards for footwear slip resistance and the EU's REACH chemicals framework shape material selection and market access for synthetic mesh and rubber sole suppliers serving European distribution channels. The US Consumer Product Safety Commission monitors athletic footwear safety claims, while Japan's Ministry of Economy, Trade and Industry enforces JIS labeling standards that influence domestic consumer trust and retail placement. Stakeholders must monitor how evolving state-level extended producer responsibility laws in California and New York reshape end-of-life collection obligations for textile and rubber components.
Market Dynamics
REACH compliance in Europe is modularizing material selection across the volleyball footwear supply chain, forcing manufacturers to reformulate adhesives and synthetic mesh uppers while Japanese school club participation drives replacement cycle compression for lightweight indoor court models.
Growth Catalysts
- REACH chemical restrictions:European ECHA mandates on VOC emissions push manufacturers toward water-based adhesives and recycled synthetic materials, opening premium positioning for compliant suppliers.
- Collegiate equipment budget expansion:United States athletic departments are increasing allocations for indoor court sports, directly lifting institutional procurement volumes for multi-court volleyball footwear.
- Osaka manufacturing cluster concentration:Specialized production scale in Japan's Kansai region enables rapid domestic distribution response to school club replacement cycles.
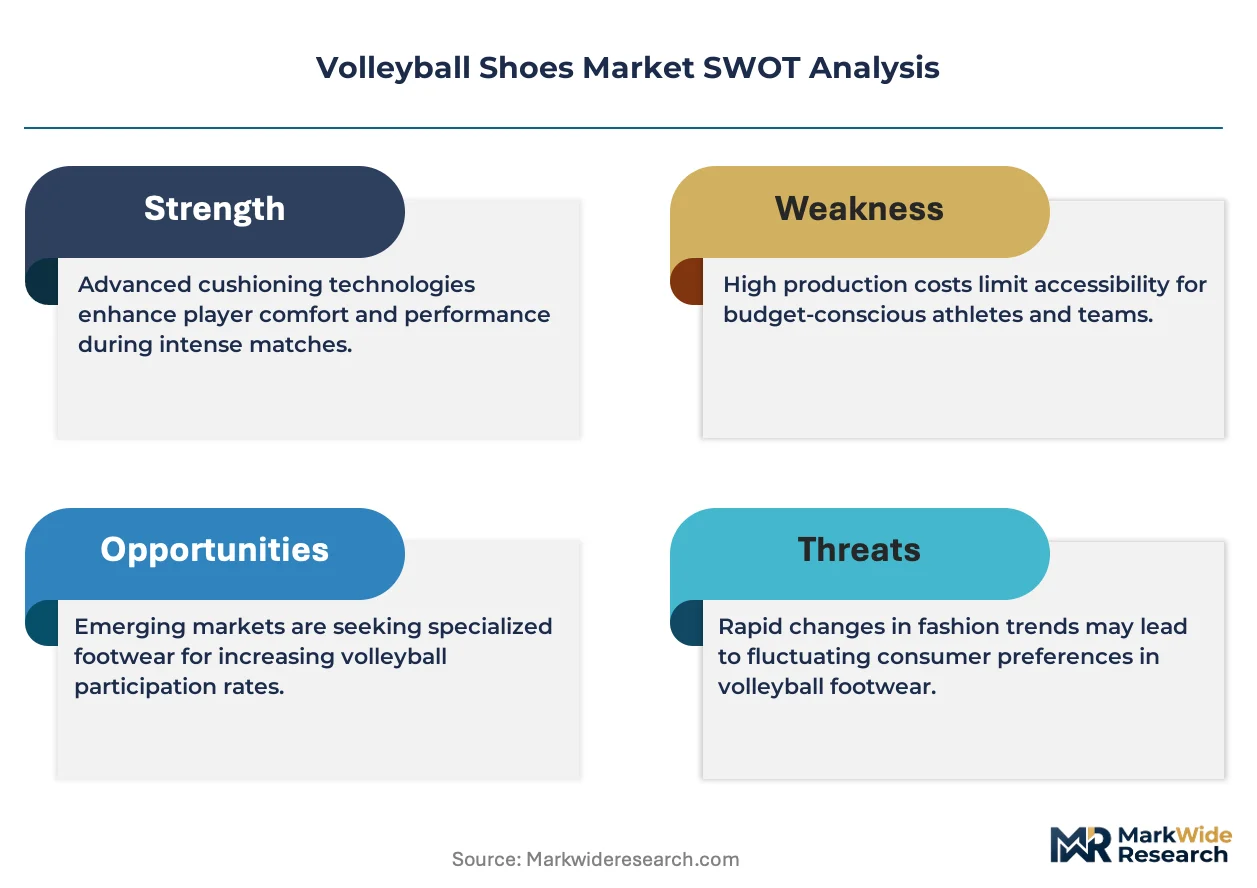
Market Restraints
- Petroleum-derived synthetic rubber volatility:Gum rubber sole compounds depend on feedstock pricing subject to energy market fluctuations, compressing margin stability for budget-tier positioning.
- Single-region production concentration:Volleyball-specific manufacturing capacity clusters heavily in East Asian facilities, exposing supply continuity to localized logistics disruptions.
- Biomechanical customization limits:Mass-production tooling cannot accommodate extreme foot morphology variations without manual retooling costs that exclude amateur segments.
Strategic Opportunities
- Subscription fitting services:Digital foot-scanning platforms combined with maintenance plans create recurring revenue streams beyond initial footwear sales.
- California extended producer responsibility:State-level textile collection mandates position early-compliant brands for preferential retail placement in the largest United States consumer market.
- Gel-EVA cushioning convergence:Hybrid midsole technologies bridge performance tiers, enabling single-SKU strategies across professional and serious amateur segments.
Industry Challenges
- Specialized last design expertise scarcity:Pattern engineers with volleyball-specific biomechanical knowledge concentrate at legacy Japanese manufacturers, constraining new entrant product development timelines.
- JIS certification compliance duration:Japan's Ministry of Economy, Trade and Industry labeling standards require extended testing protocols that delay market entry for imported product lines.
- Multi-court traction pattern IP complexity:Herringbone outsole geometries face dense patent thickets around pivot-point placement and groove depth specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volleyball Shoes Market |
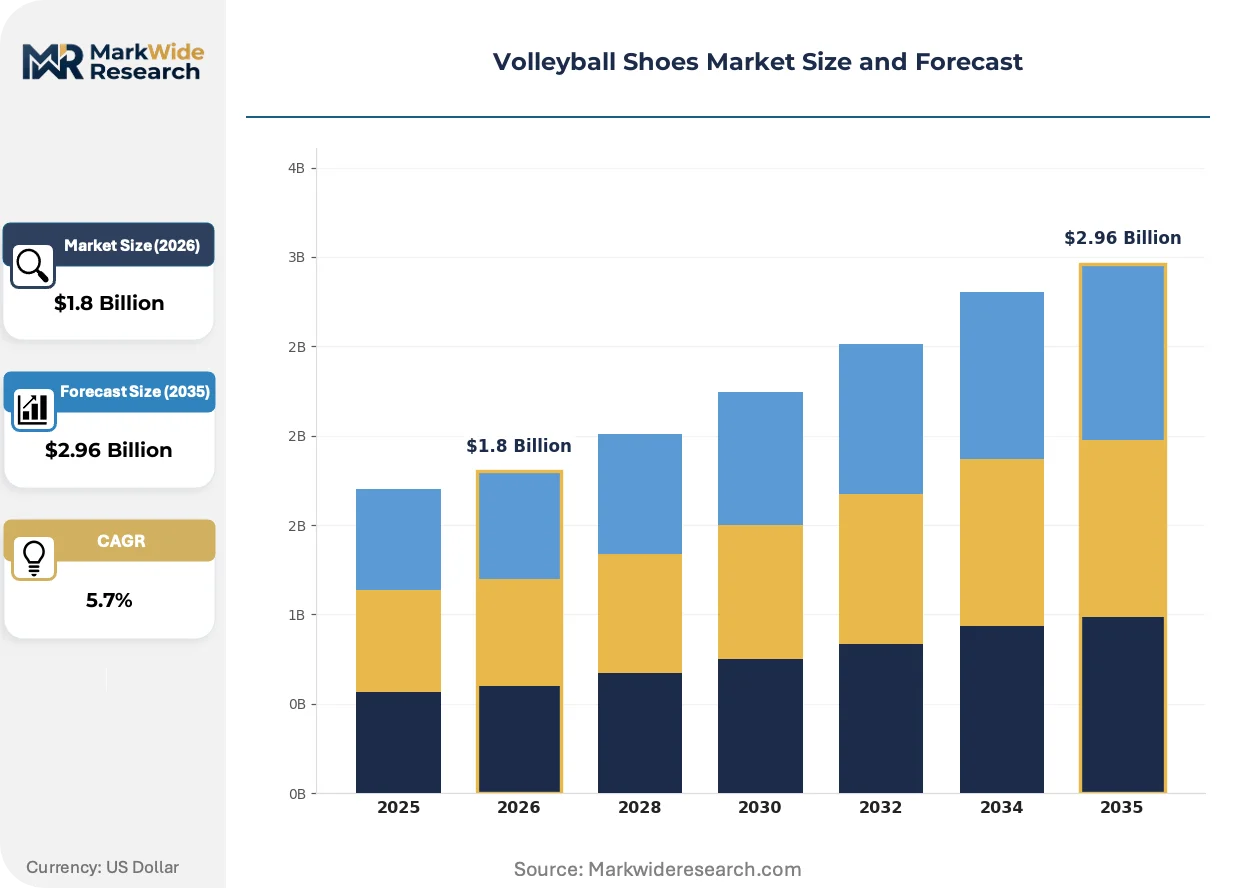
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Shoes, Outdoor Shoes, Multi-Court Shoes, Lightweight Shoes End User: Professional Athletes, Amateur Players, Coaches, Fitness Enthusiasts Material: Synthetic Mesh, Rubber Sole, EVA Foam, Textile Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Adidas, Under Armour, ASICS, Brooks, New Balance, Nike, LI-NING, On, Mizuno, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volleyball Shoes Market Evolving Landscape
Software-defined cushioning platforms are fragmenting traditional hardware-based product lifecycles, while regulatory chemical frameworks and compressed replacement cycles among institutional buyers reshape competitive positioning across price tiers.
Modular midsole systems using interchangeable gel and EVA inserts are modularizing how athletes customize energy return and impact absorption for tournament versus training conditions. Professional leagues and collegiate programs in Japan and the United States are adopting these platforms fastest, typically replacing core modules at twelve-to-eighteen-month intervals rather than purchasing entirely new footwear.
EU REACH Annex XVII restrictions on phthalate plasticizers and heavy metal pigments now govern colorway development for synthetic mesh uppers bound for European distribution channels. Manufacturers serving Germany, France, and Italy must reformulate dye processes and adhesive bonding agents, with premium tier suppliers absorbing compliance costs while budget positioning faces margin compression or market exit.
Institutional procurement teams at United States universities and Japanese school districts are consolidating vendor relationships through multi-year framework agreements that bundle footwear, fitting services, and end-of-life collection. This behavior concentrates volume with suppliers offering comprehensive service stacks, displacing transactional retail relationships for competitive and educational segments.
Volleyball Shoes Market Segmentation
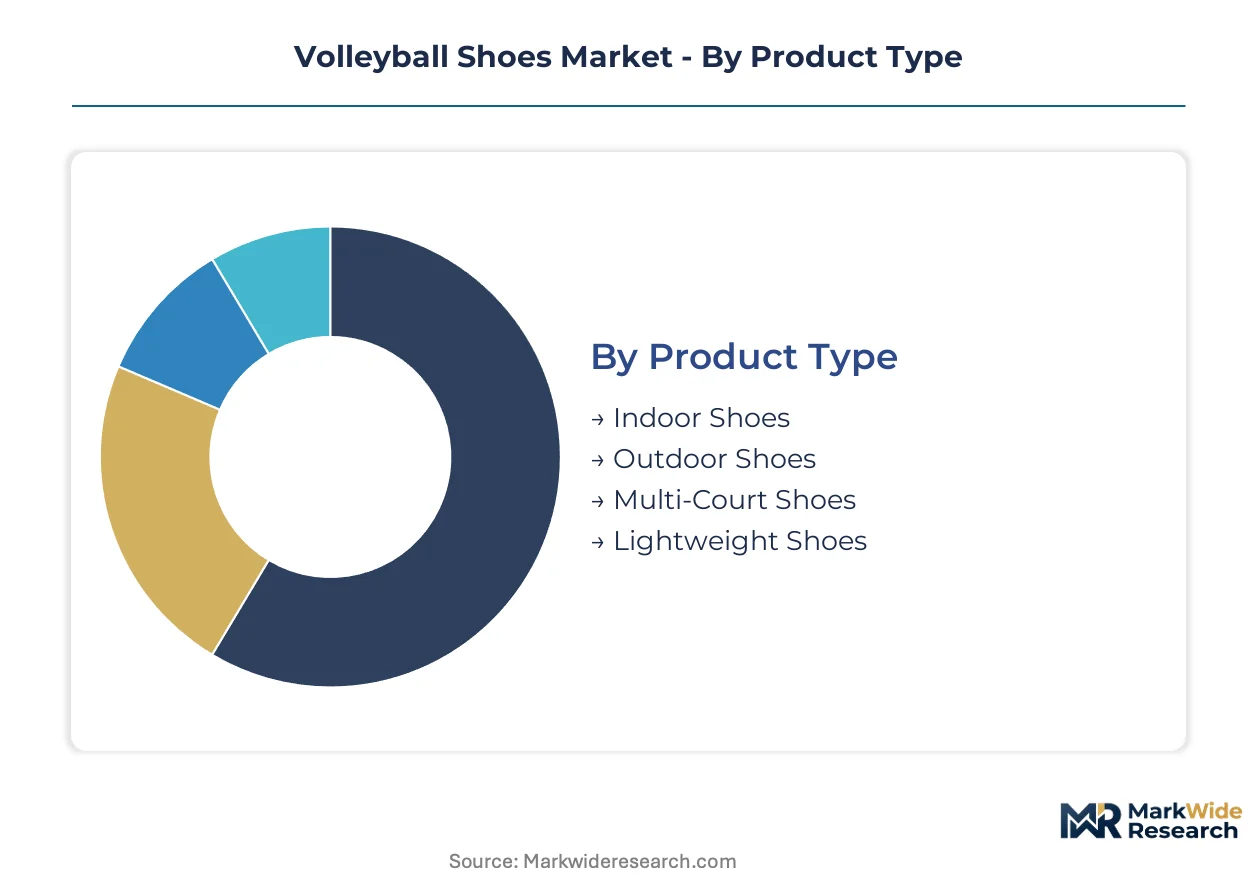
Volleyball footwear segmentation reflects divergent biomechanical demands across court surfaces, athlete commitment levels, and procurement budgets. Manufacturers configure material stacks and cushioning platforms differently for each category, with institutional buyers and professional athletes driving premium tier development.
Product Type:
Surface specifications and tournament formats differentiate buyer requirements across this category.
- Indoor Shoes:Gum rubber outsoles with herringbone traction patterns dominate hardwood court adherence. Japanese school club procurement and United States collegiate programs sustain replacement cycles for reinforced midfoot shank designs.
- Lightweight Shoes:Reduced upper mass and minimal heel counter construction prioritize energy conservation during extended tournament play. Professional athletes in Japan and elite collegiate programs in the United States drive fastest adoption for modular midsole compatibility.
- Multi-Court Shoes:Hybrid traction geometries accommodate both hardwood and synthetic surfaces for recreational facility operators.
- Outdoor Shoes:Deeper lug patterns and weather-resistant uppers serve beach and grass court variants with limited institutional procurement.
Indoor shoes lead volumes today; lightweight shoes are gaining share fastest.
End User:
Performance expectations and replacement frequency separate commercial segments in this dimension.
- Professional Athletes:Custom-lasted footwear with tournament-specific cushioning modules commands highest per-unit pricing. Japanese V.League and United States NCAA Division I programs compress replacement cycles to twelve-to-eighteen-month intervals.
- Amateur Players:Mass-market distribution through sporting goods retail and e-commerce platforms sustains volume production economies. Budget-tier positioning serves recreational participation in emerging volleyball markets with limited biomechanical customization.
- Coaches:Institutional procurement through university athletic departments and school district frameworks bundles fitting services with volume discounts.
- Fitness Enthusiasts:Cross-training usage patterns favor multi-court versatility over sport-specific engineering.
Amateur players anchor volume production; professional athletes command margin concentration.
Material:
REACH compliance timelines and petroleum feedstock exposure reshape supplier selection criteria.
- Synthetic Mesh:Engineered polyester and nylon uppers with recycled content ratios respond to EU ECHA mandates on VOC emissions. Premium tier suppliers absorb reformulation costs while budget positioning faces margin compression.
- Rubber Sole:Natural gum rubber compounds deliver optimal hardwood traction but concentrate supply risk on Southeast Asian plantation output. Energy market volatility transmits directly to sole unit pricing.
- EVA Foam:Ethylene-vinyl acetate midsole cores balance energy return with manufacturing scalability across price tiers.
- Textile:Knitted upper constructions reduce pattern engineering complexity for rapid colorway rotation.
Synthetic mesh dominates upper construction; recycled content variants are climbing the fastest.
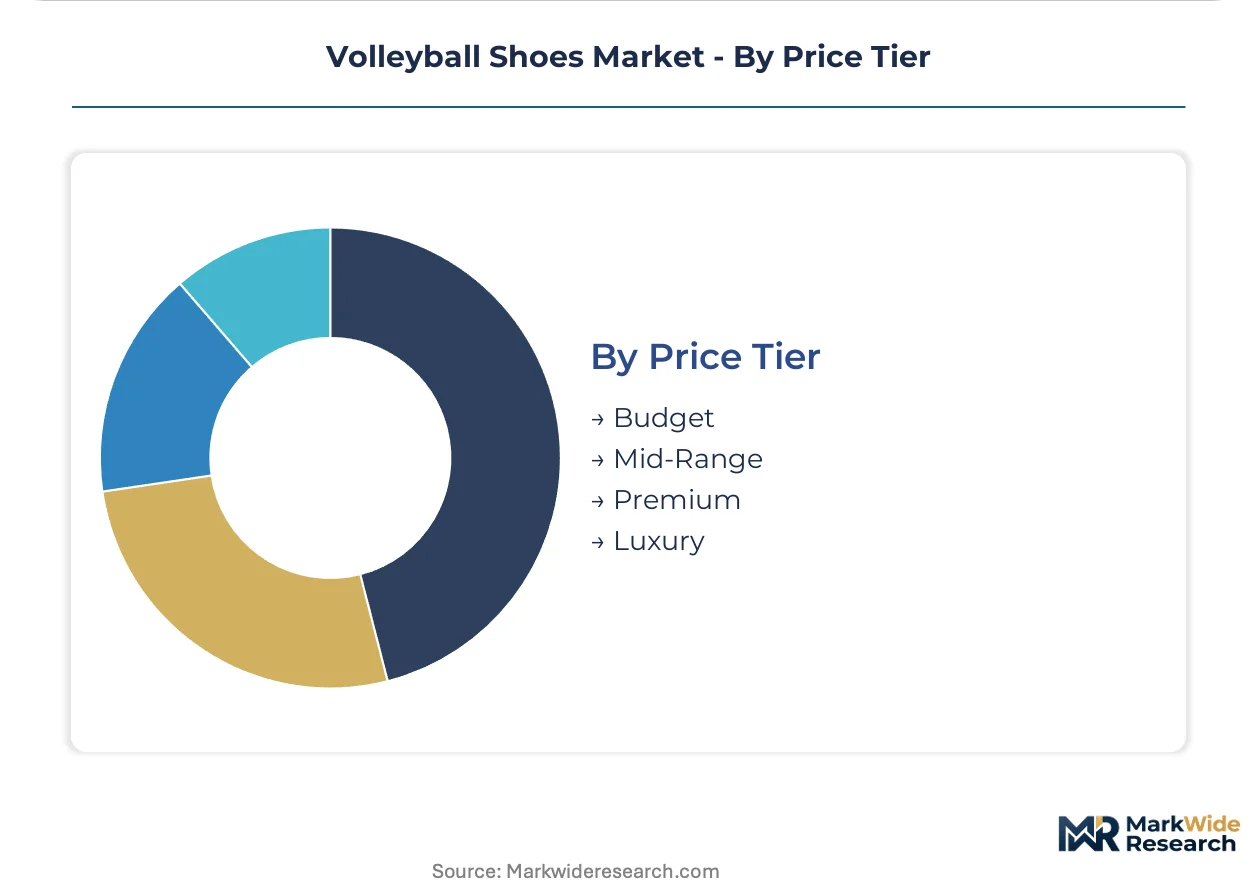
Price Tier:
Procurement authority and performance certification requirements stratify commercial access.
- Premium:Athlete endorsement contracts and limited-edition colorways capture disproportionate margin pools. JIS certification and NCAA compliance documentation sustain positioning among Japanese school clubs and United States collegiate programs.
- Budget:Mass amateur participation in emerging markets depends on simplified construction without modular midsole compatibility. REACH compliance costs threaten market exit for suppliers lacking scale.
- Mid-Range:Gel-EVA cushioning convergence enables single-SKU strategies bridging serious amateur and entry-professional segments.
- Luxury:Artisan construction and heritage branding serve collector demand with minimal athletic function differentiation.
Premium tier commands margin concentration; mid-range positioning shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan compresses replacement cycles through school club procurement, while the United States concentrates institutional demand in NCAA Division I programs. Germany and France absorb REACH compliance costs into premium positioning, and Brazil's emerging amateur base sustains budget-tier volume production.
United States
NCAA Division I athletic departments and collegiate club programs drive institutional procurement volumes for multi-court footwear. The Consumer Product Safety Commission monitors athletic footwear safety claims and marketing representations. California's extended producer responsibility laws for textile collection reshape end-of-life obligations for brands serving the largest domestic consumer market.
Japan
Junior high and high school club volleyball participation creates compressed twelve-to-eighteen-month replacement cycles for lightweight indoor models. The Ministry of Economy, Trade and Industry enforces JIS labeling standards that influence domestic consumer trust and retail placement. Osaka's Kansai manufacturing cluster enables rapid distribution response to school district procurement timelines.
Germany
Amateur volleyball league participation and recreational facility operators sustain mid-range product demand across indoor court specifications. ECHA REACH Annex XVII restrictions on phthalate plasticizers govern synthetic mesh upper formulations. Bavaria's sporting goods retail concentration channels compliant product flows into Central European distribution networks.
France
Club volleyball federation membership and regional tournament circuits support steady equipment turnover among competitive amateurs. EU REACH frameworks on VOC emissions from adhesives push manufacturers toward water-based bonding agents. The Lyon-Grenoble corridor hosts specialized synthetic material suppliers serving compliant footwear producers.
Brazil
Emerging amateur participation in beach and indoor variants sustains budget-tier volume demand through mass retail channels. The national consumer protection regulator monitors product safety standards for imported athletic footwear. São Paulo's industrial suburbs concentrate assembly operations for price-sensitive Latin American distribution.
Volleyball Shoes Market Competitive Landscape
Top-tier vendors anchor premium positioning through athlete endorsements and modular technology platforms, while mid-tier specialists compete on manufacturing scale and regional distribution density. The vendor base stratifies across heritage Japanese manufacturers, diversified sportswear conglomerates, and emerging Asia-Pacific challengers. Three archetypes dominate: biomechanical engineering specialists, software-defined cushioning platform operators, and verticalized domestic producers. Consolidation pressure manifests through framework agreement bundling and end-of-life service integration rather than outright acquisition activity.
Within the heritage specialist tier, ASICS Corporation and Mizuno Corporation represent decades-long concentration in volleyball-specific last design and domestic Japanese distribution control. Nike Inc. exemplifies the platform operator archetype through software-defined cushioning investments that extend product lifecycles for elite athlete segments. These three anchors demonstrate how competitive position derives from either manufacturing heritage depth or digital-physical integration scale.
| Leading Market Players |
|---|
| Adidas |
| Under Armour |
| ASICS |
| Brooks |
| New Balance |
| Nike |
| LI-NING |
| On |
| Mizuno |
| Others |
Value Network & Pricing Analysis
Captive production of gum rubber sole compounds in Southeast Asian plantation networks anchors both supply security and pricing power for tier-one manufacturers serving Japanese school clubs and United States collegiate programs. This backward integration into natural rubber feedstock insulates premium positioning from petroleum-derived synthetic volatility while compressing cost structures for budget-tier competitors lacking equivalent upstream control.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for gum rubber outsole units bound for mass-market distribution. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified Japanese domestic product from NCAA-compliant United States collegiate procurement and unmarked Latin American budget imports. Price differentiation hinges on certification grade and modular midsole compatibility. Cost compression in the economy tier is intensifying because REACH compliance mandates force reformulation expenses onto suppliers lacking scale. Amateur recreational players in emerging markets exhibit highest price sensitivity; professional athletes in Japan's V.League demonstrate lowest sensitivity due to institutional procurement frameworks.
Supply Chain Analysis
Japan's domestic-content thresholds for JIS labeling are reshaping sourcing patterns toward Osaka-Kansai manufacturing clusters. Production gravity centers on Japan, Vietnam, and China, with specialized last-design engineering concentrating in Osaka. Raw material dependencies draw from Southeast Asian natural rubber plantations, Chinese synthetic mesh textile mills, and Korean EVA foam suppliers. Single-region concentration in East Asian facilities exposes continuity to localized logistics disruptions. Distribution runs through institutional procurement frameworks at United States universities and Japanese school districts, bypassing traditional retail for competitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Volleyball footwear operates as a regulatory compounder where EU REACH Annex XVII phthalate restrictions and California extended producer responsibility laws simultaneously expand compliance costs and consolidate demand toward certified suppliers.
For Market Incumbents: Acquire specialized last-design engineering teams concentrated at legacy Japanese manufacturers to compress new entrant development timelines. Secure captive gum rubber supply agreements with Southeast Asian plantation networks before feedstock volatility transmits to sole unit pricing. Defend against software-defined cushioning platforms by embedding modular midsole compatibility across premium and mid-range product lines. For New Entrants and Emerging Players: Launch via subscription-based digital fitting services bundled with maintenance plans to bypass capital-intensive manufacturing scale requirements. Target United States collegiate club programs outside NCAA Division I frameworks where vendor consolidation has not yet concentrated procurement. Exploit white space in REACH-compliant recycled synthetic mesh uppers for European amateur leagues where premium incumbents absorb compliance costs. For Investors and Strategic Acquirers: Consolidation pressure builds where framework agreement bundling displaces transactional retail relationships for institutional buyers. Long-term viability favors suppliers integrating end-of-life collection with fitting services and volume procurement. Target acquisition candidates with JIS certification infrastructure and Osaka manufacturing presence. Watch California textile collection mandate enforcement as inflection indicator for preferential retail placement obligations.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Midsole Platform Development | Software-defined cushioning extends replacement cycles for Japanese V.League professionals. |
| REACH-Compliant Material Reformulation | Water-based adhesives and recycled mesh secure European ECHA market access. |
| Framework Agreement Bundling | Multi-year institutional contracts consolidate volume with comprehensive service stacks. |
| Digital Foot-Scanning Subscription Launch | Recurring revenue streams monetize athlete relationships beyond initial footwear sales. |
| Osaka Manufacturing Cluster Expansion | Domestic production scale enables rapid response to Japanese school club replacement cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary research incorporated pattern engineers at legacy Japanese footwear manufacturers, procurement directors at United States NCAA Division I athletic departments, synthetic material suppliers in the Lyon-Grenoble corridor, and distribution channel partners serving German amateur volleyball leagues. Secondary validation drew from JIS certification databases, ECHA REACH Annex XVII substance restrictions, United States Consumer Product Safety Commission athletic footwear guidelines, and Japanese Ministry of Economy, Trade and Industry labeling standards. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, material, and price tier segments.
Segment-weighting approaches distributed volume and value projections across indoor, lightweight, multi-court, and outdoor product categories, with additional stratification by professional athlete, amateur player, coach, and fitness enthusiast end users. CAGRs were derived from replacement cycle analysis and institutional procurement trend modeling. Forecast inputs incorporated REACH compliance timeline assumptions, petroleum feedstock volatility scenarios, and school club participation rates in Japan.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended ECHA chemical restriction timelines or accelerated California textile collection mandate enforcement. Model assumptions reflect current regulatory frameworks and procurement patterns without projecting specific policy implementation dates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Motocross Gears Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Golf Gloves Market
Sports Equipment
US Fencing Market
Sports Equipment
Slam Ball Market
Sports Equipment
Sports and Leisure Equipment Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Curling Equipment Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Cleat Market
Sports Equipment
Table Tennis Equipment Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Balance Bike Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
Golf Club Grips Market