
 Dance Equipment Market | 2026-2036
Dance Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Dance Equipment Market Analytics
Smart textile integration with embedded biomechanical sensors is reconfiguring how performance footwear and apparel are engineered for real-time movement analytics. Capezio leverages decades of artisanal manufacturing heritage to sustain premium positioning in pointe shoe craftsmanship. Bloch anchors its competitive stance through vertical control over last-making and custom fitting protocols across professional ballet markets. Gaynor Minden differentiates via polymer shank technology that extends product lifespan beyond traditional paste-construction alternatives.
Dance equipment encompasses purpose-built footwear, apparel, accessories, and stage props engineered to withstand repetitive high-impact loading while permitting multi-axial joint articulation; pointe shoes typically incorporate satin uppers, leather soles, and reinforced toe boxes rated for 8-12 hours of performance wear. The Shoes category dominates value capture due to technical complexity and replacement frequency driven by material fatigue. Synthetic materials represent the fastest-expanding segment as manufacturers reduce leather dependence to address cost volatility and animal-welfare compliance. Professional Dancers generate the highest per-capita spend, though Dance Schools aggregate volume through institutional procurement contracts that reshape pricing structures.
The U.S. Consumer Product Safety Commission monitors flammability standards for theatrical costumes, while California's Proposition 65 mandates chemical disclosure for synthetic dyes used in dance apparel. The EU REACH regulation restricts phthalates and azo dyes in imported textiles, forcing Asian suppliers to reformulate material compositions or forfeit market access. Stakeholders must monitor emerging state-level right-to-repair legislation that could mandate replaceable components in electronic-enabled dance training equipment.
Market Dynamics
Smart textile integration with embedded biomechanical sensors is reconfiguring competitive positioning across performance footwear and apparel segments, forcing legacy manufacturers to rebuild R&D pipelines around real-time movement analytics capabilities.
Growth Catalysts
- EU REACH chemical compliance:Tightening restrictions on phthalates and azo dyes in imported textiles are accelerating supplier consolidation toward certified European vendors capable of guaranteed material traceability.
- Professional dance school procurement:Institutional budget expansion across metropolitan studio clusters is aggregating volume through multi-year equipment contracts that reshape traditional wholesale pricing structures.
- Synthetic material substitution:Polymer-based shank technologies are extending product lifespans beyond traditional paste-construction alternatives, reducing replacement frequency while improving performance consistency.
Market Restraints
- Leather cost volatility:Traditional pointe shoe construction depends on specialized hide grades subject to agricultural commodity swings, compressing margin stability for artisanal manufacturers.
- Asian supplier concentration:Bulk synthetic textile production clusters in southeastern China create geographic vulnerability to regional logistics disruptions or tariff reconfigurations.
- Biomechanical sensor calibration limits:Embedded textile electronics face accuracy degradation under sweat exposure and repeated flex cycling, constraining reliability guarantees for professional performance use.
Strategic Opportunities
- Right-to-repair legislation:Emerging state-level mandates for replaceable components in electronic-enabled training equipment create aftermarket service revenue streams for sensor-integrated product lines.
- Polymer shank convergence:Combining thermoplastic engineering with 3D-printed custom fitting protocols enables mass personalization at unit economics previously reserved for bespoke craftsmanship.
- Dance school direct channels:Bypassing traditional retail through institutional procurement portals captures volume commitments while reducing distributor margin extraction.
Industry Challenges
- Smart textile engineering talent scarcity:The intersection of apparel manufacturing and embedded systems design requires hybrid skill sets rarely available in traditional footwear labor pools.
- California Proposition 65 disclosure complexity:Chemical labeling mandates for synthetic dyes create compliance documentation burdens that extend product launch timelines and increase legal exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dance Equipment Market |
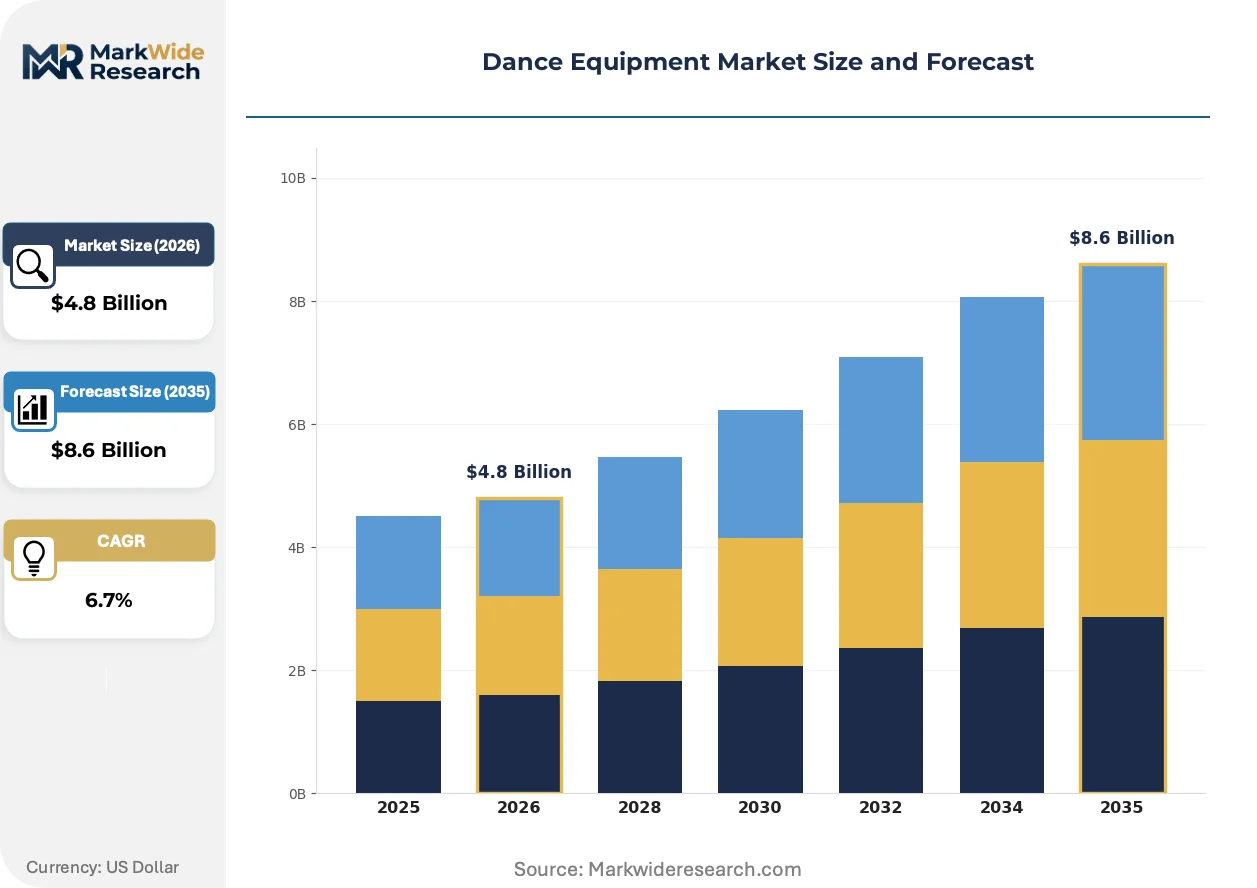
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shoes, Clothing, Accessories, Props Material: Leather, Synthetic, Cotton, Nylon Application: Theater, Fitness, Competitions, Recreational End User: Professional Dancers, Students, Dance Schools, Hobbyists |
| Companies Covered | Capezio, Bloch, Sansha, Grishko, Gaynor Minden, Freed of London, Mirella, Dancewear Solutions, Roch Valley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dance Equipment Market Evolving Landscape
Performance equipment engineering is pivoting from static durability metrics toward dynamic biomechanical feedback systems, embedding sensor networks directly into garments and footwear that were previously purely mechanical.
Biomechanical sensor integration is migrating from aftermarket accessories to factory-embedded textile architectures. Professional ballet companies and competitive dance studios are piloting these systems for injury prevention and technique optimization. The technology is migrating from niche performance analytics toward mainstream training equipment specifications, compressing the competitive window for manufacturers lacking embedded electronics capabilities.
EU REACH enforcement is tightening material certification requirements for imported dancewear, with ECHA inspectors expanding azo dye and phthalate testing protocols at entry points. Asian suppliers face reformulation costs or market exclusion, accelerating supplier qualification toward European-certified vendors. Professional pointe shoe manufacturers with established European material sourcing are consolidating advantage over competitors dependent on uncertified Asian textile streams.
Institutional procurement patterns are fragmenting traditional retail channels as dance schools consolidate purchasing through dedicated vendor portals. Metropolitan studio clusters in New York, Los Angeles, and Chicago are negotiating direct manufacturer relationships that displace distributor intermediaries. This concentration is most visible in the United States, where professional school networks aggregate sufficient volume to command custom fitting protocols and extended payment terms previously reserved for national retail chains.
Dance Equipment Market Segmentation
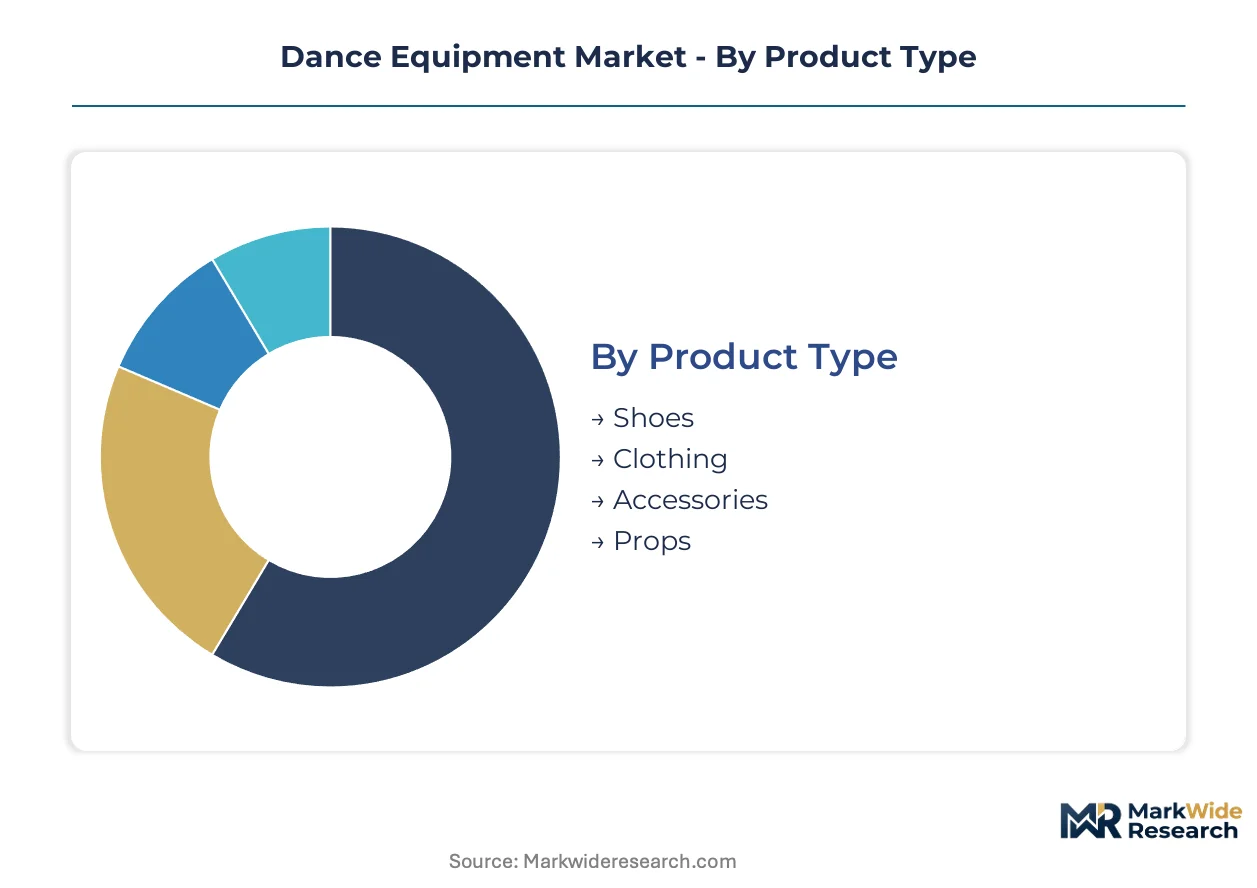
Dance equipment segmentation reveals starkly different replacement cycles across categories, with footwear demanding frequent renewal due to material fatigue while props endure for years. Understanding these temporal patterns shapes inventory planning, margin structures, and supplier relationships across the value chain.
Product Type:
Replacement velocity varies dramatically within this category, with high-impact footwear cycling every 8-12 performance hours against props that persist across production seasons.
- Shoes:Pointe shoes incorporate satin uppers, leather soles, and reinforced toe boxes engineered for repetitive high-impact loading. New York, Los Angeles, and Chicago metropolitan studio clusters drive concentrated procurement through institutional contracts that reshape traditional wholesale pricing structures.
- Clothing:Performance apparel permits multi-axial joint articulation through engineered stretch panels and seam placement. EU REACH enforcement tightens material certification requirements for imported dancewear, accelerating supplier consolidation toward European-certified vendors capable of guaranteed material traceability.
- Accessories:Supplementary items span bags, warm-up gear, and protective equipment with moderate durability expectations.
- Props:Stage elements including portable barres, mats, and theatrical backdrops exhibit extended service lifespans with minimal replacement frequency.
Shoes anchors the volume base while Clothing gains share at the steepest rate.
Material:
Cost tier stratification separates premium natural inputs from mass-market synthetics, with mid-grade alternatives capturing institutional budget constraints.
- Leather:Specialized hide grades supply traditional pointe shoe construction with biomechanical conformity and breathability. Agricultural commodity swings compress margin stability for artisanal manufacturers dependent on consistent hide sourcing.
- Synthetic:Polymer-based textiles reduce leather dependence to address cost volatility and animal-welfare compliance. Polymer shank technologies extend product lifespans beyond traditional paste-construction alternatives, climbing the fastest as manufacturers reformulate material compositions to satisfy EU REACH phthalate and azo dye restrictions.
- Cotton:Natural fiber base layers and practice wear prioritize moisture absorption and skin contact comfort for extended training sessions.
- Nylon:High-tenacity synthetic provides durability for tights, straps, and reinforcement panels in high-stress garment zones.
Leather retains premium positioning while Synthetic expands volume most aggressively.
Application:
Volume concentration clusters in training environments against sporadic but high-specification demand from performance contexts.
- Theater:Production-specific costumes and footwear must satisfy U.S. Consumer Product Safety Commission flammability standards for theatrical costumes. California's Proposition 65 mandates chemical disclosure for synthetic dyes, creating compliance documentation burdens that extend product launch timelines.
- Fitness:Studio-based training equipment emphasizes durability under daily repetitive use across varied dance modalities. Metropolitan studio clusters negotiate direct manufacturer relationships that displace distributor intermediaries and capture volume commitments.
- Competitions:Regulated performance wear adheres to sanctioning body specifications with limited customization tolerance.
- Recreational:Entry-level price sensitivity drives simplified construction and reduced specification requirements for casual participants.
Fitness commands the volume base while Theater expands at the steepest trajectory.
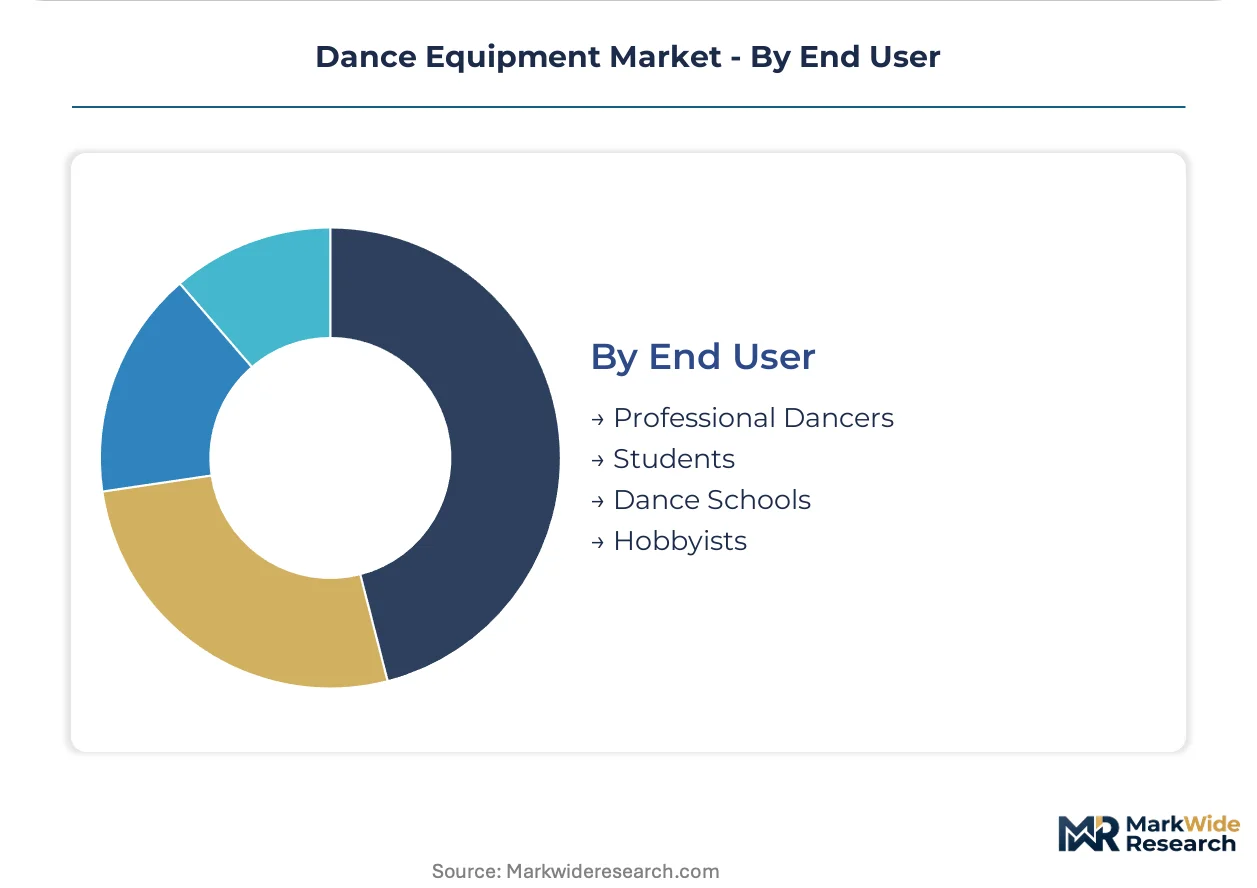
End User:
Per-capita spend inversely correlates with aggregate volume, creating divergent go-to-market economics across customer types.
- Professional Dancers:Highest per-capita expenditure on technical footwear with custom fitting protocols and premium material specifications. Embedded biomechanical sensor integration migrates from aftermarket accessories to factory-embedded textile architectures for injury prevention and technique optimization.
- Dance Schools:Institutional procurement contracts aggregate volume through multi-year equipment commitments that reshape pricing structures. Direct manufacturer portals bypass traditional retail channels and reduce distributor margin extraction.
- Students:Intermediate specification requirements balance durability demands against budget constraints during skill development phases.
- Hobbyists:Price-driven purchasing prioritizes accessibility over technical performance characteristics for intermittent use patterns.
Dance Schools anchor the volume base while Professional Dancers sustain premium tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports synthetic textiles and polymer components to European and North American dancewear manufacturers, establishing the dominant east-west trade corridor in this market. Finished equipment flows concentrate through specialized distributors serving metropolitan studio clusters in destination markets.
United States
Professional dance schools in New York, Los Angeles, and Chicago are expanding equipment procurement budgets through institutional contracts. The U.S. Consumer Product Safety Commission monitors flammability standards for theatrical costumes used in Broadway productions. California's Proposition 65 mandates chemical disclosure for synthetic dyes, creating compliance documentation burdens for apparel suppliers serving West Coast studio networks.
Germany
Technical dance footwear manufacturers source certified materials through domestic suppliers to satisfy EU REACH phthalate and azo dye restrictions. ECHA inspectors have expanded testing protocols at German entry points for imported dancewear. The Bavarian and North Rhine-Westphalian industrial corridors host specialized textile finishing operations that serve Central European distribution networks.
United Kingdom
London's theater district generates concentrated demand for performance-grade pointe shoes and theatrical costumes with strict fire-safety specifications. The UK's post-EU regulatory framework maintains REACH-aligned chemical standards for imported textiles. Greater Manchester and Birmingham host regional dance school networks that aggregate procurement volume through direct manufacturer relationships.
France
Paris-based ballet companies sustain premium-tier demand for artisanal pointe shoe craftsmanship with custom fitting protocols. ANSM and CNIL oversight extends to wearable sensor data collection in smart textile pilot programs. The Île-de-France region concentrates both professional performance institutions and specialized retail channels serving competitive dancers.
Japan
METI-supported textile innovation programs accelerate biomechanical sensor integration into performance apparel for injury prevention. JIS standards govern material specifications for theatrical equipment used in Tokyo's commercial dance theater productions. The Kanto region around Tokyo anchors domestic demand, with Osaka's Kansai district hosting secondary studio clusters and regional distribution hubs.
Dance Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base clusters around three archetypes: heritage craft houses with artisanal positioning, synthetic-material innovators with polymer engineering capabilities, and institutional-direct specialists with dance school procurement portals. Dominant competitive moves include backward integration into captive material supply and geographic expansion through metropolitan studio cluster penetration.
Within the heritage craft tier, Capezio and Bloch exemplify channel-controlling positions built on decades of manufacturing legacy. Gaynor Minden occupies a position as the synthetic-material innovator archetype, representing polymer engineering disruption against traditional paste-construction methods. These three companies anchor the competitive structure, with Capezio's artisanal heritage and Bloch's vertical control over last-making protocols contrasting against Gaynor Minden's thermoplastic engineering approach.
| Leading Market Players |
|---|
| Capezio |
| Bloch |
| Sansha |
| Grishko |
| Gaynor Minden |
| Freed of London |
| Mirella |
| Dancewear Solutions |
| Roch Valley |
| Others |
Value Network & Pricing Analysis
EU REACH phthalate restrictions on Asian textile imports determine both pricing tier spreads and supply chain shape, compressing margins for uncertified suppliers while consolidating procurement toward European-certified vendors capable of guaranteed material traceability.
Pricing Analysis
Current-generation polymer shank technology commands substantial premiums over traditional paste-construction alternatives, while next-generation biomechanical sensor integration sits at prototype pricing tiers awaiting manufacturing scale. Three-tier pricing structure across premium artisanal, standard institutional, and economy recreational levels separates custom-fitted pointe shoes from volume-contract school procurement and entry-level hobbyist gear. Pricing pressure stems from leather cost volatility as agricultural commodity swings compress margin stability for heritage manufacturers. Dance schools exhibit highest price sensitivity through aggregated institutional procurement, while professional dancers sustain lowest sensitivity via per-capita technical specification demands.
Supply Chain Analysis
Export-control scrutiny on embedded sensor components limits flows of biometric-capable microelectronics to finished goods manufacturers, constraining smart textile production scale. Bulk synthetic textile production clusters in southeastern China, Vietnam, and Bangladesh feed raw material streams to European and North American dancewear finishers. Specialized hide grades from Italian and Argentinian tanneries supply traditional pointe shoe construction. Single-source vulnerability concentrates in southeastern China's polymer textile corridor, exposing downstream manufacturers to regional logistics disruptions. Distribution runs through institutional procurement portals serving metropolitan studio clusters, displacing traditional wholesale distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Institutional procurement consolidation fragments traditional retail channels, creating niche opportunities for direct-manufacturer relationships and specialized fitting services that bypass distributor intermediaries.
For Market Incumbents: Harden competitive moats through backward integration into captive European material supply chains certified for EU REACH compliance, insulating margin structures from Asian supplier reformulation costs. Deepen channel control by expanding proprietary fitting protocols across professional ballet companies, countering polymer-shank substitute technologies with artisanal craftsmanship differentiation.
For New Entrants and Emerging Players: Build out white-space positions in smart textile aftermarket services, targeting right-to-repair mandates for replaceable sensor components in electronic-enabled training equipment. Penetrate underserved metropolitan studio clusters in secondary US cities through direct institutional procurement portals, capturing volume commitments with custom fitting protocols previously reserved for national retail chains.
For Investors and Strategic Acquirers: EU REACH enforcement expansion reshapes the acquisition landscape toward European-certified material suppliers and verticalized manufacturers with guaranteed traceability. Long-term viability favors hybrid craft-technology archetypes blending artisanal heritage with polymer engineering capabilities. Monitor ECHA inspector deployment patterns at German and French entry points as inflection indicators for supplier consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Textile Integration | Embedded biomechanical sensors in pointe shoes enable real-time injury prevention analytics for professional companies. |
| Polymer Shank Convergence | Thermoplastic engineering combined with 3D-printed custom fitting reduces replacement frequency while improving performance consistency. |
| Direct Institutional Procurement | Bypassing traditional retail through school vendor portals captures volume commitments and reduces distributor margin extraction. |
| European Material Certification | REACH-compliant supply chains insulate manufacturers from Asian supplier exclusion risks and reformulation cost burdens. |
| Right-to-Repair Service Buildout | Replaceable sensor component programs create aftermarket revenue streams compliant with emerging state-level mandates. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary validation anchors the qualitative findings in this study. Primary fieldwork incorporated dance school procurement directors, pointe shoe manufacturing engineers, professional company wardrobe supervisors, textile compliance consultants, and biomechanical sensor developers. Secondary sources included EU ECHA regulatory filings, US Consumer Product Safety Commission flammability standards documentation, California Proposition 65 chemical disclosure records, and customs trade data on synthetic textile imports. Bottom-up segment sizing triangulated against top-down market calibration ensures methodological robustness.
Calibration against historical replacement cycle data and institutional contract velocity informs the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, material composition, application context, and end-user archetype alongside regional regulatory cluster differentiation. CAGRs derive from trend extrapolation of procurement budget expansion and material substitution rates. Forecast inputs incorporate professional dancer population estimates and dance school network growth patterns.
Practitioners should monitor ECHA enforcement intensity and state-level right-to-repair legislative progression for early signals of supply chain reconfiguration. Forecasts reflect documented assumptions on material certification timelines and smart textile manufacturing scale. Material shifts in EU REACH restricted substance lists or embedded sensor reliability breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Tennis Ball Machine Market
Sports Equipment
Power Sports Aftermarket Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
North America Stand-Up Paddleboard Market
Sports Equipment
Hydration Belt Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
Sports Flooring Market
Sports Equipment
Table Tennis Equipment Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Alpine Ski Equipment Market
Sports Equipment
Go Kart Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
Riding Gear Market
Sports Equipment
Europe Artificial Grass Market
Sports Equipment
Diving Board Market