
 Potty Training Seat Market | 2026-2036
Potty Training Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Potty Training Seat Market Analytics
Accessory and replacement pad revenue is reshaping margin distribution across the potty training seat value chain. Munchkin leverages broad retail shelf presence to sustain recurring consumable sales. BabyBjorn anchors premium positioning through Scandinavian design heritage and ergonomic certification. Summer Infant competes on price-accessible distribution through mass-market channels.
A potty training seat is a child-sized removable fixture designed to reduce toilet aperture diameter, typically manufactured from polypropylene or TPE overmolded composites with weight ratings between 20 and 50 kilograms, enabling toddlers to transition from diapers to independent toilet use. The plastic material segment dominates production volume due to injection molding scalability and color customization flexibility. Multifunctional seats combining step-stool integration represent the fastest-growing product type as parents seek space-efficient solutions for compact urban bathrooms.
The US Consumer Product Safety Commission enforces ASTM F963 standards for mechanical integrity and phthalate restrictions, while the EU's REACH regulation governs SVHC thresholds in soft-touch components. India's BIS mandates IS 9873 compliance for child product safety, creating divergent testing burdens for exporters. Stakeholders must monitor evolving state-level chemical disclosure requirements in California's Proposition 65 framework and prepare for potential harmonization with emerging Asian regulatory regimes.
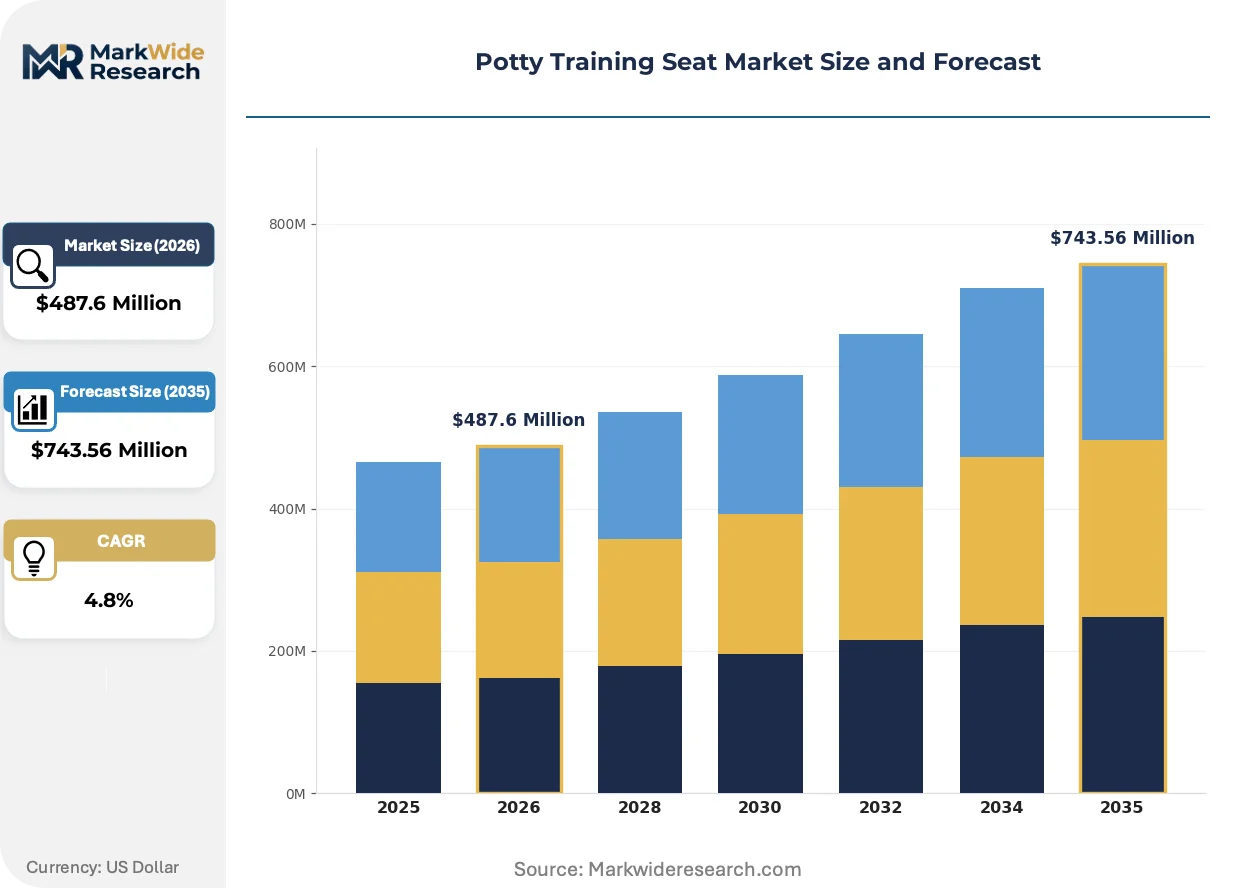
Market Dynamics
Dual-income households in China's tier-one cities are compressing bathroom footprints and demanding space-efficient, multifunctional potty training solutions that integrate step-stool functionality with ergonomic seating.
Growth Catalysts
- EU Safety Directives:EN 71-3 chemical migration limits are forcing material upgrades across soft-touch TPE components, creating premium tier expansion opportunities for compliant manufacturers.
- Daycare Infrastructure Modernization:Licensed childcare facilities in the United States are issuing bulk procurement tenders for ASTM F963-certified hygiene fixtures, institutionalizing volume demand.
- Injection Molding Scale Economics:Polypropylene processing advances are collapsing unit production costs for color-customized seats, enabling mass-market penetration in price-sensitive segments.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene resin prices fluctuate with crude oil benchmarks, compressing margin predictability for injection molders serving the plastic segment.
- Divergent Certification Burdens:India's BIS mandates IS 9873 testing distinct from ASTM F963 and REACH SVHC protocols, fragmenting compliance costs for exporters targeting multiple jurisdictions.
- Extended Product Lifecycles:Durable polypropylene construction enables 3-5 year usage spans per unit, limiting replacement frequency and aftermarket pad attachment revenue.
Strategic Opportunities
- California Proposition 65 Harmonization:State-level chemical disclosure requirements are creating first-mover advantage for brands preemptively adopting unified labeling across all North American shipments.
- Compact Urban Bathroom Convergence:Step-stool integrated multifunctional seats address square-footage constraints in Tokyo, Seoul, and Shanghai high-rise apartments.
- Direct-to-Consumer Channel Expansion:Subscription-based replacement pad programs bypass retail margin stacking and capture recurring revenue from ergonomic-conscious parents.
Industry Challenges
- Cross-Border Testing Redundancy:Manufacturers must duplicate mechanical integrity assessments under ASTM F963, EN 71-1, and IS 9873 frameworks, extending product launch timelines.
- Ergonomic Certification Talent Scarcity:Pediatric biomechanics expertise required for Scandinavian design heritage positioning commands premium compensation, constraining mid-tier R&D staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potty Training Seat Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adjustable Seats, Travel Seats, Multifunctional Seats, Non-slip Seats Material: Plastic, Wood, Foam, Silicone End User: Parents, Caregivers, Daycares, Pediatric Clinics Design Style: Character-themed, Minimalist, Ergonomic, Portable |
| Companies Covered | Munchkin, Prince Lionheart, BabyBjorn, Primo, Joovy, Fisher Price, Summer Infant, Bemis, Dreambaby, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potty Training Seat Market Evolving Landscape
Material science breakthroughs and regulatory tightening are compressing traditional product lifecycles while opening premium positioning pathways for certified ergonomic designs.
Thermoplastic elastomer overmolding is collapsing the functional boundary between rigid structural frames and soft-touch seating surfaces, enabling single-shot manufacturing that reduces assembly labor. Premium brands in Germany and Japan are adopting this process to achieve seamless hygiene profiles that resist bacterial colonization in crevices. The technology is collapsing the cost gap between economy plastic seats and mid-tier ergonomic alternatives.
REACH SVHC candidate list expansion is forcing reformulation of phthalate-based plasticizers in soft-touch components across European supply chains. Manufacturers serving EU markets are accelerating migration to bio-based TPE alternatives ahead of 2025 sunset dates for legacy chemistries. Small-batch producers in Poland and Portugal face disproportionate testing cost burdens relative to volume-scaled competitors.
Urban parents are abandoning standalone potty chairs in favor of toilet-mounted seats that eliminate separate cleaning protocols and floor-space occupation. Mass-market retailers in the United States are reducing SKU allocations for traditional floor potties, reallocating shelf space to multifunctional step-stool combinations. This behavioral pivot is most pronounced in metropolitan zip codes with sub-800 square foot average apartment sizes.
Potty Training Seat Market Segmentation
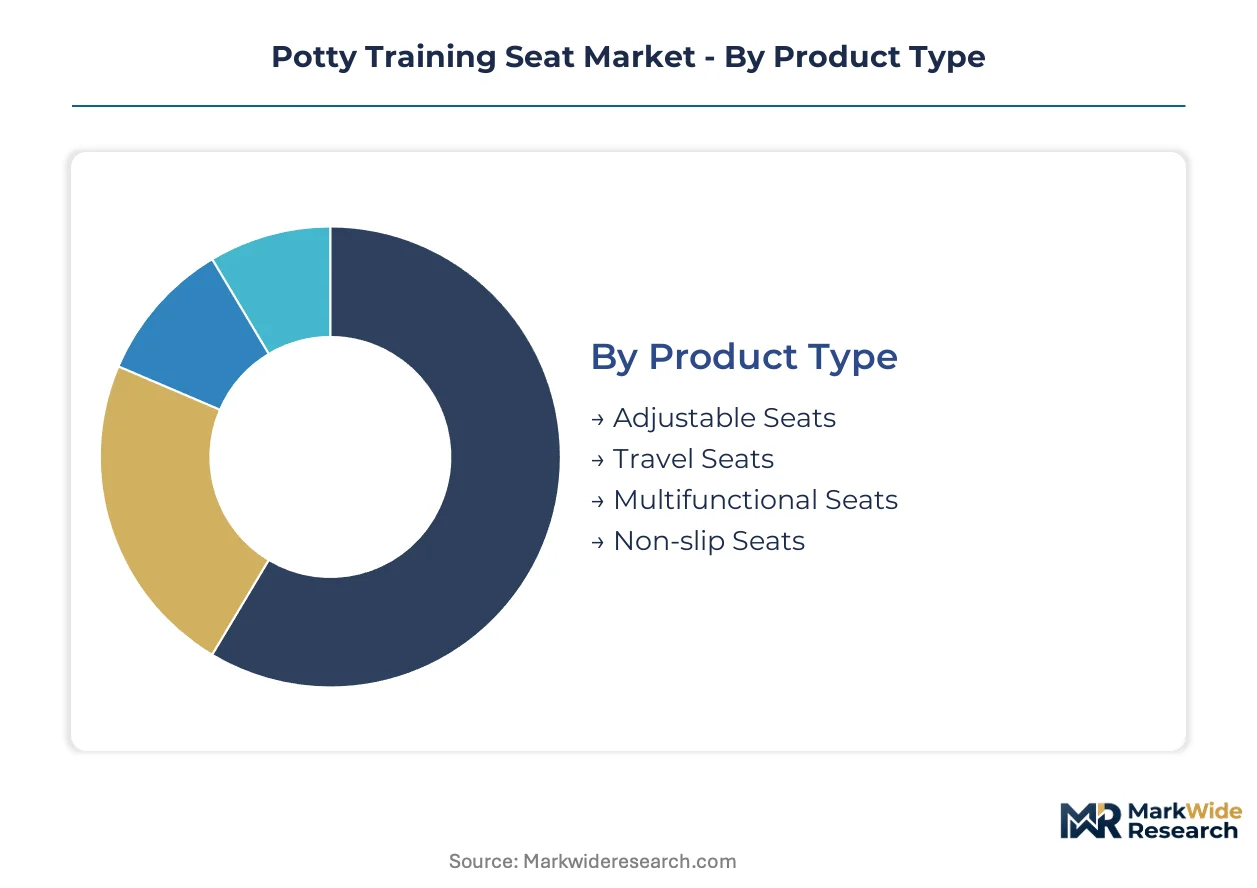
Product differentiation in the potty training seat market concentrates around installation geometry, material compliance thresholds, and end-use procurement patterns. Manufacturers calibrate SKU portfolios across these dimensions to capture recurring replacement revenue versus one-time household purchases.
Product Type:
Installation geometry and functional integration separate price tiers and determine retail shelf space allocation.
- Multifunctional Seats:These units combine toilet-mounted seating with integrated step-stool platforms, typically constructed from reinforced polypropylene with 50kg load ratings. Demand clusters in Shanghai, Tokyo, and Seoul high-rise apartments where bathroom footprints average under 4 square meters, compressing storage requirements for dual-purpose fixtures.
- Adjustable Seats:Hinged aperture mechanisms accommodate toilet bowl rim widths from 14 to 19 inches, manufactured with TPE overmolded contact surfaces for anti-slip stability. Daycare procurement tenders in the United States specify these for multi-fixture compatibility across aging infrastructure.
- Travel Seats:Collapsible silicone or TPE designs fold to sub-2-inch thickness for diaper bag portability.
- Non-slip Seats:Suction-cup or rubberized grip patterns address hard-surface bathroom flooring common in European rental units.
Multifunctional seats hold installed capacity. Travel seats are rotating up the share rankings.
Material:
Feedstock selection governs unit economics, color customization latitude, and regulatory compliance burden across export markets.
- Plastic:Injection-molded polypropylene dominates production volume due to 30-second cycle times and pigment flexibility, though REACH SVHC thresholds and California Proposition 65 disclosure requirements are forcing reformulation of legacy plasticizers in soft-touch variants.
- Silicone:Platinum-cured grades achieve FDA food-contact compliance and resist bacterial colonization in crevice-free designs, commanding premium positioning in German and Japanese direct-to-consumer channels where hygiene certification drives parental purchase decisions.
- Wood:Baltic birch and bamboo laminates serve Scandinavian aesthetic preferences with FSC chain-of-custody documentation.
- Foam:PU or EVA cushions provide transitional seating for children with sensory processing preferences.
Plastic holds installed capacity. Silicone is rotating up the share rankings.
End User:
Procurement authority and volume concentration shape pricing structures and certification documentation requirements.
- Daycares:Licensed childcare facilities issue bulk tenders for ASTM F963-certified units with institutional durability warranties, creating volume anchors for manufacturers with injection molding scale and third-party testing partnerships.
- Parents:Individual purchasers prioritize ergonomic certification and Scandinavian design heritage for single-unit transactions, driving premium tier expansion through direct-to-consumer subscription models for replacement pad attachments.
- Caregivers:Grandparent and nanny purchasers emphasize portability and simplified cleaning protocols.
- Pediatric Clinics:Occupational therapy practices specify biomechanically validated seating for developmental delay interventions.
Daycares hold installed capacity. Parents are rotating up the share rankings.
Design Style:
Aesthetic positioning and functional certification separate mass-market commoditization from premium margin capture.
- Ergonomic:Pediatric biomechanics validation and hip-angle certification command 3-4x unit price multiples, with German and Japanese manufacturers leveraging design heritage to sustain positioning against mass-market competitors.
- Minimalist:Neutral color palettes and concealed hardware align with contemporary bathroom fixture aesthetics in Copenhagen, Amsterdam, and Melbourne residential renovations.
- Character-themed:Licensed IP drives impulse purchase velocity in big-box retail.
- Portable:Ultra-lightweight construction targets air travel and multi-location caregiving.
Ergonomic holds installed capacity. Minimalist is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between markets prioritizing space efficiency and those emphasizing institutional durability. China's tier-one cities compress bathroom footprints below 4 square meters, while US daycare procurement drives volume through ASTM F963-certified bulk tenders. European parents demand REACH-compliant soft-touch materials, creating premium tier segmentation absent in price-sensitive emerging markets.
United States
Licensed childcare facilities anchor institutional demand through multi-unit procurement tenders specifying ASTM F963 mechanical integrity certification. The Consumer Product Safety Commission enforces phthalate restrictions that elevate testing costs for imported soft-touch components. Manufacturing clusters in Ohio and Pennsylvania supply injection-molded polypropylene seats to mass-market retailers, while California's Proposition 65 disclosure requirements fragment labeling protocols across state lines.
China
Shanghai, Beijing, and Shenzhen dual-income households drive premium ergonomic adoption as bathroom footprints shrink in high-rise residential towers. The State Administration for Market Regulation enforces GB standards for child product safety, creating parallel compliance tracks distinct from export-market certifications. Yangtze River Delta injection molders dominate polypropylene production scale, supplying both domestic multifunctional seat demand and contract manufacturing for European brands.
Germany
REACH SVHC thresholds and ECHA chemical migration limits force TPE reformulation in soft-touch seating surfaces, compressing margins for small-batch producers. Bavaria and Baden-Württemberg house precision molders serving Scandinavian design heritage brands with pediatric biomechanics certification. Berlin and Hamburg direct-to-consumer channels prioritize silicone overmolded seats with seamless hygiene profiles resistant to bacterial colonization.
India
Bureau of Indian Standards mandates IS 9873 testing distinct from ASTM and EN protocols, fragmenting export compliance burdens for multinational suppliers. Maharashtra and Gujarat manufacturing clusters supply plastic seats to price-sensitive domestic segments while building BIS certification capacity for premium tier expansion. Delhi-NCR and Bangalore dual-income households increasingly specify ergonomic designs as bathroom renovation spending rises.
Japan
METI product safety guidelines and JIS standards govern mechanical integrity testing for toilet-mounted seats in compact urban bathrooms. Tokyo and Osaka metropolitan areas concentrate demand for multifunctional step-stool combinations addressing sub-3-square-meter bathroom constraints. Kyushu-based molders specialize in platinum-cured silicone production for hygiene-critical direct-to-consumer channels serving design-conscious parents.
Potty Training Seat Market Competitive Landscape
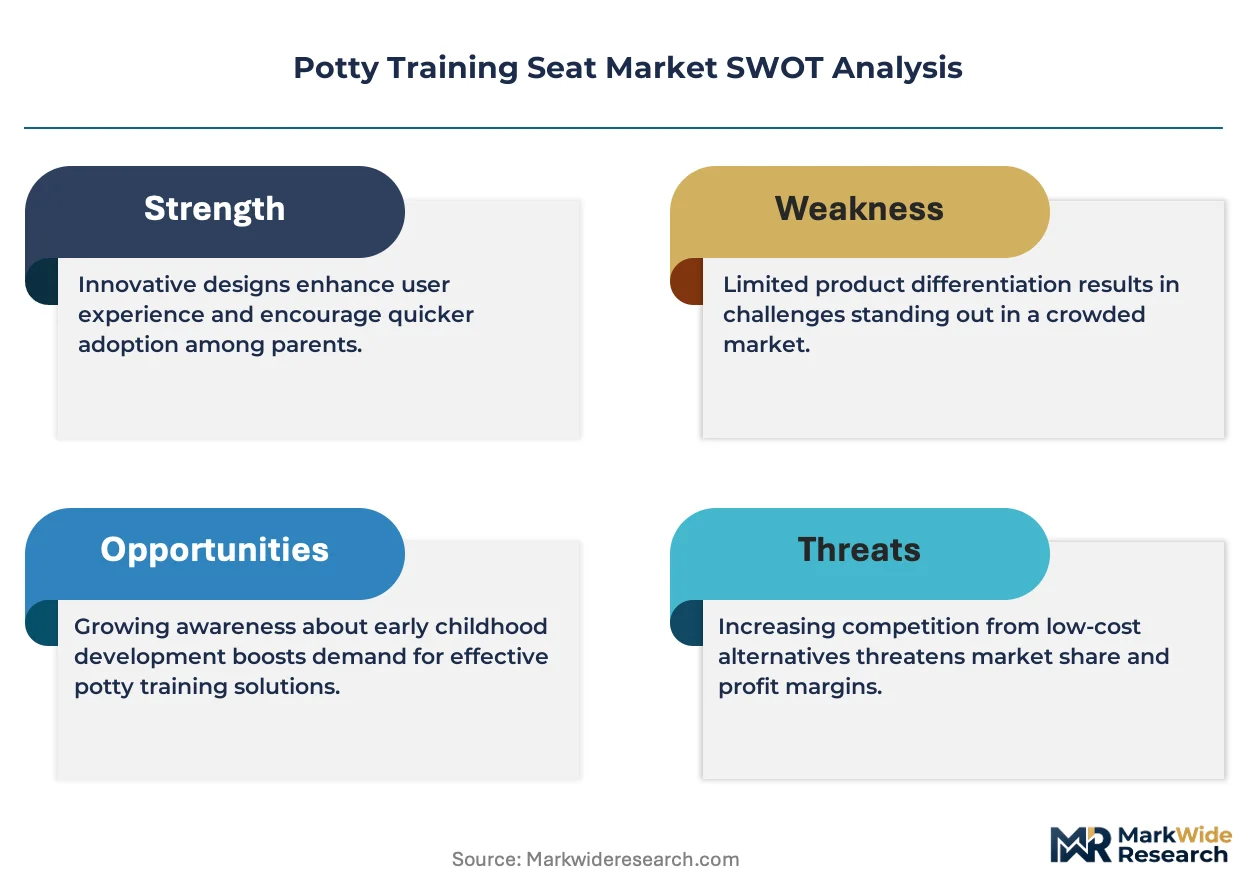
Capability concentration sits with ergonomic certification specialists; scale advantage sits with mass-market injection molders serving retail distribution. The market structures around three tiers: Scandinavian design heritage brands commanding 3-4x price multiples, broad-shelf-presence retailers capturing recurring consumable revenue, and contract manufacturers supplying private-label programs. Strategic moves concentrate on material compliance upgrades ahead of REACH sunset dates and direct-to-consumer channel expansion bypassing retail margin stacking.
Among heritage-positioned specialists, BabyBjorn anchors Scandinavian ergonomic certification, while Munchkin occupies mass-market retail scale. Summer Infant exemplifies price-accessible distribution through big-box channels. These three represent distinct competitive archetypes: design-premium, retail-scale-recurring, and value-positioned volume, each calibrating SKU portfolios around installation geometry, material compliance thresholds, and end-use procurement patterns.
| Leading Market Players |
|---|
| Munchkin |
| Prince Lionheart |
| BabyBjorn |
| Primo |
| Joovy |
| Fisher Price |
| Summer Infant |
| Bemis |
| Dreambaby |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta injection molders concentrate polypropylene capacity, capturing upstream margin pools that downstream brands must reclaim through ergonomic certification premiums or subscription-based replacement pad programs.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between mass-market retailers and Yangtze River Delta molders, insulating volume players from polypropylene resin volatility while spot-market exposure concentrates among small-batch ergonomic specialists. Three-tier pricing structure separates Scandinavian heritage brands commanding ergonomic certification premiums from mid-tier TPE overmolded alternatives and economy polypropylene seats sold through big-box channels. Cost compression in the economy tier is intensifying because REACH SVHC reformulation deadlines are collapsing the cost gap between rigid plastic and soft-touch variants. Daycare procurement officers exhibit lowest price sensitivity due to institutional durability warranties, while grandparent purchasers in price-sensitive segments drive volume through promotional velocity.
Supply Chain Analysis
Contract manufacturing concentrates with Yangtze River Delta polypropylene specialists, Bavaria precision molders serving ergonomic certification requirements, and Kyushu platinum-cured silicone producers for hygiene-critical direct-to-consumer channels. Feedstock dependencies center on propylene monomer from petrochemical complexes, TPE compounds requiring phthalate-free plasticizer reformulation, and platinum-cured silicone grades achieving FDA compliance. Single-source vulnerability runs through Yangtze River Delta concentration for injection-molded polypropylene capacity serving global volume demand. Distribution runs through mass-market retail shelf space allocation for economy tiers, direct-to-consumer subscription channels for replacement pad recurring revenue, and institutional procurement tenders for daycare volume anchors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market structures around regulatory entrenchment as the primary defensive moat, with BIS, ASTM F963, and REACH certification requirements creating switching costs that institutional buyers cannot easily circumvent.
For Market Incumbents: Insulate market position by accelerating backward integration into platinum-cured silicone production for hygiene-critical European and Japanese channels, and by locking multi-year ASTM F963 certification partnerships with US daycare procurement consortiums. Emerging Polish and Portuguese TPE reformulation specialists threaten mid-tier margin capture as REACH sunset dates approach. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer replacement pad subscription programs, where recurring revenue models bypass retail margin stacking and ergonomic-conscious parents demonstrate loyalty stickiness. White-space concentration sits in California Proposition 65 preemptive labeling for unified North American compliance, and in compact urban bathroom multifunctional seats for Seoul and Tokyo high-rise apartments. Go-to-market execution should prioritize pediatric biomechanics certification partnerships to access premium tier positioning. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier ergonomic specialists with existing EN 71-3 compliance infrastructure and scalable TPE overmolding capacity, as these assets capture margin expansion from REACH-driven material upgrades across European supply chains. Long-term viability favors players with dual certification tracks spanning ASTM F963 and BIS IS 9873 protocols. Monitor ECHA SVHC candidate list expansion velocity as the inflection signal for accelerated bio-based TPE migration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses retail margin stacking and captures recurring replacement pad revenue from ergonomic-conscious parents. |
| Backward Integration into Silicone Production | Secures captive supply of platinum-cured grades for hygiene-critical German and Japanese premium channels. |
| Multi-Jurisdiction Certification Investment | Builds BIS IS 9873, ASTM F963, and EN 71-3 parallel tracks to access institutional daycare tenders across three continents. |
| Compact Urban Bathroom Product Line Expansion | Addresses sub-4-square-meter constraints in Shanghai, Tokyo, and Seoul high-rise residential towers. |
| Bio-Based TPE Reformulation Partnership | Positions ahead of REACH 2025 sunset dates for legacy phthalate plasticizers in soft-touch seating surfaces. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with injection molding operations directors, daycare procurement managers, pediatric biomechanics certification specialists, and mass-market retail category buyers; and secondary validation through BIS certification registries, ASTM F963 compliance databases, ECHA SVHC candidate list updates, and customs trade records for polypropylene resin and finished seat imports. Bottom-up triangulation across manufacturing capacity surveys and top-down demand modeling across end-user segments anchored volume and value estimates.
Forecast inputs considered installation geometry evolution, material compliance threshold tightening across regulatory jurisdictions, and urban bathroom footprint compression in high-rise residential markets. Segmentation dimensions modeled include product type, material grade tier, end-user procurement authority, and design style positioning. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules across the analysis window. Industry-specific inputs incorporated REACH SVHC reformulation timelines and daycare infrastructure modernization tender pipelines.
Macroeconomic conditions sit as an overlay; deviation in crude oil benchmarks affecting polypropylene resin costs, dual-income household formation rates in Chinese tier-one cities, or childcare facility licensing velocity in the United States would shift the trajectory. Quarterly review of ECHA regulatory updates, BIS certification queue lengths, and Yangtze River Delta molder capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Feeding Pillow Market
Baby Products
Global Adaptive Strollers Market
Baby Products
South Africa Baby Care Products Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Baby Walker Market
Baby Products
LAMEA Baby Care Products Market
Baby Products
Baby Stroller Market
Baby Products
Maternity Products Market
Baby Products
Baby Care and Mother Care Market
Baby Products
Smart Bottle Warmers Market
Baby Products
Netherlands Baby Care Products Market
Baby Products
Crib Mattress Market
Baby Products
Baby Gift Basket Market
Baby Products
Home Care Packaging Market
Baby Products
Baby Bottle Holder Market
Baby Products
Baby Cradles Market