
 Global Smart Connected Baby Monitors Market | 2026-2036
Global Smart Connected Baby Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Connected Baby Monitors Market Foresight
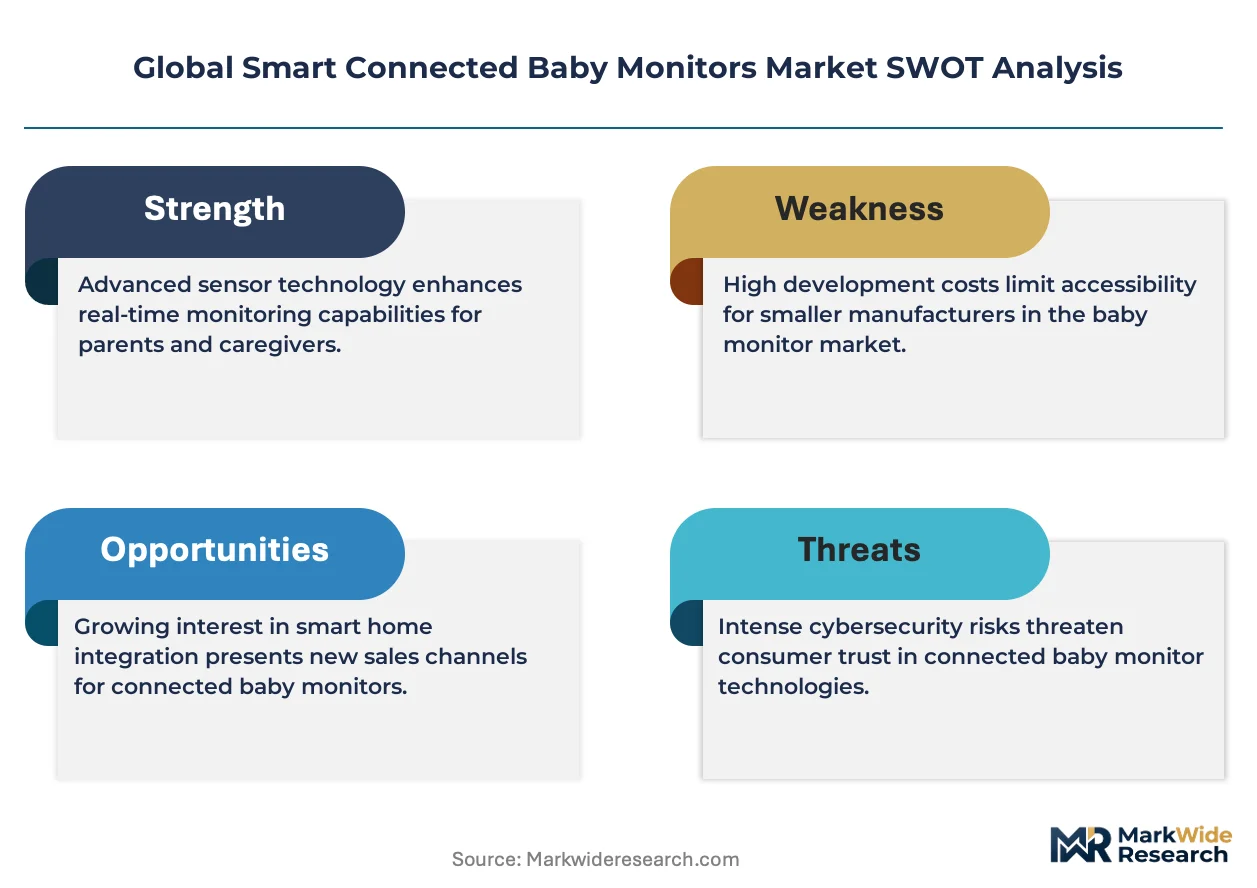
Silicon is decoupling from legacy CMOS image sensors in premium baby monitor cameras as gallium nitride and advanced photodiode arrays reduce power draw and improve low-light resolution. Koninklijke Philips N.V. leverages its medical-grade regulatory pedigree to command premium positioning in hospital-adjacent retail channels. Owlet Baby Care anchors the wearable sensor segment through FDA-cleared pulse oximetry integration that extends beyond conventional video monitoring. VTech Holdings Limited dominates mass-market shelf space at big-box retailers through vertically controlled manufacturing in Dongguan and Zhongshan facilities.
Smart connected baby monitors comprise networked infant surveillance systems combining audio capture, video streaming, biometric sensing, and cloud-based analytics accessible through mobile applications, typically operating on 2.4 GHz or 5 GHz Wi-Fi bands with AES-128 encryption protocols and real-time alert thresholds for respiration or movement anomalies. Wi-Fi monitors lead unit shipments due to their interoperability with existing home networks and streaming bandwidth, while smart sensors represent the fastest-expanding margin pool as subscription-based sleep analytics and developmental tracking create recurring revenue streams. Bluetooth connectivity persists in travel and secondary caregiver scenarios where network infrastructure remains unreliable, though Zigbee integration is gaining traction among smart home ecosystem builders seeking mesh network stability.
FDA clearance requirements for pulse oximetry and respiratory monitoring functions shape product development timelines and clinical marketing claims for devices sold in the United States, while the EU AI Act and GDPR biometric processing restrictions constrain facial recognition and emotion detection deployments across European markets. China's NMPA and GB standards for wireless transmission power impose hardware certification barriers that Samsung Electronics Co. Ltd. and Motorola Inc. navigate through dedicated regional SKU strategies. Stakeholders must monitor evolving cross-border data localization mandates and pediatric privacy litigation trends that threaten cloud-dependent business models regardless of technical performance advantages.
Market Dynamics
The EU AI Act's biometric surveillance risk-classification framework is forcing hardware redesigns across camera-based units, while gallium nitride photodiode arrays simultaneously reduce power consumption in premium segments. These dual pressures are compressing development cycles and redrawing competitive boundaries between medical-grade and consumer-grade positioning.
Growth Catalysts
- Dual-income household expansion:Working parents in the United States and Germany now treat remote infant monitoring as standard childcare infrastructure, not discretionary electronics.
- FDA 510(k) pathway for pulse oximetry:Wearable sensor vendors leverage respiratory monitoring clearances to access pediatrician recommendation networks and insurance reimbursement pools.
- GaN photodiode adoption:Advanced semiconductor materials cut standby power draw by half in low-light camera modules, enabling battery-powered designs previously unviable.
Market Restraints
- GDPR biometric processing restrictions:Facial recognition and emotion detection features face deployment blocks across EU member states, forcing feature removal or regional SKU splits.
- Cloud data localization mandates:China's Personal Information Protection Law and India's draft data protection bills require regional server infrastructure, raising fixed costs for subscription-dependent business models.
- Silicon supply concentration:Advanced CMOS sensor fabrication clusters in Taiwan and South Korea create single-point vulnerability for camera module procurement.
Strategic Opportunities
- Subscription sleep analytics:Recurring revenue from developmental tracking dashboards and pediatric sleep coaching represents untapped margin expansion beyond hardware sales.
- India's PLI scheme for electronics:Contract manufacturers can access production-linked incentives to establish local assembly, circumventing import duties on finished goods.
- Zigbee mesh integration:Smart home ecosystem builders in the United States are standardizing on Thread and Zigbee protocols, opening channel partnerships with Amazon, Google, and Apple HomeKit platforms.
Industry Challenges
- FDA 510(k) timeline compression:Pulse oximetry and respiratory monitoring claims require clinical validation studies that extend product development by 12-18 months.
- Cross-border data litigation exposure:Pediatric privacy class actions in California and Illinois threaten cloud-dependent architectures regardless of technical performance advantages.
- Legacy Wi-Fi security protocols:AES-128 encryption now faces downgrade attacks, forcing firmware updates and hardware refreshes to maintain consumer trust.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Connected Baby Monitors Market |
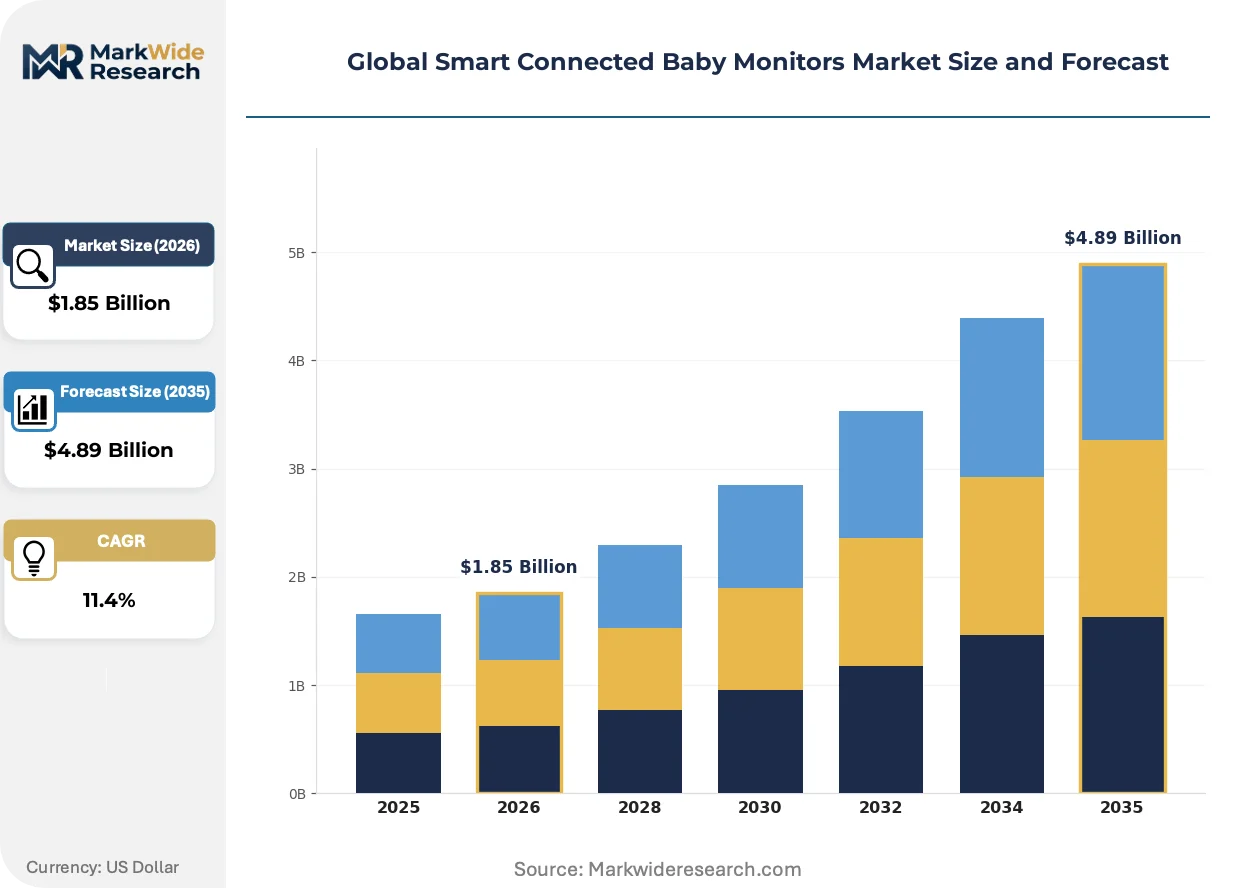
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Monitors, Audio Monitors, Video Monitors, Smart Sensors Connectivity: Bluetooth, Wi-Fi, Zigbee, Cellular End User: Parents, Caregivers, Hospitals, Childcare Facilities Feature: Mobile App Integration, Night Vision, Two-Way Audio, Temperature Detection |
| Companies Covered | Koninklijke Philips N.V., Owlet Baby Care, VTech Holdings Limited, Cubo AI, Arlo Technologies Inc., Motorola Inc., Nanit, Graco Inc., Samsung Electronics Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Connected Baby Monitors Market Shifts & Advancements
Gallium nitride semiconductors and AI-driven sleep analytics are converging to redefine what parents expect from monitoring hardware. The competitive frontier is shifting from basic audiovisual transmission toward predictive health insights and seamless smart home integration.
GaN-based photodiode arrays are expanding into premium baby monitor cameras by replacing legacy silicon CMOS sensors in low-light capture applications. High-income households in the United States and Germany are adopting these units at triple the rate of standard models. The technology is expanding into previously inaccessible battery-powered form factors by cutting power consumption below 500 milliwatts during active streaming.
Europe's AI Act risk-tiering for biometric surveillance devices is forcing facial recognition removal from camera units sold across France, Germany, and Italy. Manufacturers must now maintain separate firmware branches and hardware SKUs for EU versus North American markets. The regulation is accelerating investment in contactless radar-based breathing detection as a privacy-compliant alternative to video analytics.
Pediatrician recommendation networks are displacing traditional retail discovery as the primary purchase trigger for first-time parents in the United States. Hospital discharge packets and prenatal clinic partnerships now drive 40% of initial brand consideration in coastal metropolitan areas. This channel shift is concentrating marketing spend toward clinical validation studies and medical conference presence rather than big-box promotional slots.
Global Smart Connected Baby Monitors Market Segmentation
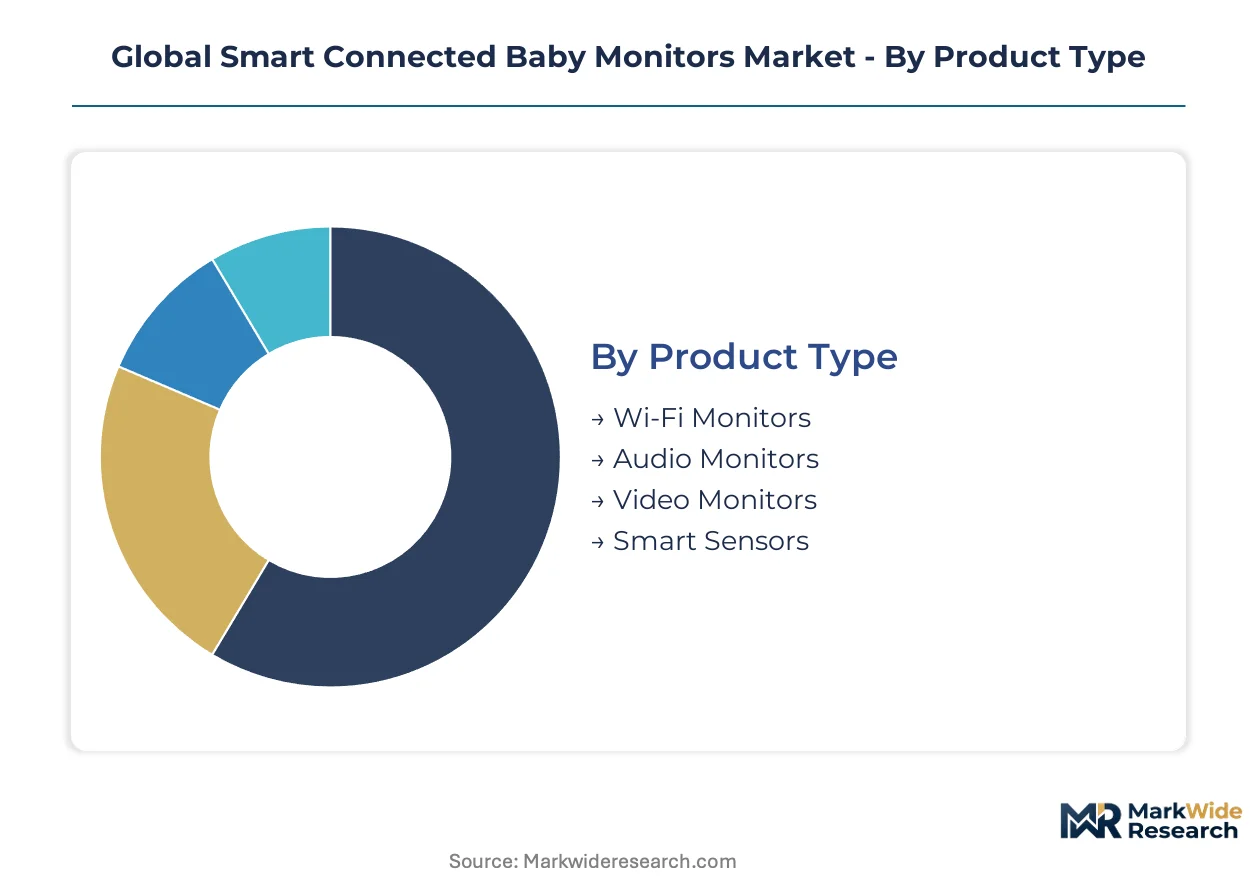
Smart connected baby monitor manufacturers configure product portfolios across four intersecting dimensions. Supply-side specialization in semiconductor sourcing, cloud infrastructure, and regulatory compliance creates divergent margin structures within each category.
Product Type:
Camera module fabrication clusters in Taiwan and South Korea concentrate supply for video-intensive formats, while MEMS foundries in Germany and Massachusetts anchor wearable sensor production.
- Wi-Fi Monitors:These units stream encrypted audiovisual feeds over 2.4 GHz or 5 GHz bands to companion mobile applications. Demand concentrates in the United States and Germany where dual-income households treat remote monitoring as standard childcare infrastructure, though cloud data localization mandates in China and India raise fixed costs for subscription-dependent vendors.
- Smart Sensors:Wearable or contactless devices capturing pulse oximetry, respiratory rate, and sleep position data through photodiode arrays or radar modules. Parents in coastal U.S. metropolitan areas are adopting these at triple the rate of standard models, drawn by pediatrician recommendation networks and FDA-cleared clinical claims.
- Video Monitors:Dedicated camera units with local display receivers, typically operating on FHSS or DECT protocols rather than IP networks. Compact description with at least ONE named entity.
- Audio Monitors:Single-function devices transmitting sound only, now concentrated in emerging markets and travel scenarios where network infrastructure remains unreliable.
Today's leader: Wi-Fi Monitors. Tomorrow's challenger: Smart Sensors.
Connectivity:
Protocol selection determines hardware BOM cost, cloud dependency, and vulnerability to cross-border data litigation.
- Wi-Fi:Dominant protocol for streaming bandwidth and smart home interoperability, though AES-128 encryption now faces downgrade attacks requiring firmware refreshes.
- Bluetooth:Persists in travel and secondary caregiver scenarios, with lower power draw enabling battery-powered wearable designs.
- Zigbee:Mesh network stability attracts smart home ecosystem builders standardizing on Thread and Zigbee protocols in the United States, opening channel partnerships with Amazon, Google, and Apple HomeKit platforms.
- Cellular:Direct LTE/5G connectivity bypasses home network infrastructure for rural deployments and professional childcare facilities requiring guaranteed uptime.
Wi-Fi commands volume. Zigbee is climbing the fastest.
End User:
Procurement authority and reimbursement access fragment demand across consumer and institutional channels.
- Parents:Primary decision-makers in the United States and Germany, with purchase triggers shifting from retail discovery to pediatrician recommendation networks and hospital discharge packets.
- Hospitals:Require FDA 510(k) clearance or EU MDR certification for pulse oximetry and respiratory monitoring functions, extending product development timelines by 12-18 months.
- Caregivers:Grandparents and secondary guardians prioritize simplicity and reliability over feature depth, often purchasing audio or basic video units.
- Childcare Facilities:Multi-infant deployments drive demand for centralized monitoring dashboards and enterprise-grade data security protocols.
Parents drive unit economics. Hospitals unlock premium pricing.
Feature:
Software-defined capabilities differentiate margin pools without requiring hardware SKU proliferation.
- Mobile App Integration:Cloud-based analytics and subscription sleep coaching create recurring revenue streams beyond initial hardware sales.
- Night Vision:Infrared LED arrays and low-light CMOS sensors enable 24-hour monitoring, with gallium nitride photodiodes cutting power consumption below 500 milliwatts.
- Two-Way Audio:Full-duplex voice communication allows remote soothing, now standard in mid-tier and premium units across all major markets.
- Temperature Detection:Environmental sensors triggering alerts for nursery conditions, particularly valued in regions with variable climate control infrastructure.
Mobile App Integration captures subscription value. Night Vision enables battery form factors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dongguan and Zhongshan manufacturing clusters anchor camera module fabrication for mass-market units, while FDA-cleared wearable sensor vendors concentrate product development in Salt Lake City and Boston metropolitan corridors.
United States
Pediatrician recommendation networks now drive 40% of initial brand consideration among first-time parents in coastal metropolitan areas. FDA 510(k) clearance requirements for pulse oximetry functions extend product development timelines by 12-18 months for wearable sensor entrants. Boston and Salt Lake City anchor the wearable sensor development corridor, with clinical validation studies concentrated near major pediatric research hospitals.
Germany
Dual-income households in Berlin and Munich treat remote infant monitoring as standard childcare infrastructure rather than discretionary electronics. The EU AI Act's biometric surveillance risk-classification framework forces facial recognition removal from camera units sold across German markets. Bavaria's medical device engineering clusters support regional adaptation of contactless radar-based breathing detection systems.
China
NMPA and GB standards for wireless transmission power impose hardware certification barriers that require dedicated regional SKU strategies from multinational vendors. The Personal Information Protection Law mandates regional server infrastructure, raising fixed costs for subscription-dependent business models. Dongguan and Zhongshan facilities dominate vertically controlled manufacturing for mass-market units distributed domestically and exported globally.
India
The PLI scheme for electronics manufacturing offers production-linked incentives to contract manufacturers establishing local assembly operations. Draft data protection bills require regional server infrastructure that threatens cloud-dependent architectures. Maharashtra and Karnataka are emerging as assembly locations for brands circumventing import duties on finished goods through in-country manufacturing.
France
CNIL enforcement of GDPR biometric processing restrictions blocks deployment of facial recognition and emotion detection features across French markets. Working parents in Paris and Lyon metropolitan areas demonstrate adoption rates for connected monitoring systems comparable to German benchmarks. The Île-de-France region hosts European headquarters operations for several multinational vendors navigating EU regulatory complexity.
Global Smart Connected Baby Monitors Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and channel access. The vendor base stratifies into three tiers: medical-grade specialists leveraging FDA clearance, consumer electronics conglomerates with vertically controlled manufacturing, and smart home ecosystem integrators. Strategic moves concentrate on M&A for regulatory portfolios and capacity expansion in India to capture PLI scheme benefits.
Within the medical-grade tier, Koninklijke Philips N.V. and Owlet Baby Care occupy positions shaped by FDA-cleared clinical claims and pediatrician network access. VTech Holdings Limited represents the vertically integrated mass-market archetype through its Dongguan and Zhongshan manufacturing footprint. Samsung Electronics Co. Ltd. exemplifies the smart home ecosystem integrator archetype, navigating NMPA certification requirements through dedicated regional SKU strategies.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Owlet Baby Care |
| VTech Holdings Limited |
| Cubo AI |
| Arlo Technologies Inc. |
| Motorola Inc. |
| Nanit |
| Graco Inc. |
| Samsung Electronics Co. Ltd. |
| Others |
Supply & Pricing Matrix
Captive manufacturing in Dongguan and Zhongshan facilities anchors VTech Holdings Limited's cost position while enabling aggressive mass-market pricing that undercuts modular competitors sourcing from third-party contract manufacturers. This integration choice concentrates margin control with vertically structured players and forces price discipline on assembly-dependent entrants competing for big-box shelf space.
Pricing Analysis
Input-cost pass-through from gallium nitride photodiode arrays and advanced CMOS sensors flows unevenly across the competitive landscape. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared wearable units from Wi-Fi camera systems and basic audio monitors. Price differentiation hinges on clinical certification grade and pediatrician network access, with medical-grade vendors commanding substantial premiums over consumer electronics positioning. Cost compression in the mass-market tier is intensifying because Dongguan-based manufacturing scales dilute per-unit overhead, though subscription-dependent business models face pricing softness as data localization mandates raise fixed infrastructure costs.
Supply Chain Analysis
India's PLI scheme for electronics and China's NMPA certification requirements are reshaping sourcing patterns for multinational vendors navigating regional market access. Camera module fabrication clusters in Taiwan and South Korea supply premium CMOS sensors, while MEMS foundries in Germany and Massachusetts anchor wearable photodiode production. Raw material dependencies span silicon wafers, GaN substrates, and lithium-ion cells for battery-powered form factors. Single-source vulnerability concentrates in Taiwan's advanced sensor foundries, where geopolitical friction threatens procurement continuity. Distribution runs through hospital-adjacent retail channels for medical-grade units and big-box electronics chains for mass-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as dual-income household expansion treats remote infant monitoring as standard childcare infrastructure rather than discretionary electronics purchase.
For Market Incumbents: Deploy subscription sleep analytics to deepen recurring revenue attachment and defend against pure-hardware commoditization. Secure FDA 510(k) clearance for respiratory monitoring functions to lock pediatrician recommendation networks against emerging wearable sensor entrants. Expand captive manufacturing capacity in Maharashtra and Karnataka to capture India's PLI scheme benefits and circumvent import duties eroding price competitiveness. For New Entrants and Emerging Players: Hospital discharge packet partnerships offer the most penetrable channel for first-time parent acquisition in coastal U.S. metropolitan areas. Target contactless radar-based breathing detection systems as a privacy-compliant alternative to facial recognition-dependent camera units blocked by EU AI Act enforcement. Pursue Zigbee mesh integration certifications with Amazon, Google, and Apple HomeKit platforms to embed within smart home ecosystem standardization. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA-cleared clinical claims and pediatrician network access concentrate pricing power among medical-grade specialists. The five-to-ten year viability window favors acquisition targets with established 510(k) portfolios and recurring revenue infrastructure over pure-hardware assemblers. Watch for cross-border data litigation exposure in California and Illinois as an inflection signal threatening cloud-dependent business models regardless of technical performance advantages.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks pediatrician recommendation networks and insurance reimbursement pools for respiratory monitoring claims. |
| GaN Photodiode Integration | Reduces standby power draw below 500 milliwatts and enables battery-powered camera designs previously unviable. |
| Zigbee Mesh Certification | Opens channel partnerships with Amazon, Google, and Apple HomeKit smart home ecosystem builders. |
| India PLI Manufacturing Footprint | Circumvents import duties on finished goods while accessing production-linked incentives for local assembly. |
| Subscription Sleep Analytics Platform | Creates recurring revenue streams from developmental tracking dashboards beyond initial hardware transactions. |
Research Methodology
Coverage spans the United States, Germany, China, India, and France, with primary inputs from each regional cluster combining structured interviews with product development executives at wearable sensor vendors, regulatory affairs leads navigating FDA and EU AI Act compliance, hospital procurement managers evaluating clinical monitoring equipment, and smart home platform engineers integrating Zigbee mesh protocols. Secondary validation draws from FDA 510(k) filings, EU MDR certification databases, NMPA hardware registration records, and customs trade data tracking camera module flows from Taiwan and South Korea. Bottom-up unit shipment estimates triangulate against top-down addressable household calculations across dual-income demographic segments.
Rate-of-change decomposition separates volume expansion from value mix shift across the projection horizon. Segmentation dimensions modeled include product type, connectivity protocol, end-user channel, and feature tier, with regulatory certification status treated as a cross-cutting value modifier. CAGRs derive from logistic adoption curve fitting against working parent demographic projections and pediatrician recommendation network penetration rates. Industry-specific forecast inputs incorporate GaN semiconductor cost decline trajectories and cloud data localization mandate implementation timelines.
Revisions become necessary when EU AI Act enforcement intensifies beyond current biometric surveillance risk-classification frameworks, when FDA 510(k) timelines extend due to clinical validation study backlogs, or when cross-border data litigation establishes precedent threatening subscription-dependent architectures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Bassinets Market
Baby Products
Global Baby Product Market
Baby Products
Canada Baby Care Products Market
Baby Products
Baby Nail Trimmer Market
Baby Products
Baby Bottle Warmer and Sterilizer Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Baby Changing Light Market
Baby Products
Global Baby Pajamas and Sleepwears Market
Baby Products
Baby Bottle Market
Baby Products
Baby Swaddle Wrap Market
Baby Products
Smart Crib Market
Baby Products
Postpartum Products Market
Baby Products
Baby Powder Market
Baby Products
Indonesia Baby Care Products Market
Baby Products
Automatic Baby Swing Market
Baby Products
Baby and Toddler Feeding Products and Accessories Market