
 Portable Cribs Market | 2026-2036
Portable Cribs Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Cribs Market Analytics
Buyer concentration among millennial and Gen Z parents is recalibrating how manufacturers allocate R&D budgets toward compact, app-integrated designs. Graco Children's Products Inc. leverages its deep retail partnerships and broad playard portfolio to sustain shelf dominance across mass-market channels. Delta Children anchors its position through vertical control over wood sourcing and domestic assembly capacity for folding cribs. Million Dollar Baby Co. differentiates via premium material positioning and specialty retail presence in urban markets.
A portable crib constitutes a collapsible or foldable infant sleeping enclosure designed for temporary use, typically constructed with aluminum tubing, mesh sidewalls, or finished wood slats meeting ASTM F406 and CPSC 16 CFR 1220 structural integrity thresholds; its primary commercial purpose is to provide safe, transportable sleep environments for infants aged zero to thirty-five months in homes, travel settings, and temporary care facilities. Playard configurations dominate volume due to multifunctional demand spanning sleep and contained play, while travel cribs capture the fastest expansion as remote work patterns extend family mobility. Fabric and mesh materials lead feature-driven purchasing for breathability and reduced weight, though solid wood segments retain margin concentration among buyers seeking durability and aesthetic integration with home furnishings.
The US Consumer Product Safety Commission enforces mandatory crib standards under 16 CFR 1219 and 1220, while ASTM International maintains voluntary F406 and F1169 protocols that most retailers treat as de facto market access requirements; the EU's General Product Safety Directive and harmonized EN 716 standards impose parallel conformity obligations for exporters. Health Canada's Consumer Product Safety Act and Cribs, Cradles and Bassinets Regulations add a third compliance layer for North American suppliers. Stakeholders must monitor evolving chemical restrictions under state-level frameworks such as Washington's Children's Safe Products Act and track how California's Proposition 65 litigation patterns reshape material specifications across supplier networks.
Market Dynamics
Millennial and Gen Z parents are compressing product lifecycles through preference for modular, travel-ready designs that collapse into carry-on dimensions. This demographic pivot is forcing manufacturers to retool assembly lines toward aluminum-tubing fabrication and app-integrated monitoring features.
Growth Catalysts
- ASTM F406 Standards Harmonization:Voluntary protocols adopted by major retailers as de facto entry requirements are streamlining compliance costs for cross-border suppliers.
- Remote Work Mobility:Extended family travel patterns are accelerating replacement cycles for traditional stationary cribs with collapsible alternatives.
- Aluminum Tubing:Lightweight corrosion-resistant framing is displacing steel in mid-tier manufacturing, reducing unit shipping weights by substantial margins.
Market Restraints
- Solid Wood Input Volatility:Finished hardwood slat pricing fluctuates with North American lumber futures, compressing margin stability for domestic assemblers.
- Mesh Supplier Concentration:Breathable fabric sidewall production clusters in Southeast Asian textile hubs, creating single-source vulnerability for Western brands.
- California Proposition 65:Chemical disclosure litigation patterns are forcing preemptive material reformulation across supplier networks regardless of actual hazard presence.
Strategic Opportunities
- Subscription Rental Channels:Urban millennial parents in dense metropolitan markets are adopting short-term lease models for temporary sleep solutions.
- EU Green Deal Alignment:Circular economy packaging mandates and recycled content thresholds favor suppliers with established sustainability credentials.
- Sensor-Textile Convergence:Integration of respiratory monitoring fabrics with collapsible frames opens premium positioning in safety-conscious segments.
Industry Challenges
- Multi-Jurisdiction Certification:Simultaneous compliance with CPSC 16 CFR 1220, EN 716, and Health Canada regulations extends product launch timelines by 8-14 months.
- Legacy Retail Inventory Reconciliation:Mass-market channel partners maintain rigid seasonal buying calendars that misalign with direct-to-consumer velocity patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Cribs Market |
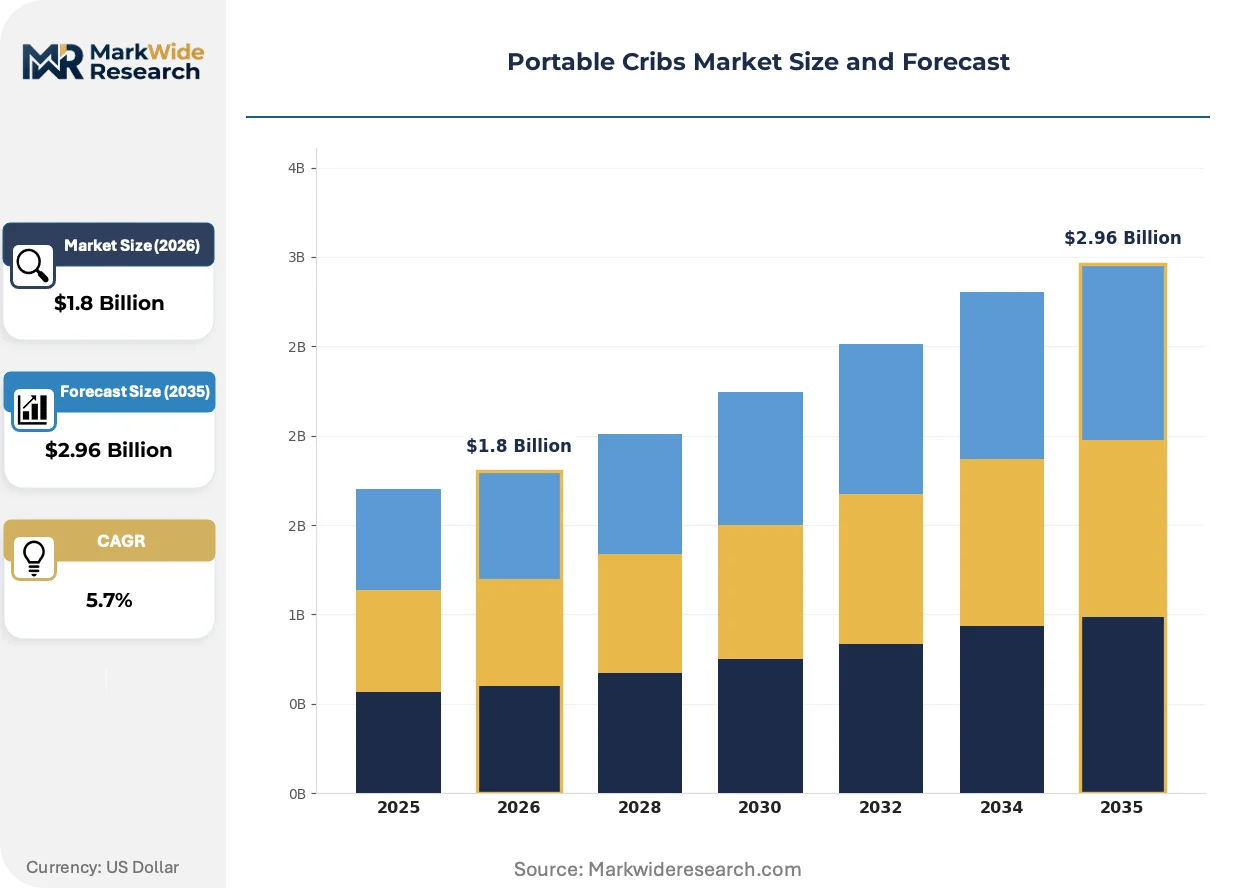
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Playard, Travel Crib, Folding Crib, Bassinet Material: Wood, Metal, Fabric, Plastic End User: Parents, Caregivers, Childcare Centers, Family Services Features: Portable, Lightweight, Adjustable, Easy Assembly |
| Companies Covered | Graco Children's Products Inc., Delta Children, Storkcraft Manufacturing Inc., Million Dollar Baby Co., Dream On Me Inc., Kolcraft Enterprises Inc., 4moms, Happiest Baby, Inc., HALO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Cribs Market Evolving Landscape
Product architecture is bifurcating between ultra-light travel configurations and premium wood-finished folding designs. This split is fragmenting R&D investment and reshaping how suppliers configure their manufacturing footprints.
Magnetic quick-release locking hardware is consolidating around a single dominant patent pool held by European component suppliers. Mid-tier manufacturers are licensing these mechanisms to avoid engineering redundancy. The technology is consolidating assembly labor into fewer specialized facilities with automated riveting stations.
Washington State's Children's Safe Products Act is expanding chemical disclosure requirements beyond federal baselines. Suppliers must now document flame retardant and phthalate content through third-party testing. Fabric and foam component vendors are most affected, with several reformulating adhesives to preempt enforcement actions.
Direct-to-consumer channels are capturing preference share from traditional baby specialty retailers. Millennial buyers research ASTM certification marks independently before purchasing. This pattern is most visible in coastal United States metropolitan markets where showroom traffic has declined substantially.
Portable Cribs Market Segmentation
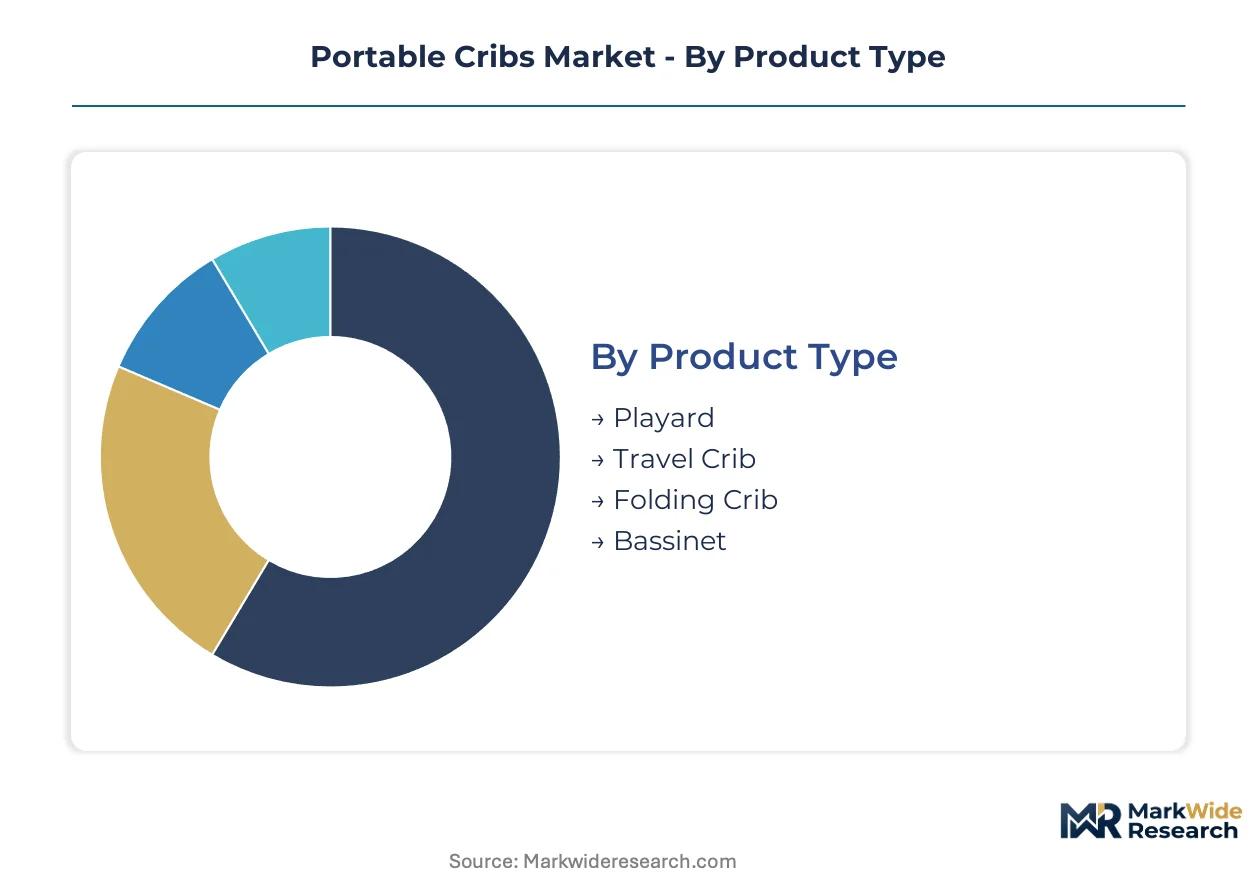
Portable cribs fragment across four distinct dimensions that determine manufacturing configuration and channel strategy. Product architecture and material selection drive unit economics, while end-user concentration and feature prioritization shape pricing power and replacement cycles.
Product Type:
Volume concentrates in multifunctional configurations, while premium positioning clusters around specialized mobility solutions.
- Playard:Enclosed mesh-sided structures with integrated bassinet inserts and changing stations dominate mass-market volume through dual sleep-play functionality. Demand concentrates among suburban dual-income households seeking extended-use nursery furniture, constrained by seasonal retail buying calendars that misalign with direct-to-consumer velocity.
- Travel Crib:Ultra-light aluminum-tubing frames engineered for carry-on dimensional compliance capture the steepest expansion trajectory. Millennial parents in coastal United States metropolitan markets drive preference for collapsible designs supporting remote-work family mobility.
- Folding Crib:Hinged wood or metal frames with locking hardware provide semi-permanent sleep solutions for secondary residences. Grandparent households and vacation rental operators represent core demand clusters.
- Bassinet:Compact bedside sleepers with limited weight capacity serve zero-to-four-month age windows. Hospital discharge gift registries and urban apartment dwellers prioritize space-minimal designs.
Mature deployment sits with Playard configurations. Newer deployment is concentrated in Travel Crib segments.
Material:
Input cost volatility separates margin-stable from margin-compressed manufacturing strategies.
- Wood:Finished hardwood slats meeting ASTM F1169 structural thresholds anchor premium positioning through aesthetic integration with home furnishings. North American lumber futures volatility compresses margin stability for domestic assemblers dependent on solid wood inputs.
- Metal:Aluminum tubing fabrication displaces steel in mid-tier production, reducing unit shipping weights substantially. Corrosion-resistant framing enables lightweight travel configurations demanded by mobile millennial parents.
- Fabric:Breathable mesh sidewalls and textile components dominate feature-driven purchasing for reduced weight and ventilation. Southeast Asian textile hub concentration creates single-source vulnerability for Western brands.
- Plastic:Injection-molded base frames and connector hardware provide cost-optimized structural elements. Mass-market channel partners specify plastic-heavy configurations for entry-price positioning.
Established supply relationships concentrate in Metal and Fabric segments. Emerging qualification requirements are reshaping Plastic sourcing.
End User:
Purchase authority and volume scale diverge sharply across institutional and consumer channels.
- Parents:Millennial and Gen Z first-time buyers research ASTM certification marks independently before purchasing. Direct-to-consumer channels capture preference share from traditional baby specialty retailers in dense metropolitan markets.
- Caregivers:Extended family members and temporary guardians prioritize rapid assembly and compact storage. Replacement cycles accelerate as multigenerational caregiving arrangements expand.
- Childcare Centers:Licensed facilities mandate compliance with CPSC 16 CFR 1220 and state-specific ratios for sleep equipment. Procurement runs through group purchasing organizations with rigid specification requirements.
- Family Services:Government and nonprofit temporary housing programs demand durable, sanitizable designs with audit-compliant safety documentation. Budget constraints favor metal-framed configurations over wood alternatives.
Volume concentration sits with Parents. Procurement formalization is advancing fastest in Childcare Centers.
Features:
Feature bundling determines retail shelf positioning and margin capture across channel tiers.
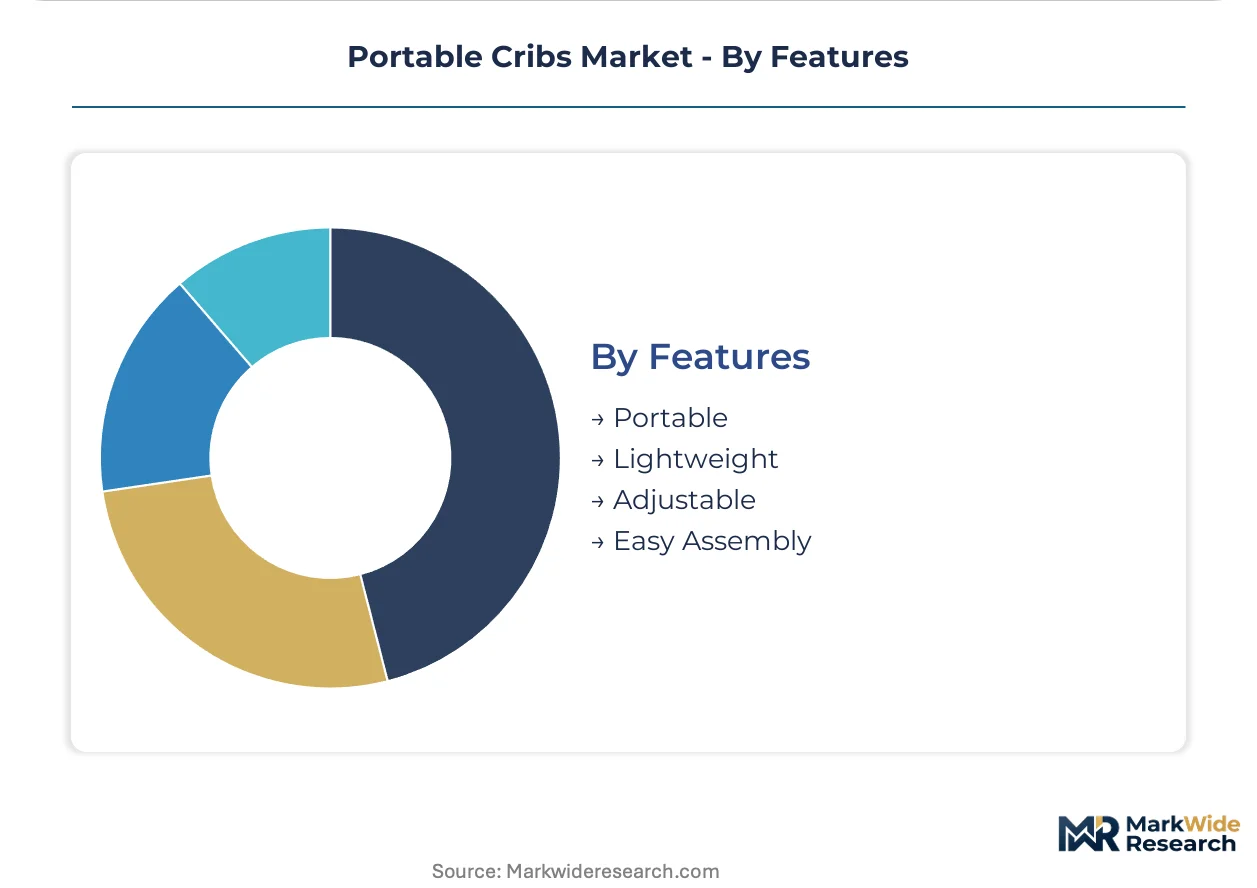
- Portable:Collapsible frames with carry bags and travel cases constitute baseline market entry requirements. Retailers treat portable certification as de facto access condition.
- Lightweight:Sub-seven-kilogram total unit weight enables single-parent transport and airline gate-check compliance. Aluminum tubing investment separates compliant from non-compliant suppliers.
- Adjustable:Multi-position mattress heights and convertible bassinet-crib configurations extend product lifecycle value. Premium positioning commands measurable price premiums in specialty retail.
- Easy Assembly:Tool-free locking mechanisms and color-coded connection points reduce return rates and customer service burden. Magnetic quick-release hardware licensing consolidates around European patent pools.
Universal deployment sits with Portable and Easy Assembly. Premium differentiation concentrates in Lightweight and Adjustable combinations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dual-income households in the United States concentrate portable crib demand through space-saving nursery priorities. Millennial parents across coastal metropolitan areas accelerate preference for travel-ready collapsible designs. Regulatory harmonization between CPSC, EU, and Health Canada standards shapes cross-border supplier strategies.
United States
Suburban dual-income households drive Playard volume through extended-use sleep-play functionality. CPSC 16 CFR 1220 enforcement maintains strict structural integrity thresholds for domestic market access. Dallas-Fort Worth manufacturing clusters specialize in aluminum-tubing fabrication for lightweight travel configurations.
Germany
Urban apartment dwellers prioritize compact folding cribs for secondary residence and grandparent childcare arrangements. EU Green Deal circular economy mandates accelerate recycled content requirements for packaging and textile components. Bavarian industrial zones concentrate precision locking hardware production for premium wood-finished segments.
China
Export-oriented manufacturing hubs supply aluminum tubing and mesh textile components to Western brands under ASTM F406 compliance protocols. SAMR market supervision and GB standards alignment create parallel certification tracks for domestic versus export production. Yangtze River Delta textile clusters dominate breathable mesh sidewall fabrication for global supply chains.
United Kingdom
London metropolitan parents adopt subscription rental models for temporary sleep solutions in dense housing markets. CE marking and harmonized EN 716 standards impose conformity obligations for EU-UK trade continuity. Midlands distribution centers coordinate direct-to-consumer fulfillment for collapsible travel crib segments.
Canada
Cross-border retail integration channels US-manufactured portable cribs through Toronto and Vancouver metropolitan corridors. Health Canada's Cribs, Cradles and Bassinets Regulations add third-layer compliance for North American suppliers. Montreal-area textile testing laboratories service flame retardant documentation requirements under provincial consumer protection frameworks.
Portable Cribs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue app-integrated monitoring and sensor-textile convergence. The supplier base organizes around three distinct maturity tiers: mass-market volume leaders with deep retail partnerships, premium specialists commanding urban specialty presence, and component-focused assemblers serving private-label channels. Strategic differentiation concentrates on aluminum-tubing fabrication scale, magnetic quick-release hardware licensing, and direct-to-consumer velocity capture. Dominant competitive moves include vertical control over wood sourcing and strategic positioning within rental subscription channels.
Within the mass-market tier, Graco Children's Products Inc. and Delta Children exemplify archetypal scale-driven positioning through retail partnership depth and domestic assembly infrastructure. Million Dollar Baby Co. occupies a specialist position representing premium material positioning and urban market concentration. These three anchors illustrate how supplier strategies diverge between volume-scale fabrication, captive supply chain control, and specialty channel premiumization.
| Leading Market Players |
|---|
| Graco Children's Products Inc. |
| Delta Children |
| Storkcraft Manufacturing Inc. |
| Million Dollar Baby Co. |
| Dream On Me Inc. |
| Kolcraft Enterprises Inc. |
| 4moms |
| Happiest Baby, Inc. |
| HALO |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between CPSC-compliant domestic assembly and import-dependent private-label sourcing manifests in both margin capture and supplier geography. Premium wood-finished folding cribs command measurable price premiums through captive North American lumber sourcing, while mass-market playard configurations compete on aluminum-tubing scale economies anchored in Yangtze River Delta fabrication clusters.
Pricing Analysis
Volume-mass-market versus margin-premium splits dominate pricing architecture across the portable cribs landscape. Three-tier pricing structure across premium, standard, and economy levels tracks ASTM F406 certification depth and domestic assembly presence. Price differentiation hinges on solid wood input grades and magnetic quick-release hardware licensing costs. Cost compression in entry-tier plastic-heavy configurations is intensifying because Southeast Asian component suppliers face escalating chemical disclosure requirements under Washington State's Children's Safe Products Act. Childcare center procurement through group purchasing organizations exhibits highest price sensitivity, while urban millennial direct-to-consumer buyers absorb premiums for lightweight aluminum-tubing travel configurations.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth, Toronto metropolitan corridors, and Midlands UK coordinate hub-and-spoke fulfillment patterns for collapsible travel crib segments. Manufacturing gravity draws from China for aluminum tubing and mesh textiles, Vietnam for precision fabric finishing, and domestic US facilities for solid wood slat assembly. Raw material dependencies rest on North American lumber futures, Yangtze River Delta breathable mesh production, and European magnetic locking hardware patent pools. Single-source vulnerability concentrates in Southeast Asian textile hubs supplying mesh sidewalls to Western brands. Distribution runs through mass-market retail seasonal buying calendars misaligned with direct-to-consumer velocity patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races are accelerating as incumbents pursue backward control over aluminum-tubing fabrication and millennial-facing direct-to-consumer channels to defend margin capture against private-label encroachment.
For Market Incumbents: Lock in exclusive licensing terms for European magnetic quick-release hardware patent pools before consolidation completes. Secure captive supply of North American hardwood slats through long-term offtake agreements with Pacific Northwest sawmills. Sensor-textile convergence represents the emerging entrant archetype threatening premium positioning; counter through accelerated R&D partnerships with respiratory monitoring fabric developers. For New Entrants and Emerging Players: EU Green Deal circular economy mandates in Germany and France open a window for subscription rental channel penetration targeting London and Berlin metropolitan apartment dwellers. White-space opportunity concentrates in sensor-integrated travel crib configurations for remote-work mobile parents. Sanitizable metal-framed designs for family services procurement channels offer the most penetrable institutional entry point. Go-to-market execution should prioritize direct-to-consumer velocity capture through independent ASTM certification mark education. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-tier assemblers combining aluminum-tubing fabrication scale with domestic wood-finished folding crib capacity given CPSC enforcement tightening on import compliance documentation. Long-term viability over the next decade favors suppliers with established sustainability credentials aligned to EU packaging mandates and recycled content thresholds. Acquisition target archetype: component-focused assemblers serving private-label channels with latent direct-to-consumer infrastructure. Signal to watch: California Proposition 65 litigation settlement patterns forcing preemptive material reformulation across supplier networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Tubing | Captive Yangtze River Delta fabrication capacity secures lightweight travel crib supply against Southeast Asian competitor expansion. |
| Direct-to-Consumer Channel Launch | Millennial research patterns on ASTM certification marks favor bypassing legacy retail seasonal buying calendar constraints. |
| Sensor-Textile R&D Partnership | Respiratory monitoring fabric integration opens premium positioning in safety-conscious coastal United States metropolitan markets. |
| Subscription Rental Model Expansion | Urban density in London and New York accelerates short-term lease adoption for temporary sleep solutions. |
| EU Green Deal Compliance Certification | Recycled content thresholds and circular economy packaging mandates secure continental European market access continuity. |
Research Methodology
Independent corroboration across CPSC enforcement action databases, ASTM technical committee proceedings, and Health Canada product recall registries underwrites the qualitative findings on regulatory compliance burden. Primary interviews with juvenile product safety engineers, retail category buyers at mass-market chains, aluminum-tubing procurement managers, and textile compliance officers at Southeast Asian suppliers combined with secondary validation from customs trade records, SEC 10-K filings of publicly traded parent companies, and state-level chemical disclosure enforcement databases. Bottom-up segment sizing and top-down macroeconomic triangulation cross-check volume estimates across the analysis window.
Rate-of-change decomposition separates volume growth from pricing dynamics across product type, material composition, end-user channel, and feature bundling dimensions. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Modeling incorporates remote-work mobility indices, dual-income household formation rates, and multi-jurisdiction certification timeline data as portable crib-specific forecast inputs throughout the projection horizon.
Caveats apply where CPSC standard revision timelines, EU-UK regulatory divergence post-Brexit, or lumber futures volatility could materially shift the outlook. Forecasts reflect documented assumptions on millennial preference persistence and aluminum-tubing supply chain stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Walker Market
Baby Products
AI Smart Baby Monitors Market
Baby Products
Baby Swaddle Wrap Market
Baby Products
Feeding Pillow Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Baby Detergents and Laundry Products Market
Baby Products
Children Products Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Stroller Rental Market
Baby Products
Baby Powder Market
Baby Products
India Baby Care Products Market
Baby Products
Sippy Cups Market
Baby Products
Baby Personal Care Products Market
Baby Products
Diaper Bag Market
Baby Products
Cloth Diapers Market
Baby Products
Baby Food Dispensing Spoon Market