
 Smart Baby Monitor Market | 2026-2036
Smart Baby Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Baby Monitor Market Analysis
FCC Part 15 certification for unlicensed radio frequency emissions is reorganizing competitive entry in the smart baby monitor space. Nanit sustains technology leadership through computer vision and breathing wear integration. VTech Communications anchors volume production through its established electronics manufacturing scale across Asian facilities. Samsung Electronics competes by leveraging its broader smart home ecosystem and display technology heritage.
A smart baby monitor comprises a wireless transmitter-receiver system capturing audio, video, biometric, or environmental data from an infant's surroundings, typically operating on 2.4 GHz or 5 GHz bands with AES-128 encryption for data security. The device serves the primary commercial purpose of enabling remote parental supervision while generating actionable health and sleep analytics through edge computing or cloud-based AI processing. Video monitors with night vision and temperature sensing capture the largest installed base, while smart wearables with heart rate and oxygen saturation tracking represent the fastest-expanding margin pool. Wi-Fi-enabled models dominate connectivity architecture, though Bluetooth retains strength in closed-network deployments prioritizing cybersecurity.
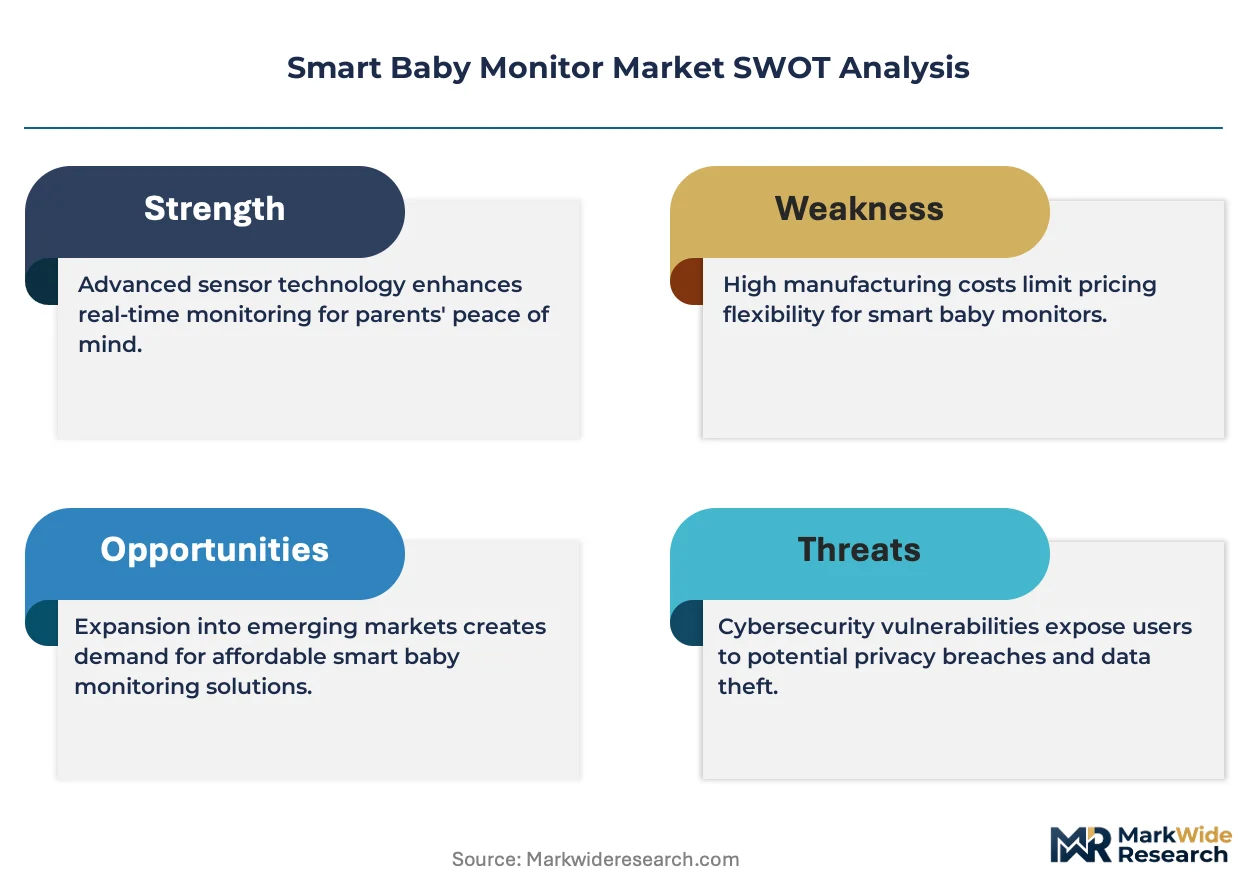
The FCC governs RF emission limits and cybersecurity labeling requirements for US-market devices, while the EU Radio Equipment Directive mandates CE marking and RED compliance for wireless products sold across member states. China's MIIT enforces GB standards for radio transmission equipment, creating a three-jurisdiction compliance burden for multinational suppliers. Stakeholders must monitor evolving AI governance frameworks and data localization mandates that will determine which feature sets remain exportable across regulatory boundaries.
Market Dynamics
FCC Part 15 certification requirements for unlicensed RF emissions are restructuring competitive entry barriers, forcing new entrants to absorb six-figure compliance costs before first revenue. This regulatory gatekeeping favors incumbents with established testing protocols and legal infrastructure.
Growth Catalysts
- Dual-income household expansion:Millennial and Gen Z parents in two-earner families generate sustained demand for remote monitoring capabilities that reduce caregiver dependency.
- AI-enabled health analytics:Edge-computing algorithms processing breathing patterns and sleep architecture create subscription revenue streams beyond hardware margins.
- EU Radio Equipment Directive harmonization:CE marking standardization across member states reduces per-country compliance fragmentation for cross-border suppliers.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate image sensor and Wi-Fi chipset fabrication, creating single-source vulnerability for video monitor producers.
- RF spectrum congestion:2.4 GHz band saturation in dense urban environments degrades transmission reliability and drives customer dissatisfaction.
- Data localization mandates:China's PIPL and emerging EU cloud sovereignty rules fragment cloud architecture economics for multinational vendors.
Strategic Opportunities
- Rural and semi-urban India:BIS certification pathways and PLI scheme incentives for electronics manufacturing create first-mover potential in underpenetrated tier-2 and tier-3 cities.
- Pediatric telehealth integration:API partnerships with remote pediatric platforms transform monitors into clinical data collection endpoints reimbursable under evolving insurance frameworks.
- Direct-to-consumer subscription models:Recurring revenue from AI-generated sleep coaching and developmental milestone tracking reduces customer acquisition cost dependence.
Industry Challenges
- Embedded systems cybersecurity expertise:Shortage of firmware engineers capable of implementing AES-256 encryption and secure boot protocols delays product launches.
- Multi-jurisdiction certification timelines:Sequential FCC, CE, and MIIT approval processes extend time-to-market by 8-14 months for feature-rich models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Baby Monitor Market |
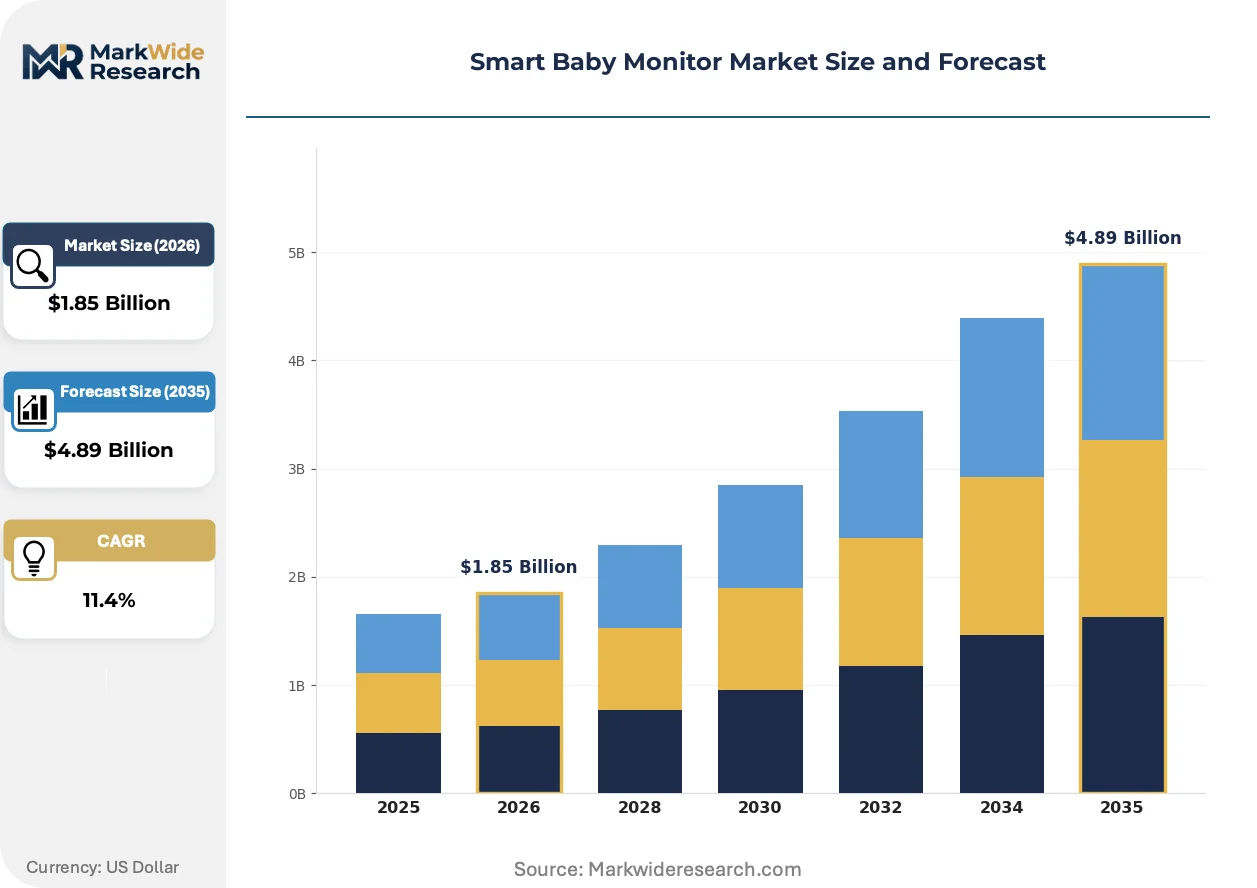
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio Monitor, Video Monitor, Movement Monitor, Smart Wearable Technology: Wi-Fi, Bluetooth, Zigbee, Cellular End User: Parents, Caregivers, Hospitals, Childcare Centers Feature: Voice Activation, Night Vision, Two-Way Talk, Temperature Sensor |
| Companies Covered | VTech Communications, Inc., Motorola Mobility LLC, Samsung Electronics Co. Ltd., Nanit, Owlet, Summer Infant, Angelcare, iBaby Labs, Inc., Miku Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Baby Monitor Market Emerging Trajectories
Computer vision algorithms trained on infant sleep datasets are redefining what parents expect from monitoring hardware. The category is shifting from passive surveillance to predictive health intervention.
On-device neural processing units capable of real-time breathing pattern analysis without cloud transmission are displacing Wi-Fi-dependent architectures that expose families to data breach risks. Privacy-conscious buyers in Germany and California are adopting these closed-loop systems at three times the rate of traditional connected monitors. This hardware shift is compressing cloud infrastructure margins while expanding semiconductor content value per unit.
The EU AI Act's risk classification for biometric inference systems is forcing redesign of health analytics pipelines. Developers must now implement human-in-the-loop review for any algorithmic alert triggering caregiver intervention. Premium product lines targeting Nordic markets are responding by hiring clinical advisory boards to validate algorithmic outputs against pediatric protocols.
Parents are consolidating device ecosystems around single-vendor smart home platforms rather than standalone baby monitors. This behavior pressures independent hardware makers to achieve Matter protocol certification for interoperability with Amazon Alexa, Google Home, and Apple HomeKit. The United States exhibits the highest concentration of platform-locked households, where switching costs now exceed hardware price differentials.
Smart Baby Monitor Market Segmentation
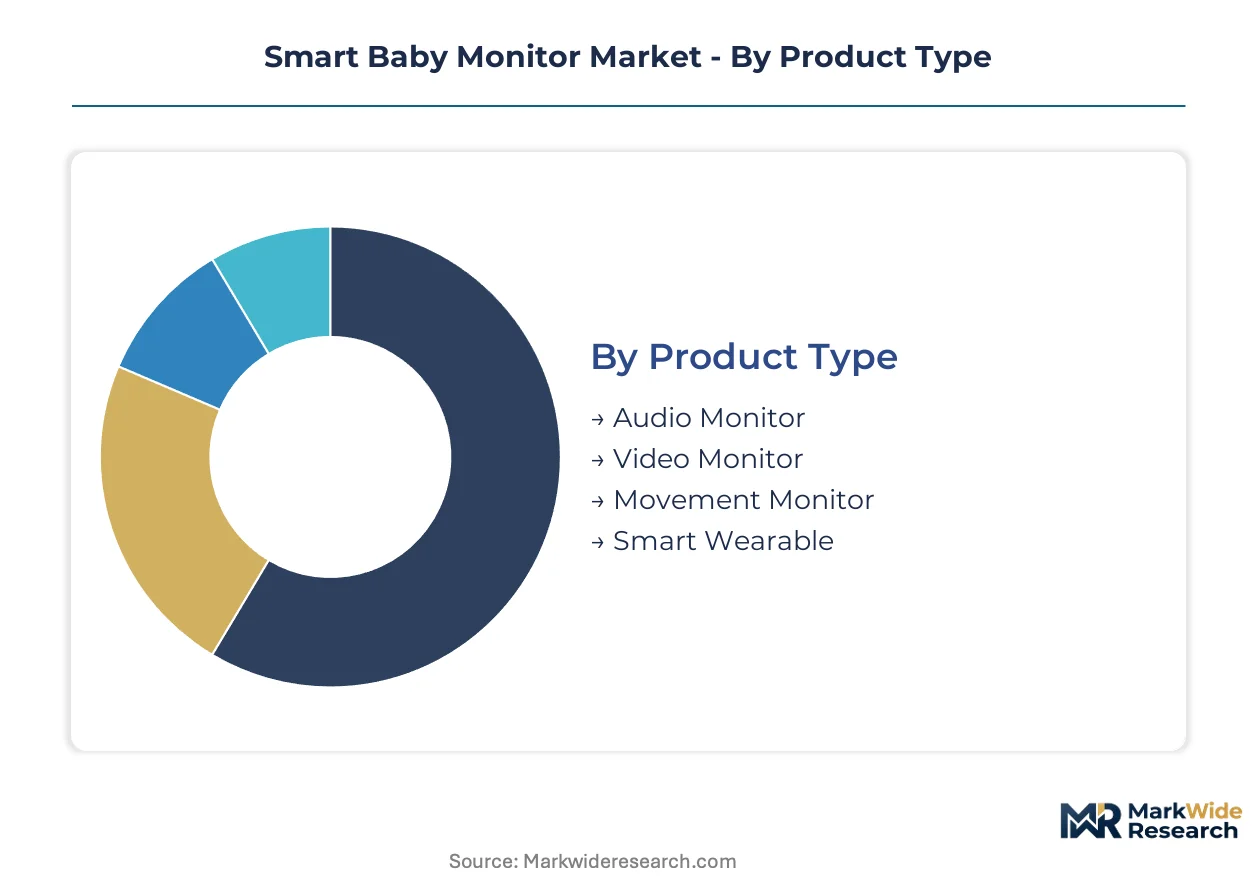
Segmentation in the smart baby monitor market reveals how regulatory compliance costs, connectivity standards, and end-user risk tolerance fragment purchasing behavior across hardware categories. Understanding these divides enables suppliers to prioritize certification investments and distribution channel selection.
Product Type:
FCC Part 15 certification intensity varies sharply across hardware form factors, with video and movement monitors facing stricter RF emission testing than audio-only devices due to transmission bandwidth requirements.
- Audio Monitor:Single-channel or DECT 6.0 wireless systems transmitting sound with minimal power draw. Demand concentrates in price-sensitive rural US households and emerging Asian markets where FCC and MIIT compliance costs must stay below retail price floors.
- Video Monitor:2.4 GHz or 5.8 GHz RF systems with CMOS image sensors and night vision IR LEDs. Parents in German and Californian markets drive adoption of closed-loop models with on-device storage to satisfy GDPR and emerging state privacy statutes.
- Movement Monitor:Pressure pad or radar-based breathing detection systems requiring medical-grade sensor calibration. NICU discharge protocols in US hospital systems generate institutional procurement demand.
- Smart Wearable:Sock or band form factors with pulse oximetry and accelerometry. BIS certification pathways in India and CE marking under EU MDR create dual-jurisdiction launch complexity for biometric hardware.
Established volume favors video monitors; emerging adoption favors smart wearables.
Technology:
Connectivity architecture determines cloud infrastructure exposure and recurring revenue potential, with Wi-Fi models enabling subscription analytics while closed protocols protect against data localization penalties.
- Wi-Fi:IEEE 802.11ac/ax transmission enabling cloud AI processing and smartphone app integration. Dual-income households in the United States and China generate demand for remote workplace monitoring capabilities.
- Bluetooth:BLE 5.0 or 5.2 protocols for localized phone-to-device pairing without internet exposure. German and Nordic markets prefer this architecture for GDPR-aligned data sovereignty.
- Zigbee:Mesh networking for whole-home coverage with Matter protocol compatibility. Smart home ecosystem consolidation in US metropolitan areas drives specification requirements.
- Cellular:LTE-M or NB-IoT modules for locations lacking broadband infrastructure. Rural India and remote Australian communities represent addressable demand pockets.
Wi-Fi dominates revenue contribution; Bluetooth climbs the fastest on privacy positioning.
End User:
Procurement authority splits between retail consumers prioritizing ease-of-use and institutional buyers demanding liability protection through clinical validation.
- Parents:Individual purchasers responding to pediatrician recommendations and direct-to-consumer marketing. Millennial and Gen Z cohorts in dual-income US households drive premium feature adoption.
- Caregivers:Grandparents and non-parental family members seeking simplified interfaces with large display elements. This segment tolerates higher price points for usability guarantees.
- Hospitals:Maternity wards and pediatric units requiring FDA 510(k) clearance or equivalent national regulator approval for clinical-grade monitoring. Procurement runs through group purchasing organizations with multi-year contract cycles.
- Childcare Centers:Licensed facilities facing state-mandated staff-to-infant ratios that technology supplements. US state licensing boards increasingly permit monitor-assisted supervision in compliance audits.
Parents anchor volume scale; hospitals command the steepest expansion trajectory on reimbursement evolution.
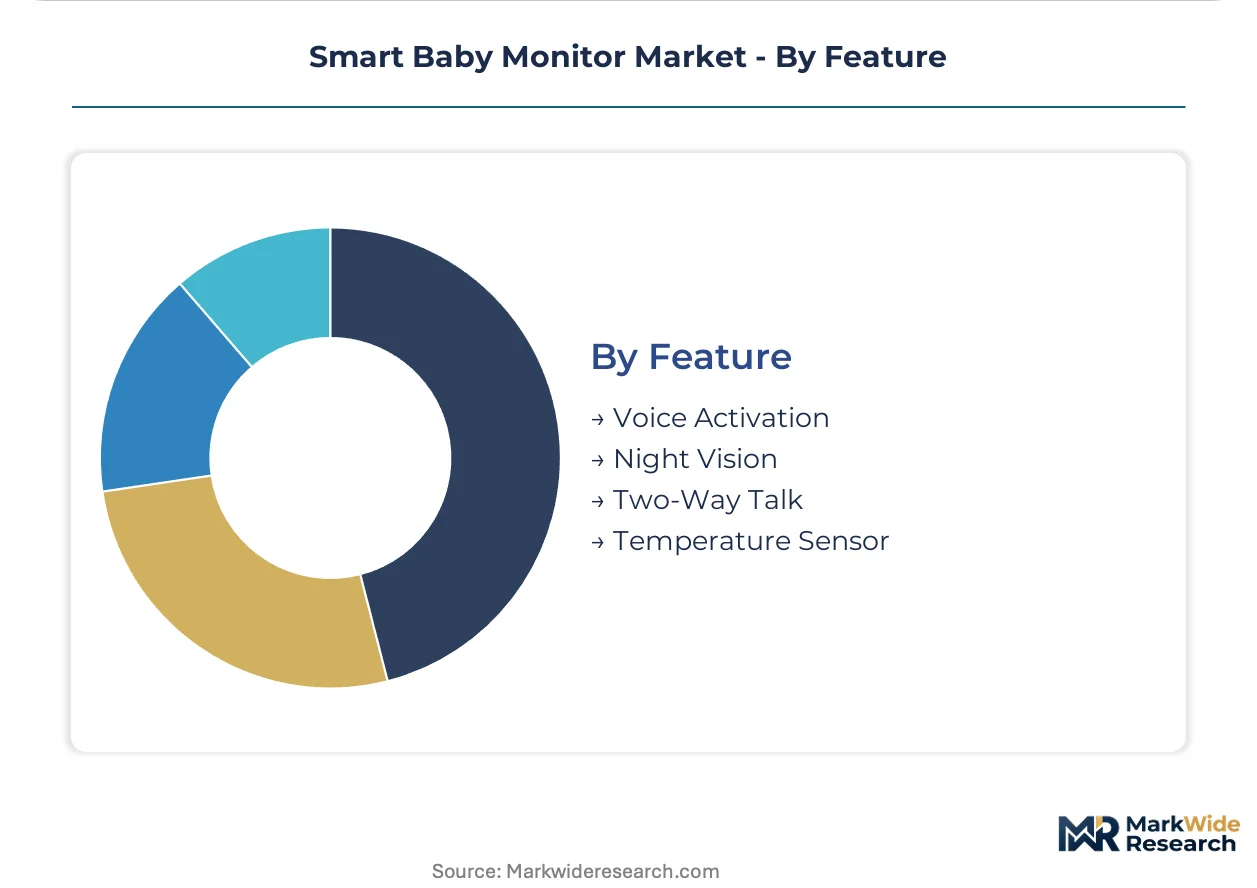
Feature:
Feature bundling strategies reflect regional energy costs, housing stock age, and parental anxiety profiles that shape willingness to pay for sensor redundancy.
- Voice Activation:VOX circuitry reducing power consumption and RF transmission duty cycles. European markets with high electricity tariffs favor this efficiency specification.
- Night Vision:Near-infrared LED illumination with automatic ambient light detection. Standard inclusion in video monitor bundles across all price tiers.
- Two-Way Talk:Full-duplex audio enabling parental voice soothing without physical presence. Differentiates mid-tier from economy positioning in US retail channels.
- Temperature Sensor:Ambient or skin-surface thermal monitoring with alert thresholds. Overheating prevention messaging resonates in Australian and Southwest US markets with extreme climate exposure.
Night vision and two-way talk define table stakes; voice activation gains share fastest on energy cost sensitivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives for electronics manufacturing in India and BIS certification streamlining are accelerating regional production shifts. Germany's GDPR enforcement and the EU AI Act's biometric risk classifications reshape feature exportability. China's MIIT GB standards and data localization under PIPL fragment cloud architecture economics for multinational vendors.
United States
Dual-income Millennial and Gen Z households in metropolitan areas drive premium feature adoption for remote workplace monitoring. FCC Part 15 certification requirements for unlicensed RF emissions impose six-figure compliance costs that favor incumbents with established testing protocols. Greater Boston and Silicon Valley concentrate venture-backed startups developing edge-computing algorithms for breathing pattern analysis.
Germany
Privacy-conscious buyers in Berlin and Bavaria adopt closed-loop Bluetooth monitors at three times the rate of Wi-Fi-dependent architectures to satisfy GDPR alignment. The EU AI Act's human-in-the-loop mandate for biometric inference systems forces redesign of health analytics pipelines. Stuttgart's automotive electronics cluster supplies neural processing units for on-device AI capabilities.
China
MIIT enforces GB standards for radio transmission equipment while PIPL data localization mandates fragment cloud infrastructure for multinational vendors. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou concentrate image sensor and Wi-Fi chipset assembly capacity. Domestic brands leverage direct-to-consumer channels to capture price-sensitive demand in tier-2 and tier-3 cities.
India
BIS certification pathways and PLI scheme incentives for electronics manufacturing create first-mover potential in underpenetrated tier-2 and tier-3 urban centers. Maharashtra and Karnataka state industrial policies attract contract manufacturers serving export markets. Bangalore's hardware startup ecosystem develops low-cost movement monitors for NICU discharge protocols in public hospital systems.
Australia
Temperature sensing features resonate in Queensland and Western Australian markets with extreme climate exposure and overheating prevention messaging. The Therapeutic Goods Administration (TGA) regulates medical-grade monitoring claims for smart wearable form factors. Sydney and Melbourne concentrate pediatric telehealth platform development enabling API partnerships with monitor hardware vendors.
Smart Baby Monitor Market Vendor Landscape
Player mix skews toward consumer electronics conglomerates with established Asian manufacturing scale and venture-backed specialists in computer vision and biometric sensing. Market structure exhibits tiered consolidation where premium positioning requires clinical validation infrastructure while volume production depends on Shenzhen and Taiwan supply chain integration. Three archetypes dominate: diversified electronics manufacturers leveraging smart home ecosystem lock-in, pediatric health technology specialists monetizing subscription analytics, and contract manufacturing platforms serving white-label retail channels. Competitive dynamics center on sequential multi-jurisdiction certification timelines and direct-to-consumer subscription model economics that reduce customer acquisition cost dependence.
Within the diversified electronics tier, Samsung Electronics Co. Ltd. and VTech Communications, Inc. occupy positions shaped by manufacturing scale and distribution breadth. Nanit exemplifies the health technology specialist archetype with computer vision and breathing wear integration. Motorola Mobility LLC anchors the legacy consumer electronics segment with established retail channel relationships. These named entities represent competitive positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| VTech Communications, Inc. |
| Motorola Mobility LLC |
| Samsung Electronics Co. Ltd. |
| Nanit |
| Owlet |
| Summer Infant |
| Angelcare |
| iBaby Labs, Inc. |
| Miku Inc |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen month certification timelines for FCC Part 15, CE marking, and MIIT GB standards create inventory risk that compresses pricing power for new entrants lacking established testing protocols. This lead-time burden concentrates margin protection with incumbents who amortize compliance costs across multi-year product cycles while forcing aspirants into aggressive price positioning to recover sunk certification investments.
Pricing Analysis
Certification grade creates the primary spread between premium and economy positioning, with FDA 510(k) cleared movement monitors commanding substantial premiums over basic audio devices lacking clinical validation. Three-tier pricing structure across premium, standard, and economy levels stratifies by sensor sophistication and AI analytics bundling, with subscription SaaS tiers for sleep coaching generating recurring revenue that offsets hardware margin compression. Pricing pressure stems from semiconductor supply concentration in Taiwan and South Korea, which elevates BOM costs for video monitors with CMOS sensors. Parents in dual-income US households exhibit lowest price sensitivity for biometric wearables, while rural price-sensitive buyers in emerging Asian markets drive economy audio monitor volume.
Supply Chain Analysis
Inventory exposure concentrates in Yangtze River Delta manufacturing hubs, where Shanghai and Suzhou facilities assemble image sensors and Wi-Fi chipsets for global brands. Supply draws from Taiwan for neural processing units, South Korea for advanced CMOS fabrication, and China for plastic housings and PCB assembly. Single-source vulnerability in Taiwan semiconductor foundries threatens production continuity for edge-AI enabled monitors. Distribution runs through direct-to-consumer channels for premium health technology specialists, while mass-market volume flows through established electronics retail networks and white-label contract manufacturing platforms serving big-box retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around dual-income Millennial and Gen Z households who demand predictive health analytics, fragmenting procurement authority away from traditional retail gatekeepers toward direct-to-consumer subscription relationships.
For Market Incumbents: Shield subscription revenue streams by deepening clinical validation infrastructure for algorithmic health alerts, as the EU AI Act's human-in-the-loop mandates raise compliance barriers against unvalidated entrants. Prioritize backward integration into neural processing unit supply through partnerships with Stuttgart automotive electronics clusters to secure on-device AI capacity. Fortify direct-to-consumer channel control to reduce customer acquisition cost dependence as retail intermediaries lose pricing leverage. For New Entrants and Emerging Players: Pediatric telehealth API partnerships represent the most penetrable white-space, as hospitals and remote pediatric platforms seek reimbursable clinical data collection endpoints that incumbent hardware makers under-serve with closed proprietary systems. Target tier-2 and tier-3 Indian cities where BIS certification streamlining and PLI scheme incentives lower entry barriers against established multinational brands. Pursue white-label manufacturing relationships with domestic Indian contract manufacturers to bypass sequential multi-jurisdiction certification timelines. For Investors and Strategic Acquirers: Long-term, this sits as a health technology platform play because predictive infant analytics transform hardware margins into recurring SaaS revenue with embedded switching costs. Acquisition candidates should demonstrate FDA 510(k) clearance pathways or CE marking under EU MDR for biometric wearables, plus established direct-to-consumer subscription economics. Monitor reimbursement framework evolution for pediatric telehealth integration as the inflection signal determining which feature sets achieve clinical legitimacy.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Investment | Simultaneous FCC, CE, and MIIT approval reduces time-to-market gaps against Asian contract manufacturers. |
| On-Device AI Chipset Partnership | Neural processing unit integration from Stuttgart automotive suppliers enables GDPR-compliant closed-loop architectures. |
| Pediatric Telehealth API Development | Clinical data pipeline partnerships with Sydney and Melbourne telehealth platforms create reimbursable endpoint status. |
| Direct-to-Consumer Subscription Launch | Recurring revenue from sleep coaching analytics reduces CAC dependence and builds platform lock-in. |
| India Manufacturing Footprint Establishment | Maharashtra and Karnataka PLI incentives lower cost base for export markets while capturing domestic tier-2 demand. |
Methodological Framework
Operator-level perspectives from connected device hardware engineers, pediatric telehealth platform CTOs, FCC certification consultants, and hospital biomedical procurement committees anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC filings from consumer electronics conglomerates, FCC equipment authorization databases, EU MDR notified body clearance records, and MIIT GB standard certification registries. Bottom-up unit economics modeling triangulated against top-down market sizing from trade customs data and retail channel shipment disclosures.
Sensitivity analysis tested forecast robustness across alternative semiconductor supply scenarios and regulatory delay assumptions throughout the projection horizon. Segmentation dimensions modeled include product type, connectivity architecture, end-user procurement authority, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to hardware shipment trajectories and subscription attach-rate projections, with inputs from edge-AI adoption curves and pediatric telehealth reimbursement evolution.
Underlying assumptions cover stable FCC Part 15 enforcement intensity, CE marking harmonization persistence, and MIIT GB standard continuity, with deviation risk concentrated in EU AI Act implementation timelines and PIPL data localization expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Crib Mattress Market
Baby Products
North America Baby Bottle Market
Baby Products
Diaper Pails Market
Baby Products
Baby Feeding Bottles Market
Baby Products
Japan Baby Care Product Market
Baby Products
Breast Milk Storage Products Market
Baby Products
Global Baby Carriers Market
Baby Products
Baby Swaddle Wrap Market
Baby Products
China Maternity Goods Market
Baby Products
Kids Activity Box Market
Baby Products
Diaper Bag Market
Baby Products
Maternity Products Market
Baby Products
Smart Pacifier Market
Baby Products
Baby Food Dispensing Spoon Market
Baby Products
Baby Nail Trimmer Market
Baby Products
Feeding Bra Market