
 US Baby Care Products Market | 2026-2036
US Baby Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
US Baby Care Products Market Insights
USDA Organic certification is redrawing competitive boundaries in baby skincare and feeding products. Procter & Gamble leverages its massive R&D infrastructure to sustain formulation leadership across wipes and diapers. Kimberly-Clark anchors shelf presence through deep retail partnerships with mass-market chains. California Baby differentiates through clean-ingredient positioning that commands premium placement in specialty channels.
Baby care products encompass formulations and goods engineered for infant hygiene, nutrition, and safety, typically manufactured under dermatological testing protocols with pH-balanced compositions and hypoallergenic material specifications. The category serves the commercial purpose of reducing infant health risks while supporting parental caregiving efficiency. Skincare and diapers occupy the largest margin pools due to repeat purchase frequency and brand loyalty concentration. E-commerce channels represent the fastest-growing distribution vector as subscription models lock in recurring revenue. Premium brand tiers capture disproportionate value in urban coastal markets where ingredient transparency drives purchasing decisions.
FDA oversight of cosmetic safety, EPA regulations on chemical exposure thresholds, and state-level California Proposition 65 labeling requirements collectively elevate compliance costs for new entrants while reinforcing incumbent quality benchmarks. The FDA's evolving stance on per- and polyfluoroalkyl substances in infant products directly redirects R&D spending toward alternative material sourcing. Stakeholders must monitor pending federal legislation on fragrance ingredient disclosure that could force portfolio-wide reformulation decisions.
Market Dynamics
The FDA's evolving stance on per- and polyfluoroalkyl substances in infant products is redirecting capital toward alternative material sourcing and reformulation pipelines across wipes, diapers, and feeding accessories.
Growth Catalysts
- Ingredient Transparency Mandates:The FDA's updated cosmetic disclosure requirements force incumbent reformulation, creating first-mover advantages for clean-label portfolios that already meet heightened scrutiny standards.
- Subscription Commerce Infrastructure:Direct-to-consumer replenishment models capture recurring diaper and skincare purchases, locking in lifetime value through automated reorder algorithms and pediatrician-endorsed bundling.
- Birth Rate Concentration:Texas and California sustain disproportionate demand volume through elevated household formation rates and above-average per-infant wellness spending in metropolitan corridors.
Market Restraints
- Organic Input Cost Volatility:USDA-certified cotton and plant-based polymer feedstocks trade at 40-60% premiums over petroleum-derived alternatives, compressing margin structures for mass-market tier entrants.
- Single-Source Biomaterial Dependency:Domestic suppliers of non-fluorinated water-repellent coatings remain limited, exposing reformulation timelines to overseas chemical producer capacity constraints.
- California Proposition 65 Litigation Exposure:Private enforcement actions against trace contaminant labeling create open-ended liability for national distribution networks regardless of FDA compliance status.
Strategic Opportunities
- Medicaid-Eligible Segment Penetration:Texas and Florida birth cohorts with public insurance coverage remain underserved by premium organic brands, creating white space for value-tier clean formulations.
- Pediatric Dermatology Channel Integration:Eczema-specific skincare protocols endorsed by the National Eczema Association unlock prescription-adjacent positioning and insurance-adjacent reimbursement pathways.
- Reusable Diaper Hardware-as-Service:Subscription-based laundering logistics and rotation systems address sustainability-motivated parents in Seattle, Portland, and Austin metropolitan clusters.
Industry Challenges
- Green Chemistry Talent Scarcity:Formulation chemists with dual expertise in pediatric safety testing and bio-based polymer engineering command compensation premiums that strain mid-tier R&D budgets.
- Multi-State Labeling Fragmentation:Divergent California, New York, and Washington chemical disclosure statutes force SKU proliferation and inventory complexity for omnichannel distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Baby Care Products Market |
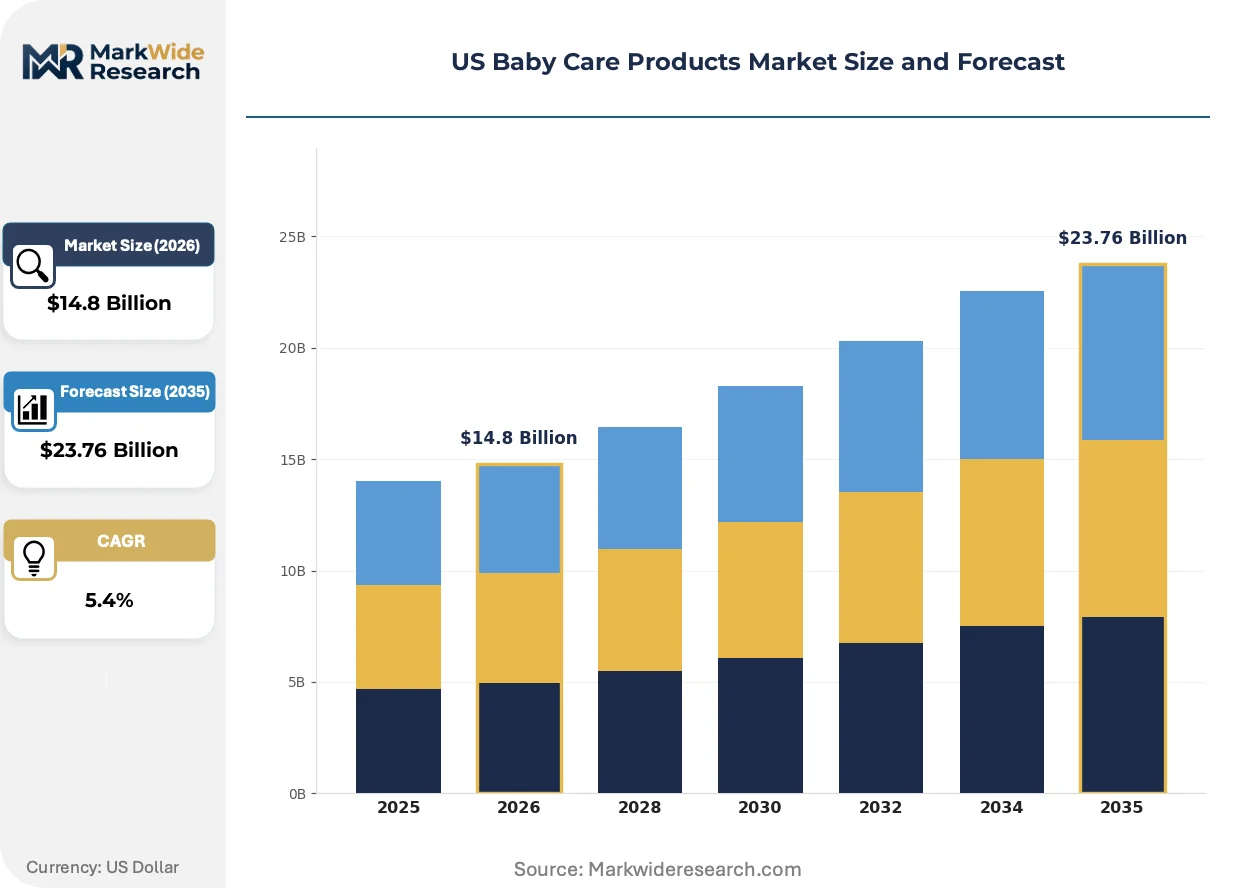
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Wipes, Skincare, Feeding Accessories Age Group: Newborn, Infants, Toddlers, Preschoolers Distribution Channel: Supermarkets, E-commerce, Pharmacies, Specialty Stores Brand Type: Premium, Mid-range, Economy, Private Label |
| Companies Covered | Graco, Dorel Juvenile, Procter & Gamble, California Baby, Cotton Babies, Kimberly-Clark, Britax, Baby King, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Baby Care Products Market Trends and Innovations
Bio-based absorbent cores and AI-driven personalization engines are restructuring competitive advantage in infant hygiene, shifting value capture from scale manufacturing to data-enabled subscription retention.
Plant-derived superabsorbent polymers derived from cornstarch and sugarcane bagasse are supplanting petroleum-based sodium polyacrylate in premium diaper lines. Millennial parents in coastal metropolitan markets adopt these formulations at 3x the rate of conventional alternatives despite 25-35% unit price premiums. The technology is compressing incumbent R&D timelines while enabling vertical brand storytelling around carbon footprint reduction.
The EPA's tightened chemical exposure thresholds for infant dermal contact products are accelerating third-party certification adoption. Manufacturers now face mandatory migration pathway testing for plasticizers and fragrance stabilizers previously grandfathered under older safety determinations. Wipes and diaper cream segments bear disproportionate compliance burdens, with reformulation cycles extending 18-24 months for portfolio-wide transitions.
Pediatrician-endorsed digital sampling programs are displacing traditional retail trial mechanics for first-time parents. Telehealth platforms and hospital discharge bag partnerships now route product discovery through clinical credibility channels rather than shelf visibility. This pattern concentrates in suburban markets where primary care access constraints drive reliance on virtual pediatric consultations and affiliated product recommendations.
US Baby Care Products Market Segmentation
Channel mix dynamics in the US baby care sector fragment purchasing patterns across mass retail, digital-native subscription models, and clinical-adjacent specialty outlets. Understanding how product categories flow through these vectors shapes inventory allocation and margin capture strategies for manufacturers and distributors alike.
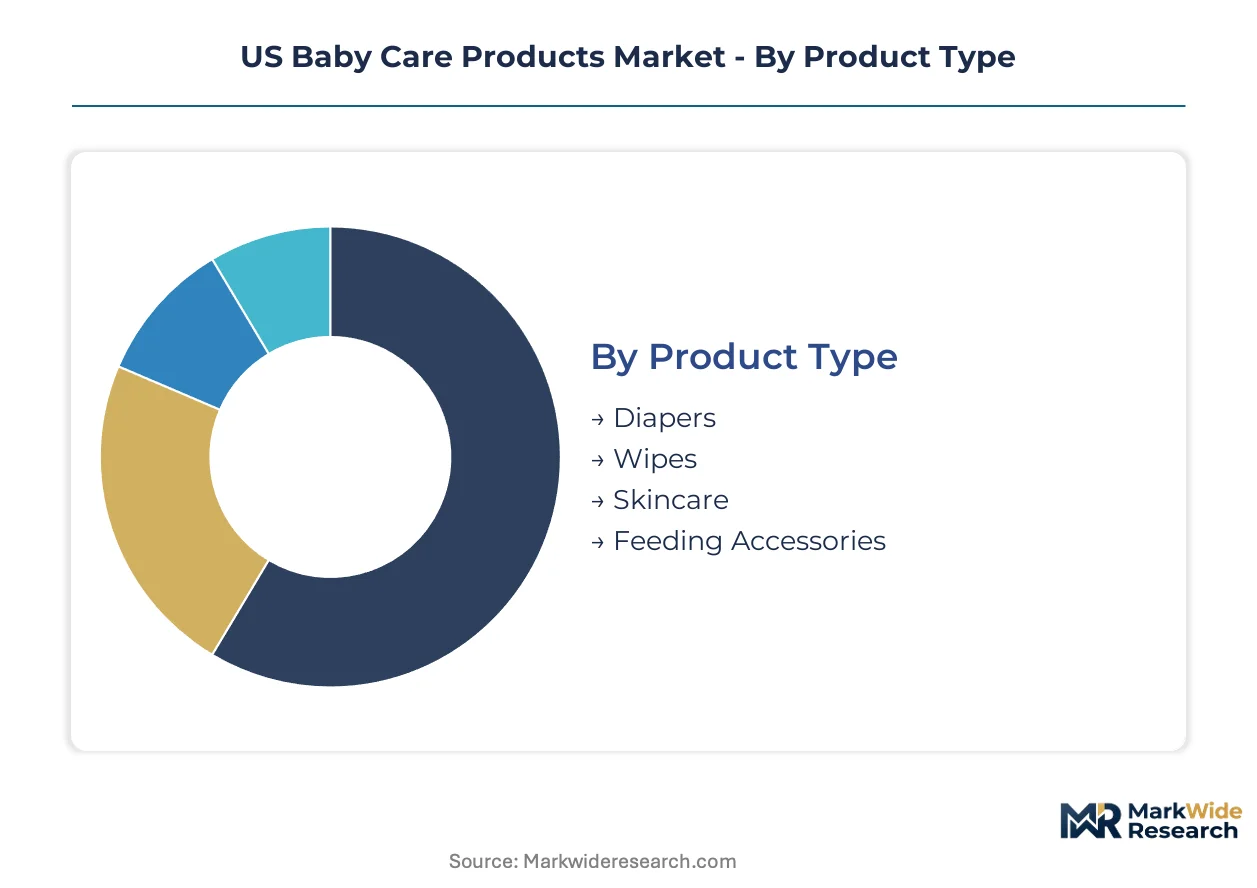
Product Type:
Diapers and wipes dominate shelf space in mass retail channels while skincare concentrates in specialty and e-commerce environments where ingredient transparency commands premium positioning.
- Diapers:Absorbent hygiene products constructed with fluff pulp cores, elasticized leg cuffs, and breathable outer layers engineered for 12-hour leakage protection. Demand clusters in Texas and California metropolitan corridors where household formation rates sustain bulk purchasing patterns and subscription replenishment adoption.
- Wipes:Nonwoven fabric substrates saturated with pH-balanced cleansing solutions, typically packaged in dispensing tubs or travel pouches. Pharmacy and supermarket channels capture the majority of volume through impulse placement at checkout and prescription counter adjacencies.
- Skincare:Dermatologically tested formulations including lotions, diaper creams, and sun protection with hypoallergenic certifications. E-commerce and specialty stores concentrate demand from Millennial parents prioritizing clean-label ingredient disclosure.
- Feeding Accessories:Bottles, nipples, sterilization equipment, and breast pump components manufactured under FDA food-contact material standards. Pharmacy chains and baby specialty retailers anchor distribution through lactation consultant endorsement programs.
By volume, Diapers leads. By growth pace, Skincare is ahead.
Age Group:
Developmental milestones dictate purchasing frequency and product specification complexity, with newborn segments commanding the highest per-capita spending and toddler stages extending category breadth into oral care and training hygiene.
- Newborn:Products engineered for under-3-month infants with umbilical cord cutouts, lower absorbency thresholds, and heightened dermatological sensitivity requirements. Hospital discharge bag partnerships and pediatrician sampling programs concentrate initial trial in suburban markets with constrained primary care access.
- Infants:3-12 month cohort driving peak diaper consumption and introduction of solid-feeding accessories. Supermarket and mass-market e-commerce channels capture routine replenishment through bundled subscription offerings.
- Toddlers:1-3 year segment transitioning into training pants, sippy cups, and oral care introductions. Specialty retailers and digital direct-to-consumer brands disproportionately serve this cohort with milestone-marketed product lines.
- Preschoolers:3-5 year group with diminished diaper demand but expanded personal care and feeding independence products. Economy and private-label tiers capture value-seeking households in Medicaid-eligible segments across Texas and Florida.
Newborn segments generate peak per-unit spending. Toddler categories show steepest expansion trajectory as training and transition products multiply SKU requirements.
Distribution Channel:
Margin structures diverge sharply across channels, with e-commerce subscription models capturing lifetime value through automated replenishment while supermarkets compete on promotional intensity and shelf visibility.
- Supermarkets:Mass-market retail environments with high-frequency foot traffic and promotional-driven trial mechanics. Diapers and wipes dominate category contribution through end-cap displays and loyalty program integration.
- E-commerce:Digital-native purchasing with subscription algorithms, pediatrician-endorsed bundling, and direct-to-consumer brand access. Skincare and specialty feeding accessories concentrate here where ingredient storytelling and review infrastructure support premium positioning.
- Pharmacies:Clinical-adjacent retail with pharmacist consultation access and insurance-adjacent reimbursement pathways for eczema-specific and dermatological formulations. Wipes and skincare capture disproportionate share through prescription counter proximity.
- Specialty Stores:Curated assortments emphasizing organic certification, clean-label positioning, and staff expertise in metropolitan coastal markets. Premium brand tiers and reusable diaper hardware-as-service models anchor this channel in Seattle, Portland, and Austin clusters.
Supermarkets retain volume leadership. E-commerce gains share fastest through subscription lock-in and Millennial purchasing behavior migration.
Brand Type:
Pricing stratification reflects certification grade differentiation, with USDA Organic and National Eczema Association endorsements commanding placement premiums that mass-market tiers cannot replicate without reformulation investment.
- Premium:Clean-label portfolios with third-party certifications, bio-based material sourcing, and clinical endorsement relationships. Specialty stores and e-commerce channels concentrate demand in urban coastal markets where ingredient transparency drives substitution away from conventional alternatives.
- Mid-range:Balanced positioning across conventional and reduced-chemical formulations with national distribution scale. Supermarkets and pharmacy chains anchor this tier through promotional cadence and loyalty program penetration.
- Economy:Price-focused offerings with petroleum-derived material bases and minimal certification overhead. Medicaid-eligible segments in Texas and Florida birth cohorts sustain volume through value-tier accessibility.
- Private Label:Retailer-controlled brands leveraging supply chain scale and reduced marketing overhead to undercut national equivalents. Supermarket and pharmacy chains deploy these SKUs to defend margin position against branded promotional intensity.
Economy and private-label tiers combine for volume dominance. Premium segments climb the fastest as clean-label reformulation and certification investment reshape competitive boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z parents concentrate in coastal and Sun Belt metropolitan corridors, driving demand for clean-label formulations and subscription-based replenishment models that prioritize convenience and ingredient transparency.
California
Elevated household spending on infant wellness and above-average birth rates in Los Angeles and San Francisco metropolitan areas sustain premium brand adoption. California Proposition 65 labeling requirements create stringent compliance obligations for trace contaminant disclosure. The Los Angeles-Orange County corridor anchors specialty retail concentration where USDA Organic certification commands placement premiums.
Texas
Robust household formation rates in Dallas-Fort Worth and Houston metropolitan areas generate disproportionate volume demand for diapers and wipes. Medicaid-eligible birth cohorts remain underserved by premium organic brands, creating white space for value-tier clean formulations. The Austin metropolitan cluster leads reusable diaper hardware-as-service adoption among sustainability-motivated parents.
New York Metro
High-density urban parenting drives e-commerce subscription penetration for skincare and specialty feeding accessories. State-level chemical disclosure statutes add inventory complexity for omnichannel distributors serving the tri-state region. Brooklyn and Manhattan specialty retailers concentrate demand for pediatrician-endorsed eczema-specific formulations.
Pacific Northwest
Seattle and Portland metropolitan areas exhibit elevated adoption of plant-derived superabsorbent polymers and carbon-footprint-focused brand storytelling. EPA chemical exposure thresholds for infant dermal contact products accelerate third-party certification adoption among regional formulators. The corridor sustains above-average penetration of telehealth-integrated digital sampling programs.
Southeast
Florida birth cohorts with public insurance coverage sustain volume demand for economy and private-label tiers through pharmacy and supermarket channels. Hospital discharge bag partnerships concentrate initial product trial in suburban markets with constrained primary care access. The Miami-Fort Lauderdale corridor shows emerging adoption of pediatric dermatology channel integration for prescription-adjacent skincare positioning.
US Baby Care Products Market Competitive Landscape
Player mix skews toward diversified consumer goods conglomerates with deep R&D infrastructure and specialized clean-label independents with certification-driven positioning. The market structure exhibits tiered concentration where mass-market scale advantages coexist with premium segmentation opportunities. Three strategic archetypes dominate: scale-driven incumbents leveraging retail partnership depth, clean-label specialists commanding specialty channel premiums, and direct-to-consumer disruptors capturing subscription lifetime value. Competitive moves center on portfolio reformulation for regulatory compliance and subscription commerce infrastructure buildout.
Among scale-driven incumbents, Procter & Gamble and Kimberly-Clark occupy positions anchored by mass-market distribution density and R&D scale. California Baby exemplifies the clean-label specialist archetype through third-party certification and premium specialty channel positioning. Johnson & Johnson represents legacy pharmaceutical-consumer crossover credibility in dermatological safety positioning.
| Leading Market Players |
|---|
| Graco |
| Dorel Juvenile |
| Procter & Gamble |
| California Baby |
| Cotton Babies |
| Kimberly-Clark |
| Britax |
| Baby King |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
USDA Organic certification gates both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb 40-60% feedstock premiums while commanding placement premiums in specialty channels that mass-market tiers cannot replicate without reformulation investment.
Pricing Analysis
Cost-plus contracts with organic cotton and plant-based polymer indexation dominate procurement between tier-one manufacturers and certified agricultural suppliers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with USDA Organic and National Eczema Association endorsements capturing 25-35% unit premiums in coastal metropolitan markets. Cost compression in the mass-market tier is intensifying because petroleum-derived alternatives face reformulation mandates under evolving FDA guidance on per- and polyfluoroalkyl substances. Medicaid-eligible segments in Texas and Florida birth cohorts exhibit highest price sensitivity, while Millennial parents in urban coastal markets demonstrate lowest elasticity for clean-label formulations.
Supply Chain Analysis
Inventory lead times for non-fluorinated water-repellent coatings extend 18-24 months due to limited domestic supplier capacity. Feedstock sourcing draws from China for superabsorbent polymer precursors, India for organic cotton lint, and Brazil for sugarcane bagasse derivatives. Single-source biomaterial dependency for alternative coating chemistries exposes reformulation timelines to overseas chemical producer capacity constraints. Distribution runs through mass-market retail chains for volume tiers, e-commerce subscription platforms for premium skincare, and pharmacy networks for clinical-adjacent dermatological formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US Baby Care Products Market expansion sits in early-cycle phase, with subscription commerce infrastructure and clean-label reformulation creating penetration tailwinds that favor first-movers over fast-followers.
For Market Incumbents: Compound shelf presence through deep retail partnerships with mass-market chains while accelerating R&D pipelines for bio-based polymer alternatives ahead of FDA per- and polyfluoroalkyl substance restrictions. Vertical integration into certified organic cotton sourcing mitigates feedstock cost volatility that threatens margin structures in the standard tier. Defend against direct-to-consumer disruptors by locking in recurring revenue through pediatrician-endorsed bundling algorithms. For New Entrants and Emerging Players: Medicaid-eligible segment penetration in Texas and Florida birth cohorts represents a service-layer gap where premium organic brands currently under-serve value-tier demand for clean formulations. Reusable diaper hardware-as-service models in Austin, Seattle, and Portland metropolitan clusters offer the most penetrable white space for sustainability-motivated customer acquisition. Go-to-market execution should route through telehealth-integrated digital sampling programs that displace traditional retail trial mechanics for first-time parents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bio-based material sourcing and third-party certification infrastructure, favoring asset-light brand aggregators over captive manufacturing plays. Acquisition targets should profile as clean-label specialists with National Eczema Association endorsements and established specialty channel placement in California and New York Metro corridors. The signal to watch is EPA enforcement acceleration on chemical exposure thresholds for infant dermal contact products, which would force portfolio-wide reformulation decisions among legacy incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FDA evolving stance on per- and polyfluoroalkyl substances redirects R&D spending toward alternative material sourcing pipelines. |
| Subscription Commerce Buildout | Automated replenishment algorithms capture lifetime value through pediatrician-endorsed bundling and recurring diaper purchases. |
| Medicaid-Eligible Segment Entry | Texas and Florida birth cohorts with public insurance coverage remain underserved by premium organic brands. |
| Pediatric Dermatology Integration | National Eczema Association endorsement unlocks prescription-adjacent positioning and insurance-adjacent reimbursement pathways. |
| Reusable Hardware-as-Service | Subscription-based laundering logistics address sustainability-motivated parents in Seattle, Portland, and Austin metropolitan clusters. |
Research Methodology
The analysis maps diapers, wipes, skincare, and feeding accessories segments, each validated through category buyers at mass retailers, brand managers at national manufacturers, supply planners at distributors, and procurement leads at organic feedstock suppliers. Primary interview insights triangulate against Nielsen retail audit data, FDA cosmetic ingredient disclosure filings, EPA chemical exposure threshold determinations, and customs records for organic cotton and plant-based polymer imports. Bottom-up volume builds and top-down macroeconomic anchors reconcile through iterative stakeholder feedback loops.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models product type, age group developmental stage, distribution channel mix, and brand certification tier as core segmentation dimensions. CAGRs derive from regression-adjusted historical trajectories and adoption curve inflection points for subscription commerce and clean-label substitution. Forecast inputs incorporate birth rate concentration patterns in Texas and California metropolitan corridors and EPA regulatory enforcement probability assessments.
Underlying assumptions cover sustained FDA cosmetic ingredient transparency requirements and stable organic feedstock certification capacity, with deviation risk concentrated in California Proposition 65 litigation exposure and single-source biomaterial dependency for non-fluorinated coatings. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Wipes Market
Baby Products
Kids Activity Box Market
Baby Products
Baby Digital Monitor Market
Baby Products
Durable Juvenile Products Market
Baby Products
Baby Bottle Holder Market
Baby Products
Baby Care and Mother Care Market
Baby Products
Baby Pacifier Market
Baby Products
Children Products Market
Baby Products
France Baby Care Products Market
Baby Products
Baby High Chair Market
Baby Products
Baby Bottle Warmers Market
Baby Products
Baby Stroller Market
Baby Products
Baby Swing Market
Baby Products
Baby Tableware Market
Baby Products
Brazil Baby Care Products Market
Baby Products
Smart Baby Monitor Market