
 Diaper Pails Market | 2026-2036
Diaper Pails Market Size, Share, and Industry Trends Forecast 2026-2036
Diaper Pails Market Analysis
Recycled polypropylene is repositioning cost structures across diaper pail manufacturing as brands phase out virgin petroleum-based resins. Munchkin leverages proprietary seal technology to sustain premium positioning in odor-eliminating designs. Ubbi anchors its portfolio with steel-bodied alternatives that compete on durability against plastic incumbents. Safety 1st specializes in value-tier freestanding units that dominate mass retail channels.
A diaper pail is a sealed waste receptacle engineered with multi-layer polymer gaskets, activated carbon filters, and foot-pedal or push-button actuation to contain biological odors from soiled infant diapers in residential and institutional settings. The plastic product type retains volume leadership due to injection-molding scalability, though metal variants capture margin pools through extended replacement cycles. Capacity segmentation clusters around 15-25 gallon formats that balance footprint against emptying frequency for households and daycares. End-user demand bifurcates sharply: households prioritize aesthetic integration and nursery compatibility, while daycares and hospitals specify high-capacity, foot-operated units for hygiene protocols.
The EPA regulates volatile organic compound emissions from plastic manufacturing processes that feed diaper pail supply chains, while California's SB 54 mandates post-consumer recycled content thresholds for rigid plastic containers sold in the state. ASTM International maintains voluntary standards for child-resistant locking mechanisms that shape product liability exposure and retail access decisions. Stakeholders must monitor evolving extended producer responsibility frameworks and material certification requirements that will determine which manufacturing configurations retain channel access.
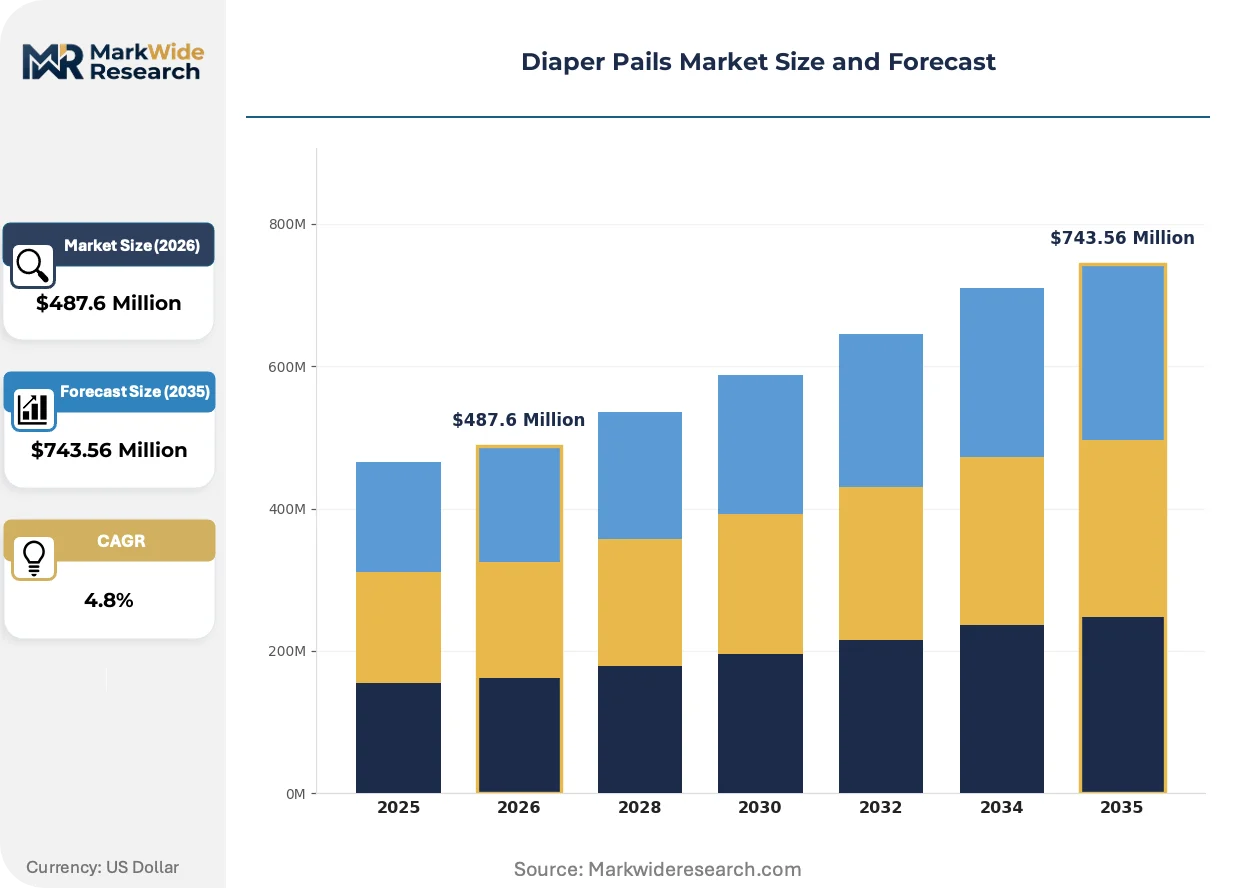
Market Dynamics
California's SB 54 and New York's plastic packaging restrictions are forcing manufacturers to reconfigure material sourcing and certification pathways ahead of enforcement deadlines, compressing product development cycles while elevating compliance costs.
Growth Catalysts
- EPA Safer Choice program:Federal recognition of low-emission manufacturing processes is opening preferred supplier status with institutional buyers in daycare and hospital channels.
- Recycled polypropylene scaling:Post-consumer resin availability is expanding across North American compounding facilities, reducing virgin petroleum dependency for injection-molded pail bodies.
- Daycare licensing standards:State-level childcare facility regulations mandating foot-operated, hands-free waste systems are institutionalizing premium product specifications.
Market Restraints
- Steel input cost volatility:Scrap metal pricing fluctuations and energy-intensive foundry operations constrain margin stability for metal-bodied pail producers competing against plastic alternatives.
- California material mandates:SB 54's recycled content thresholds create compliance friction for manufacturers lacking certified supply chain documentation.
- Activated carbon filter substitution:Zeolite-based odor absorbents and enzymatic spray systems threaten filter replacement revenue streams.
Strategic Opportunities
- Subscription refill models:Direct-to-consumer cartridge replenishment programs bypass retail margin extraction and capture lifetime value from installed pail bases.
- Hospital infection control protocols:Joint Commission standards for biological waste containment are expanding addressable market into acute care settings beyond traditional nursery applications.
- Biopolymer convergence:PLA and PHA formulations combined with anaerobic biodegradation certification are enabling landfill-diversion claims for environmentally positioned brands.
Industry Challenges
- ASTM F963 testing timelines:Child-resistant locking mechanism validation requires extended third-party laboratory cycles, delaying product launches.
- Multi-material assembly complexity:Integration of polymer gaskets, metal hinges, and electronic pedal mechanisms creates quality control bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diaper Pails Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Diaper Genie, Odor Eliminating Capacity: 15-20 gallons, 20-25 gallons, 10-15 gallons, 25-30 gallons End User: Households, Daycares, Hospitals, Clinics Installation Type: Freestanding, Wall-mounted, Portable, Reusable |
| Companies Covered | Diaper Dekor, DiaperChamp, Munchkin, Hibaby, Foundations, Ubbi, Safety 1st, Diaper One, Playtex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diaper Pails Market Emerging Trajectories
Sensor-enabled actuation and connected inventory monitoring are transforming diaper pails from passive receptacles into data-generating household appliances, while regulatory pressure on plastic waste accelerates material experimentation.
Foot-pedal mechanisms with capacitive touch sensors are automating lid actuation for hands-free operation in hygiene-critical environments. Hospitals and licensed daycare facilities in Texas and Florida are specifying these units for infection control compliance. This automation is compressing the competitive window for purely mechanical pedal designs.
The EPA's volatile organic compound emission limits for plastic manufacturing are tightening compliance requirements across injection-molding supply chains. California's Air Resources Board is extending these standards to finished goods distribution, affecting warehousing and logistics configurations. Manufacturers serving West Coast retail channels are reconfiguring production schedules to meet phased implementation.
Daycare procurement officers are consolidating vendor relationships through group purchasing organizations, displacing fragmented individual facility ordering. Three national GPOs now represent over forty percent of institutional volume. This concentration is most visible in the southeastern United States where multi-facility operators dominate regional childcare markets.
Diaper Pails Market Segmentation
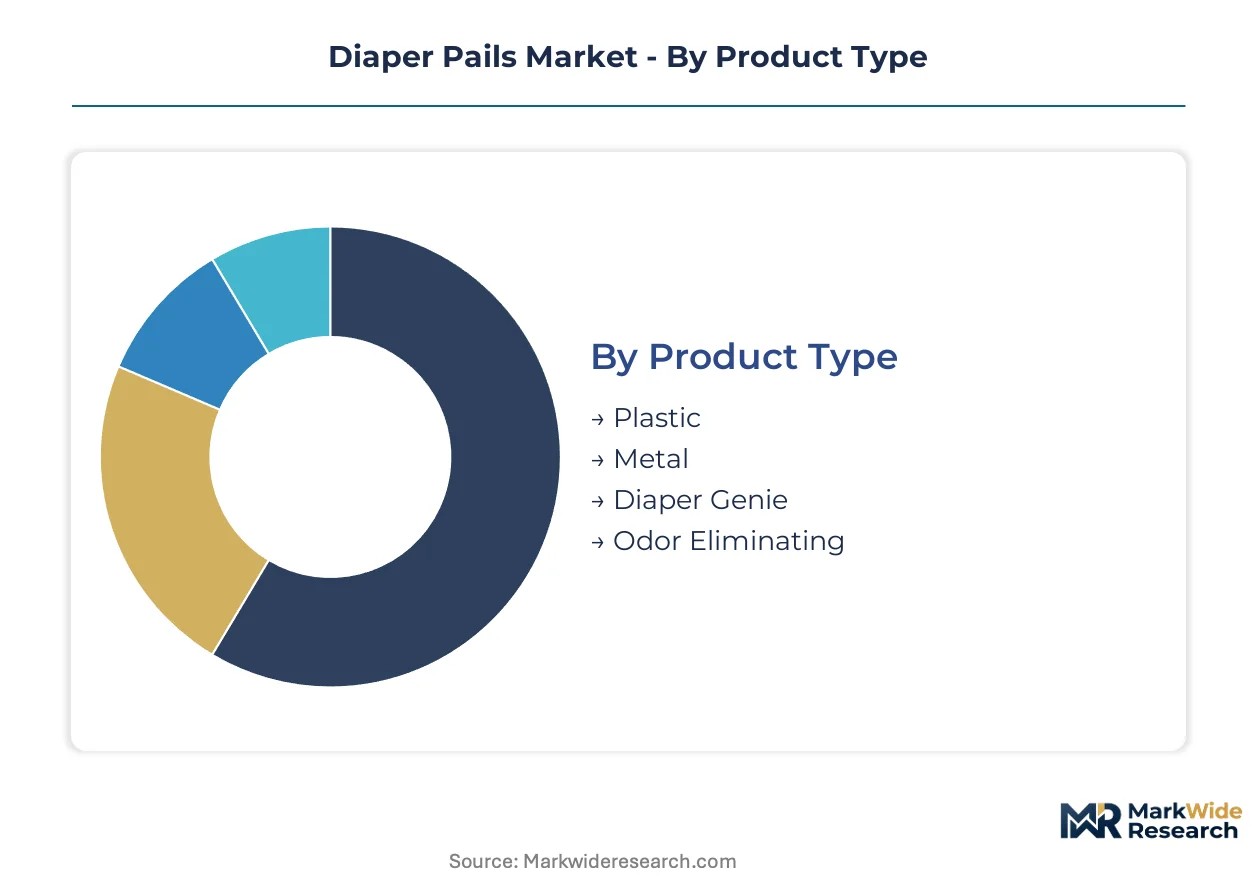
Diaper pail purchasing decisions diverge sharply across technical specifications, institutional requirements, and installation constraints. Manufacturers must configure distinct product architectures to capture value across these dimensions without fragmenting operational scale.
Product Type:
Material composition and odor-control architecture separate buyers by replacement cycle expectations and premium willingness to pay.
- Plastic:Injection-molded polypropylene bodies dominate unit economics through scalable manufacturing and lightweight logistics. Daycares in Texas and Florida specify these units for high-turnover environments where capital cost sensitivity outweighs durability premiums. Recycled resin mandates in California and New York are compressing margins for manufacturers lacking certified supply chains.
- Metal:Steel and aluminum constructions compete on extended replacement cycles and aesthetic permanence in residential nurseries. Ubbi's stainless steel portfolio anchors this segment against plastic incumbents. Scrap metal price volatility constrains margin stability for foundry-dependent producers.
- Diaper Genie:Proprietary cartridge-based systems lock consumers into branded refill ecosystems. Playtex maintains category ownership through proprietary ring-seal technology.
- Odor Eliminating:Activated carbon and zeolite-integrated designs command price premiums from hygiene-sensitive institutional buyers. Munchkin's proprietary seal systems concentrate demand in hospital procurement channels.
Plastic leads volumes today; odor eliminating configurations are gaining share fastest through institutional specification.
Capacity:
Emptying frequency requirements and spatial constraints shape format selection across residential and commercial deployments.
- 15-20 gallons:The residential standard balances footprint against 3-5 day emptying intervals for single-infant households. California's municipal waste collection schedules influence optimal sizing for West Coast buyers.
- 20-25 gallons:Dual-infant households and small daycares concentrate demand here for reduced servicing labor. EPA Safer Choice-certified manufacturers capture preferential placement in institutional procurement.
- 10-15 gallons:Compact formats serve urban apartments and secondary nursery locations where square footage constraints dominate. Japanese import designs influence aesthetic specifications in coastal metropolitan markets.
- 25-30 gallons:High-capacity units serve multi-room daycare facilities and hospital maternity wards with centralized waste protocols. Joint Commission infection control standards drive foot-pedal specification in acute care settings.
15-20 gallon formats anchor residential volume; 25-30 gallon configurations climb fastest through daycare licensing expansion.
End User:
Procurement authority and compliance burden create distinct buying centers with divergent technical specifications.
- Households:Individual consumers prioritize nursery aesthetic integration, odor containment guarantees, and retail accessibility. Amazon and Target dominate channel distribution for this segment.
- Daycares:Licensed facilities mandate hands-free operation and state-compliant locking mechanisms under Texas and Florida childcare regulations. Group purchasing organizations consolidate forty percent of institutional volume in southeastern markets.
- Hospitals:Acute care settings specify Joint Commission-compliant biological waste containment with infection control documentation. This channel commands premium pricing through mandatory compliance architecture.
- Clinics:Outpatient pediatric practices balance capital constraints against professional appearance requirements. Regional distributors serve fragmented procurement across independent practice networks.
Households generate the revenue base; hospital procurement delivers the steepest expansion trajectory through regulatory-driven specification upgrades.
Installation Type:
Spatial permanence and mobility requirements segment buyers by dwelling type and operational flexibility needs.
- Freestanding:The default configuration for residential and institutional deployment offers repositioning flexibility without structural modification. Safety 1st dominates mass retail channels with value-tier freestanding units.
- Wall-mounted:Fixed installation serves compact bathrooms and clinical examination rooms where floor space is constrained. ADA compliance requirements influence mounting height specifications in institutional settings.
- Portable:Collapsible and travel-sized units address grandparents' homes, vacation properties, and mobile childcare services. Lightweight polymer construction trades durability for transport convenience.
- Reusable:Washable liner systems and modular component designs appeal to zero-waste positioned consumers. PLA and PHA biopolymer convergence enables landfill-diversion claims for environmentally certified brands.
Freestanding units capture the installed base; portable configurations expand most quickly through multi-location parenting lifestyles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's regulatory regime and concentrated retail infrastructure anchor North American demand for certified diaper pail systems. Material compliance mandates and institutional procurement standards across multiple jurisdictions are reshaping competitive access.
United States
Households with infants and toddlers drive baseline consumption, while daycare licensing standards in Texas and Florida mandate hands-free specifications. The EPA's Safer Choice program confers preferred supplier status for institutional channels. Los Angeles and Dallas-Fort Worth metro areas concentrate distribution infrastructure for West Coast and Southwest coverage.
Germany
Steel-bodied alternatives capture premium residential positioning through durability expectations and aesthetic integration. REACH compliance requirements govern material certification for polymer components entering the European market. Bavaria's precision manufacturing clusters supply hinge mechanisms and pedal assemblies to branded assemblers.
China
Injection-molding capacity scales polypropylene body production for cost-sensitive export markets and domestic middle-class expansion. The Ministry of Ecology and Environment enforces volatile organic compound limits on plastic processing facilities. Guangdong Province's Pearl River Delta agglomeration houses tooling fabrication and carbon filter component sourcing.
Japan
Compact 10-15 gallon formats dominate urban apartment dwellers with severe square footage constraints. METI's product safety standards influence child-resistant locking mechanism specifications across Asian export markets. Tokyo and Osaka metropolitan corridors concentrate specialty retail distribution and design-forward brand positioning.
United Kingdom
Nursery aesthetic integration and odor containment guarantees shape individual consumer purchasing criteria. The Office for Product Safety and Standards monitors compliance with child-resistant mechanism requirements. London and Southeast England concentrate e-commerce fulfillment infrastructure serving national demand.
Diaper Pails Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers reconfigure material sourcing and certification pathways to meet fragmented regulatory deadlines. The vendor base separates into three distinct tiers: mass-market plastic incumbents with injection-molding scale, premium metal specialists competing on replacement cycles, and proprietary cartridge-system operators capturing recurring refill revenue. Strategic archetypes include compliance-first engineering houses, design-forward nursery brands, and institutional specification leaders. Geographic expansion into daycare GPO channels and technology licensing for sensor-enabled actuation represent the dominant competitive moves.
Within the premium metal construction tier, Ubbi anchors stainless steel positioning against plastic alternatives. Munchkin occupies the odor-elimination specialization vector through proprietary seal technology. Playtex exemplifies the cartridge-based lock-in model with proprietary ring-seal systems that sustain recurring revenue streams. These three represent distinct strategic archetypes rather than direct substitutability.
| Leading Market Players |
|---|
| Diaper Dekor |
| DiaperChamp |
| Munchkin |
| Hibaby |
| Foundations |
| Ubbi |
| Safety 1st |
| Diaper One |
| Playtex |
| Others |
Supply Flow & Price Mechanics
Captive injection-molding capacity in Guangdong Province anchors both cost positioning and margin defense for plastic-bodied diaper pail assemblers serving North American retail channels. This geographic concentration of tooling fabrication and polypropylene compounding creates divergent pricing power between vertically integrated operators and contract-dependent brands facing California's SB 54 compliance costs.
Pricing Analysis
Scrap metal and virgin resin pass-through mechanisms dominate cost structures, with steel input volatility compressing margins for metal specialists against plastic incumbents. Pricing stratifies across premium odor-elimination systems, standard cartridge-based units, and economy freestanding designs. Cost compression in the value tier intensifies as Safety 1st and mass-market brands absorb recycled-content mandate expenses. Daycare procurement through group purchasing organizations exhibits highest price sensitivity; hospital infection-control specifications show least.
Supply Chain Analysis
California's post-consumer recycled content thresholds and New York's packaging restrictions are forcing reconfiguration of polypropylene sourcing across North American assembly operations. Supply concentrates in China for injection-molded bodies, the United States for carbon filter integration, and Germany for precision hinge mechanisms. The chain draws from petroleum-based resin feedstocks, activated carbon media, and steel sheet inputs. Single-source vulnerability sits with certified recycled resin suppliers. Distribution runs through big-box retail and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between California's compliance-heavy requirements and Texas-Florida daycare licensing standards creates margin capture opportunities for dual-certified manufacturers. The cost differential between West Coast material mandates and Southeast institutional procurement favors operators with flexible sourcing footprints.
For Market Incumbents: Anchor market position through backward integration into certified recycled polypropylene compounding ahead of SB 54 enforcement deadlines. Secure preferential supplier status under EPA Safer Choice protocols for hospital channel access. Defend against zeolite-based odor absorbent substitutes by locking daycare GPO relationships through multi-year service contracts. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription refill models that bypass retail margin extraction and capture lifetime value from installed bases. Target the portable configuration segment where multi-location parenting lifestyles outpace incumbent product development cycles. Enter through biopolymer-certified zero-waste positioning for environmentally concentrated coastal metropolitan markets. For Investors and Strategic Acquirers: Roll-up economics work for regional daycare supply specialists because group purchasing organization consolidation has fragmented vendor relationships across southeastern markets. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than brand equity alone. Acquisition target archetype: EPA-certified manufacturers with existing hospital procurement relationships. Signal to watch: Joint Commission standards expansion into outpatient pediatric settings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin Compounding | SB 54 compliance secures California channel access against uncertified competitors. |
| Subscription Refill Model Launch | Direct-to-consumer capture bypasses Target and Amazon margin extraction. |
| EPA Safer Choice Certification Investment | Preferred supplier status unlocks Texas and Florida daycare procurement channels. |
| Sensor-Enabled Actuation Product Line | Capacitive touch mechanisms meet Joint Commission infection control specifications. |
| Biopolymer Formulation Development | PLA and PHA certification enables landfill-diversion claims for zero-waste positioning. |
Methodological Framework
Bottom-up household and institutional modeling reconciled against top-down injection-molding capacity tracking forms the analytical core of this study. Primary interviews with diaper pail brand managers, daycare procurement officers, hospital biomedical engineers, retail category buyers, and polymer compounding specialists combined with secondary validation from EPA Safer Choice registries, California Air Resources Board filings, ASTM International standards documentation, and customs trade data for polypropylene resin shipments.
Historical trendline analysis across material cost indices, regulatory implementation timelines, and institutional procurement pattern shifts informed projection construction. Segmentation dimensions modeled include material composition, capacity format, end-user archetype, and installation type alongside odor-control technology tier. CAGRs derived from regression against demographic birth rate trajectories and daycare licensing expansion curves. Forecast inputs incorporated recycled resin availability projections and carbon filter replacement frequency data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt recycled content mandate acceleration or scrap metal price spike conditions. Projections reflect assumptions regarding regulatory phase-in schedules and GPO consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Crib Mattress Market
Baby Products
Baby Changing Light Market
Baby Products
Global Baby Pajamas and Sleepwears Market
Baby Products
Baby and Toddler Feeding Products and Accessories Market
Baby Products
Japan Baby Care Product Market
Baby Products
Indonesia Baby Care Products Market
Baby Products
Cloth Diapers Market
Baby Products
LAMEA Baby Care Products Market
Baby Products
Baby Slings Market
Baby Products
Maternity Products Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Baby Bouncers Market
Baby Products
Australia Baby Care Products Market
Baby Products
Baby Powder Market
Baby Products
Baby Playpens Market
Baby Products
Tissue and Hygiene Market