
 Baby Walker Market | 2026-2036
Baby Walker Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Walker Market Analysis
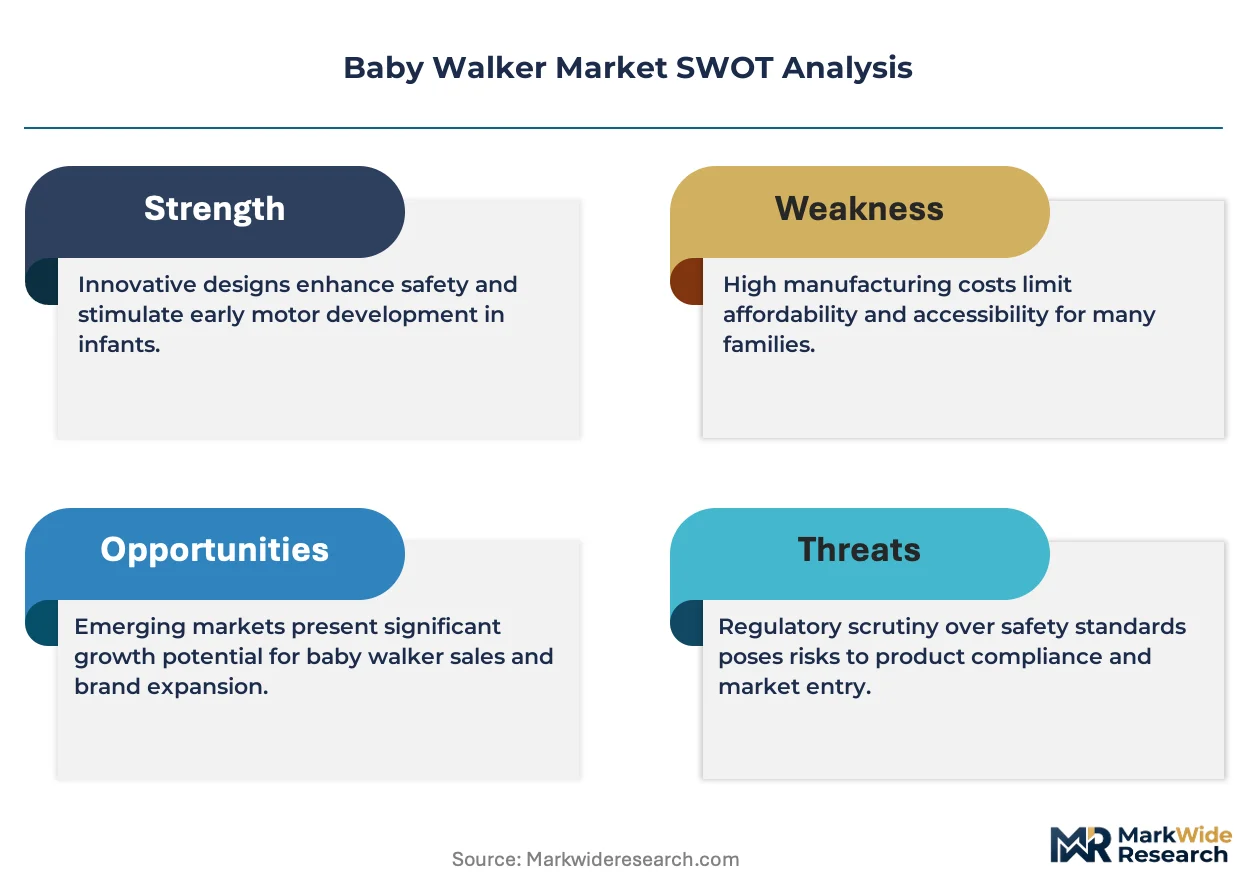
REACH compliance is pivoting how European manufacturers source phthalate-free plastics and redesign braking mechanisms. Chicco Limited leverages backward integration into polymer compounding to sustain margin control across its walker lines. Fisher-Price, Inc. anchors North American shelf presence through licensed character partnerships and big-box exclusivity. Kids II, Inc. differentiates via pediatric-therapist-designed activity centers that command premium positioning.
A baby walker is a wheeled mobility aid with a suspended seat frame, typically constructed from injection-molded polypropylene or bent hardwood, designed to support infants who can hold their heads upright while allowing foot-propelled movement across flat surfaces. Convertible walkers and sit-to-stand variants now lead innovation pipelines as parents seek extended product lifecycles beyond the traditional six-to-twelve month usage window. Plastic dominates material mix due to cost scalability, though wood gains traction in European premium channels where sustainability credentials influence purchase decisions. Infant-focused configurations remain the volume core, while toddler-oriented activity walkers capture disproportionate margin as bundled electronic features justify higher price points.
The US Consumer Product Safety Commission enforces mandatory stationary activity center standards alongside voluntary ASTM F977 walker guidelines, creating a bifurcated compliance landscape that favors larger suppliers with dedicated testing laboratories. China's SAMR implements national standard GB 14749 for infant walkers, requiring domestic and imported products to pass tip-resistance and opening-width tests before market authorization. Stakeholders must monitor pending revisions to the EU Toy Safety Directive's chemical migration limits, as these will force reformulation of soft-touch TPE grips and printed fabric components within the next regulatory cycle.
Market Dynamics
Convertible walker architectures are compressing replacement cycles as parents demand multi-stage utility from a single purchase, forcing manufacturers to redesign frame geometries and modular seating systems around extended-use specifications rather than traditional six-month lifespans.
Growth Catalysts
- REACH chemical migration limits:ECHA's tightening phthalate restrictions in soft-touch grips are accelerating reformulation investments that differentiate compliant European suppliers from import-dependent competitors.
- Tier-two Indian urbanization:Organized retail penetration in cities like Jaipur and Lucknow is creating branded shelf access where unorganized toy dealers previously dominated walker distribution.
- Injection-molded polypropylene scalability:Advances in thin-wall molding techniques are reducing per-unit material costs while maintaining structural load ratings for heavier toddler configurations.
Market Restraints
- Propylene feedstock volatility:Crude-linked polymer pricing swings compress margin predictability for plastic-dominant walker portfolios, particularly affecting mid-tier manufacturers without captive resin supply.
- Zhejiang supplier concentration:Over half of global walker frame stamping and wheel assembly capacity clusters in a single Chinese province, exposing buyers to localized logistics disruptions and tariff exposure.
- ASTM F977 voluntary status:The absence of mandatory federal standards in the United States allows marginal products to compete on price against tested alternatives, degrading category quality signaling.
Strategic Opportunities
- Brazilian northeast corridor:Underpenetrated cities like Recife and Fortaleza lack dedicated infant mobility retail, creating first-mover advantage for brands establishing localized assembly partnerships.
- EU Green Deal circularity mandates:Upcoming extended producer responsibility rules will reward modular, disassemblable walker designs with reduced end-of-life fees and preferential public procurement access.
- Telehealth-integrated activity tracking:Convergence of Bluetooth-enabled step counters with pediatric physical therapy platforms is opening subscription revenue streams alongside hardware sales.
Industry Challenges
- GB 14749 testing backlog:China's SAMR authorization queues for tip-resistance certification are extending product launch timelines by four to six months for new market entrants.
- Multi-material bonding expertise:Wood-plastic hybrid construction requires specialized adhesive chemistry and humidity-controlled curing environments that scarce process engineers can configure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Walker Market |
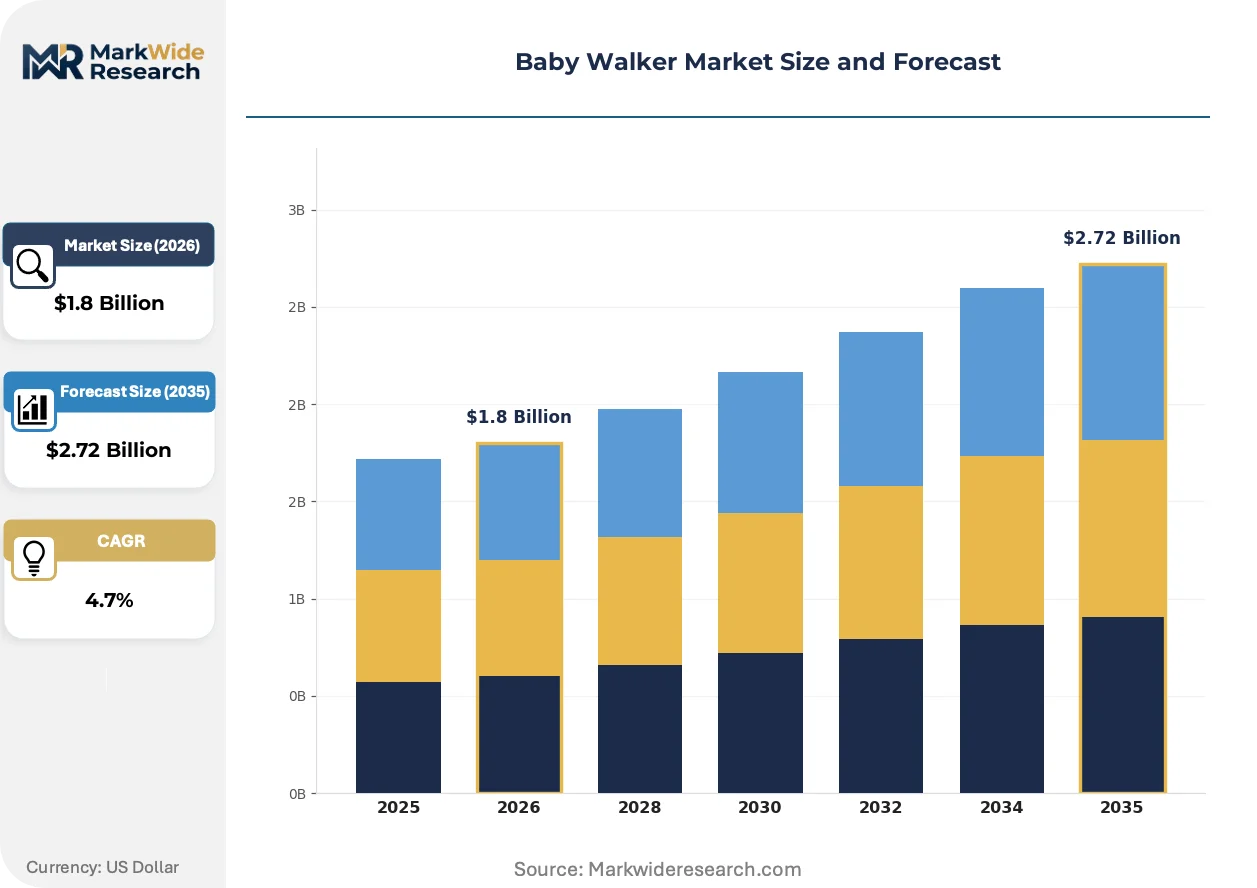
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Walkers, Convertible Walkers, Activity Walkers, Sit-to-Stand Walkers Material: Plastic, Wood, Metal, Fabric End User: Parents, Caregivers, Retailers, Distributors Age Group: Infants, Toddlers, Pre-schoolers, Others |
| Companies Covered | Chicco Limited, Fisher-Price, Inc., Kids II, Inc., Baby Trend, Inc., Dream On Me, Inc., Delta Children's Products Corp., Brevi s.r.l., Mothercare plc, Hefei Craft Child Product Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Walker Market Emerging Trajectories
Walker functionality is migrating beyond passive mobility toward active developmental instrumentation, with sensor integration and convertible architectures redefining what parents expect from a single purchase.
Smart activity tracking is expanding into premium walker lines as MEMS accelerometers and pressure-sensitive footplates capture gait metrics for pediatric telehealth consultations. First-time parents in digitally connected households are adopting these configurations at three times the rate of conventional walkers. The data infrastructure is compressing warranty and after-sales service into continuous remote monitoring relationships.
REACH substance restrictions are forcing immediate redesign of TPE grip compounds and printed fabric dyes across European supply chains. Manufacturers holding pre-validated alternative formulations are capturing shelf space as competitors face six-month reformulation cycles. Sit-to-stand variants with textile components are most affected, driving accelerated migration to laser-etched polypropylene surfaces.
Subscription-based product rotation is displacing outright ownership in Scandinavian urban markets, where parents lease convertible walkers through bundled pediatric service packages. Specialty retailers in Stockholm and Copenhagen are piloting these programs, with logistics platforms handling sanitization and size exchanges. The model is compressing brand loyalty around service reliability rather than initial purchase satisfaction.
Baby Walker Market Segmentation
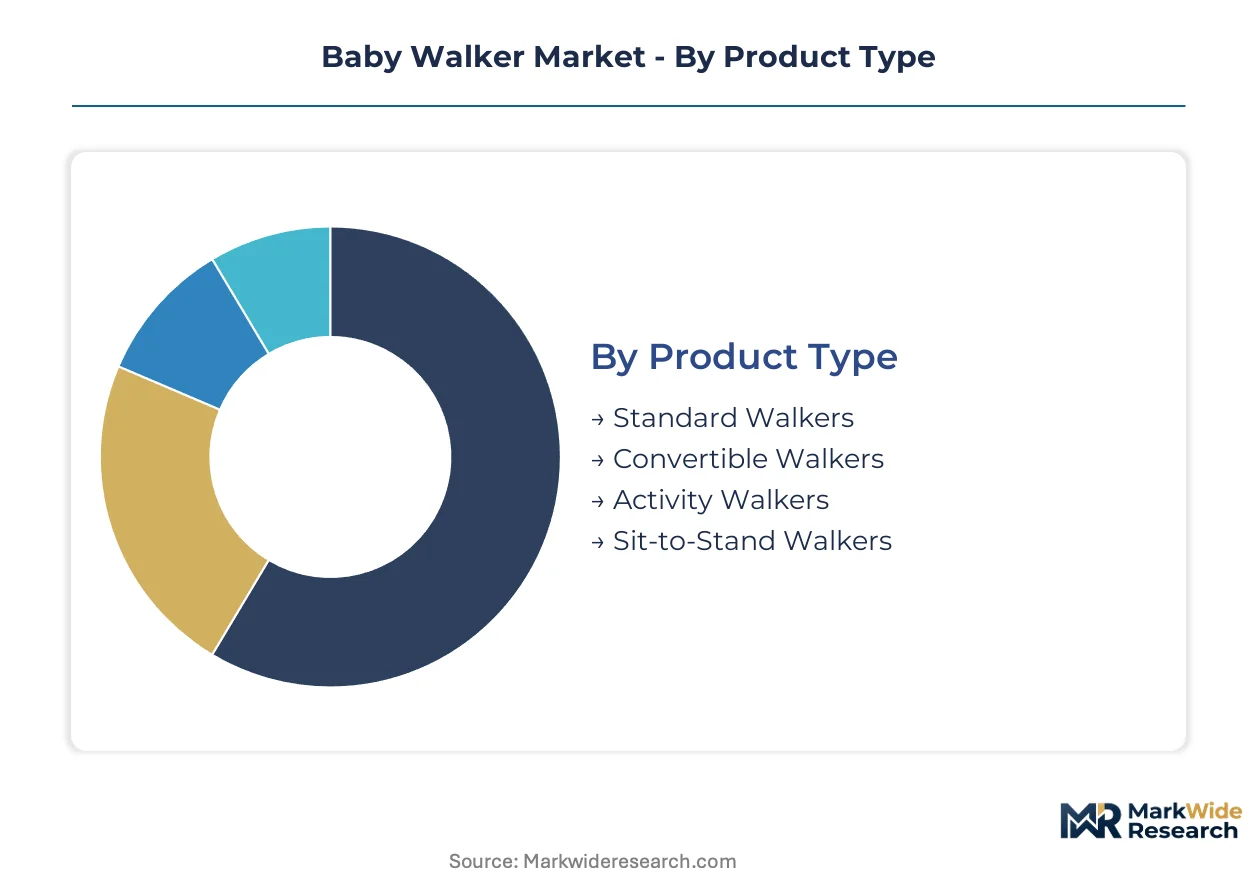
Segmentation in the baby walker market reveals how product lifecycles and replacement patterns vary across construction methods, purchase channels, and developmental stages. Manufacturers align R&D spending with segments showing compressed upgrade cycles or premium pricing tolerance.
Product Type:
Upgrade cycles differ sharply across walker architectures, with multi-stage designs commanding pricing premiums that offset lower replacement frequency.
- Convertible Walkers:Modular frame systems accommodate seated mobility, standing support, and push-walker modes through adjustable seat heights and removable activity trays. Urban Chinese first-time parents in tier-one cities are expanding purchases of these configurations as extended product lifecycles justify higher upfront expenditure.
- Standard Walkers:Fixed-frame suspended-seat designs remain the volume baseline for price-sensitive distribution channels. Procurement concentrates in India's tier-two cities where organized retail penetration is displacing unorganized toy dealers with branded alternatives.
- Activity Walkers:Electronic feature bundles including lights, sounds, and interactive panels capture disproportionate margin in North American big-box retail.
- Sit-to-Stand Walkers:Pediatric-therapist-designed configurations command premium positioning through developmental credentialing.
Standard walkers sit at the top of the volume ranking, with convertible walkers climbing the fastest.
Material:
Cost tier differentiation separates premium positioning from mass-market penetration, with raw material selection directly determining margin structure and channel access.
- Plastic:Injection-molded polypropylene dominates global production due to thin-wall molding advances that reduce per-unit material costs while maintaining structural load ratings. Zhejiang province clusters over half of global frame stamping and wheel assembly capacity, exposing buyers to localized logistics disruptions.
- Wood:Bent hardwood construction gains traction in European premium channels where sustainability credentials influence purchase decisions and REACH-compliant finishes command shelf space.
- Metal:Steel and aluminum reinforcement components strengthen braking mechanisms under EU General Product Safety Regulation stability testing protocols.
- Fabric:Textile seat inserts and printed fabric components face pending EU Toy Safety Directive chemical migration limit revisions.
Plastic captures the largest volume share, with wood expanding most quickly in premium European distribution.
End User:
Customer type determines pricing elasticity and service bundling opportunities, with institutional purchasers demanding specifications that diverge from consumer preferences.
- Parents:First-time purchasers drive feature complexity and telehealth-integrated activity tracking adoption at three times the rate of repeat buyers.
- Caregivers:Professional childcare facilities prioritize durability certifications and sanitization-friendly surfaces over electronic features.
- Retailers:Organized chains in Indian tier-two cities and Brazilian northeast corridors are consolidating shelf space around compliant suppliers with localized assembly partnerships.
- Distributors:Wholesale procurement concentrates on standard walkers with predictable inventory turns and minimal SKU complexity.
Parents generate the highest per-unit revenue, with retailers gaining share fastest through channel consolidation in emerging markets.
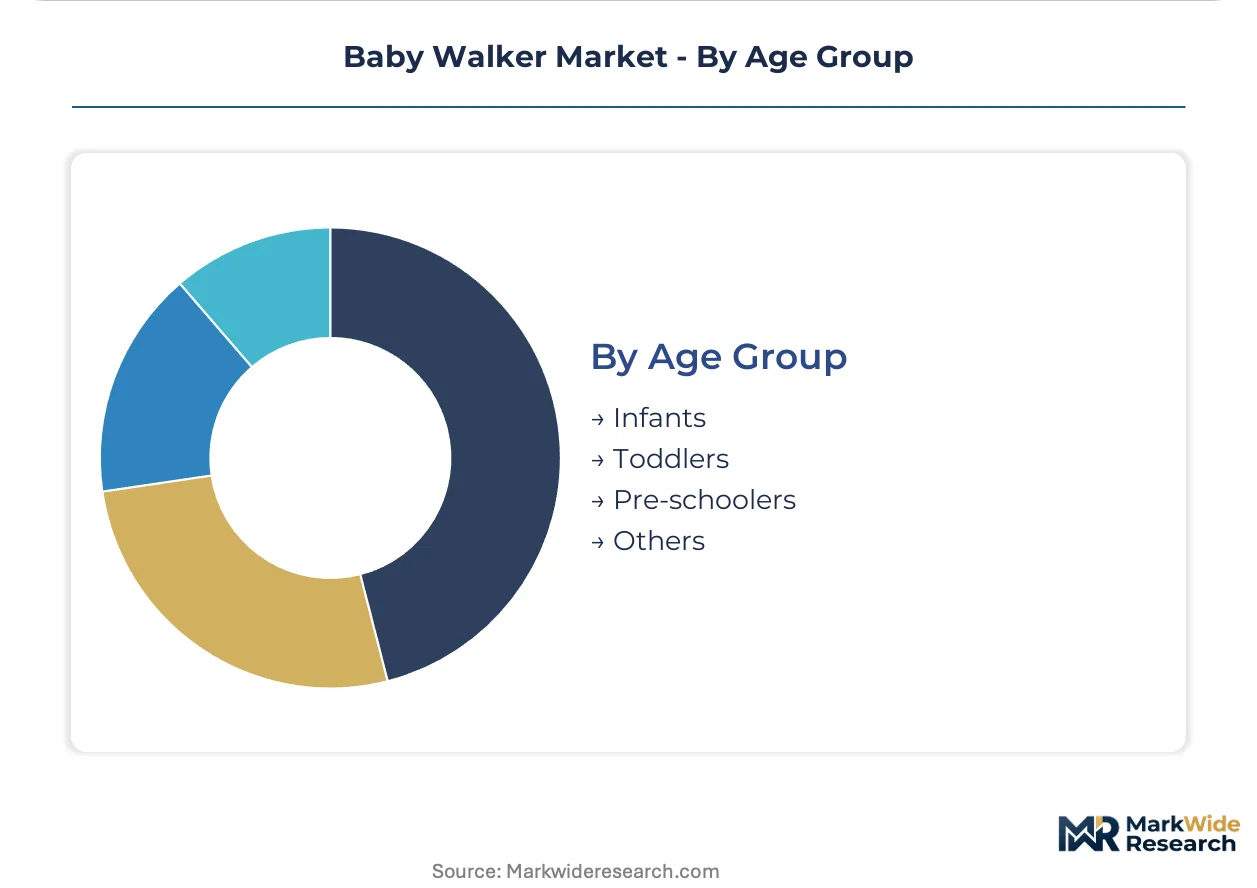
Age Group:
Developmental stage alignment dictates safety certification requirements and feature sophistication, with boundary-crossing designs capturing margin from overlapping segments.
- Infants:Head-up stability support for six-to-twelve month usage windows remains the volume core, with GB 14749 tip-resistance and opening-width testing mandatory for China market authorization.
- Toddlers:Heavier configurations with reinforced load ratings justify bundled electronic features and premium price points in North American and European distribution.
- Pre-schoolers:Push-walker and activity center variants extend utility beyond traditional walker lifecycles, with ASTM F977 voluntary guidelines creating quality signaling gaps exploited by marginal competitors.
- Others:Therapeutic and special-needs adaptations require pediatric-therapist design validation and command niche premium positioning.
Infants anchor volume production, with toddlers showing the steepest expansion trajectory as parents seek extended-use specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer compounding specialists cluster in Zhejiang province and the Po Valley, anchoring walker frame production networks that feed assembly operations across three continents. These engineering talent pools sustain thin-wall molding expertise and REACH-compliant formulation capabilities that differentiate regional supply bases.
United States
Licensed character partnerships drive shelf presence in big-box retail channels, with ASTM F977 voluntary guidelines creating quality signaling gaps that marginal competitors exploit. The CPSC enforces mandatory stationary activity center standards alongside voluntary walker protocols, bifurcating compliance burdens. Injection-molding capacity concentrates in Ohio and Michigan, serving domestic assembly of electronic-featured toddler configurations.
China
First-time parents in tier-one cities expand purchases of convertible walkers as extended product lifecycles justify higher upfront expenditure. SAMR implements GB 14749 national standards requiring tip-resistance and opening-width testing before market authorization, with certification queues extending launch timelines. Zhejiang province hosts over half of global frame stamping and wheel assembly capacity, exposing buyers to localized logistics disruptions.
Germany
Sustainability credentials influence purchase decisions in premium channels, with bent hardwood construction gaining traction among environmentally conscious consumers. ECHA's REACH restrictions accelerate reformulation of TPE grip compounds and printed fabric dyes, rewarding manufacturers with pre-validated alternative formulations. The KBA and federal consumer protection frameworks enforce stability testing protocols under updated EU General Product Safety Regulation mandates.
India
Organized retail penetration in tier-two cities like Jaipur and Lucknow creates branded shelf access where unorganized toy dealers previously dominated distribution. BIS standards and import certification requirements shape procurement specifications for domestic and foreign suppliers. Maharashtra and Gujarat host emerging assembly partnerships targeting price-sensitive volume segments.
Brazil
Underpenetrated northeast corridor cities including Recife and Fortaleza lack dedicated infant mobility retail, creating first-mover advantage for brands establishing localized assembly partnerships. ANVISA regulates product safety for imported and domestically manufactured walkers, with compliance costs favoring larger suppliers. São Paulo state anchors distribution infrastructure serving southeastern demand concentration.
Baby Walker Market Vendor Landscape
The competitive structure tilts toward brand-licensed multinationals with dedicated testing laboratories and captive retail shelf agreements. Three distinct archetypes populate the landscape: vertically integrated polymer compounders controlling resin supply chains, pediatric-therapist-credentialed specialists commanding premium positioning, and scale-driven assemblers competing on thin-wall molding efficiency. Dominant competitive moves include backward integration into polymer compounding to sustain margin control, and strategic partnerships with organized retail chains in emerging market tier-two cities.
Within the vertically integrated tier, Chicco Limited exemplifies captive supply chain architecture, while Fisher-Price, Inc. anchors licensed character positioning in North American mass retail. Kids II, Inc. occupies the pediatric-credentialed specialist position. These three entities represent divergent strategic bets on formulation control, intellectual property leverage, and clinical validation respectively.
| Leading Market Players |
|---|
| Chicco Limited |
| Fisher-Price, Inc. |
| Kids II, Inc. |
| Baby Trend, Inc. |
| Dream On Me, Inc. |
| Delta Children's Products Corp. |
| Brevi s.r.l. |
| Mothercare plc |
| Hefei Craft Child Product Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Backward integration into polymer compounding anchors both supply security and pricing power for manufacturers controlling captive resin streams, while import-dependent competitors absorb margin volatility from crude-linked polypropylene feedstock swings.
Pricing Analysis
Bundled subscription services in Scandinavian markets diverge sharply from transactional per-unit sales dominating Indian tier-two cities. Three-tier pricing structure across premium, standard, and economy levels separates telehealth-integrated activity trackers from basic suspended-seat designs. Price differentiation stems from REACH-compliant formulation costs and pediatric-therapist credentialing. First-time parents in digitally connected households show lowest price sensitivity, while organized retail chains in emerging markets negotiate aggressively on volume procurement.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and Brazil's ANVISA localization incentives are reshaping sourcing patterns away from pure import dependency. Frame stamping and wheel assembly concentrate in China's Zhejiang province, South Korea's polymer compounding corridor, and Italy's Po Valley molding clusters. Raw material flows draw from Saudi propylene feedstock, German REACH-compliant additive packages, and Vietnamese textile components. Single-province concentration in Zhejiang exposes buyers to tariff exposure and logistics chokepoints. Distribution runs through big-box exclusivity agreements in North America and organized retail consolidation in Indian tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baby walker market functions as a stable compounder, with convertible architecture demand and regulatory compliance investments driving steady replacement cycle compression and margin expansion.
For Market Incumbents: Lock in polymer compounding capacity and SAMR pre-certification relationships to defend against new entrants facing GB 14749 testing backlogs. Prioritize pediatric-therapist design partnerships that justify premium positioning against price-competitive standard walker imports. For New Entrants and Emerging Players: The gap between economy-tier standard walkers and premium sit-to-stand configurations offers white-space entry through modular frame systems targeting Brazilian northeast corridor cities. Establish localized assembly partnerships in Recife or Fortaleza before incumbent shelf consolidation hardens. Pursue ANVISA compliance as a go-to-market differentiator where import-dependent competitors face cost disadvantages. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH reformulation investments and captive resin supply separate viable suppliers from margin-compressed assemblers. Target mid-tier manufacturers with validated alternative TPE formulations and established organized retail relationships in Indian tier-two cities. Watch SAMR certification queue lengths as an inflection signal for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Chicco Limited's captive resin supply insulates margins from propylene volatility. |
| Pediatric-Therapist Design Partnership | Kids II, Inc. commands premium positioning through clinical validation credentials. |
| Localized Assembly Partnership | First-mover brands in Brazil's northeast corridor capture shelf before consolidation. |
| REACH-Compliant Formulation Pre-Validation | European suppliers with alternative TPE compounds capture six-month lead times. |
| Telehealth Platform Integration | Bluetooth-enabled gait tracking opens subscription revenue alongside hardware sales. |
Methodological Framework
Bottom-up infant mobility modeling reconciled against top-down polymer supply tracking forms the analytical core of this study. Primary interviews with pediatric product brand managers, organized retail category buyers in India and Brazil, injection-molding plant engineers in Zhejiang and Ohio, and regulatory affairs specialists at SAMR and ANVISA combined with secondary validation from customs trade databases, SEC filings of listed toy manufacturers, BIS certification registries, and ECHA REACH substance restriction updates.
Historical trendline analysis of replacement cycle compression and material cost trajectories informed projection frameworks across the forecast period. Segmentation dimensions modeled include product architecture, material composition, end-user type, and age group alignment, with regional regulatory cluster effects and organized retail penetration rates as industry-specific inputs. CAGRs derived from volume-weighted segment growth rates reconciled against macroeconomic demand elasticity assumptions.
Caveats apply where SAMR certification queue extensions, propylene feedstock volatility spikes, or EU Toy Safety Directive chemical migration limit revisions could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Baby Tableware Market
Baby Products
Global Pregnancy Pillow Market
Baby Products
Smart Bottle Warmers Market
Baby Products
Mexico Baby Care Products Market
Baby Products
AI Smart Baby Monitors Market
Baby Products
Breastfeeding Accessories Market
Baby Products
Smart Crib Market
Baby Products
Diaper Pails Market
Baby Products
Global Baby Mattresses Market
Baby Products
Baby Powder Market
Baby Products
Baby Changing Light Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Puppy Teething Toys Market
Baby Products
Baby Nipple/Teat Market
Baby Products
Home Care Packaging Market