
 Aviation Compliance Monitoring Software Market | 2026-2036
Aviation Compliance Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Compliance Monitoring Software Market Outlook
Cloud-native architecture is tilting development priorities across aviation compliance platforms as operators abandon legacy on-premises installations. MetricStream leverages extensive GRC module libraries to anchor enterprise airline accounts. Drata competes through continuous control monitoring that reduces manual audit preparation. Osprey Flight Solutions specializes in geopolitical risk overlays that differentiate its offering for international flight operations.
Aviation compliance monitoring software encompasses digital platforms that track regulatory adherence across flight operations, maintenance, safety management, and audit workflows through automated data capture, exception flagging, and documentation retention with configurable alert thresholds. Cloud-based deployments capture expanding share as carriers prioritize remote accessibility and reduced IT overhead, while safety management modules lead feature adoption due to ICAO Annex 19 mandates. Maintenance tracking segments show concentrated margin pools among specialized MRO-integrated vendors.
FAA Part 121 and Part 135 regulations, EASA implementing rules, and ICAO safety management standards collectively shape product requirements by mandating documented hazard identification and corrective action tracking. EASA's management system requirements and FAA voluntary disclosure programs create divergent compliance templates that vendors must accommodate. Stakeholders should evaluate platform adaptability to emerging sustainability reporting obligations and cross-border data residency constraints before committing to long-term contracts.
Market Dynamics
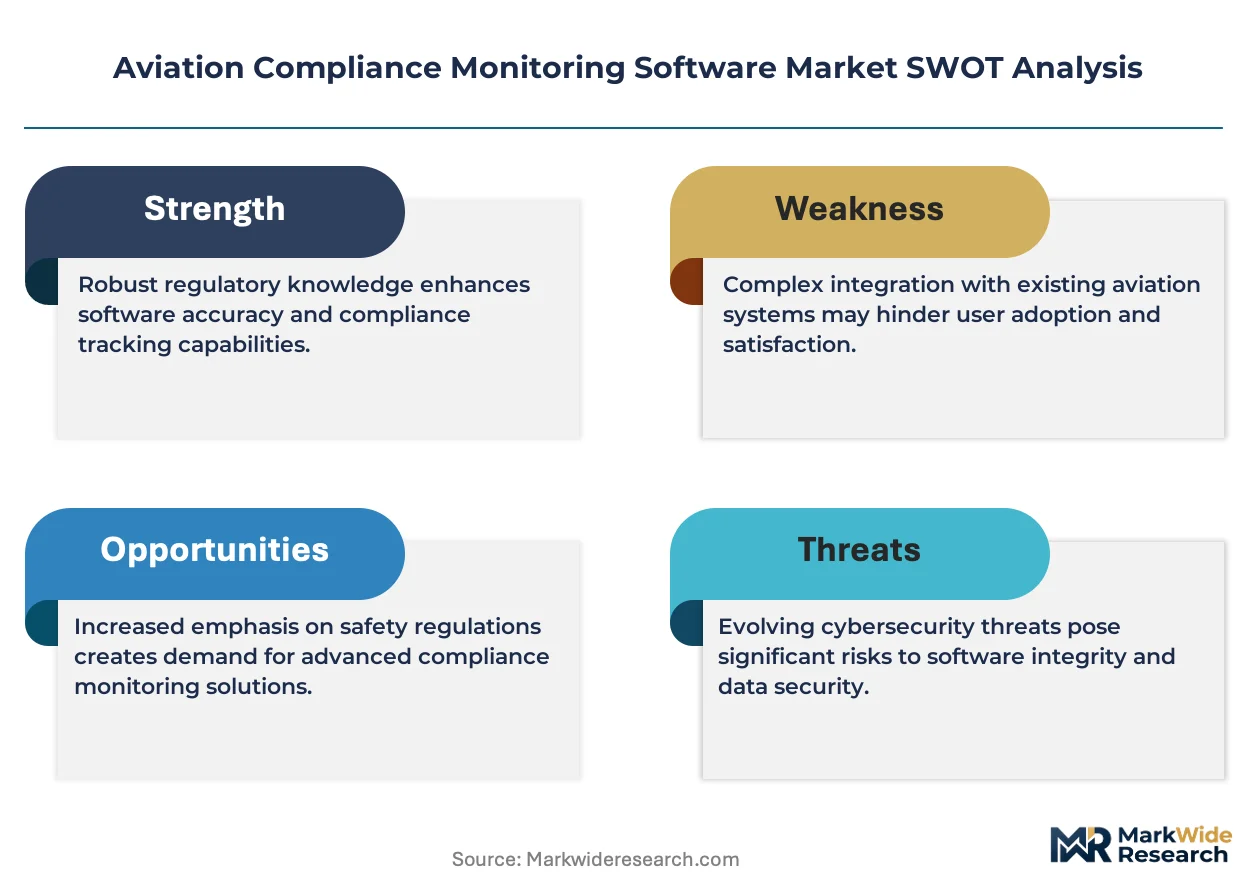
Cloud-native architecture is displacing legacy on-premises installations across aviation compliance platforms as carriers prioritize remote accessibility and reduced IT overhead. FAA Part 135 operators face intensified safety management system obligations that demand automated audit trails and real-time exception flagging.
Growth Catalysts
- ICAO Annex 19 mandates:Safety management system requirements drive carrier investment in digital hazard identification and corrective action tracking modules.
- EASA implementing rules:Management system obligations for European operators create standardized demand for integrated compliance documentation platforms.
- Geopolitical risk overlays:International flight operations require real-time threat intelligence integration that specialized vendors now embed within compliance suites.
Market Restraints
- Data residency constraints:Cross-border flight operations face fragmentation as Brazil's ANVISA, Saudi Arabia's SFDA, and UAE's MOHAP impose divergent data localization requirements.
- Aviation-grade certification timelines:FAA software approval processes for safety-critical systems extend implementation cycles beyond typical enterprise SaaS deployment windows.
- Specialized MRO vendor concentration:Maintenance tracking segments show margin capture by narrow vertical specialists with deep airline system integrations.
Strategic Opportunities
- Sustainability reporting convergence:EU CSRD disclosure requirements and ICAO CORSIA carbon accounting create demand for emissions tracking modules within compliance platforms.
- API-first architectures:Open integration standards enable modular procurement where carriers assemble best-of-breed components rather than monolithic suites.
- India's DGCA modernization:Regulatory digitization across Indian aviation authorities creates greenfield demand absent legacy system entrenchment.
Industry Challenges
- Aviation cybersecurity expertise scarcity:FAA AC 119-1 guidance on information security demands specialized talent pools that carriers and vendors struggle to staff.
- Legacy system integration friction:Decades-old maintenance databases and proprietary flight operations systems resist seamless API connectivity with modern cloud platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Compliance Monitoring Software Market |
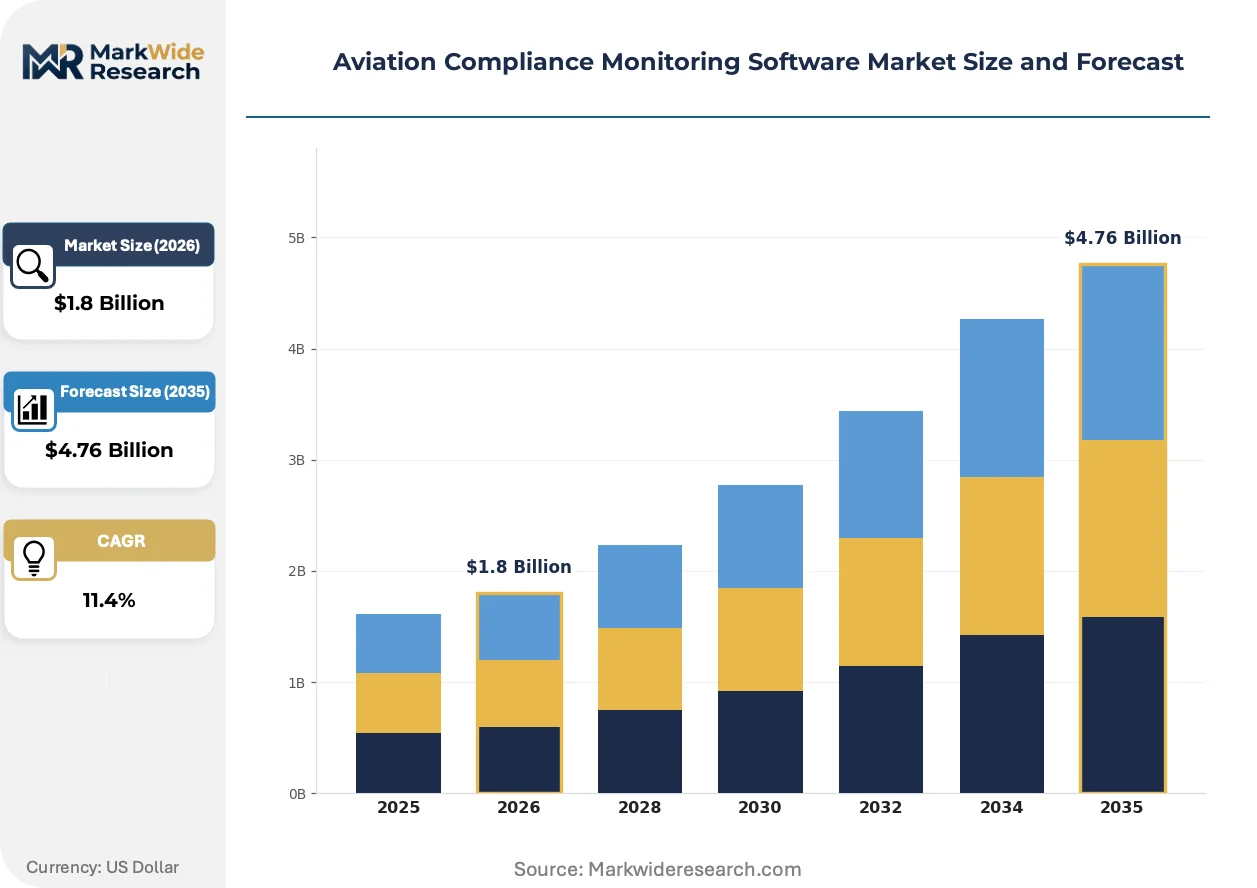
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Operations, Maintenance Tracking, Safety Management, Audit Management End User: Airlines, Regulatory Bodies, Aviation Consultants, Training Organizations Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Feature: Real-Time Reporting, Data Analytics, Custom Alerts, Document Management |
| Companies Covered | MetricStream, Osprey Flight Solutions, Vanta, AuditBoard, SAFVR, Drata, Secureframe, SMS Pro, LogicGate Risk Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Compliance Monitoring Software Market Strategic Shifts
Digital twin architectures are compressing compliance verification cycles from months to days. Artificial intelligence is embedding exception detection directly into operational data streams. Sustainability disclosure mandates are forcing convergence between environmental reporting and traditional safety compliance workflows.
Continuous control monitoring technology is virtualizing audit preparation workflows that previously required manual documentation assembly. Part 135 operators and regional carriers are adopting these platforms fastest, drawn by reduced inspector preparation hours. The technology is virtualizing the traditional three-year audit cycle into always-on compliance posture assessment.
EASA's management system requirements and FAA voluntary disclosure programs are diverging compliance templates that vendors must accommodate simultaneously. Product roadmap prioritization splits between European integrated management system approaches and US voluntary self-disclosure frameworks. Maintenance tracking modules face the most complex dual-certification demands as they touch both jurisdictions' airworthiness standards.
Carrier procurement teams are unbundling after-sales service contracts from software licensing, demanding transparent API documentation and self-service configuration. Traditional vendor-implemented deployment models are losing share to platform-as-a-service offerings with embedded training resources. This pattern concentrates in United States Part 121 operators with mature procurement functions and dedicated aviation IT staff.
Aviation Compliance Monitoring Software Market Segmentation
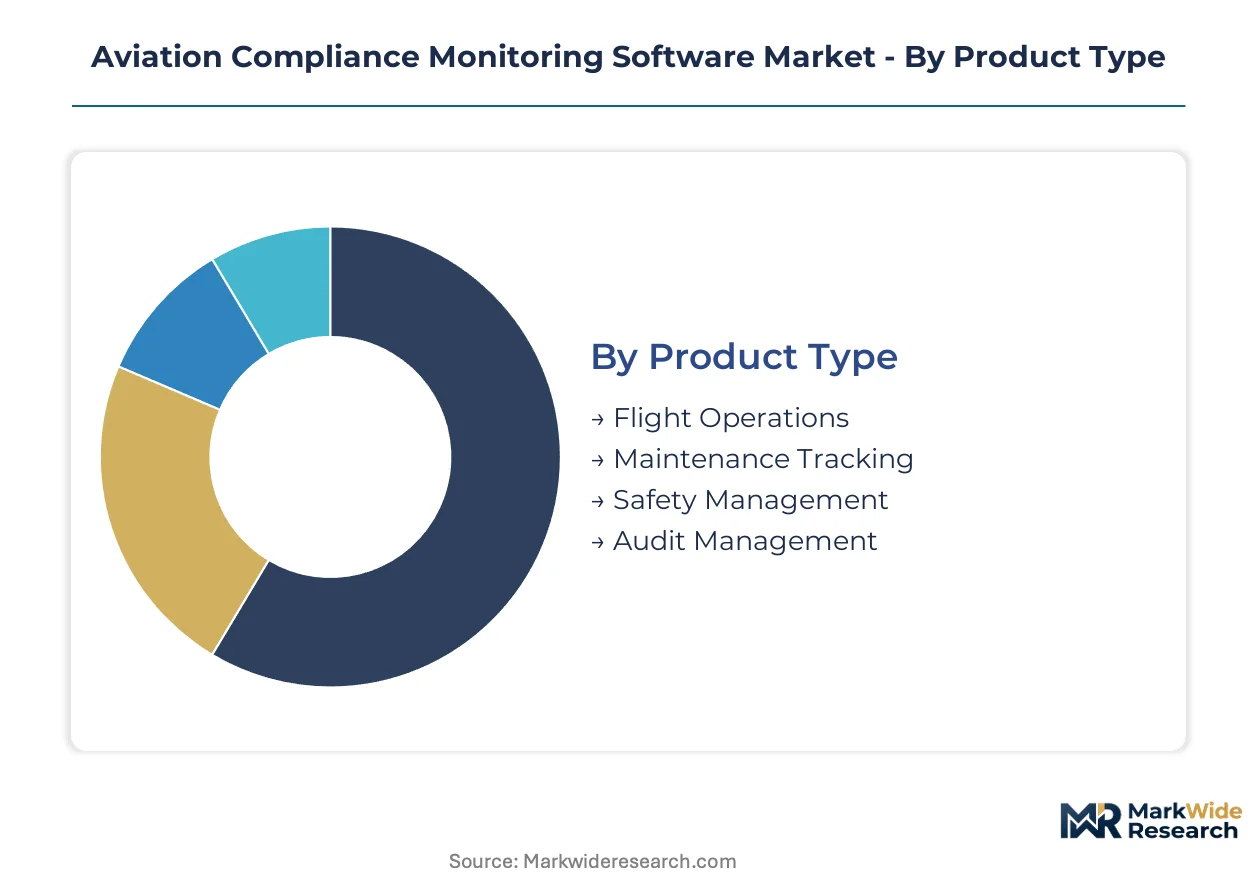
Segmentation in aviation compliance software reflects divergent procurement priorities across operator maturity levels. Carriers with established safety management systems demand deep integration, while emerging market entrants prioritize rapid deployment over customization depth.
Product Type:
Mature segments dominate installed base volumes, though emerging categories show steepest adoption curves among digital-native operators.
- Flight Operations:Modules track crew scheduling, flight duty limitations, and route compliance against ICAO Annex 6 standards. Major US Part 121 carriers anchor demand here as fatigue risk management systems become mandatory.
- Safety Management:Platforms embed hazard reporting, risk assessment matrices, and corrective action tracking per ICAO Annex 19. EASA-registered operators in Germany and France drive replacement cycles as management system requirements tighten.
- Maintenance Tracking:Systems interface with MRO databases to flag airworthiness directive deadlines and component life limits.
- Audit Management:Tools automate documentation assembly for regulatory inspections and internal quality reviews.
Safety Management handles the majority of throughput; Flight Operations is expanding most quickly on share as fatigue science advances.
End User:
Customer type determines pricing tolerance and implementation complexity, with direct operators commanding premium feature sets.
- Airlines:Full-service and low-cost carriers deploy integrated suites spanning flight, maintenance, and safety domains. US Part 135 operators with intensified SMS obligations represent the fastest-climbing adoption segment.
- Regulatory Bodies:Civil aviation authorities utilize oversight platforms for operator surveillance and certificate management. EASA and FAA inspection teams drive standardization requirements that cascade to vendor roadmaps.
- Aviation Consultants:Third-party advisory firms license multi-tenant tools for client audit preparation and gap analysis.
- Training Organizations:Approved training entities track instructor qualifications and student progress against competency frameworks.
Airlines absorb the dominant procurement volume; Regulatory Bodies are gaining share fastest as authorities digitize oversight functions.
Deployment:
Architecture choices concentrate around remote accessibility needs and data sovereignty constraints.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance and enable mobile access for distributed flight crews. European operators prioritize EU-hosted instances to satisfy GDPR and emerging data residency mandates.
- SaaS:Subscription models with embedded updates reduce capital expenditure and accelerate feature delivery. Regional carriers in India and Southeast Asia favor this route given limited in-house IT infrastructure.
- Hybrid:Configurations split sensitive operational data on-premises with analytics workloads in cloud environments.
- On-Premises:Legacy installations persist among defense contractors and operators in jurisdictions with strict data localization rules.
Cloud-Based deployments command the largest current footprint; SaaS is climbing fastest as procurement teams unbundle implementation from licensing.
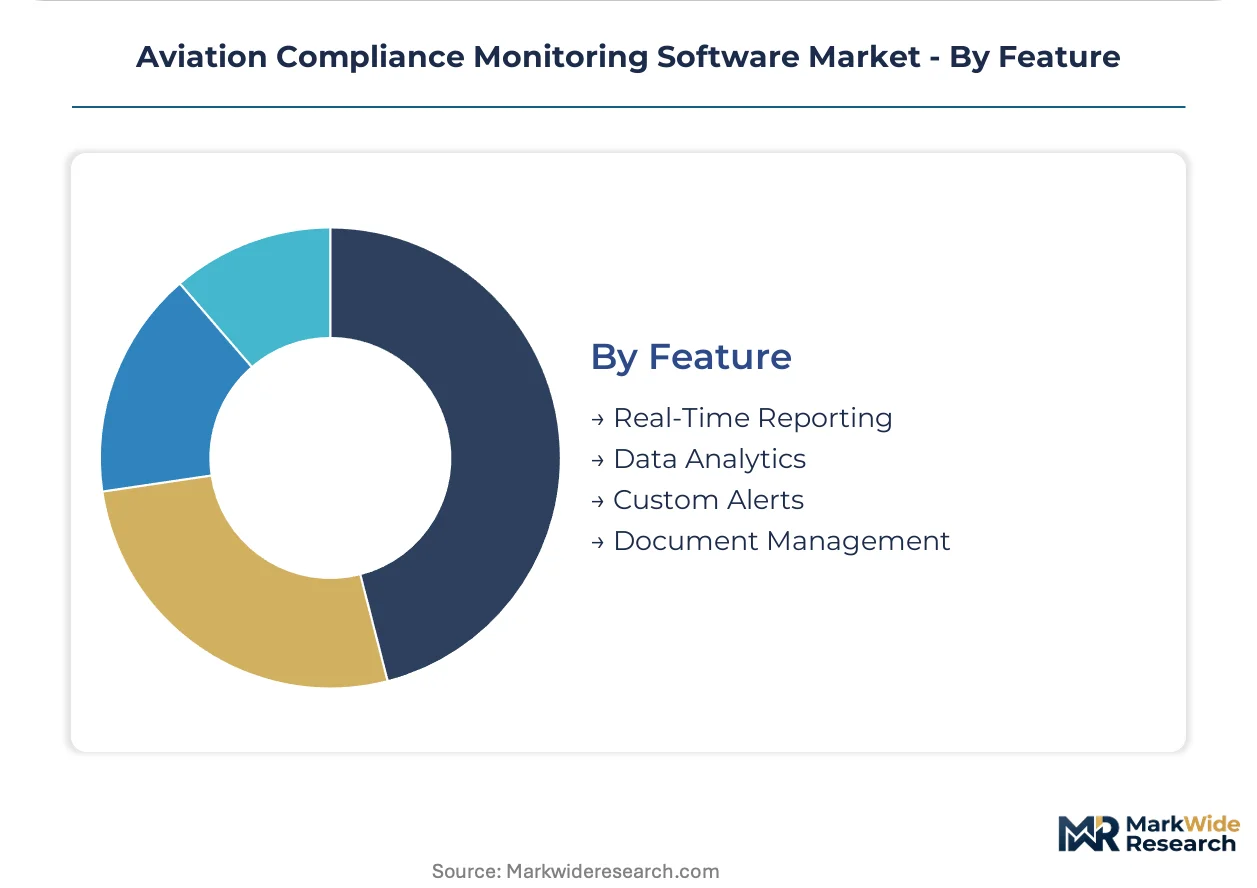
Feature:
Capability depth separates enterprise-grade platforms from point solutions.
- Real-Time Reporting:Dashboards surface compliance exceptions as they occur rather than through periodic batch reviews. Part 135 operators facing unannounced inspections value instantaneous posture visibility.
- Data Analytics:Predictive models identify leading indicators of regulatory drift before formal non-compliance occurs.
- Custom Alerts:Configurable thresholds notify responsible parties when parameters exceed defined risk tolerances.
- Document Management:Repositories maintain version-controlled records with audit trails for regulatory evidence.
Real-Time Reporting anchors the feature investment hierarchy; Data Analytics is gaining traction fastest as AI embeds into operational data streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based compliance software vendors export subscription services to European and Asia-Pacific carriers seeking FAA-aligned safety management frameworks. Cross-border data flows concentrate through cloud-hosted instances in Frankfurt, Singapore, and Sydney to satisfy local residency requirements.
United States
FAA Part 135 operators drive procurement volume as intensified SMS obligations mandate automated audit trails. The FAA's voluntary disclosure programs create compliance templates that vendors adapt for self-reporting workflows. Dallas-Fort Worth and Atlanta anchor the densest operator clusters, where regional carriers deploy cloud-native platforms for distributed fleet management.
Germany
EASA-registered operators in Bavaria and North Rhine-Westphalia replace legacy systems as management system requirements tighten. EASA implementing rules standardize integrated compliance documentation demands across European air carriers. Frankfurt's aviation finance hub concentrates advisory firms licensing multi-tenant tools for client gap analysis.
United Kingdom
Post-Brexit regulatory divergence forces dual-track compliance investments from UK-registered carriers serving EU routes. The Civil Aviation Authority's digitization roadmap shapes vendor feature priorities for oversight platform integration. London's Heathrow corridor hosts consultancy practices embedding geopolitical risk overlays into client compliance suites.
India
DGCA modernization initiatives create greenfield demand absent legacy system entrenchment across domestic carriers. Regulatory digitization mandates documented hazard identification for scheduled operators expanding international networks. Bangalore and Hyderabad's IT corridors attract SaaS vendors establishing EU-hosted instances for GDPR-compliant service delivery.
United Arab Emirates
Dubai-based long-haul carriers invest in real-time reporting modules to satisfy unannounced inspection protocols from multiple regulatory jurisdictions. MOHAP data localization requirements split sensitive operational data from analytics workloads in hybrid architectures. Abu Dhabi's sovereign aviation funds channel investment toward API-first platforms enabling modular procurement strategies.
Aviation Compliance Monitoring Software Market Competitive Environment
Channel-controlling players compete with product-specialist players across deployment and feature dimensions. Enterprise GRC incumbents anchor airline accounts through extensive module libraries, while continuous monitoring specialists capture regional carrier segments with reduced implementation friction. Two strategic archetypes dominate: horizontal governance platforms extending into aviation verticals, and purpose-built flight operations specialists with deep regulatory domain expertise. Competitive moves concentrate on API-first architecture development and sustainability reporting module expansion.
Within the enterprise platform tier, MetricStream and Drata occupy positions representing divergent technical approaches to compliance automation. MetricStream exemplifies the governance-centric archetype leveraging cross-industry GRC foundations for aviation module extension. Drata anchors the continuous-control segment with real-time monitoring architectures that compress audit preparation cycles. Osprey Flight Solutions sits within the specialized vertical tier, representing the geopolitical risk overlay archetype for international flight operations.
| Leading Market Players |
|---|
| MetricStream |
| Osprey Flight Solutions |
| Vanta |
| AuditBoard |
| SAFVR |
| Drata |
| Secureframe |
| SMS Pro |
| LogicGate Risk Cloud |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure concentration in the United States, Germany, and Singapore anchors margin capture at the platform layer, where SaaS vendors extract recurring revenue while hardware and connectivity costs commoditize downstream. Compliance software pricing power rests on regulatory certification depth rather than raw compute resources.
Pricing Analysis
Legacy on-premises installations command 40-60% premium over cloud-native equivalents due to customization requirements and perpetual licensing models. Pricing stratifies across enterprise, mid-market, and regional carrier tiers, with FAA Part 121 operators showing lowest price sensitivity given audit failure costs. Cost compression in the mid-market segment is intensifying because API-first architectures enable modular procurement that bypasses monolithic suite premiums. Regional carriers and Part 135 operators represent the most price-sensitive buyer segment, prioritizing rapid deployment over feature depth.
Supply Chain Analysis
Upstream cloud infrastructure feeds from hyperscaler data centers concentrated in the United States, Ireland, and Singapore, with EU-hosted instances commanding 15-25% cost premium for GDPR compliance. Critical inputs include aviation-grade encryption modules, real-time data streaming architectures, and regulatory content libraries maintained by EASA and FAA. Single-source vulnerability concentrates in specialized MRO system integrations where decades-old proprietary databases resist API connectivity. Distribution runs through direct enterprise sales for major carriers and channel partners for regional operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation compliance software is crossing into platform economics where API ecosystems and modular interoperability determine competitive survival. The shift from monolithic suites to composable architectures rewards vendors who embed into broader operational technology stacks.
For Market Incumbents: Build switching-cost moats through deep MRO system integrations that capture maintenance workflow data. Incumbents should anchor enterprise airline accounts with embedded training resources and self-service configuration tools that reduce customer churn. The threat of continuous-control specialists like Drata compressing audit preparation cycles demands investment in real-time monitoring parity. Vertical integration into regulatory content maintenance—direct EASA and FAA rule-feed partnerships—creates data advantages that modular competitors cannot replicate.
For New Entrants and Emerging Players: Establish a beachhead in India's DGCA modernization wave, where greenfield demand lacks legacy system entrenchment and procurement teams prioritize rapid SaaS deployment. New entrants should target sustainability reporting modules as the most penetrable feature category, where EU CSRD and ICAO CORSIA obligations outpace incumbent roadmap prioritization. A compliance-as-a-service angle—embedding carbon accounting directly into flight operations data streams—sidesteps direct competition with established safety management platforms.
For Investors and Strategic Acquirers: Capital is best deployed toward API-first platforms with demonstrated interoperability across MRO, flight operations, and safety management domains. Long-term viability over the next decade hinges on regulatory certification breadth spanning FAA, EASA, and emerging authority digitization programs. The acquisition target archetype combines vertical aviation expertise with horizontal GRC scalability. Watch for inflection when major carriers unbundle after-sales service contracts from software licensing, signaling procurement maturity that favors platform economics over professional services dependency.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Development | Enables modular procurement where carriers assemble best-of-breed components rather than monolithic suites. |
| Sustainability Reporting Module Expansion | Captures EU CSRD and ICAO CORSIA compliance demand as environmental disclosure converges with safety workflows. |
| MRO System Integration Deepening | Locks in maintenance tracking segments where specialized vendors capture concentrated margin pools. |
| Regulatory Content Partnership | Secures direct EASA and FAA rule-feed access that accelerates compliance update delivery versus manual interpretation. |
| Geographic Expansion to India | Exploits DGCA digitization mandates creating greenfield demand absent legacy system entrenchment. |
Study Parameters
A spread of perspectives from airline safety directors, FAA compliance officers, EASA audit specialists, and cloud platform engineers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through FAA guidance material, EASA implementing rules, ICAO Annex documentation, and vendor SEC disclosures. Bottom-up triangulation across operator deployment data and top-down regulatory mandate analysis anchored market sizing.
Demand-supply balance framing shaped the analytical approach across the projection horizon. Segmentation dimensions modeled include deployment architecture, operator size tier, regulatory jurisdiction cluster, and integration complexity level. CAGRs derived from fitted growth curves against historical adoption patterns and regulatory deadline schedules. Forecast inputs incorporated SMS mandate rollout timelines and cloud infrastructure expansion trajectories.
Sensitivities concentrate around ICAO regulatory timeline acceleration and cross-border data residency fragmentation. Forecasts reflect documented assumptions on technology substitution rates and carrier procurement cycle timing. Material shifts in FAA software certification processes or EASA management system requirement scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
Compliance and Traceability Solutions Market
Regulatory Compliance Technology
General Data Protection Regulation (GDPR) Market
Regulatory Compliance Technology
Anti-Money Laundering Systems Market
Regulatory Compliance Technology
Management System Certification Market
Regulatory Compliance Technology
Cross-Border Customs and Trade Compliance Orchestration Platforms Market
Regulatory Compliance Technology
Global Anti- Money Laundering Solutions Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
Regtech Software Market
Regulatory Compliance Technology
Global GDPR Services Market
Regulatory Compliance Technology
Global Regulatory Technology (Regtech) Market
Regulatory Compliance Technology
Global AML Software Market
Regulatory Compliance Technology
GDPR Assessment Tools Market
Regulatory Compliance Technology
Compliance Testing Solutions Market
Regulatory Compliance Technology
Regulatory Change Management Software Market
Regulatory Compliance Technology
Regulatory Information Management System Market
Regulatory Compliance Technology
US Anti Money Laundering Solution Market