
 Global AML Software Market | 2026-2036
Global AML Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global AML Software Market Analysis
Subscription-based transaction monitoring is broadening what financial institutions purchase as a recurring capability rather than a perpetual license. Oracle Corporation leverages its cloud infrastructure to anchor large-bank deployments across multiple jurisdictions. SAS Institute Inc. competes through deep analytics specialization in behavioral risk scoring. NICE Actimize sustains its position via real-time payment fraud integration alongside AML workflows.
Anti-money laundering software encompasses transaction monitoring, customer due diligence, and suspicious activity reporting systems that apply rule-based and machine-learning algorithms to detect illicit financial flows. The primary purpose is automating compliance with financial crime regulations while reducing false-positive rates in high-volume payment environments. Cloud-based deployment is outpacing on-premise installations as banks seek elastic compute for real-time screening workloads. Transaction monitoring services capture the largest revenue pool within service-type segmentation, though risk assessment modules are gaining traction among asset managers. Banks remain the dominant customer type, yet online platforms represent the fastest-expanding buyer segment due to digital payment proliferation.
The Financial Action Task Force sets baseline standards that national regulators transpose into binding obligations, directly shaping software feature requirements across jurisdictions. The EU AI Act imposes algorithmic transparency mandates on automated compliance systems deployed within European financial institutions. The US Financial Crimes Enforcement Network and the UK Financial Conduct Authority enforce suspicious activity reporting timelines that drive refresh cycles for legacy platforms. Stakeholders must evaluate how divergent regulatory timetables for AI governance and real-time payment oversight will reshape procurement priorities and vendor certification requirements.
Market Dynamics
Real-time payment proliferation is compressing transaction screening windows from hours to milliseconds, forcing banks to abandon batch-processed legacy systems for continuous monitoring architectures that operate within payment rails.
Growth Catalysts
- EU AI Act transparency mandates:European financial institutions must deploy explainable machine-learning models for automated compliance decisions, creating procurement urgency for algorithmic audit tools.
- Digital payment platform expansion:Online payment processors now face equivalent AML obligations to traditional banks, expanding the addressable customer base beyond incumbent financial institutions.
- Behavioral biometrics integration:Continuous authentication layered with transaction monitoring reduces false positives by correlating device fingerprints with payment patterns.
Market Restraints
- Cloud infrastructure concentration:Three hyperscale providers dominate elastic compute for real-time screening, creating single-point-of-failure risk for multi-jurisdictional deployments.
- Data localization requirements:Cross-border transaction monitoring faces fragmentation as India, China, and Russia mandate domestic data residency for financial surveillance records.
- Legacy system technical debt:Core banking platforms built on COBOL architectures resist API-native integration with modern screening engines, extending implementation timelines.
Strategic Opportunities
- Asset manager risk assessment modules:Investment funds managing private wealth face tightening beneficial ownership disclosure rules, opening specialized workflow demand.
- Regulatory sandbox participation:Singapore's MAS and the UK's FCA permit controlled testing of AI-driven monitoring in live payment environments, accelerating vendor certification.
- Embedded finance convergence:Non-bank platforms integrating lending and payment functions require lightweight compliance APIs that traditional enterprise suites fail to address.
Industry Challenges
- Explainable AI skill scarcity:Financial institutions struggle to hire compliance technologists capable of translating black-box model outputs into regulator-defensible documentation.
- Multi-jurisdictional rule engine maintenance:Banks operating across FATF, EU AI Act, and FinCEN jurisdictions must synchronize divergent alert escalation protocols within single platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AML Software Market |
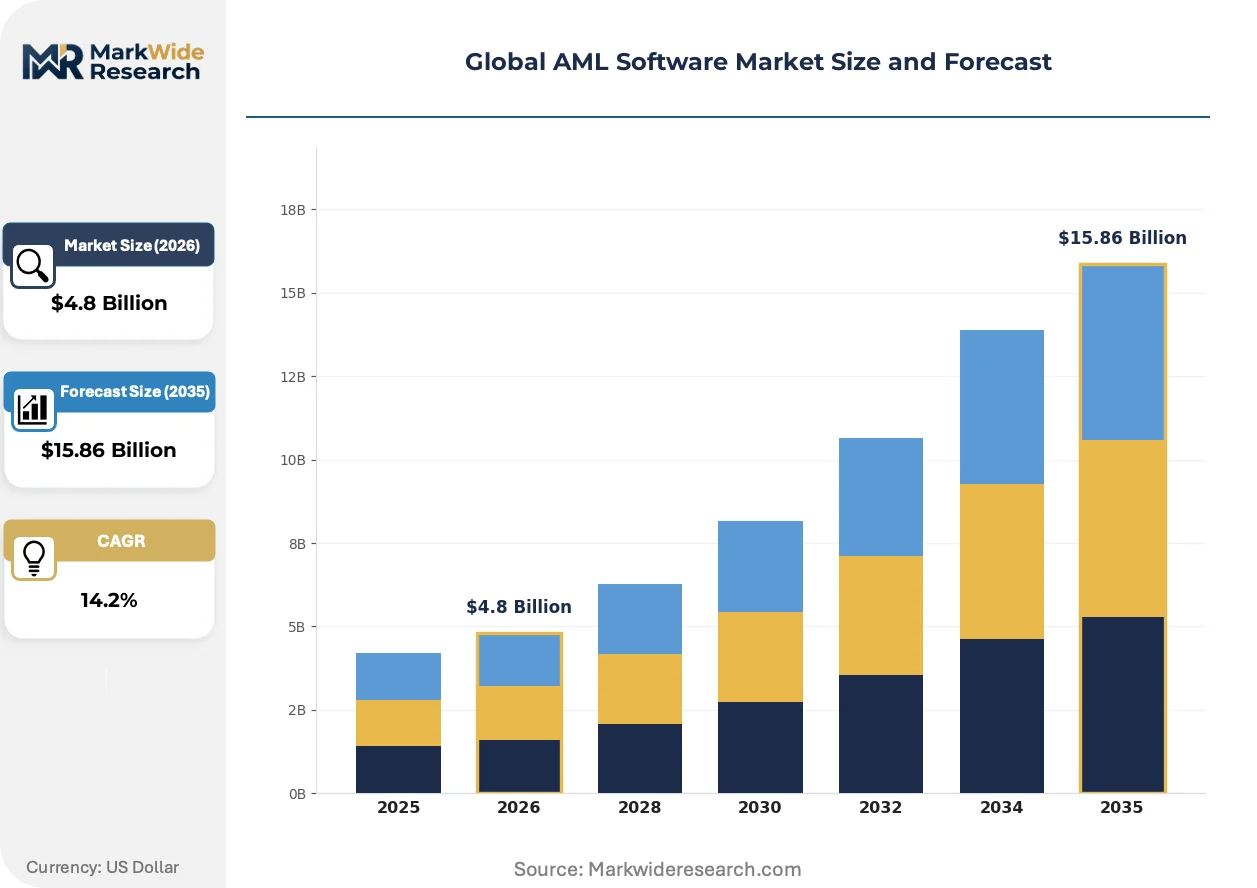
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Customer Type: Banks, Insurance Companies, Asset Management, Online Platforms Service Type: Compliance Management, Transaction Monitoring, Risk Assessment, Case Management End User: Financial Institutions, Government Agencies, Corporations, Regulatory Bodies |
| Companies Covered | Oracle Corporation, SAS Institute Inc., NICE Actimize, FICO, Tata Consultancy Services Limited, ACI Worldwide, LexisNexis Risk Solutions, Cognizant Technology Solutions Corporation, Feedzai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AML Software Market Emerging Trajectories
Federated learning architectures and explainable AI frameworks are redefining how compliance data moves across institutional boundaries. Vendors now compete on model transparency rather than detection accuracy alone.
Graph neural networks for relationship mapping are overtaking rule-based entity resolution in correspondent banking surveillance. Tier-one institutions in London and New York deploy these systems to uncover nested ownership structures across shell entities. The technology is overtaking manual investigator workflows, compressing complex case resolution from weeks to hours.
The EU AI Act's high-risk system classification imposes conformity assessments on automated AML decision engines before deployment. European banks must maintain human oversight interfaces and algorithmic change logs. Asset managers with EU fund domiciles are most affected, renegotiating vendor contracts to include audit rights and model documentation deliverables.
Subscription-based deployment models now dominate procurement conversations for mid-tier banks previously locked out of enterprise-tier capabilities. Per-transaction pricing replaces perpetual licenses, aligning vendor revenue with payment volume growth. This shift is most visible among regional banks in the United States and building societies in the United Kingdom seeking elasticity without capital commitment.
Global AML Software Market Segmentation
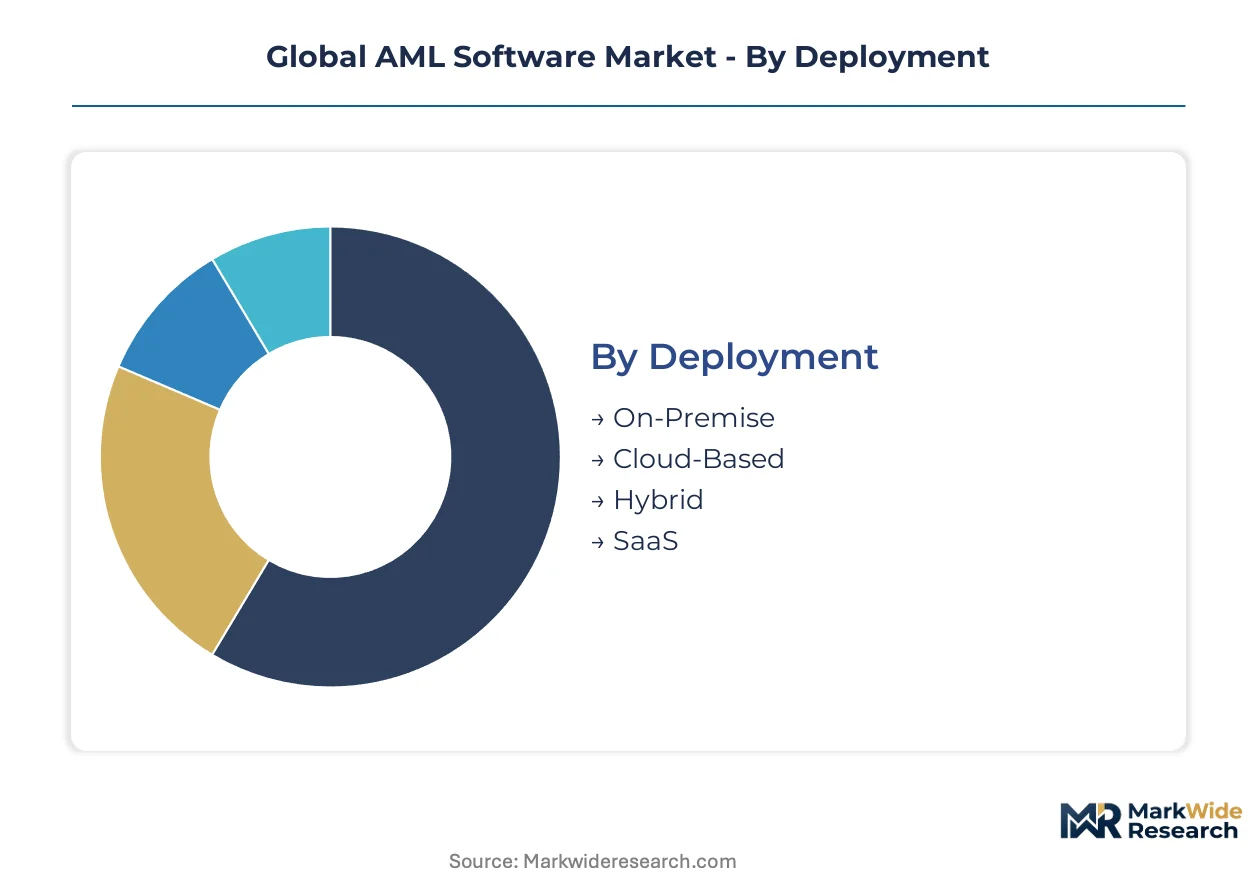
AML software procurement patterns diverge sharply across deployment architectures and institutional risk profiles. Vendors must align pricing models, integration complexity, and regulatory certification to distinct buyer capabilities and compliance maturity levels.
Deployment:
Cost tier separates buyers with capital reserves for infrastructure ownership from those prioritizing operational flexibility.
- Cloud-Based:Elastic compute architectures enable real-time screening across payment rails without fixed hardware commitments. Tier-one banks in Singapore and the United States favor multi-tenant configurations for cross-border transaction monitoring, driven by compressed implementation timelines and reduced internal IT burden.
- SaaS:Per-transaction pricing aligns vendor revenue with payment volume fluctuations, attracting mid-tier institutions seeking enterprise-tier capabilities without perpetual license outlays. Building societies in the United Kingdom and regional banks across the United States gravitate toward this model for regulatory sandbox participation.
- On-Premise:Domestic data residency mandates in India, China, and Russia compel sovereign infrastructure deployment for surveillance record retention.
- Hybrid:Segregated architectures isolate core transaction data on-premise while leveraging cloud analytics for model training workloads.
Cloud-Based deployments lead volumes today; SaaS is gaining share fastest.
Customer Type:
Application complexity varies with regulatory scrutiny intensity and transaction velocity.
- Banks:Correspondent banking relationships demand nested ownership resolution across shell entities, compressing case resolution from weeks to hours through graph neural network deployment. London and New York institutions drive feature requirements for continuous monitoring architectures.
- Online Platforms:Digital payment processors face equivalent AML obligations to traditional banks with thinner compliance infrastructure, expanding addressable demand beyond incumbent financial institutions. Singapore's MAS and the UK's FCA regulatory sandboxes accelerate vendor certification for this segment.
- Insurance Companies:Policy premium laundering risks necessitate specialized behavioral scoring for high-value contract transactions.
- Asset Management:Beneficial ownership disclosure tightening for private wealth funds opens specialized workflow demand across EU fund domiciles.
Banks dominate procurement value; Online Platforms show the steepest expansion trajectory.
Service Type:
Volume concentration tracks regulatory enforcement priority and false-positive reduction imperatives.
- Transaction Monitoring:Real-time payment proliferation compresses screening windows from hours to milliseconds, forcing abandonment of batch-processed legacy systems. The EU AI Act's explainability mandates reshape algorithmic audit tool procurement for automated compliance decisions.
- Risk Assessment:Investment funds managing private wealth face tightening beneficial ownership rules, opening specialized module demand. Asset managers renegotiate vendor contracts to include audit rights and model documentation deliverables under European conformity assessment requirements.
- Compliance Management:Multi-jurisdictional rule engine maintenance synchronizes divergent alert escalation protocols across FATF, EU AI Act, and FinCEN jurisdictions.
- Case Management:Investigator workflow compression from graph neural network outputs reduces manual resolution timelines for correspondent banking surveillance.
Transaction Monitoring anchors revenue pools; Risk Assessment modules are climbing the fastest.
End User:
Maturity gradients separate institutions with embedded compliance functions from external oversight bodies.
- Financial Institutions:Internal audit functions demand human oversight interfaces and algorithmic change logs under EU AI Act high-risk system classifications. European banks maintain conformity assessments before automated decision engine deployment.
- Regulatory Bodies:Supervisory technology adoption accelerates as the US Financial Crimes Enforcement Network and UK Financial Conduct Authority enforce suspicious activity reporting timelines that drive refresh cycles for legacy platforms.
- Government Agencies:Financial intelligence units require cross-border data sharing protocols that conflict with emerging data localization mandates.
- Corporations:Non-financial entities with payment integration face emerging compliance obligations under expanded beneficial ownership registries.
Financial Institutions absorb the majority of vendor capacity; Regulatory Bodies are expanding procurement most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys more automated transaction monitoring capacity than any single European market, yet Singapore's regulatory sandbox programs accelerate vendor certification cycles faster than Western counterparts.
United States
Large-bank consolidation and real-time payment network expansion drive procurement urgency. FinCEN enforces suspicious activity reporting timelines that compress legacy platform refresh cycles. New York and Chicago financial centers anchor correspondent banking surveillance deployments.
United Kingdom
Building societies and challenger banks accelerate cloud migration for elastic compliance workloads. The FCA permits controlled AI-driven monitoring testing in live payment environments through its regulatory sandbox. London's fintech cluster concentrates graph neural network adoption for nested ownership resolution.
Singapore
Cross-border payment hub status attracts regional headquarters for AML software vendors seeking Asia-Pacific market entry. MAS sandbox frameworks enable live-environment testing of explainable AI compliance engines. The financial district hosts multi-tenant cloud configurations serving Southeast Asian banking networks.
Germany
Savings bank associations and cooperative banking groups seek SaaS alternatives to legacy on-premise installations. The EU AI Act imposes conformity assessments on automated decision engines before deployment. Frankfurt's banking quarter drives demand for algorithmic audit tools and human oversight interfaces.
India
Domestic data residency mandates compel sovereign infrastructure deployment for surveillance record retention. The central bank tightens beneficial ownership disclosure requirements for private wealth funds. Mumbai and Bangalore financial technology corridors expand regional vendor delivery capabilities.
Global AML Software Market Vendor Landscape
Top-tier vendors anchor enterprise banking deployments, while mid-tier specialists compete on per-transaction pricing and rapid implementation timelines. The vendor base organizes around three strategic archetypes: cloud infrastructure providers leveraging elastic compute scale, analytics specialists emphasizing behavioral risk scoring, and fraud-AML convergence players integrating real-time payment screening. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and portfolio diversification into embedded finance compliance APIs.
Within the analytics-specialist tier, SAS Institute Inc. and FICO exemplify deep quantitative modeling heritage applied to behavioral risk scoring. Oracle Corporation anchors the cloud-infrastructure archetype through multi-jurisdictional banking deployments. NICE Actimize occupies a position at the fraud-AML convergence point, representing real-time payment integration capabilities.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAS Institute Inc. |
| NICE Actimize |
| FICO |
| Tata Consultancy Services Limited |
| ACI Worldwide |
| LexisNexis Risk Solutions |
| Cognizant Technology Solutions Corporation |
| Feedzai |
| Others |
Supply Flow & Price Mechanics
Compliance technologist concentration in Bangalore and Singapore generates labor-cost differentials that widen pricing-tier spreads between explainable AI engineering boutiques and legacy platform vendors. European conformity assessment requirements for EU AI Act high-risk systems further stratify vendor positioning, as algorithmic audit capabilities command premium positioning against standard transaction monitoring deployments.
Pricing Analysis
Capacity additions in cloud infrastructure regions are reshaping price floors for real-time screening workloads, compressing margins for on-premise legacy vendors. Three-tier pricing structure across premium, standard, and economy levels segments by deployment complexity and regulatory certification depth. Pricing pressure stems from per-transaction SaaS models displacing perpetual licenses among mid-tier banks. Regional banks in the United States exhibit highest price sensitivity; tier-one correspondent banks in London and New York prioritize explainability certification over cost.
Supply Chain Analysis
Freight costs for specialized GPU hardware from Taiwan and South Korea amplify total cost of ownership for real-time model training workloads. Software development draws from India, Ireland, and Poland for compliance engineering talent. Dependencies center on NVIDIA tensor core architectures, cloud hyperscale compute, and open-source machine learning frameworks. Single-source vulnerability concentrates in CUDA-dependent optimization layers. Distribution runs through direct enterprise sales for tier-one banks and channel partners for mid-market SaaS penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global AML Software Market compounds steadily as regulatory enforcement intensifies across FATF jurisdictions, embedding compliance spending into institutional operating budgets regardless of credit cycles.
For Market Incumbents: Anchor multi-jurisdictional deployments through pre-certified algorithmic audit toolchains that satisfy EU AI Act conformity assessments ahead of competitor refresh cycles. Deepen vertical integration into behavioral biometrics layers to differentiate against pure-play transaction monitoring vendors. Defend against cloud-native challengers by embedding compliance APIs into embedded finance platforms before non-bank payment processors consolidate vendor relationships. For New Entrants and Emerging Players: Launch via lightweight SaaS APIs targeting building societies and regional banks in the United Kingdom and United States previously locked out of enterprise-tier capabilities. White-space concentration sits in asset manager risk assessment modules for EU fund domiciles facing beneficial ownership disclosure tightening. Penetrate through regulatory sandbox participation with Singapore's MAS and the UK's FCA to accelerate certification velocity against established vendor procurement timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier analytics specialists with explainable AI frameworks but limited geographic footprint. Long-term viability favors vendors with federated learning architectures that navigate data localization mandates in India and China. Acquisition target archetype: behavioral biometrics providers with device fingerprinting IP applicable to false-positive reduction. Watch FinCEN enforcement timelines as inflection indicator for legacy platform refresh urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding compliance APIs into embedded finance platforms captures non-bank payment processor demand. |
| Regulatory Sandbox Participation | Controlled testing with Singapore's MAS accelerates vendor certification cycles for explainable AI engines. |
| Acquisition of Specialist Firm | Behavioral biometrics providers add device fingerprinting capabilities that reduce false-positive rates. |
| Geographic Expansion | Multi-tenant cloud configurations in Singapore serve Southeast Asian cross-border banking networks. |
| Strategic Partnership | Hyperscale cloud alliances provide elastic compute for real-time screening without infrastructure ownership. |
Methodological Framework
Multiple input streams — primary interviews with compliance technology officers, regulatory affairs leads at financial institutions, and integration specialists at cloud hyperscalers — were reconciled against secondary validation from SEC filings, FATF mutual evaluation reports, and EU AI Act implementation guidance. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against aggregate banking IT spending estimates anchored volume projections. Primary fieldwork concentrated on tier-one banks in London, New York, and Singapore, mid-tier regional institutions across the United States, and asset managers with EU fund domiciles.
Data-stream reconciliation applied segmentation modeling across deployment architecture, customer type, service module, and end-user maturity gradients throughout the forecast period. CAGRs were derived from elasticity-adjusted adoption curves for real-time payment screening and regulatory mandate implementation timelines. Industry-specific inputs included FinCEN suspicious activity reporting enforcement patterns, EU AI Act conformity assessment rollout schedules, and MAS sandbox certification velocity.
Several conditions sit outside the modeled scope, including geopolitical disruptions to cloud infrastructure availability, abrupt shifts in data localization mandates beyond India and Russia, and fundamental changes to FATF recommendation timelines. Forecasts reflect assumptions about regulatory enforcement continuity and technology adoption elasticity. Stakeholders should weight assumptions against their own operating context and jurisdictional exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
US Anti Money Laundering Solution Market
Regulatory Compliance Technology
Global Anti- Money Laundering Solutions Market
Regulatory Compliance Technology
Anti-Money Laundering Systems Market
Regulatory Compliance Technology
Compliance and Traceability Solutions Market
Regulatory Compliance Technology
General Data Protection Regulation (GDPR) Market
Regulatory Compliance Technology
Global GDPR Services Market
Regulatory Compliance Technology
Regulatory Reporting Solutions Market
Regulatory Compliance Technology
Cross-Border Customs and Trade Compliance Orchestration Platforms Market
Regulatory Compliance Technology
Global Regulatory Technology (Regtech) Market
Regulatory Compliance Technology
Aviation Compliance Monitoring Software Market
Regulatory Compliance Technology
Regulatory Information Management System Market
Regulatory Compliance Technology
Nordic Regulatory Affairs Market
Regulatory Compliance Technology
United States Sales Tax Compliance Software Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
GDPR Assessment Tools Market
Regulatory Compliance Technology
Compliance Testing Solutions Market