
 General Data Protection Regulation (GDPR) Market | 2026-2036
General Data Protection Regulation (GDPR) Market Size, Share, and Industry Trends Forecast 2026-2036
General Data Protection Regulation (GDPR) Market Foresight
Europe's certified data protection officer pool is bifurcating between scarce senior practitioners and abundant entry-level talent, constraining enterprise implementation timelines. IBM Corporation leverages its consulting arm to embed GDPR modules within broader hybrid cloud deployments. Microsoft Corporation anchors its compliance stack inside Microsoft 365 governance tools, competing directly with specialized vendors. Deloitte sustains premium positioning through integrated audit and legal advisory services bundled with technical implementation.
The General Data Protection Regulation (GDPR) constitutes a legally binding data governance framework enacted by the European Union, mandating technical and organizational measures for personal data processing, storage portability, and breach notification within 72 hours. Its primary commercial purpose is to establish uniform data protection standards across member states while imposing penalties up to four percent of global annual turnover for non-compliance. Cloud-based deployment modes are capturing accelerated enterprise migration budgets as organizations retire legacy on-premises data classification systems. Data privacy management solutions dominate current revenue pools, though consent management tools are expanding fastest among ad-tech and media publishers responding to IAB Europe transparency framework mandates.
The European Data Protection Board coordinates enforcement consistency across national supervisory authorities including CNIL in France and ICO in the United Kingdom, directly shaping vendor product roadmaps through binding decision precedents. EDPB guidelines on international data transfers have forced providers to engineer supplementary contractual clauses and encryption standards into core offerings. Stakeholders must monitor emerging adequacy decisions and sector-specific codes of conduct that will determine which solution architectures achieve defensible compliance positions.
Market Dynamics
The EU AI Act's risk classification system is forcing enterprise buyers to re-architect data governance stacks, compressing vendor evaluation cycles and privileging platforms with pre-certified algorithmic auditing capabilities.
Growth Catalysts
- Cross-Border Enforcement Harmonization:The European Data Protection Board's binding decisions on international data transfers are compelling multinational enterprises to consolidate privacy management onto unified cloud platforms.
- Ad-Tech Consent Mandates:IAB Europe's Transparency and Consent Framework v2.2 is driving media publishers and programmatic advertisers to deploy specialized consent management tools with granular purpose specifications.
- France and Germany:Financial services regulators in these jurisdictions are intensifying supervisory scrutiny of data retention policies, accelerating procurement of automated data classification and retention scheduling modules.
Market Restraints
- Certified Personnel Scarcity:The bifurcation between entry-level data protection officers and experienced senior practitioners is extending implementation timelines for complex multi-jurisdictional deployments.
- Legacy System Integration Costs:On-premises data classification architectures in established enterprises require substantial capital expenditure to interface with API-native cloud compliance platforms.
- Regulatory Fragmentation Risk:Divergent national interpretations of GDPR Article 22 automated decision-making provisions are creating compliance uncertainty for AI-embedded analytics vendors.
Strategic Opportunities
- Small and Medium Enterprise Segment:Mid-market organizations across Spain and Italy remain underpenetrated by automated compliance solutions, presenting white-space for modular, price-optimized offerings.
- Healthcare Data Convergence:The intersection of GDPR and the EU Medical Device Regulation is creating demand for integrated platforms managing both clinical trial data and patient privacy.
- Blockchain-Enabled Consent Logging:Immutable distributed ledger technologies are emerging as a defensible audit trail mechanism for high-frequency consent transactions in digital advertising.
Industry Challenges
- Technical Implementation Complexity:Data mapping exercises across shadow IT environments and unsanctioned SaaS applications frequently exceed projected resource allocations.
- Competency Shortfalls in DPO Functions:Organizations struggle to staff roles combining legal expertise, information security credentials, and business process engineering capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | General Data Protection Regulation (GDPR) Market |
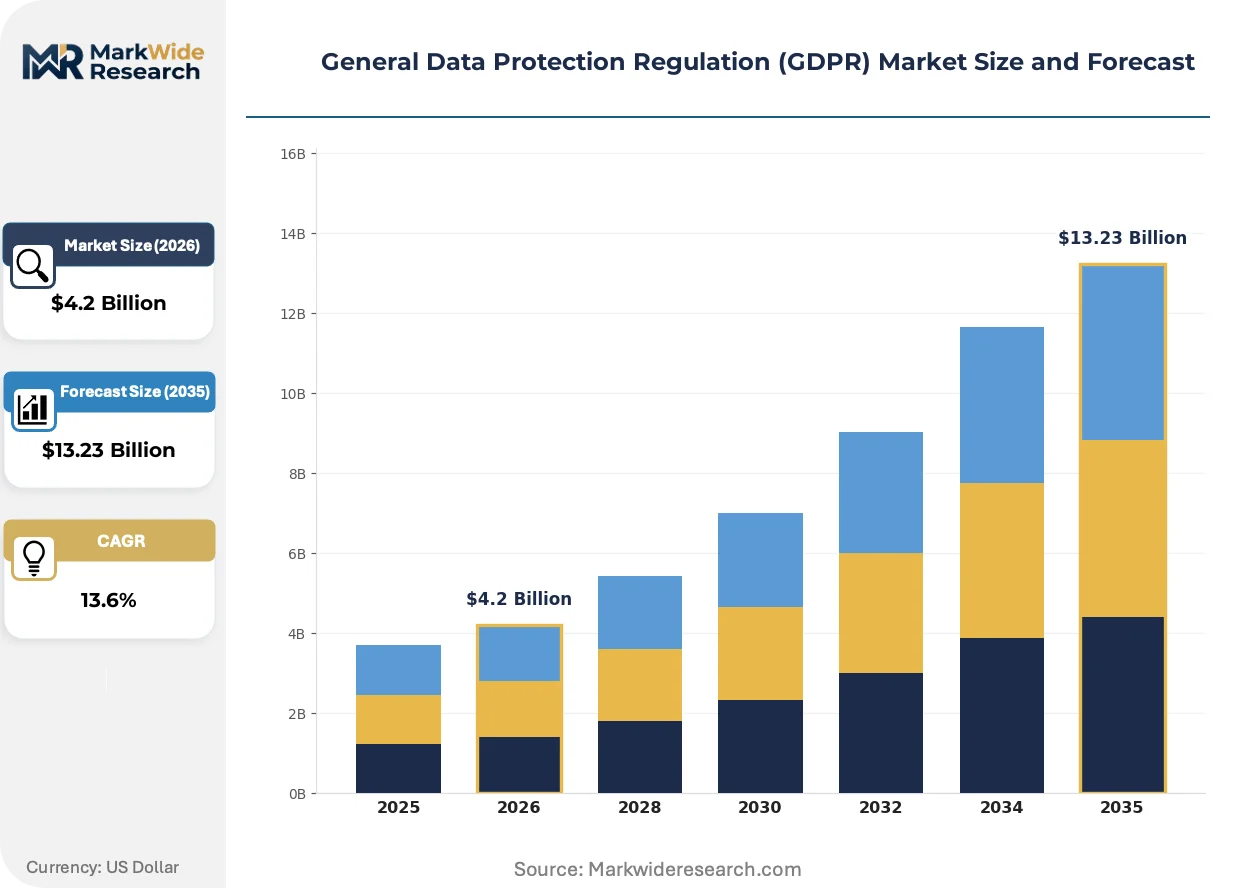
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $13.23 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Privacy Management, Compliance Management, Risk Assessment, Incident Response, Consent Management, Data Discovery Deployment Mode: Cloud-Based, On-Premises, Hybrid, Private Cloud, Public Cloud Application: Enterprise Compliance, Vendor Management, Data Subject Access Requests, Data Protection Impact Assessment, Audit & Reporting, Policy Management End User: Financial Services, Telecommunications, Information Technology, Government Agencies, Legal Firms, Educational Institutions |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, Accenture, Deloitte, PwC, KPMG, OneTrust, Capgemini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
General Data Protection Regulation (GDPR) Market Shifts & Advancements
Privacy-enhancing computation methods are migrating from research environments into production architectures, redefining how organizations balance analytical utility against data minimization obligations.
Homomorphic encryption is miniaturizing. Financial institutions in Frankfurt and Paris are piloting privacy-preserving analytics on encrypted datasets without decryption, compressing the traditional trade-off between data utility and protection. This capability is miniaturizing the compliance overhead historically associated with cross-functional data sharing.
The EU AI Act's high-risk system obligations are reshaping vendor liability frameworks. Providers of automated decision-making tools must now embed technical documentation and human oversight mechanisms directly into product architectures. Healthcare and recruitment technology segments are most affected, with Dutch and Belgian regulators issuing early guidance on conformity assessment pathways.
Enterprise buyers are consolidating vendor relationships. Procurement functions in German manufacturing and French retail are reducing their supplier rosters from point solutions toward integrated governance platforms. This concentration is most visible among organizations with operations spanning multiple EU member states, where unified audit trails reduce supervisory examination preparation costs.
General Data Protection Regulation (GDPR) Market Segmentation
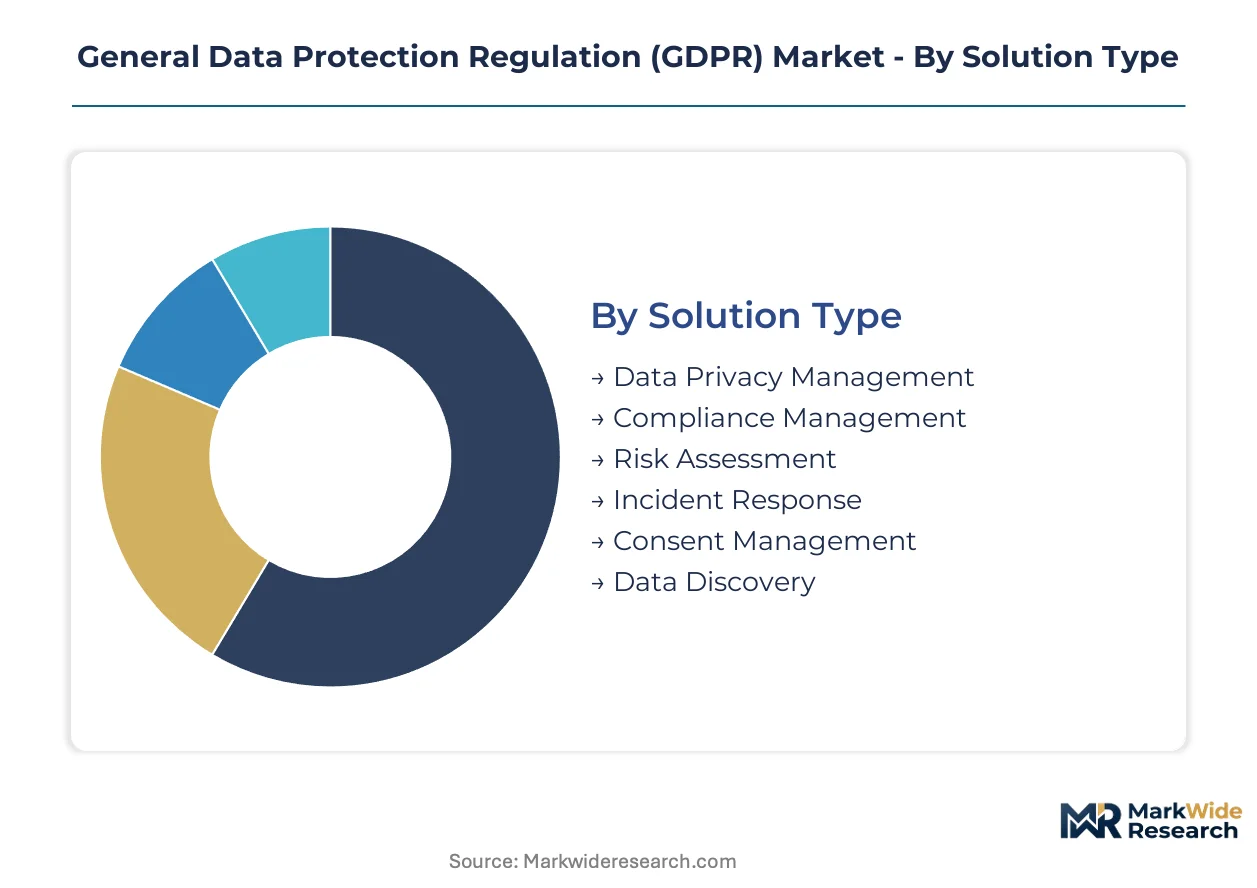
GDPR solution procurement patterns diverge sharply between multinational enterprises requiring unified cross-border governance and domestic operators managing single-jurisdiction obligations. Segmentation reveals where vendor specialization creates pricing power versus where platform consolidation dominates buying decisions.
Solution Type:
Cloud-based delivery has inverted the geographic spread of solution demand, with data privacy management tools now scaling across German manufacturing hubs and French financial centers simultaneously while consent management remains concentrated in media-dense urban clusters.
- Data Privacy Management:Core platforms automate data mapping, classification, and retention scheduling across structured and unstructured repositories. German automotive suppliers and French luxury goods houses are consolidating procurement here to satisfy supervisory authority examination protocols from CNIL and regional German data protection commissioners.
- Compliance Management:Integrated dashboards aggregate regulatory deadline tracking, documentation workflows, and audit trail maintenance. Demand concentrates among mid-market enterprises in Spain and Italy seeking to avoid the personnel costs of dedicated data protection officer functions.
- Risk Assessment:Automated scoring engines evaluate processing activity registers against Article 35 Data Protection Impact Assessment thresholds.
- Incident Response:Breach notification automation tools enforce the 72-hour supervisory authority reporting window.
- Consent Management:Granular preference centers with purpose-specific opt-in architectures. Ad-tech vendors in Amsterdam and programmatic platforms in London are driving specialized procurement responding to IAB Europe Transparency and Consent Framework mandates.
- Data Discovery:Machine learning-powered scanning for shadow IT and unsanctioned personal data repositories.
Data privacy management commands the established base. The steepest expansion runs through consent management.
Deployment Mode:
Cost tier stratification separates enterprise-grade private cloud installations from mid-market public cloud subscriptions, with hybrid architectures capturing organizations in transition from legacy on-premises data classification systems.
- Cloud-Based:Multi-tenant SaaS architectures with API-native integration into Microsoft 365, Salesforce, and SAP environments. Financial services firms in Frankfurt and Paris are accelerating migration budgets to retire capital-intensive on-premises infrastructure.
- On-Premises:Air-gapped installations for classified government processing or highly sensitive intellectual property regimes. Defense contractors and national security agencies in EU member states maintain this preference despite higher total cost of ownership.
- Hybrid:Sensitive personal data remains on-premises while analytics and reporting functions shift to cloud substrates. Healthcare networks in the Netherlands and Belgium favor this architecture to reconcile GDPR with EU Medical Device Regulation data localization requirements.
- Private Cloud:Single-tenant dedicated infrastructure with customizable encryption key management.
- Public Cloud:Shared infrastructure with standardized security certifications and rapid provisioning.
Cloud-based deployments capture the dominant revenue position. Hybrid configurations are climbing the fastest as regulated industries navigate data residency constraints.
Application:
Customer type differentiation separates large enterprises purchasing integrated suites from specialized buyers seeking point solutions for high-frequency workflows like data subject access request fulfillment.
- Enterprise Compliance:Organization-wide governance frameworks spanning multiple business units and jurisdictions. Multinational retailers with operations across Germany, France, and Poland are consolidating procurement to reduce supervisory examination preparation costs.
- Vendor Management:Automated processor due diligence, contract clause verification, and ongoing compliance monitoring. Supply chain-heavy industries including automotive and pharmaceuticals in Stuttgart and Basel are prioritizing this capability.
- Data Subject Access Requests:Workflow automation for the 30-day response deadline mandated under Article 15. High-volume consumer-facing businesses in telecommunications and utilities face the greatest processing pressure.
- Data Protection Impact Assessment:Systematic evaluation templates for high-risk processing under Article 35.
- Audit & Reporting:Evidence repositories and supervisory authority interface documentation.
- Policy Management:Version-controlled privacy notices and internal procedure documentation.
Enterprise compliance holds the deepest installed base. Data subject access request automation is expanding most quickly as consumer awareness drives submission volume.
End User:
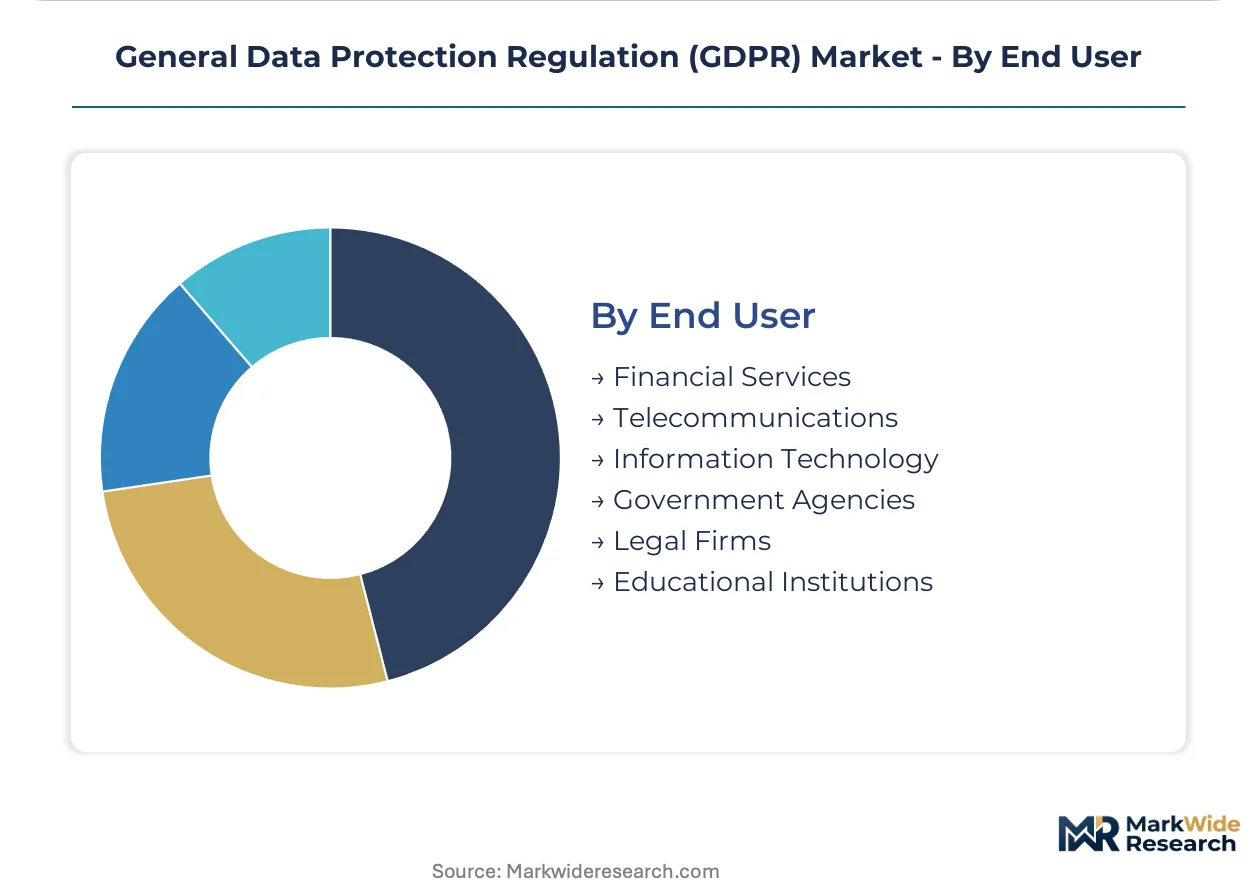
Maturity stage segmentation separates regulated industries with embedded compliance functions from sectors where GDPR implementation remains reactive and examination-driven.
- Financial Services:Banks, insurers, and asset managers with pre-existing regulatory infrastructure. BaFin in Germany and ACPR in France are intensifying scrutiny of data retention policies, accelerating automated classification module procurement.
- Telecommunications:Mobile operators and internet service providers with massive subscriber datasets. Italian and Spanish regulators have issued precedent-setting fines in this sector, concentrating vendor evaluation cycles on defensible audit trail capabilities.
- Information Technology:Software vendors and cloud service providers acting as processors for downstream controllers. SaaS companies in Dublin and Amsterdam are embedding compliance modules into product roadmaps to satisfy enterprise procurement requirements.
- Government Agencies:Public sector bodies with sovereign immunity considerations and cross-border data sharing obligations.
- Legal Firms:Advisory practices bundling technical implementation with regulatory counsel.
- Educational Institutions:Universities managing international student data and research participant privacy.
Financial services anchors current spending. Information technology service providers are gaining share fastest as processor liability expands under supervisory authority guidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes GDPR solutions through manufacturing-heavy compliance automation, while France prioritizes financial services audit trails. The United Kingdom diverges toward ad-tech consent frameworks. Italy and Spain lag in cloud migration, creating mid-market whitespace.
Germany
Automotive suppliers in Stuttgart and Munich drive demand for data mapping tools that satisfy regional data protection commissioners. BaFin intensifies scrutiny of data retention policies across banking subsidiaries. Frankfurt's financial cluster accelerates procurement of automated classification modules for cross-border transaction monitoring.
France
Luxury goods houses and ACPR-regulated insurers anchor compliance spending in Paris and Lyon. CNIL's enforcement precedents on automated decision-making force algorithmic auditing capabilities into vendor requirements. The Île-de-France tech corridor concentrates consent management specialization for media publishers.
United Kingdom
ICO's post-Brexit adequacy negotiations sustain cross-border data transfer solution demand in London and Manchester. Programmatic advertising platforms in the capital drive specialized procurement responding to IAB Europe Transparency and Consent Framework mandates. Fintech clusters prioritize breach notification automation.
Italy
Telecommunications operators face precedent-setting fines from the national data protection authority, concentrating vendor evaluation on defensible audit trails. Milan's manufacturing base lags in cloud migration, extending implementation timelines for hybrid architectures. Mid-market enterprises seek modular compliance dashboards to avoid dedicated data protection officer costs.
Spain
Energy utilities and mobile operators in Madrid and Barcelona manage high-volume data subject access request workflows. The national supervisory authority's examination protocols drive automation procurement among consumer-facing businesses. Andalusian and Valencian mid-market organizations remain underpenetrated by integrated governance platforms.
General Data Protection Regulation (GDPR) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. The upper tier bundles legal advisory, technical implementation, and ongoing audit services into multi-year enterprise contracts. Specialist vendors compete through API-native architectures and rapid deployment cycles. Dominant competitive moves include strategic partnerships with cloud hyperscalers and vertical integration into adjacent risk management software.
Within the integrated advisory tier, Deloitte and PwC exemplify bundled service models that combine regulatory counsel with technical deployment. IBM Corporation anchors the technology-centric segment, embedding compliance modules within broader enterprise infrastructure contracts. Microsoft Corporation occupies a position competing through native integration with productivity suites, displacing standalone point solutions in procurement evaluations.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| Accenture |
| Deloitte |
| PwC |
| KPMG |
| OneTrust |
| Capgemini |
| Others |
Supply & Pricing Matrix
Platform scale economies in cloud-native compliance architectures concentrate procurement leverage among hyperscaler-backed vendors, compressing price floors for point-solution providers while elevating bundled-service premiums. German financial institutions and French luxury goods houses exploit this concentration through multi-year enterprise contracts that trade customization depth for unit-cost predictability.
Pricing Analysis
Contract structures bifurcate between multi-year SaaS subscriptions with annual escalation clauses and project-based implementation fees for complex data migration scenarios. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration complexity and dedicated support tiers, with BaFin-regulated banks absorbing premium pricing for audit-ready documentation while Spanish mid-market enterprises cluster in economy tiers. Pricing pressure stems from Microsoft Corporation's native bundling of compliance modules within existing productivity licenses. Mid-market organizations in Italy and Spain exhibit highest price sensitivity due to constrained procurement budgets.
Supply Chain Analysis
Just-in-time provisioning dominates cloud-based delivery, with API-native vendors maintaining minimal inventory through automated tenant provisioning and elastic compute scaling. Engineering talent concentrates in Ireland, Germany, and the Netherlands, where Dublin's SaaS corridor and Berlin's privacy-tech cluster feed specialized development capacity. The supply chain draws from cryptographic library dependencies, cloud infrastructure substrates, and certified legal advisory capacity. Single-source vulnerability runs through hyperscaler compute platforms. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GDPR solution procurement is consolidating onto interoperability platforms that embed compliance into broader governance stacks, with EU AI Act convergence forcing vendors to architect cross-regulatory data pipelines rather than standalone privacy tools.
For Market Incumbents: Compound defensive positioning through backward integration into legal advisory capacity and captive certification training programs. Consolidate procurement relationships with German automotive suppliers facing dual GDPR and EU AI Act obligations. Prioritize embedded algorithmic auditing capabilities to preempt displacement by AI-native entrants. For New Entrants and Emerging Players: CNIL and ICO certification fast-tracks for consent management modules unlock immediate addressable market among Amsterdam ad-tech vendors and London programmatic platforms. Target underpenetrated mid-market healthcare networks in Belgium and the Netherlands managing converged GDPR and EU Medical Device Regulation data localization requirements. Lead with API-first architectures and 30-day deployment guarantees. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized vendors with pre-certified AI Act capabilities over legacy compliance incumbents. Five-to-ten-year viability hinges on cross-regulatory platform consolidation rather than point-solution depth. Monitor EDPB binding decisions on international data transfers as inflection signal for supplementary contractual clause engineering demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding GDPR modules within Microsoft 365 governance stacks displaces standalone vendors in German enterprise evaluations. |
| Certification Investment | Pre-certified EU AI Act algorithmic auditing capabilities compress vendor selection cycles for Frankfurt financial services procurement. |
| Geographic Expansion | Mid-market penetration in Spain and Italy captures whitespace from automated compliance dashboards avoiding dedicated DPO costs. |
| Strategic Partnership | Systems integrator alliances with Deloitte and Accenture bundle legal advisory with technical implementation for Paris luxury goods houses. |
| Acquisition of Specialist Firm | Consent management specialists in Amsterdam and London address IAB Europe Transparency and Consent Framework mandates for ad-tech publishers. |
Research Methodology
Operator-level perspectives from data protection officers, chief privacy officers, IT procurement leads, and regulatory affairs directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EDPB guidance documents, CNIL enforcement precedents, SEC filings from listed compliance vendors, and IAB Europe framework specifications. Bottom-up sizing of solution deployments triangulated against top-down regulatory expenditure estimates across the analysis window.
Sensitivity analysis tested forecast outputs against alternative scenarios for cloud migration velocity and AI Act implementation timelines. Segmentation dimensions modeled include deployment mode, solution type, organization size tier, vertical regulatory intensity, and regional supervisory authority enforcement posture. CAGRs were derived from trend extrapolation calibrated to disclosed vendor growth rates and procurement pipeline indicators. Forecast inputs incorporated BaFin data retention policy scrutiny intensity and IAB Europe framework adoption curves.
Decision-makers should treat outputs as directional under sustained EDPB enforcement harmonization and stable hyperscaler pricing; material deviation would warrant model refresh. Revision becomes warranted when EU AI Act conformity assessment pathways diverge across member state implementations or adequacy decision suspensions disrupt cross-border data transfer solution demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
GDPR Assessment Tools Market
Regulatory Compliance Technology
Global GDPR Services Market
Regulatory Compliance Technology
Compliance and Traceability Solutions Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
Aviation Compliance Monitoring Software Market
Regulatory Compliance Technology
Compliance Testing Solutions Market
Regulatory Compliance Technology
Regulatory Reporting Solutions Market
Regulatory Compliance Technology
Global AML Software Market
Regulatory Compliance Technology
Regulatory Change Management Software Market
Regulatory Compliance Technology
United States Sales Tax Compliance Software Market
Regulatory Compliance Technology
Global Anti- Money Laundering Solutions Market
Regulatory Compliance Technology
Regulatory Information Management System Market
Regulatory Compliance Technology
Nordic Regulatory Affairs Market
Regulatory Compliance Technology
US Anti Money Laundering Solution Market
Regulatory Compliance Technology
Anti-Money Laundering Systems Market
Regulatory Compliance Technology
Global Regulatory Technology (Regtech) Market