
 Global Regulatory Technology (Regtech) Market | 2026-2036
Global Regulatory Technology (Regtech) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Regulatory Technology (Regtech) Market Foresight
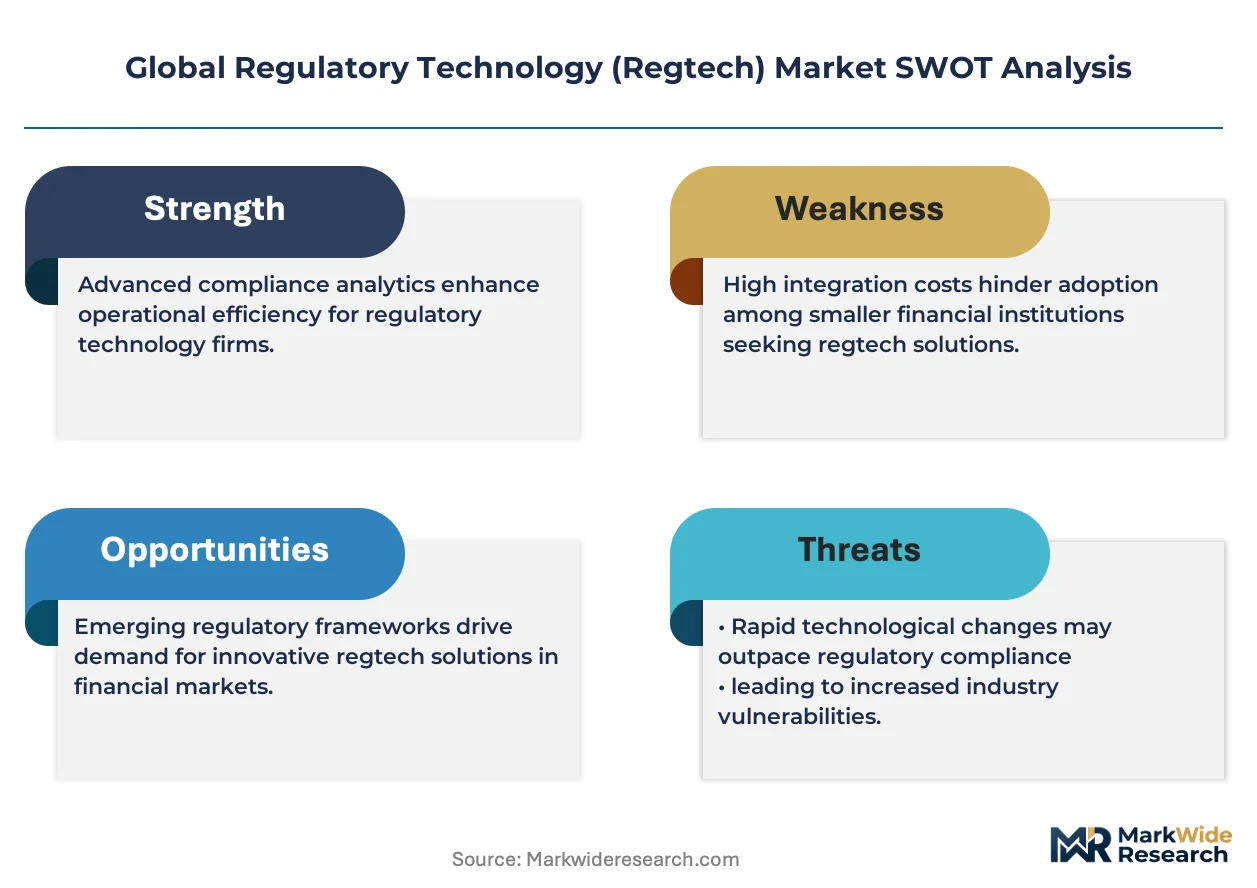
Multi-source procurement of compliance infrastructure is realigning how financial institutions distribute vendor risk. IBM leverages its hybrid cloud architecture to anchor enterprise deployments across capital markets. Thomson Reuters competes through regulatory content integration that sustains workflow automation for tier-one banks. Chainalysis specializes in blockchain analytics, occupying a defensible niche as digital asset supervision tightens.
Regulatory technology encompasses software platforms, data analytics engines, and automated reporting systems that interpret, monitor, and enforce compliance obligations across jurisdictions. These systems integrate natural language processing for regulatory text analysis, API connectivity for real-time data ingestion, and machine learning models for anomaly detection in transaction surveillance. Cloud-based deployment leads solution delivery, capturing the fastest expansion as institutions prioritize scalability and reduced capital expenditure over on-premises infrastructure. Identity verification and fraud detection command concentrated investment within the solution type dimension, reflecting escalating KYC mandates and real-time payment risks.
The SEC, FCA, and MAS shape procurement priorities through enforcement patterns that elevate real-time reporting standards. EU regulators including EBA and ESMA enforce DORA and MiFID II obligations that mandate operational resilience testing and transaction transparency. Stakeholders must monitor divergence between prescriptive rulebooks and principles-based supervision as jurisdictions compete for financial services activity.
Market Dynamics
Real-time transaction surveillance mandates from the SEC, FCA, and MAS are compressing deployment timelines for cloud-native compliance platforms. Financial institutions now face penalties measured in basis points of capital for reporting latency, forcing infrastructure replacement cycles that previously spanned seven years to collapse below twenty-four months.
Growth Catalysts
- EU AI Act enforcement:Automated decision-making audits in credit scoring and insurance underwriting are mandating algorithmic transparency tools across European banking networks.
- Digital asset supervision:Travel Rule compliance for cryptocurrency exchanges is generating dedicated blockchain analytics procurement from virtual asset service providers in Singapore and Switzerland.
- Operational resilience testing:DORA mandates from EU regulators require financial entities to demonstrate recovery capabilities within two hours, accelerating disaster-recovery-as-a-service adoption.
Market Restraints
- Specialized talent scarcity:Compliance engineering roles combining regulatory expertise with machine learning deployment command salary premiums exceeding forty percent above standard software engineering.
- Cloud concentration risk:Three hyperscale providers dominate sovereign cloud infrastructure for financial services, creating single-point-of-failure exposure for critical supervisory data.
- Cross-border data friction:GDPR adequacy determinations and Schrems II rulings complicate centralized compliance platform architectures serving multinational banking groups.
Strategic Opportunities
- Embedded finance penetration:Non-bank payment platforms in Brazil and India lack mature compliance infrastructure, creating greenfield deployment opportunities for modular KYC APIs.
- Convergence of NLP and graph analytics:Regulatory text interpretation combined with entity relationship mapping enables preemptive obligation identification before formal rulemaking concludes.
- Supervisory technology export:Regulatory agencies in emerging markets are procuring inspection automation tools developed for ECB and BoE stress-testing frameworks.
Industry Challenges
- Legacy core banking integration:Mainframe transaction feeds require expensive middleware development to achieve sub-second latency for real-time AML screening.
- Model risk management:Machine learning anomaly detection systems demand continuous validation documentation that most institutions lack operational capacity to produce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Regulatory Technology (Regtech) Market |
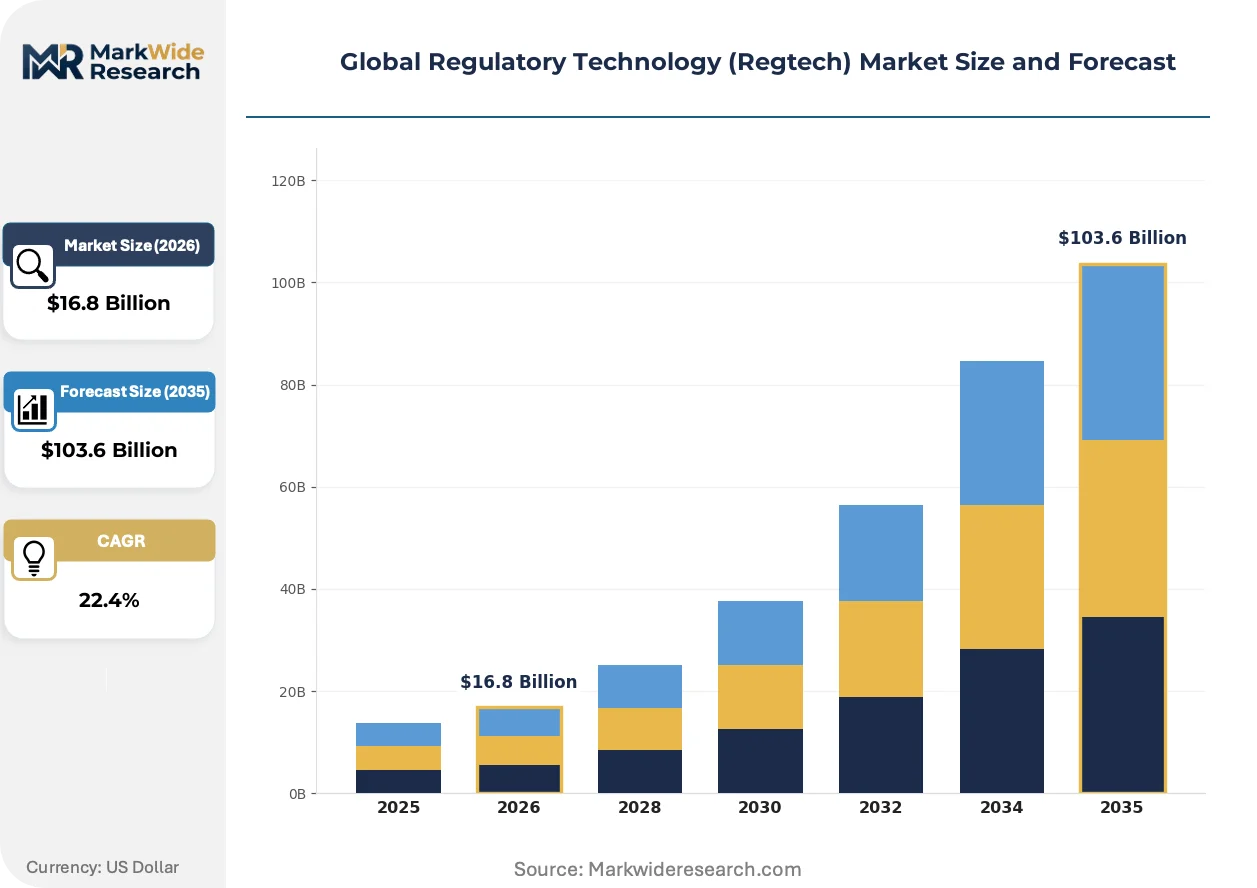
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $103.6 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Risk Management, Compliance Management, Identity Verification, Fraud Detection, Data Privacy, Reporting Automation Deployment Model: Cloud-Based, On-Premises, Hybrid, Software as a Service, Platform as a Service End User Industry: BFSI, Telecommunications, Government Agencies, Energy & Utilities, Insurance, Technology Firms Organizational Size: Small Enterprises, Mid-Sized Companies, Large Corporations, Startups, Non-Profit Organizations |
| Companies Covered | Broadridge Financial Solutions, Deloitte Touche Tohmatsu Limited, IBM, NICE Actimize, Thomson Reuters, PwC, London Stock Exchange Group, MetricStream, Chainalysis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Regulatory Technology (Regtech) Market Shifts & Advancements
Generative AI is compressing the regulatory interpretation workflow from weeks to hours, forcing platform vendors to rearchitect around large language model inference rather than static rule engines. This shift is redistributing competitive advantage toward firms with proprietary training data from enforcement actions and supervisory correspondence.
Natural language processing for regulatory text analysis is electrifying the obligation extraction process. Tier-one banks in London and New York are deploying these systems across derivatives trading desks to auto-generate compliance checklists from draft rule releases. The technology is compressing the gap between regulatory publication and operational implementation from months to days.
The EU AI Act's risk classification framework for financial algorithms is mandating conformity assessments before deployment. Asset managers operating across Frankfurt, Paris, and Amsterdam must now document training data provenance and model drift monitoring protocols. High-risk credit decisioning systems face mandatory human oversight interfaces that increase interface development costs substantially.
Consolidated vendor relationships are displacing point-solution procurement as institutions prioritize interoperability over best-of-breed functionality. Chief compliance officers at North American and Asia-Pacific banks are demanding unified data lakes spanning AML, trade surveillance, and conduct monitoring. Singaporean private banks have pioneered this approach, achieving single-view dashboards that reduce false positive rates through shared entity resolution.
Global Regulatory Technology (Regtech) Market Segmentation
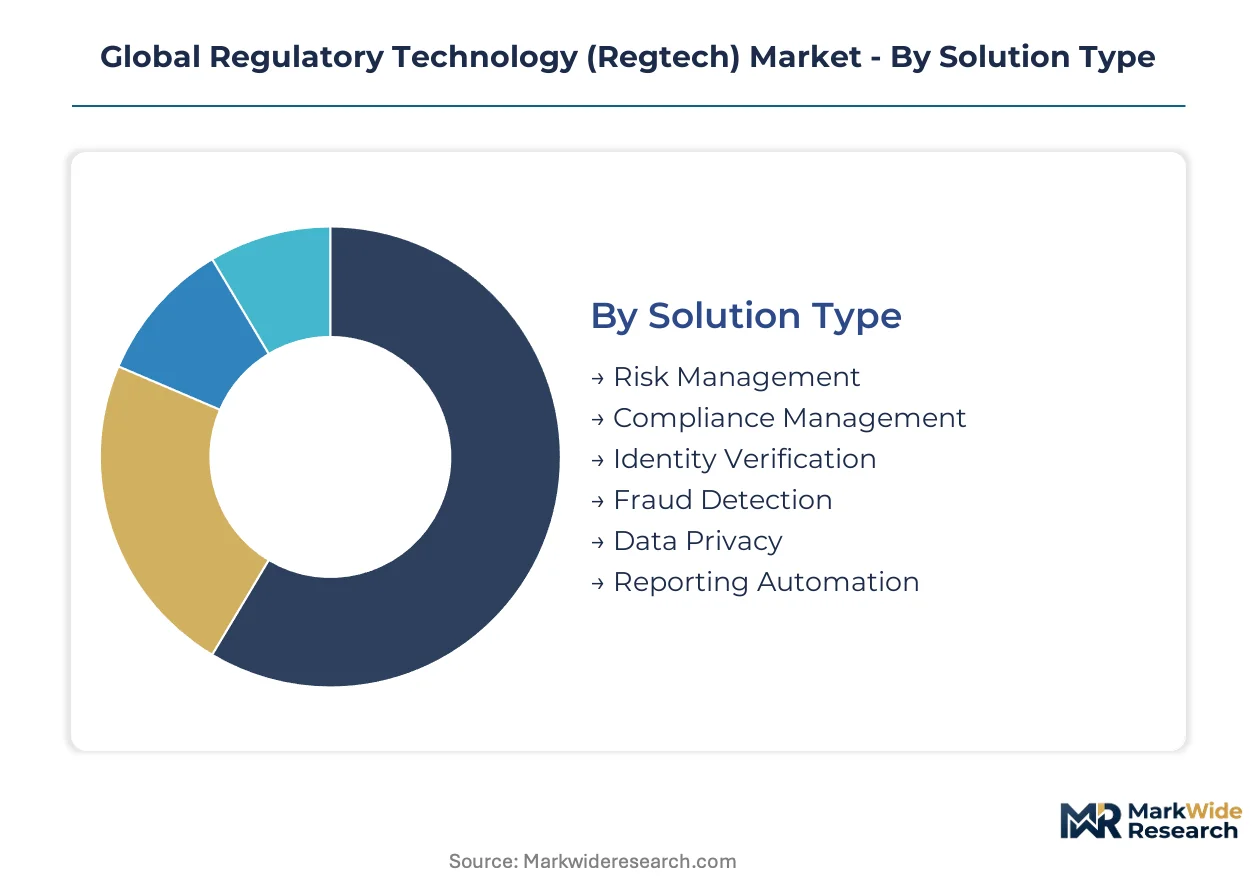
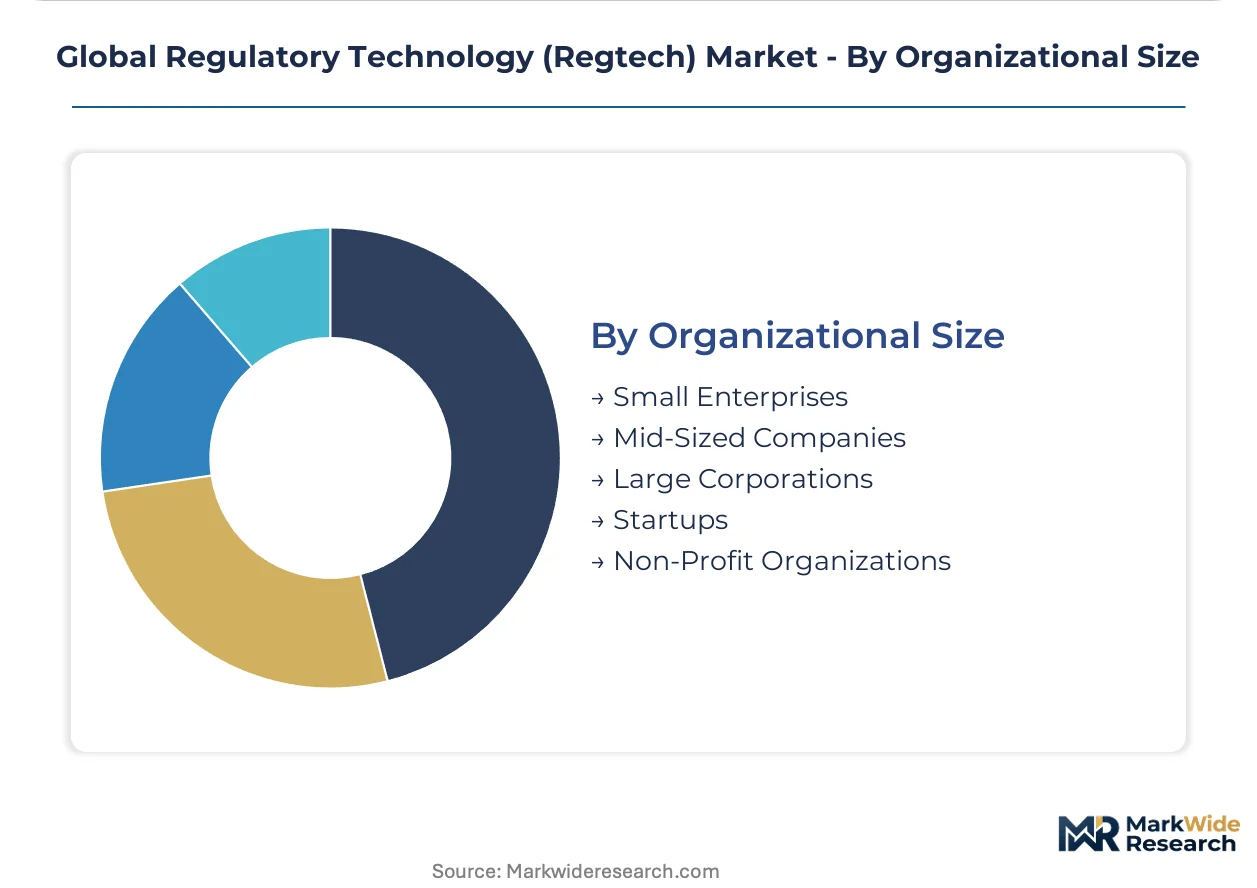
Regtech procurement patterns diverge sharply across solution architectures, with infrastructure replacement cycles compressing from seven years to under twenty-four months as real-time surveillance mandates intensify. Financial institutions now segment vendor selection by latency tolerance, data sovereignty requirements, and integration complexity with legacy core banking systems.
Solution Type:
Upgrade cycles for compliance infrastructure are collapsing as regulators impose sub-second reporting latency penalties measured in basis points of capital.
- Risk Management:Quantitative engines calculate capital adequacy, liquidity coverage, and stress-test scenarios across trading book exposures. Tier-one banks in London and New York deploy these systems for derivatives desk oversight, driven by FCA and SEC margin requirement recalibrations.
- Compliance Management:Workflow platforms orchestrate obligation tracking, audit trail generation, and regulatory calendar synchronization. Singaporean private banks concentrate procurement here, responding to MAS technology risk management guidelines that mandate automated control documentation.
- Identity Verification:Biometric authentication and document validation APIs for KYC onboarding pipelines.
- Fraud Detection:Real-time transaction scoring models flag anomalous patterns in payment rails.
- Data Privacy:Consent management and subject access request automation for GDPR and emerging jurisdiction equivalents.
- Reporting Automation:Structured data submission engines for regulatory filings including MiFID II transaction reports.
Volume placements concentrate in Risk Management; the faster expansion belongs to Identity Verification as embedded finance penetration accelerates KYC API demand.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises builds from operational-expenditure cloud contracts favored by mid-tier institutions.
- Cloud-Based:Elastic compute architectures scale surveillance capacity during market volatility spikes without fixed infrastructure commitment. European banking networks prioritize these deployments to satisfy EBA operational resilience guidelines while avoiding data center capital lock-in.
- On-Premises:Dedicated hardware installations maintain air-gapped environments for classified supervisory data or geopolitically sensitive jurisdictions. Central banks and defense-adjacent financial entities in Switzerland and Israel demand these configurations for quantum-resistant cryptography integration.
- Hybrid:Split architectures process non-sensitive workflows in public cloud while retaining core transaction data on sovereign infrastructure.
- Software as a Service:Standardized compliance modules with limited customization for cost-constrained regional banks.
- Platform as a Service:Developer environments enabling proprietary model deployment atop vendor-managed infrastructure.
Revenue concentration sits with Cloud-Based deployments; the steepest expansion trajectory belongs to Hybrid models as data localization requirements proliferate.
End User Industry:
Application intensity varies by regulatory burden density, with transaction surveillance obligations scaling proportionally to payment velocity and counterparty complexity.
- BFSI:Universal banks, investment dealers, and asset managers deploy the most comprehensive compliance stacks. US money center banks and UK clearing institutions lead procurement volume, responding to SEC Consolidated Audit Trail and FCA SYSC rule enhancements.
- Telecommunications:Mobile money operators and digital wallet providers face emerging licensing regimes requiring AML program parity with traditional banks. Nigerian and Kenyan fintech corridors drive African procurement concentration.
- Government Agencies:Tax authorities and financial intelligence units procure supervisory technology for inspection automation.
- Energy & Utilities:Commodity trading desks within integrated oil majors face CFTC and FCA position reporting mandates.
- Insurance:Solvency II and ORSA reporting requirements drive actuarial data platform investment.
- Technology Firms:Cryptocurrency exchanges and stablecoin issuers respond to Travel Rule implementation deadlines.
Procurement volume concentrates in BFSI; the fastest-climbing demand emerges from Technology Firms as virtual asset service provider licensing expands.
Organizational Size:
Customer type determines solution sophistication, with enterprise procurement favoring customizable platforms while smaller entities accept standardized SaaS configurations.
- Large Corporations:Global banking groups operate multi-jurisdiction compliance programs requiring unified data lakes spanning AML, trade surveillance, and conduct monitoring. These entities command dedicated vendor engineering resources and influence product roadmaps through co-development agreements.
- Mid-Sized Companies:Regional banks and specialty insurers seek pre-integrated modules reducing implementation timeline and internal IT burden. German Landesbanken and Australian regional banks exemplify this segment's procurement patterns.
- Small Enterprises:Community banks and credit unions prioritize cost containment over feature depth.
- Startups:Neobanks and payment fintechs embed compliance APIs from inception to accelerate licensing timelines.
- Non-Profit Organizations:Microfinance institutions and development finance entities with limited technology budgets.
Vendor revenue concentrates in Large Corporations; the most rapid expansion occurs among Startups as regulatory sandbox participation lowers compliance infrastructure barriers to entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data sovereignty requirements in Frankfurt, Singapore, and New York anchor procurement patterns for compliance infrastructure. Financial centers compete through regulatory sophistication rather than cost arbitrage. Cloud localization mandates fragment vendor deployment architectures across jurisdictions.
United States
SEC enforcement actions against reporting latency drive replacement of legacy surveillance systems at money center banks. The Consolidated Audit Trail mandate forces broker-dealers to upgrade transaction reporting infrastructure by fixed deadlines. Manhattan and Chicago trading floors deploy sub-second anomaly detection for derivatives desks.
United Kingdom
FCA operational resilience rules compress recovery time objectives to two hours for critical banking functions. SYSC 8 outsourcing guidelines mandate vendor oversight capabilities that favor established platform providers. The City of London and Edinburgh financial clusters concentrate procurement for MiFID II transaction reporting automation.
Germany
BaFin guidance on DORA implementation demands operational resilience testing documentation from Frankfurt-based universal banks. The EU AI Act risk classification framework mandates conformity assessments for credit scoring algorithms deployed across Bavarian and North Rhine-Westphalian banking networks. Munich insurers face Solvency II reporting upgrades.
Singapore
MAS technology risk management guidelines mandate automated control documentation for private banking compliance stacks. Travel Rule enforcement against virtual asset service providers generates blockchain analytics procurement from fintech corridors. The Marina Bay financial district anchors Southeast Asian regulatory technology deployment.
Switzerland
FINMA circulars on operational risk require Zurich and Geneva private banks to demonstrate disaster recovery capabilities. Geopolitical neutrality demands air-gapped infrastructure for certain supervisory data categories. Swiss cryptocurrency exchanges face Travel Rule compliance deadlines that accelerate vendor selection.
Global Regulatory Technology (Regtech) Market Competitive Landscape
Platform consolidation dominates the current landscape as institutions abandon point solutions for unified compliance stacks. The vendor base stratifies between hyperscale cloud providers, specialized analytics firms, and professional services networks with embedded technology platforms. Three strategic archetypes occupy distinct positions: cloud-native specialists, regulatory content aggregators, and audit-integrated consultancies. M&A activity and strategic partnerships represent the dominant competitive vectors as incumbents acquire machine learning capabilities and niche analytics providers.
Within the cloud infrastructure tier, IBM anchors enterprise deployments through hybrid architecture offerings. Thomson Reuters occupies a position exemplifying regulatory content integration for tier-one banking workflows. Chainalysis represents the specialized analytics archetype, serving blockchain supervision requirements as digital asset regulation tightens across Singaporean and Swiss jurisdictions.
| Leading Market Players |
|---|
| Broadridge Financial Solutions |
| Deloitte Touche Tohmatsu Limited |
| IBM |
| NICE Actimize |
| Thomson Reuters |
| PwC |
| London Stock Exchange Group |
| MetricStream |
| Chainalysis |
| Others |
Supply & Pricing Matrix
EU AI Act algorithmic transparency mandates gate qualified supply for high-risk credit scoring modules, reserving premium-tier pricing access for vendors with documented conformity assessment capabilities and proven training data provenance.
Pricing Analysis
Service-bundling separates implementation support and continuous model validation from base platform licenses, with tier-one banks in London and New York paying substantial premiums for dedicated vendor engineering resources. Pricing stratifies across enterprise, mid-market, and startup tiers based on customization depth and jurisdictional coverage breadth. Cost compression in the mid-market tier is intensifying because regional banks demand pre-integrated modules reducing internal IT burden. Startups exhibit highest price sensitivity, prioritizing standardized SaaS configurations over feature depth.
Supply Chain Analysis
SOC 2 Type II and ISO 27001 certifications gate vendor eligibility for financial institution procurement, with cloud infrastructure provisioning concentrated in the United States, Ireland, and Singapore to satisfy data localization mandates. Core components draw from specialized machine learning compute providers, regulatory content aggregators, and sovereign cloud operators. Single-source vulnerability concentrates in hyperscale infrastructure where three providers dominate critical supervisory data hosting. Distribution runs through direct enterprise sales teams and systems integrator partnerships serving mid-tier institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as real-time surveillance mandates compress replacement cycles below twenty-four months, forcing point-solution vendors without unified platform architectures toward acquisition or exit.
For Market Incumbents: Anticipate displacement by cloud-native specialists through accelerated roadmap investment in generative AI regulatory interpretation capabilities. Anchor enterprise relationships via co-development agreements for multi-jurisdiction compliance data lakes. Prioritize backward integration into proprietary training datasets from enforcement actions and supervisory correspondence to defend against LLM-native entrants. For New Entrants and Emerging Players: API-first distribution routes into embedded finance platforms in Brazil and India offer lowest competitive density against established vendor relationships. Target neobank compliance infrastructure in regulatory sandbox jurisdictions where licensing timelines favor modular KYC solutions. Pursue partnership-led go-to-market with systems integrators serving mid-tier regional banks in Germany and Australia. For Investors and Strategic Acquirers: MAS Travel Rule enforcement acceleration against Singaporean virtual asset service providers is the leading indicator that blockchain analytics procurement will outpace broader Regtech growth. Position for five-to-ten year horizon consolidation plays targeting specialized analytics firms with defensible training data moats. Monitor DORA implementation deadlines across EU member states as inflection signal for operational resilience testing platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies AML, trade surveillance, and conduct monitoring data lakes for tier-one banks. |
| Acquisition of Specialist Firm | Secures machine learning anomaly detection capabilities and compliance engineering talent. |
| Strategic Partnership | Combines regulatory content from Thomson Reuters with cloud infrastructure from IBM. |
| Geographic Expansion | Establishes sovereign cloud presence in Frankfurt and Singapore for data localization compliance. |
| Product Launch | Deploys generative AI regulatory interpretation tools for derivatives trading desks in London. |
Research Methodology
Regulatory filings from the SEC, FCA, and MAS, enforcement action databases, and vendor contract disclosure records formed the secondary backbone for market sizing and procurement pattern analysis. Primary interviews with chief compliance officers, vendor product managers, regulatory technology integration specialists, and financial intelligence unit directors provided operational validation of deployment timelines and platform selection criteria. Bottom-up segment builds triangulated against top-down macroeconomic indicators across the analysis window.
Historical trendline analysis of compliance infrastructure replacement cycles informed projection frameworks, with segmentation across solution type, deployment model, end-user industry, and organizational size. Modeled dimensions included latency tolerance thresholds, data sovereignty requirements, and legacy core banking integration complexity. CAGRs derived from regression analysis of procurement volume against regulatory mandate implementation deadlines, with specific inputs for cloud migration acceleration and embedded finance penetration rates.
The model holds under stable regulatory enforcement intensity; deviation in SEC or ECB penalty recalibration schedules would shift vendor revenue concentration. Forecasts reflect assumptions regarding cloud provider market concentration and cross-border data transfer adequacy determinations. A model refresh is warranted upon material change in EU AI Act risk classification enforcement patterns or DORA operational resilience testing deadline extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
Compliance and Traceability Solutions Market
Regulatory Compliance Technology
Aviation Compliance Monitoring Software Market
Regulatory Compliance Technology
Nordic Regulatory Affairs Market
Regulatory Compliance Technology
Regtech Software Market
Regulatory Compliance Technology
United States Sales Tax Compliance Software Market
Regulatory Compliance Technology
Regulatory Information Management System Market
Regulatory Compliance Technology
Management System Certification Market
Regulatory Compliance Technology
Regulatory Reporting Solutions Market
Regulatory Compliance Technology
Global GDPR Services Market
Regulatory Compliance Technology
Global Anti- Money Laundering Solutions Market
Regulatory Compliance Technology
Anti-Money Laundering Systems Market
Regulatory Compliance Technology
General Data Protection Regulation (GDPR) Market
Regulatory Compliance Technology
Global AML Software Market
Regulatory Compliance Technology
Cross-Border Customs and Trade Compliance Orchestration Platforms Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
Compliance Testing Solutions Market