
 Regulatory Information Management System Market | 2026-2036
Regulatory Information Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Regulatory Information Management System Market Intelligence
Software development capacity in Ireland and Germany is hardening as European vendors build specialized regulatory compliance modules. Veeva Systems leverages its cloud-native architecture to sustain dominance in life sciences customer bases. MasterControl anchors its position through deep functionality for quality management integration. ArisGlobal competes aggressively on AI-driven regulatory intelligence and submission automation tools.
A Regulatory Information Management System constitutes an enterprise software platform that centralizes dossier compilation, tracks submission status across health authorities, and maintains audit trails with version-controlled document repositories. These systems serve the primary commercial purpose of accelerating product approvals while ensuring compliance with evolving health authority standards. Cloud-based deployments now lead technology adoption as pharmaceutical and biotechnology end users prioritize scalable infrastructure and remote collaboration capabilities. Consulting and implementation services capture concentrated margin pools given the complexity of migrating from fragmented legacy systems.
FDA 21 CFR Part 11 electronic records requirements and EMA eCTD submission mandates shape product specifications and create non-negotiable compliance barriers for market entry. The EU AI Act and evolving MDR documentation standards in Europe are forcing platform vendors to embed algorithmic transparency and enhanced clinical evidence tracking. Stakeholders must monitor how health authority digitization initiatives reshape interoperability demands and subscription pricing models.
Market Dynamics
Cloud-native architectures are displacing on-premise document repositories as pharmaceutical manufacturers face compressed FDA and EMA submission timelines. Health authority digitization mandates force simultaneous upgrades across quality, regulatory, and clinical data systems.
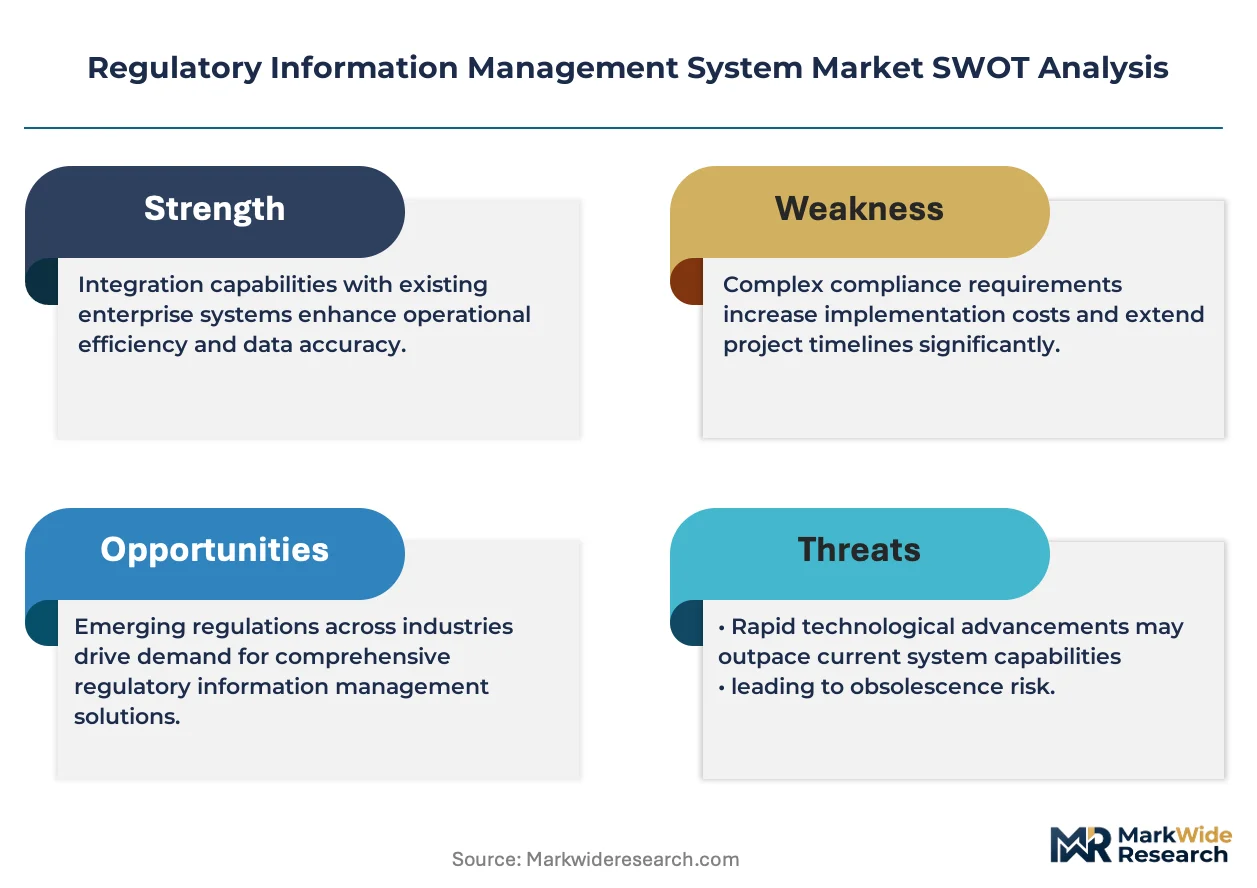
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates compel pharmaceutical manufacturers to replace paper-based dossier systems with validated digital platforms. Compliance deadlines accelerate procurement cycles.
- EMA eCTD 4.0:The European Medicines Agency's updated electronic Common Technical Document standard requires enhanced metadata management and lifecycle tracking capabilities.
- Biologics pipeline expansion:Cell and gene therapy developers in Boston, Basel, and Singapore require specialized regulatory submission tools for novel therapeutic modalities.
Market Restraints
- Implementation cost structure:Enterprise deployment of validated regulatory systems demands 18-24 month timelines with specialized validation documentation and IQ/OQ/PQ protocols.
- Specialized talent scarcity:The intersection of pharmaceutical regulatory science and enterprise software architecture concentrates qualified implementation partners in Cambridge, Massachusetts and Basel.
- Legacy system entrenchment:Documentum and SharePoint installations from the 2010s create data migration friction and sunk-cost resistance among established manufacturers.
Strategic Opportunities
- EU AI Act compliance modules:Algorithmic transparency requirements for AI-enabled drug discovery create demand for embedded audit trails and explainability documentation.
- India CDSCO expansion:Domestic pharmaceutical manufacturers scaling export operations require submission-ready dossier compilation aligned with ICH guidelines.
- API-first architectures:Open integration frameworks enable connection between regulatory systems and electronic lab notebooks, compressing data transfer latency.
Industry Challenges
- Validation documentation burden:Computer system validation for FDA-regulated environments requires specialized personnel and extends deployment timelines.
- Interoperability fragmentation:Health authority portals lack standardized APIs, forcing vendors to maintain multiple submission gateway connectors.
- Change control complexity:SaaS update cycles conflict with pharmaceutical quality management requirements for controlled system modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regulatory Information Management System Market |
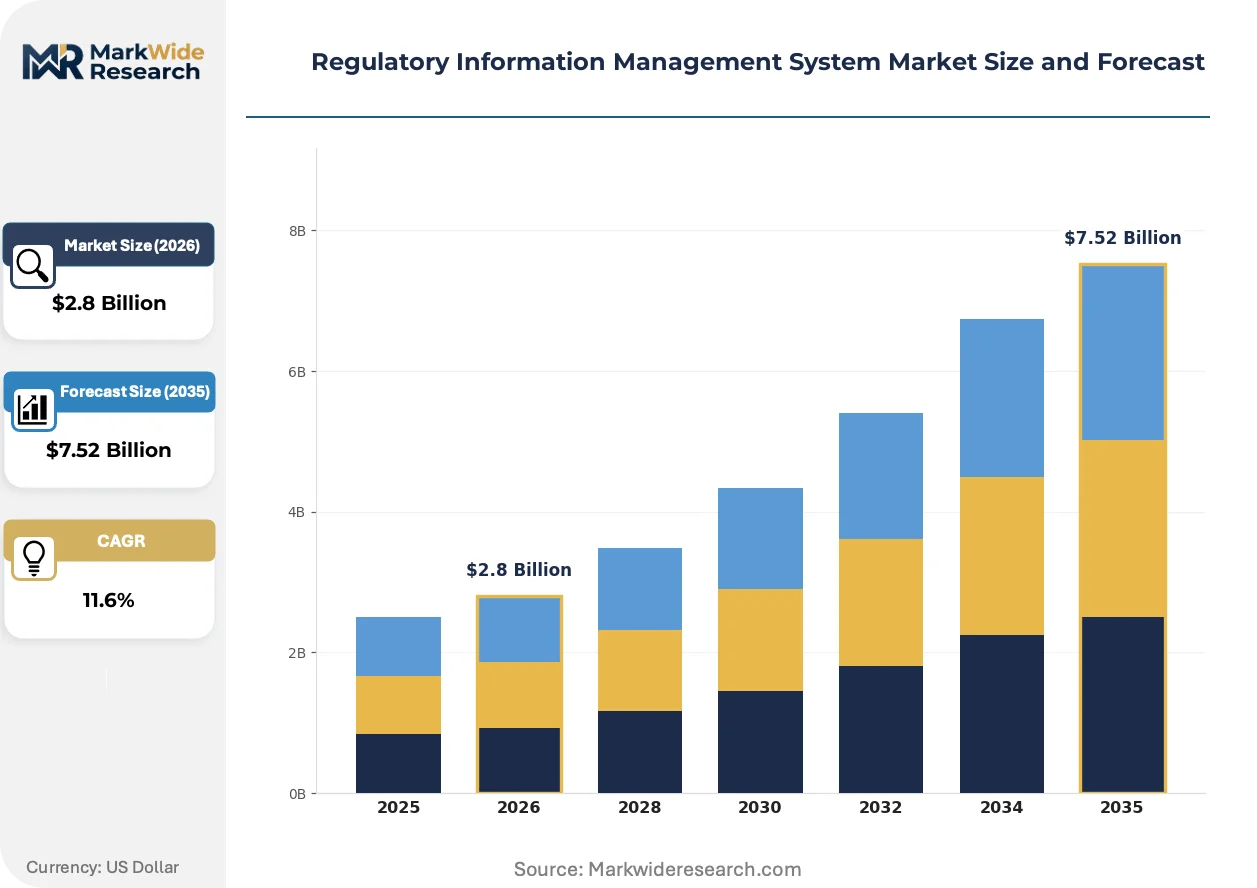
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud-Based, On-Premise, Hybrid, SaaS End User: Pharmaceuticals, Biotechnology, Medical Devices, Food & Beverage Deployment: Private Cloud, Public Cloud, Community Cloud, On-Site Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | Kalypso, MasterControl, Veeva Systems, ArisGlobal, Rimsys, DDi, Ennov, Körber AG, LORENZ Life Sciences Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regulatory Information Management System Market Strategic Shifts & Innovations
Artificial intelligence is penetrating regulatory intelligence workflows, automating precedent analysis and submission strategy optimization. Platform vendors compete on inference speed and training data breadth.
Generative AI is expanding into regulatory writing automation, drafting module summaries and response-to-questions documents from structured trial data. Mid-size biotechnology companies adopt these tools fastest to compensate for limited regulatory affairs headcount. The technology is compressing submission preparation timelines from months to weeks for standard documentation.
EMA's Clinical Trial Information System (CTIS) mandates force centralized portal submission for all EU trials, eliminating national competent authority paper pathways. Sponsors must reconfigure internal workflows around the system's structured data requirements. Small-to-mid enterprises in Germany and the Netherlands struggle most with the transition, driving demand for managed service overlays.
Buying committees now unbundle software licenses from implementation services, negotiating separate statements of work for validation and change management. Large pharmaceutical procurement functions treat regulatory platforms as commodity infrastructure, pressuring vendors on subscription pricing. This pattern is most visible among top-twenty manufacturers headquartered in the United States and Switzerland.
Regulatory Information Management System Market Segmentation
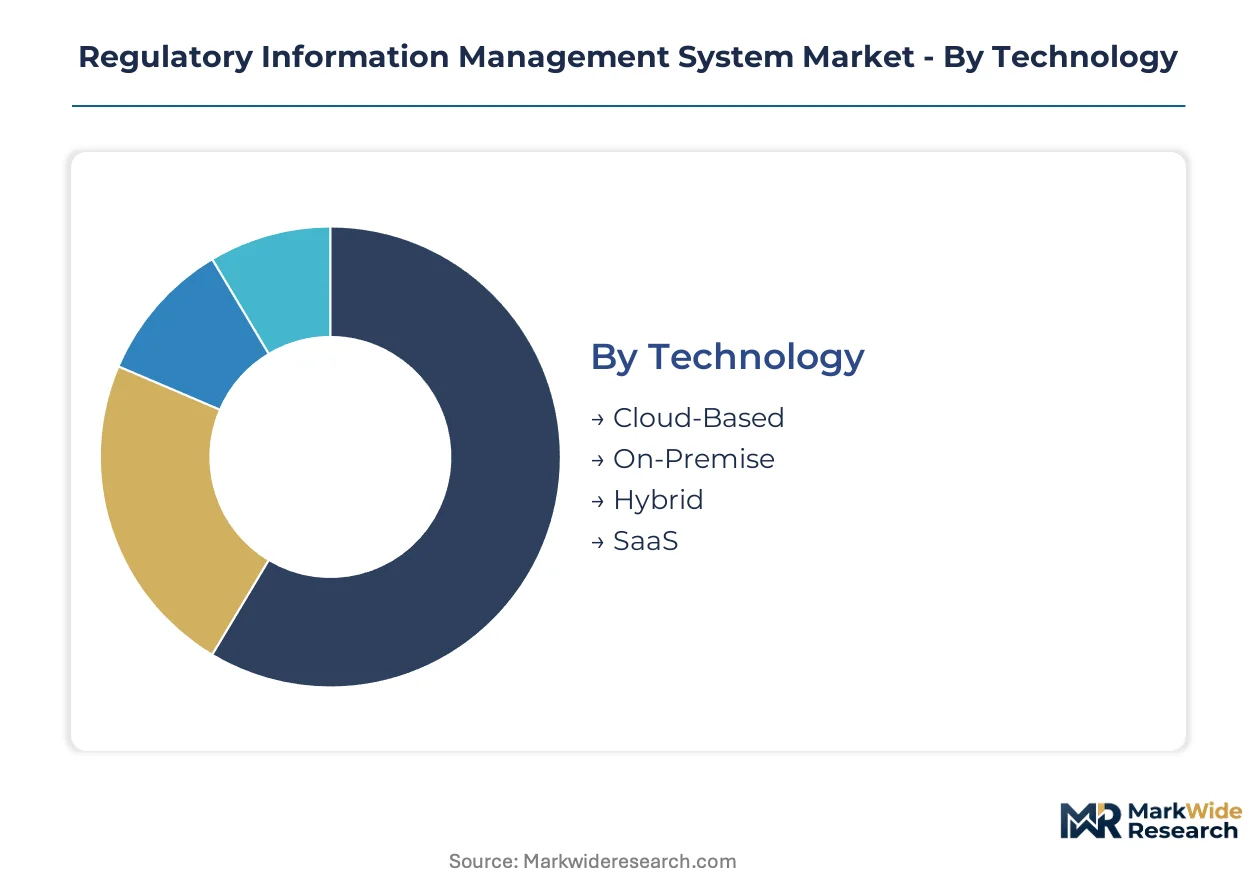
Regulatory Information Management System procurement decisions hinge on validation complexity, cloud maturity, and health authority submission pressures. Segmentation reveals how vendor offerings align with distinct buyer risk profiles and operational constraints across the pharmaceutical value chain.
Technology:
Deployment architecture drives total cost of ownership calculations and validation burden for FDA 21 CFR Part 11 compliance.
- Cloud-Based:Multi-tenant infrastructure with automated scaling handles EMA eCTD 4.0 metadata requirements without capacity planning. Pharmaceutical manufacturers in Germany and Switzerland prioritize these platforms for distributed team collaboration across Basel and Munich research clusters.
- SaaS:Subscription delivery eliminates infrastructure capital expenditure while embedding compliance updates. Boston and San Francisco biotech startups adopt fastest to preserve runway capital for clinical trials.
- On-Premise:Air-gapped installations serve manufacturers with stringent data sovereignty requirements.
- Hybrid:Mixed deployments bridge legacy document repositories with cloud-native submission tools.
Cloud-Based leads on scale; SaaS leads on momentum.
End User:
Therapeutic category determines submission complexity, dossier volume, and health authority interaction frequency.
- Pharmaceuticals:Small-molecule developers generate the highest dossier throughput with standardized eCTD modules. United States and Japan manufacturers drive replacement cycles as FDA and PMDA accelerate electronic submission mandates.
- Biotechnology:Cell and gene therapy developers require specialized tools for novel therapeutic modalities. Cambridge, Massachusetts and Basel clusters concentrate demand for adaptive pathway submission support.
- Medical Devices:EU MDR technical documentation requirements force platform upgrades for European manufacturers.
- Food & Beverage:FSSAI and FDA food facility registration workflows demand lighter regulatory intelligence modules.
Pharmaceuticals dominates absolute spend; Biotechnology climbs the fastest.
Deployment:
Infrastructure control preferences segment buyers by data sensitivity tolerance and IT governance maturity.
- Private Cloud:Dedicated tenant isolation satisfies EMA and FDA audit requirements for qualified infrastructure. Large pharmaceutical procurement functions in Switzerland and the United States mandate this architecture for IND and NDA submissions.
- Public Cloud:Shared infrastructure delivers lowest unit economics for mid-size biotechnology companies. Singapore and Netherlands sponsors leverage these deployments for CTIS trial submissions.
- Community Cloud:Industry-specific platforms serve consortium arrangements and CRO shared-service models.
- On-Site:Physical hardware installations persist where national data localization laws apply.
Private Cloud commands premium pricing; Public Cloud expands most quickly.
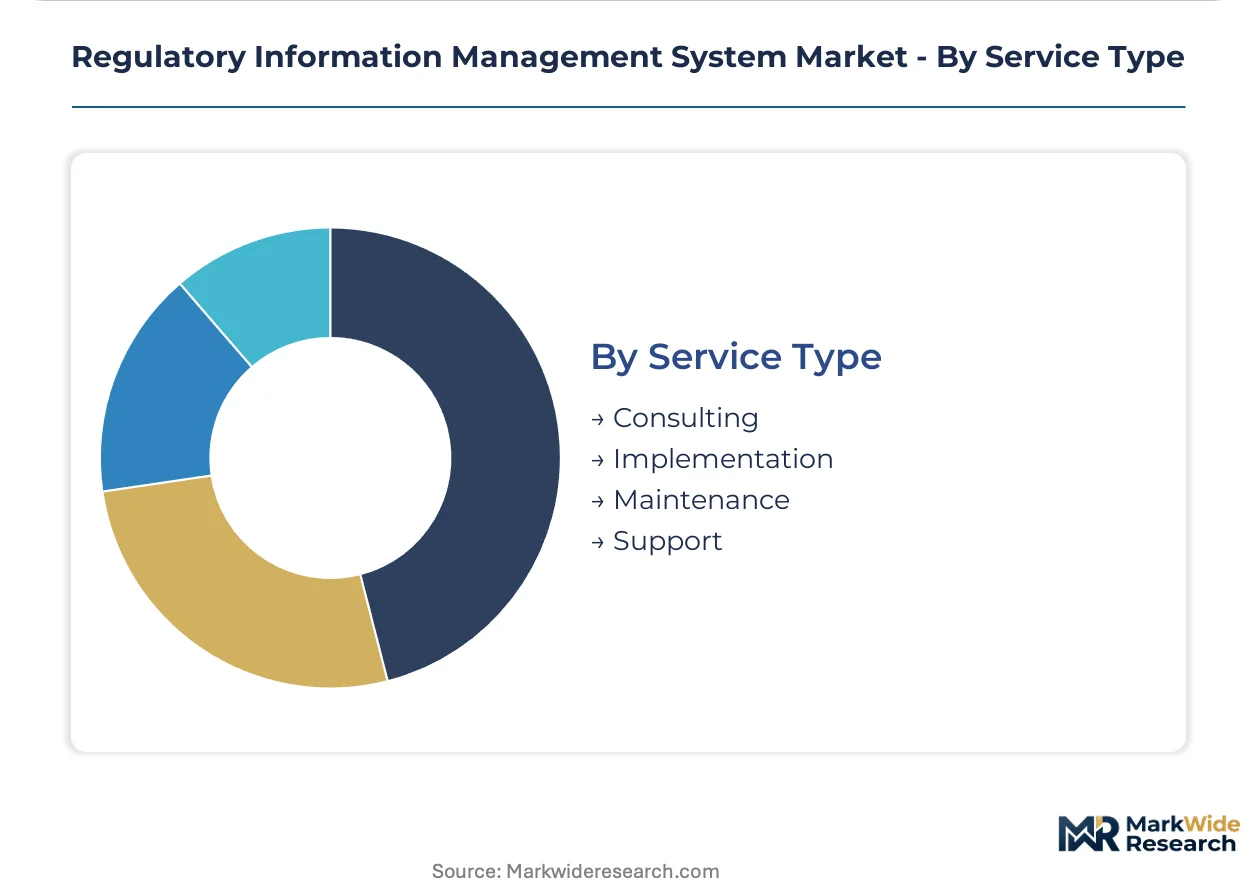
Service Type:
Professional services capture margin concentration where validation expertise and change management capabilities differentiate vendors.
- Implementation:IQ/OQ/PQ protocol execution and legacy migration demand 18-24 month specialized engagements. Cambridge and Basel implementation partners command premium rates for FDA-validated deployments.
- Consulting:Regulatory strategy and health authority negotiation support align platform configuration with submission pathways. Germany and Japan manufacturers procure these services for complex multi-market dossier coordination.
- Maintenance:Sustained engineering and patch management ensure continuous compliance.
- Support:Help desk and user training services reduce internal regulatory affairs overhead.
Implementation generates highest per-contract value; Consulting shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers migrate regulatory operations toward jurisdictions with streamlined health authority digitization, compressing cost-of-compliance gaps between established and emerging markets. Cloud infrastructure investments in Germany, Singapore, and Switzerland attract sponsors seeking qualified validation environments. FDA and EMA submission mandates synchronize procurement cycles across North America and Europe.
United States
FDA 21 CFR Part 11 electronic records mandates drive replacement of legacy document repositories among Boston and San Francisco biotech clusters. The agency's accelerated approval pathways for cell and gene therapies concentrate specialized RIM demand in Cambridge, Massachusetts. Veeva Systems anchors its cloud-native position through life sciences customer bases concentrated in these research corridors.
Germany
EMA eCTD 4.0 metadata requirements and EU MDR technical documentation standards compel platform upgrades across Baden-Württemberg and Bavaria pharmaceutical manufacturing. The country's national pharmaceutical regulator enforces structured data submissions through CTIS integration deadlines. Basel-adjacent sponsors in Freiburg and Munich procurement functions prioritize private cloud deployments for qualified infrastructure.
Japan
PMDA electronic submission mandates and Sakigake fast-track designations accelerate RIM adoption among Tokyo and Osaka pharmaceutical headquarters. The regulator's harmonization with ICH E2B(R3) standards forces metadata management upgrades. Yokohama and Kobe biologics manufacturing clusters contract specialized implementation partners for IQ/OQ/PQ validation protocols.
India
CDSCO expansion of ICH-aligned submission requirements drives domestic pharmaceutical manufacturers toward export-ready dossier compilation tools. The regulator's digitization of manufacturing license renewals creates compliance urgency in Hyderabad and Ahmedabad generic drug clusters. Mumbai and Bangalore sponsors leverage SaaS deployments to preserve capital for ANDA filing pipelines.
Switzerland
Swissmedic alignment with EMA centralized procedures and FDA mutual recognition agreements positions Basel and Zurich as regulatory strategy hubs. The country's data sovereignty requirements sustain demand for private cloud and hybrid deployments among large pharmaceutical procurement functions. Geneva and Lausanne biotech startups adopt API-first architectures for electronic lab notebook integration.
Regulatory Information Management System Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue AI-driven regulatory intelligence and submission automation niches. The vendor base concentrates among cloud-native specialists with validated life sciences infrastructure and legacy quality management integrators. Three archetypes dominate: vertically integrated platform vendors, modular point-solution specialists, and CRO-affiliated managed service providers. M&A activity targets AI capabilities and regional implementation capacity; strategic partnerships bridge electronic lab notebook and clinical data integration gaps.
Within the cloud-native tier, Veeva Systems and ArisGlobal exemplify divergent specialization strategies. Veeva leverages multi-tenant architecture dominance across United States and European pharmaceutical customer bases. ArisGlobal occupies a position anchored on AI-driven regulatory intelligence tools. MasterControl represents the quality management integration archetype, embedding deep functionality for FDA-validated environments. Körber AG and LORENZ Life Sciences Group sit within the European vendor cluster, serving EMA-centric submission workflows.
| Leading Market Players |
|---|
| Kalypso |
| MasterControl |
| Veeva Systems |
| ArisGlobal |
| Rimsys |
| DDi |
| Ennov |
| Körber AG |
| LORENZ Life Sciences Group |
| Others |
Cost & Logistics Intelligence
Cloud-native platform migration simultaneously compresses infrastructure capital requirements and concentrates vendor pricing power among validated infrastructure providers in Switzerland and Germany. FDA 21 CFR Part 11 compliance mandates create non-negotiable cost barriers that filter out undifferentiated SaaS entrants, leaving established players with embedded validation documentation libraries to command subscription premiums.
Pricing Analysis
Direct-to-enterprise sales channels bypass distributor markups for top-twenty pharmaceutical manufacturers, while mid-size biotechnology companies absorb 15-25% implementation partner margins for IQ/OQ/PQ validation support. Three-tier pricing structure across premium private cloud, standard multi-tenant SaaS, and economy public cloud tiers separates Basel-based large pharma procurement from Boston startup adopters. Pricing pressure stems from procurement functions treating regulatory platforms as commodity infrastructure, pressuring vendors on subscription renewals. Mid-size biotechnology sponsors show highest price sensitivity due to runway capital constraints, while Swiss and US large pharma demonstrate lowest sensitivity given compliance risk exposure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through dedicated customer success teams in Cambridge and Basel, while implementation partners in Germany and Ireland serve mid-market deployments. Software development capacity concentrates in Germany, Ireland, and Switzerland where regulatory compliance module specialization hardens. Cloud infrastructure draws from AWS, Azure, and Google Cloud qualified environments, with validation documentation libraries and AI training datasets as critical inputs. Single-source vulnerability sits with specialized implementation partners in Cambridge and Basel where regulatory science and enterprise architecture talent intersect. Distribution runs through vendor direct sales for large accounts and certified implementation partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on automated compliance update delivery reducing customer acquisition costs, while premium-tier private cloud deployments capture infrastructure sovereignty premiums from Swiss and US large pharma procurement functions.
For Market Incumbents: Hedge against AI-native entrants by embedding generative regulatory writing tools before mid-size biotechnology adoption accelerates. Acquire specialized implementation capacity in India and Singapore to capture CDSCO and regional health authority digitization cycles. Vertical integration into electronic lab notebook APIs compresses data transfer latency and locks in platform stickiness. For New Entrants and Emerging Players: Launch via API-first architectures targeting Geneva and Lausanne biotech startups seeking electronic lab notebook integration without legacy migration burden. Target India CDSCO-aligned submission tools where domestic generic manufacturers face export compliance urgency with limited regulatory affairs headcount. White-space opportunity sits in AI-driven precedent analysis for cell and gene therapy adaptive pathways. For Investors and Strategic Acquirers: Roll-up economics work for regional implementation specialists because validation expertise concentrates geographically and health authority digitization mandates synchronize procurement cycles across jurisdictions. Five-to-ten year viability favors vendors with embedded FDA and EMA compliance documentation libraries. Signal to watch is EMA CTIS mandate enforcement driving managed service overlay demand among German and Dutch small-to-mid enterprises.| Strategic Initiative | Industry Significance |
|---|---|
| AI Regulatory Writing Module Launch | Generative tools compress Boston biotech submission timelines from months to weeks. |
| CDSCO Compliance Certification | Hyderabad generic manufacturers gain export-ready dossier compilation for ANDA pipelines. |
| Private Cloud Infrastructure Expansion | Swiss data sovereignty requirements sustain premium pricing from Basel procurement functions. |
| Electronic Lab Notebook API Integration | Lausanne startups reduce data transfer latency through open architecture connectivity. |
| Implementation Partner Acquisition | Cambridge and Basel talent scarcity creates captive capacity for IQ/OQ/PQ validation demand. |
Research Approach
Direct dialogue with regulatory affairs directors, pharmaceutical procurement executives, cloud platform engineers, and implementation partners in Cambridge, Basel, and Munich grounded qualitative findings. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA eCTD 4.0 specifications, CDSCO circulars, and clinical trial submission databases. Bottom-up and top-down triangulation cross-checked vendor revenue estimates against health authority submission volume proxies and enterprise software spending patterns.
Bottom-up modeling aggregated segment-level adoption curves across cloud deployment modes, therapeutic categories, and service type attachments, while top-down analysis anchored total addressable market to pharmaceutical R&D expenditure and regulatory compliance cost benchmarks. CAGRs derived from health authority mandate timelines, replacement cycle assumptions for legacy Documentum and SharePoint installations, and biologics pipeline expansion rates. Forecast inputs included FDA accelerated approval pathway designations and EMA CTIS integration deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under delayed health authority digitization timelines or accelerated AI regulatory writing adoption compressing services attach rates. Outputs reflect documented assumptions around compliance deadline enforcement and cloud migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
Regtech Software Market
Regulatory Compliance Technology
US Anti Money Laundering Solution Market
Regulatory Compliance Technology
Management System Certification Market
Regulatory Compliance Technology
General Data Protection Regulation (GDPR) Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
Global Anti- Money Laundering Solutions Market
Regulatory Compliance Technology
Compliance and Traceability Solutions Market
Regulatory Compliance Technology
Global GDPR Services Market
Regulatory Compliance Technology
United States Sales Tax Compliance Software Market
Regulatory Compliance Technology
Cross-Border Customs and Trade Compliance Orchestration Platforms Market
Regulatory Compliance Technology
Aviation Compliance Monitoring Software Market
Regulatory Compliance Technology
Anti-Money Laundering Systems Market
Regulatory Compliance Technology
GDPR Assessment Tools Market
Regulatory Compliance Technology
Nordic Regulatory Affairs Market
Regulatory Compliance Technology
Regulatory Reporting Solutions Market
Regulatory Compliance Technology
Compliance Testing Solutions Market