
 Compliance and Traceability Solutions Market | 2026-2036
Compliance and Traceability Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Compliance and Traceability Solutions Market Analysis
Project finance and subscription-based SaaS licensing is narrowing the competitive field for mid-tier compliance vendors. SAP SE leverages its embedded ERP footprint to anchor traceability modules within existing enterprise workflows. TraceLink, Inc. specializes in pharmaceutical network compliance, sustaining dominance through pre-validated regulatory content libraries.
Compliance and traceability solutions encompass hardware-software systems that capture, store, and transmit product lifecycle data across distributed supply chains, typically integrating barcode scanners, RFID readers, and blockchain-anchored verification nodes to authenticate origin, custody, and condition. These systems serve industrial and commercial purposes by enabling real-time recall management, counterfeit detection, and regulatory audit readiness. Blockchain deployments within the technology segment are attracting capital due to immutable ledger architectures that reduce reconciliation costs across multi-party networks. The pharmaceuticals industry vertical commands premium pricing because serialization mandates in major jurisdictions create non-discretionary procurement cycles with compressed implementation timelines.
The FDA DSCSA, EU FMD, and China's NMPA serialization requirements are collectively elevating baseline software functionality toward interoperable data exchange standards that transcend national boundaries. EMA's guidance on audit trail integrity and WHO prequalification protocols further harden technical specifications for vendors seeking multi-jurisdictional deployment. Stakeholders must evaluate whether their current infrastructure can absorb emerging requirements for artificial intelligence-driven anomaly detection without triggering costly platform replacements.
Market Dynamics
Serialization mandates from the FDA DSCSA and EU FMD are forcing pharmaceutical manufacturers to replace fragmented point solutions with interoperable cloud-native platforms, compressing vendor consolidation timelines and elevating data-exchange standards as the primary competitive battleground.
Growth Catalysts
- EU FMD serialization deadlines:European pharmaceutical distributors must deploy unit-level traceability by statutory milestones, creating non-discretionary procurement cycles for verification systems.
- Blockchain ledger architectures:Immutable record-keeping is collapsing reconciliation costs across multi-party supply networks, attracting capital from enterprises managing complex custody chains.
- India's pharmaceutical exports:Indian generic manufacturers expanding into regulated markets are investing in compliance infrastructure to meet WHO prequalification and EU import requirements.
Market Restraints
- Cloud infrastructure concentration:Reliance on hyperscale providers for traceability platforms creates single-point vulnerabilities and vendor lock-in risks for mid-tier pharmaceutical firms.
- Legacy ERP integration costs:Brownfield deployments require expensive middleware development to connect serialization hardware with decades-old enterprise resource planning systems.
- Silicon component lead times:RFID inlays and specialized scanning hardware face extended procurement cycles due to semiconductor fabrication capacity constraints in East Asia.
Strategic Opportunities
- Brazil's ANVISA track-and-trace mandate:Latin America's largest pharmaceutical market is implementing serialization requirements, opening whitespace for vendors with Portuguese-language regulatory content libraries.
- AI-driven anomaly detection:Machine learning algorithms applied to serialization data streams enable predictive counterfeit identification before products reach dispensaries.
- Subscription-based verification networks:Network-effect platforms that connect manufacturers, distributors, and dispensaries on shared infrastructure are displacing bilateral point-to-point integrations.
Industry Challenges
- Pharmaceutical data steward shortage:Enterprises struggle to hire personnel fluent in both serialization technical standards and jurisdictional reporting requirements.
- Multi-jurisdictional audit trail harmonization:Reconciling FDA DSCSA, EU FMD, and China's NMPA data formats demands expensive platform customization for global manufacturers.
- Blockchain throughput limitations:Public ledger architectures face transaction speed constraints when processing high-volume pharmaceutical serialization events at manufacturing line speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compliance and Traceability Solutions Market |
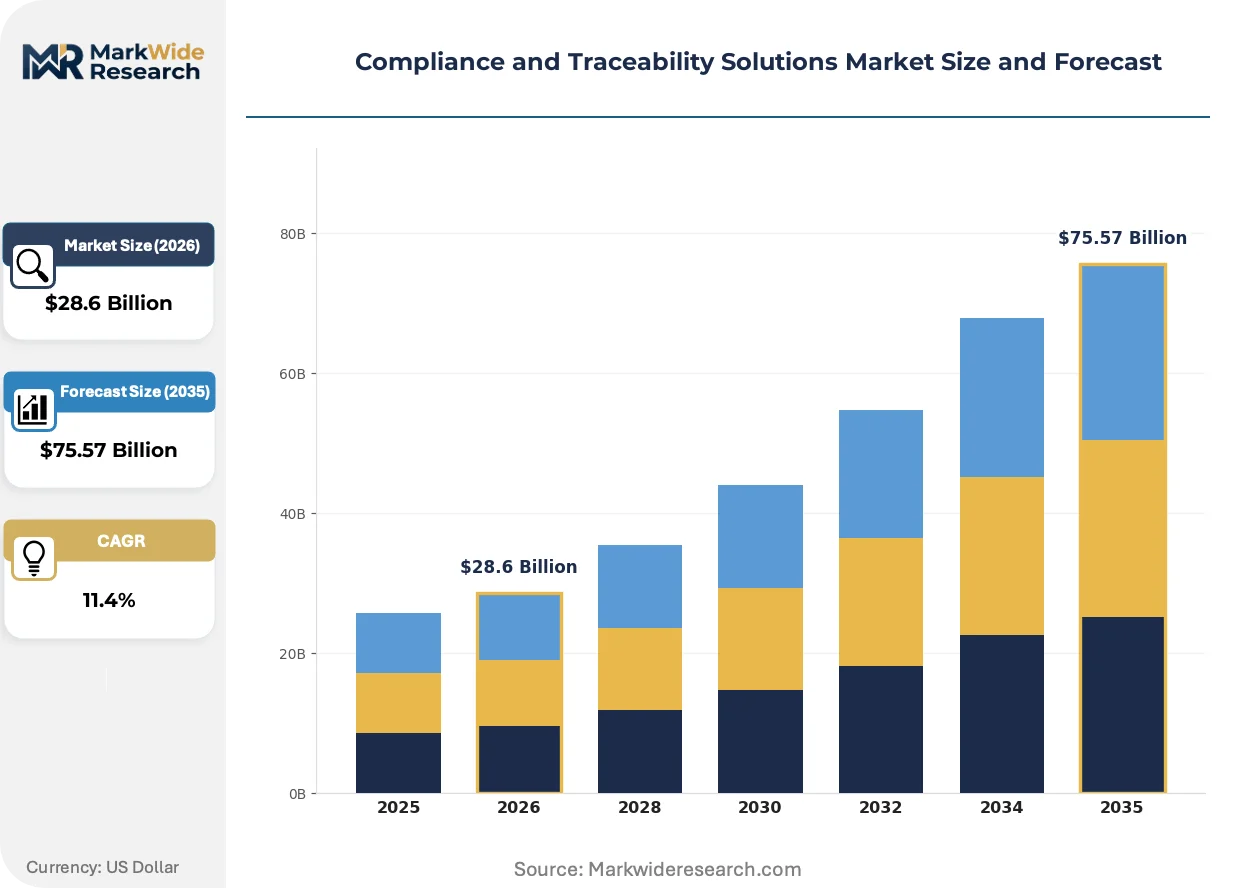
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blockchain, RFID, Barcoding, QR Codes Application: Supply Chain Management, Quality Assurance, Regulatory Compliance, Audit Trails Industry: Pharmaceuticals, Food & Beverage, Manufacturing, Retail End User: Manufacturers, Distributors, Regulators, Consumers |
| Companies Covered | SAP SE, TraceLink, Inc., Optel Group, Tata Consultancy Services, IBM Corporation, Microsoft Corporation, Oracle Corporation, Mettler-Toledo, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compliance and Traceability Solutions Market Emerging Trajectories
Distributed ledger architectures and artificial intelligence inference engines are converging to transform traceability from reactive compliance documentation into proactive supply chain intelligence, compressing the value capture window for traditional software vendors.
Blockchain-anchored verification nodes are collapsing trust establishment costs between pharmaceutical trading partners previously requiring bilateral legal agreements and manual reconciliation. Large molecule manufacturers and cold chain distributors are deploying these networks fastest. The technology is collapsing the traditional three-month partner onboarding cycle into same-day cryptographic credential issuance.
The EU AI Act's risk classification framework is imposing algorithmic audit requirements on automated compliance systems used for pharmaceutical quality verification. Industrial consequence includes mandatory documentation of training data provenance and decision explainability for serialization anomaly detection. European contract manufacturers are responding by embedding regulatory technology modules directly into manufacturing execution systems rather than maintaining separate compliance layers.
Buyer concentration among the top twenty global pharmaceutical distributors is compressing vendor evaluation cycles and demanding outcome-based pricing tied to regulatory inspection outcomes rather than software seat licenses. Regional wholesalers and independent pharmacies are being displaced from direct procurement relationships as enterprise buyers centralize traceability spending. This concentration is most visible in the United States, where the three largest drug distributors account for over ninety percent of serialized product volume.
Compliance and Traceability Solutions Market Segmentation
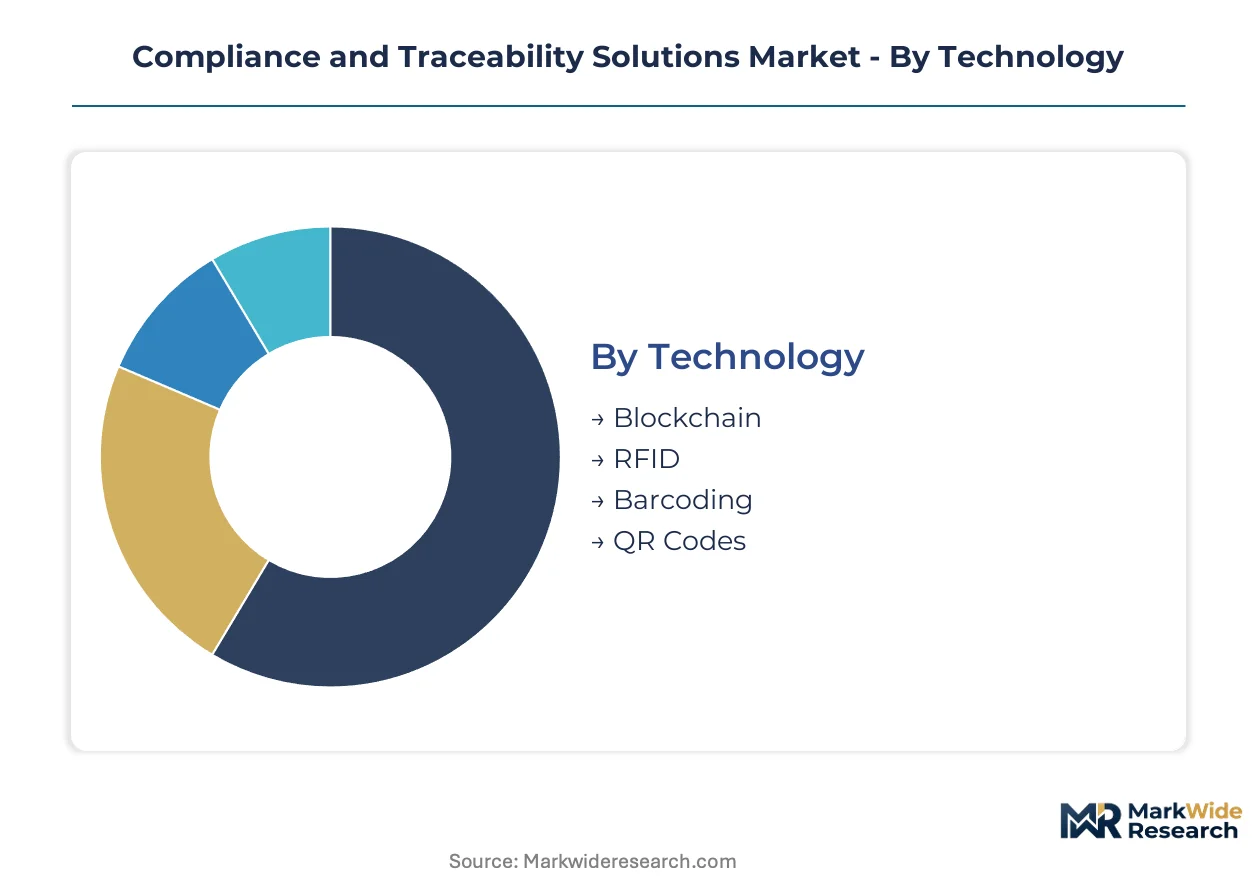
Segmentation in compliance and traceability solutions reveals distinct procurement patterns across technology maturity levels and regulatory exposure. Pharmaceutical manufacturers prioritize serialization hardware with embedded validation documentation, while food distributors emphasize cloud-native verification networks with lower capital thresholds.
Technology:
After-sales-service intensity varies sharply across technology categories, with blockchain deployments demanding continuous cryptographic key management and distributed node maintenance that extends vendor relationships far beyond initial installation.
- Blockchain:Distributed ledger architectures anchor immutable custody records across multi-party pharmaceutical networks. Demand concentrates among large molecule manufacturers in the United States and European Union facing FDA DSCSA and EU FMD reconciliation mandates. The technology collapses three-month partner onboarding cycles through cryptographic credential automation.
- RFID:Ultra-high-frequency inlays and specialized readers capture unit-level product data at line speeds exceeding barcode throughput. Pharmaceutical distributors in Germany and Switzerland deploy RFID for cold chain verification where temperature excursion logging must survive physical label degradation.
- Barcoding:Linear and 2D symbologies remain the baseline infrastructure for cost-constrained generic manufacturers.
- QR Codes:Matrix barcodes enable consumer-facing authentication applications with smartphone-readable provenance data.
Barcoding holds the largest share; momentum sits with blockchain.
Application:
Cost tier stratification separates enterprise-grade regulatory compliance suites from mid-market audit trail modules, with pricing spreading across premium validation-heavy deployments and economy SaaS subscriptions.
- Supply Chain Management:End-to-end visibility platforms integrate serialization events from active pharmaceutical ingredient sourcing through dispensary dispensing. Indian generic manufacturers expanding into regulated markets invest here to meet WHO prequalification requirements for EU export eligibility.
- Quality Assurance:Automated deviation detection systems apply machine learning to batch record anomalies. European contract manufacturers embed these modules directly into manufacturing execution systems to satisfy EU AI Act algorithmic audit requirements.
- Regulatory Compliance:Pre-validated content libraries address jurisdiction-specific reporting formats.
- Audit Trails:Immutable logging systems satisfy EMA guidance on data integrity for electronic records.
Supply chain management commands premium pricing; audit trails are expanding most quickly as enforcement tightens.
Industry:
Customer type differentiation separates multinational pharmaceutical conglomerates with dedicated compliance infrastructure from regional food distributors relying on third-party verification services.
- Pharmaceuticals:Serialization mandates create non-discretionary procurement cycles with compressed implementation timelines. FDA DSCSA and EU FMD deadlines force replacement of fragmented point solutions with interoperable cloud-native platforms.
- Food & Beverage:Track-and-trace requirements for high-risk categories drive investment in farm-to-fork visibility. French and Italian specialty producers deploy blockchain-anchored origin verification to defend premium positioning against fraudulent substitution.
- Manufacturing:Industrial asset lifecycle tracking extends beyond regulatory minimums to warranty management.
- Retail:Consumer authentication applications leverage QR code readability for counterfeit protection in luxury goods.
Pharmaceuticals dominates revenue concentration; food and beverage shows the steepest expansion trajectory as EU deforestation regulations extend traceability obligations.
End User:
Volume concentration among the three largest United States drug distributors compresses vendor evaluation cycles and demands outcome-based pricing tied to regulatory inspection outcomes.
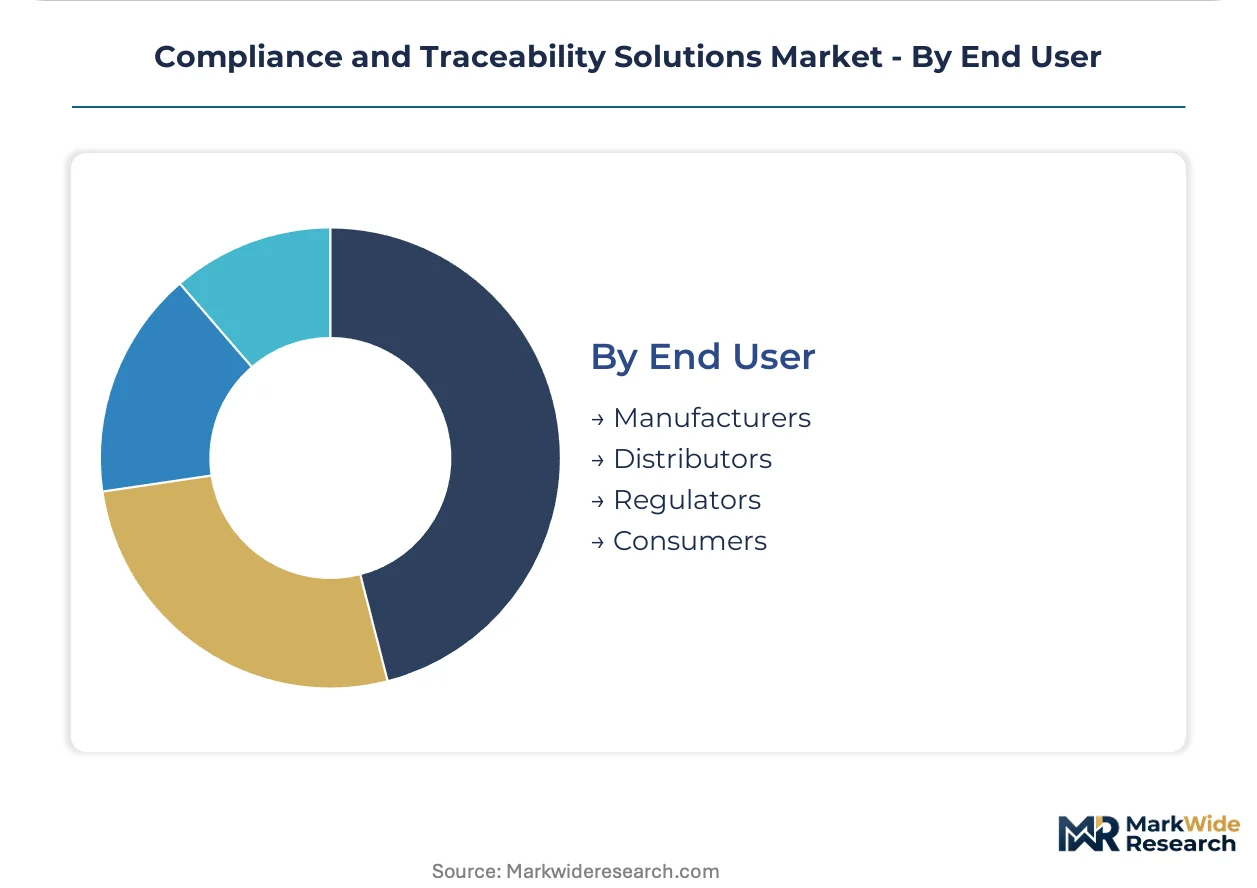
- Manufacturers:Primary responsibility for serialization encoding at production line speeds. Brazilian and Mexican pharmaceutical producers prepare for ANVISA track-and-trace mandates with Portuguese and Spanish regulatory content libraries.
- Distributors:Verification router requirements under FDA DSCSA compel wholesale infrastructure upgrades. United States distributors account for over ninety percent of serialized product volume, centralizing procurement decisions.
- Regulators:National agencies specify data exchange formats and conduct inspection readiness validation.
- Consumers:Smartphone-based product authentication represents the terminal verification node.
Manufacturers hold the largest share; distributors are gaining share fastest as verification network effects consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented pharmaceutical manufacturers drive traceability investment in jurisdictions with stringent import verification requirements. Countries with dominant generic drug production bases face acute compliance pressure as destination markets harden serialization standards. Import-dependent markets concentrate procurement authority among wholesale distributors with centralized verification infrastructure.
United States
The three largest drug distributors process over ninety percent of serialized pharmaceutical volume, compressing vendor evaluation timelines and demanding outcome-based pricing tied to FDA inspection readiness. DSCSA verification router requirements compel wholesale infrastructure upgrades ahead of full unit-level traceability enforcement. New Jersey and Pennsylvania host dense clusters of contract manufacturers embedding regulatory technology modules directly into manufacturing execution systems.
Germany
Pharmaceutical distributors in Bavaria and North Rhine-Westphalia deploy RFID-enabled cold chain verification where temperature excursion logging must survive physical label degradation. EU FMD serialization deadlines create non-discretionary procurement cycles for verification systems across wholesale operations. EMA guidance on audit trail integrity hardens technical specifications for multi-jurisdictional deployment from German manufacturing hubs.
India
Generic manufacturers in Gujarat and Maharashtra expand compliance infrastructure to meet WHO prequalification requirements for EU and US export eligibility. CDSCO alignment with international serialization standards accelerates domestic capability building among contract research and manufacturing organizations. Hyderabad and Bangalore clusters attract investment in cloud-native verification platforms serving regulated market access.
Switzerland
Large molecule manufacturers in Basel and Zurich deploy blockchain-anchored verification networks fastest, collapsing three-month partner onboarding cycles through cryptographic credential automation. Swissmedic technical specifications for biological product traceability exceed baseline EU FMD requirements, elevating platform functionality demands. The country's pharmaceutical trading hub status concentrates multi-jurisdictional data harmonization expertise.
Brazil
ANVISA track-and-trace mandate implementation opens whitespace for vendors with Portuguese-language regulatory content libraries. São Paulo and Rio de Janeiro pharmaceutical producers prepare serialization encoding capacity for statutory deadlines on unit-level verification. Import substitution policies favor local system integrators capable of bridging global platform architectures with national reporting formats.
Compliance and Traceability Solutions Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying hardware modules and validation documentation. The vendor base separates into three strategic archetypes: ERP-anchored suites leveraging embedded enterprise footprints, network-centric compliance platforms sustaining dominance through pre-validated regulatory content, and precision hardware manufacturers integrating serialization encoding with line-speed automation. Consolidation pressure intensifies as pharmaceutical buyers replace fragmented point solutions with interoperable cloud-native architectures. Vertical integration moves and strategic technology licensing agreements reshape competitive boundaries between software and hardware domains.
Within the ERP-anchored tier, SAP SE exemplifies platform consolidation through embedded traceability modules. TraceLink, Inc. occupies a position representing network-effect specialization in pharmaceutical compliance. Among precision hardware fabricators, Mettler-Toledo and Omron Corporation sit within the automation-integrated archetype, supplying encoding systems for manufacturing line deployment. IBM Corporation and Microsoft Corporation anchor cloud infrastructure supply for verification networks. These named entities illustrate structural positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| SAP SE |
| TraceLink, Inc. |
| Optel Group |
| Tata Consultancy Services |
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| Mettler-Toledo |
| Omron Corporation |
| Others |
Supply Flow & Price Mechanics
East Asian semiconductor fabrication capacity for RFID inlays and specialized scanning hardware concentrates upstream leverage, pushing margin pools downstream toward cloud-native platform orchestrators and regulatory content specialists who control multi-jurisdictional deployment timelines.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS licensing as the dominant pricing structure across compliance and traceability solutions. Three-tier pricing structure across premium validation-heavy, standard interoperable, and economy modular tiers separates pharmaceutical manufacturers with compressed FDA DSCSA deadlines from mid-tier generic producers with extended implementation windows. Pricing pressure stems from buyer concentration among the three largest United States drug distributors demanding outcome-based contracts tied to inspection readiness rather than seat licenses. Mid-tier pharmaceutical firms exhibit highest price sensitivity due to legacy ERP integration cost burdens, while large molecule manufacturers in Switzerland and Germany show lowest sensitivity given non-discretionary procurement cycles.
Supply Chain Analysis
Upstream feedstock for serialization hardware draws from Taiwan, South Korea, and Japan for semiconductor components, with Germany and Switzerland contributing precision automation systems. Specialized RFID inlays, cryptographic processors, and line-speed encoding modules rest on silicon wafer supply chains facing extended procurement cycles. Single-source vulnerability concentrates in East Asian semiconductor fabrication capacity, creating exposure to geopolitical disruption and export restriction scenarios. Distribution runs through hyperscale cloud infrastructure providers anchoring verification networks, with enterprise software vendors and system integrators occupying intermediate tiers between component fabricators and end-user pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as jurisdictional serialization mandates multiply faster than incumbent platform consolidation, creating specialized niches for regional regulatory content libraries and AI-driven anomaly detection modules.
For Market Incumbents: Insulate embedded ERP footprints through deeper manufacturing execution system integration, preempting displacement by cloud-native network platforms. SAP SE and Oracle Corporation must accelerate pre-validated content library expansion for emerging ANVISA and NMPA requirements before TraceLink captures Latin American and Chinese market share. Vertical integration into hardware-software bundles for cold chain verification defends margin position against automation specialists like Mettler-Toledo encroaching on pharmaceutical line-speed deployments. For New Entrants and Emerging Players: Mid-market contract manufacturers in Brazil and Mexico represent the most penetrable entry point, where Portuguese and Spanish regulatory content libraries face undersupply against ANVISA deadline pressure. AI-driven anomaly detection for serialization data streams offers whitespace unconstrained by incumbent pre-validation investments, with European contract manufacturers embedding compliance modules directly into manufacturing execution systems per EU AI Act requirements. Go-to-market through system integrators bridging global platform architectures with national reporting formats bypasses direct competition with established verification networks. For Investors and Strategic Acquirers: Capital is best deployed toward network-effect platforms with multi-jurisdictional regulatory content libraries, as these assets compound defensibility through each additional jurisdiction added. Long-term viability hinges on artificial intelligence inference capabilities transforming traceability from reactive compliance into proactive supply chain intelligence. Signal to watch: FDA DSCSA enforcement actions against verification router non-compliance, which would accelerate replacement of fragmented point solutions and validate consolidation premiums paid for interoperable cloud-native architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Content Library Expansion | Pre-validated jurisdiction-specific modules compress implementation timelines for FDA, EMA, and ANVISA mandates. |
| AI-Driven Anomaly Detection Development | Machine learning algorithms applied to serialization data enable predictive counterfeit identification before dispensary distribution. |
| Cloud-Native Platform Integration | Network-effect architectures displace bilateral point-to-point connections through shared verification infrastructure. |
| Hardware-Software Bundle Positioning | Cold chain verification systems with embedded temperature logging defend premium positioning against label degradation risks. |
| Geographic Regulatory Certification | WHO prequalification and EU import compliance capability unlocks regulated market access for Indian generic manufacturers. |
Methodological Framework
Operator-level perspectives from pharmaceutical compliance officers, serialization system architects, regulatory affairs directors, and wholesale distributor IT procurement leads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA DSCSA guidance documents, EMA audit trail integrity specifications, WHO prequalification protocols, and ANVISA technical standards. Trade data from pharmaceutical serialization hardware imports, cloud infrastructure capex disclosures from hyperscale providers, and enterprise software licensing filings supplemented interview-derived intelligence. Bottom-up demand modeling across manufacturer, distributor, and regulator end-user segments triangulated against top-down market sizing from platform vendor revenue disclosures.
Scenario-bracketing framed analytical approach across the projection horizon, with baseline, accelerated enforcement, and delayed mandate implementation pathways informing range estimates. Segmentation dimensions modeled encompassed technology category, application function, industry vertical, and end-user procurement authority, with regional regulatory cluster and serialization deadline phasing as industry-specific stratifiers. CAGRs derived from fitted growth curves anchored to observable deployment waves around statutory milestones, incorporating pharmaceutical production volume trends and generic manufacturer export expansion patterns as demand-side inputs.
Macroeconomic conditions sit as an overlay; deviation in pharmaceutical capital expenditure cycles, cloud infrastructure investment rates, or East Asian semiconductor fabrication capacity utilization would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and jurisdictional deadline adherence. Cross-checking against FDA DSCSA verification router deployment statistics and EU FMD system go-live announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
Global Regulatory Technology (Regtech) Market
Regulatory Compliance Technology
Aviation Compliance Monitoring Software Market
Regulatory Compliance Technology
Global Anti- Money Laundering Solutions Market
Regulatory Compliance Technology
Global AML Software Market
Regulatory Compliance Technology
Cross-Border Customs and Trade Compliance Orchestration Platforms Market
Regulatory Compliance Technology
Anti-Money Laundering Systems Market
Regulatory Compliance Technology
GDPR Assessment Tools Market
Regulatory Compliance Technology
US Anti Money Laundering Solution Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
Compliance Testing Solutions Market
Regulatory Compliance Technology
Regtech Software Market
Regulatory Compliance Technology
United States Sales Tax Compliance Software Market
Regulatory Compliance Technology
General Data Protection Regulation (GDPR) Market
Regulatory Compliance Technology
Regulatory Information Management System Market
Regulatory Compliance Technology
Nordic Regulatory Affairs Market
Regulatory Compliance Technology
Regulatory Change Management Software Market