
 Compliance Testing Solutions Market | 2026-2036
Compliance Testing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Compliance Testing Solutions Market Outlook
The direct sales channel for enterprise-grade compliance testing is narrowing as certification bodies consolidate multi-standard contracts with tier-one manufacturers. Keysight Technologies leverages its instrumentation heritage to anchor high-frequency EMC validation workflows for 5G and automotive radar suppliers. TÜV SÜD competes through its network of notified-body laboratories across industrial verticals, while SGS differentiates by extending field-testing capabilities into renewable energy installations and grid-connected equipment.
Compliance testing solutions encompass the systems, services, and protocols used to verify that products, processes, and software conform to statutory, industry, and customer-specific standards, employing calibrated measurement chains traceable to national metrology institutes and automated test sequences governed by scripted frameworks. Their primary purpose is to preempt regulatory rejection, liability exposure, and supply chain disruption before commercial release. Software compliance and automated testing represent the fastest-expanding service categories, driven by continuous integration pipelines in medical device firmware and automotive embedded systems. Electrical safety and in-lab testing retain the largest revenue share but face margin compression as commoditized offerings proliferate.
FDA regulations govern premarket submission testing for active medical devices under 21 CFR Part 820, while IEC 60601 establishes baseline electrical safety and electromagnetic compatibility requirements for healthcare equipment internationally. CE marking enforcement through ECHA and national notified bodies restricts market access for non-conforming industrial and consumer products entering Europe. Stakeholders must monitor the divergence between FDA's software-as-medical-device guidance and EU MDR cybersecurity annexes to avoid duplicative validation costs.
Market Dynamics
Automotive electrification and software-defined vehicle architectures are compressing validation timelines while multiplying the test protocols manufacturers must satisfy before production release. Tier-one suppliers now contract for simultaneous EMC, functional safety, and cybersecurity verification rather than sequential validation phases.
Growth Catalysts
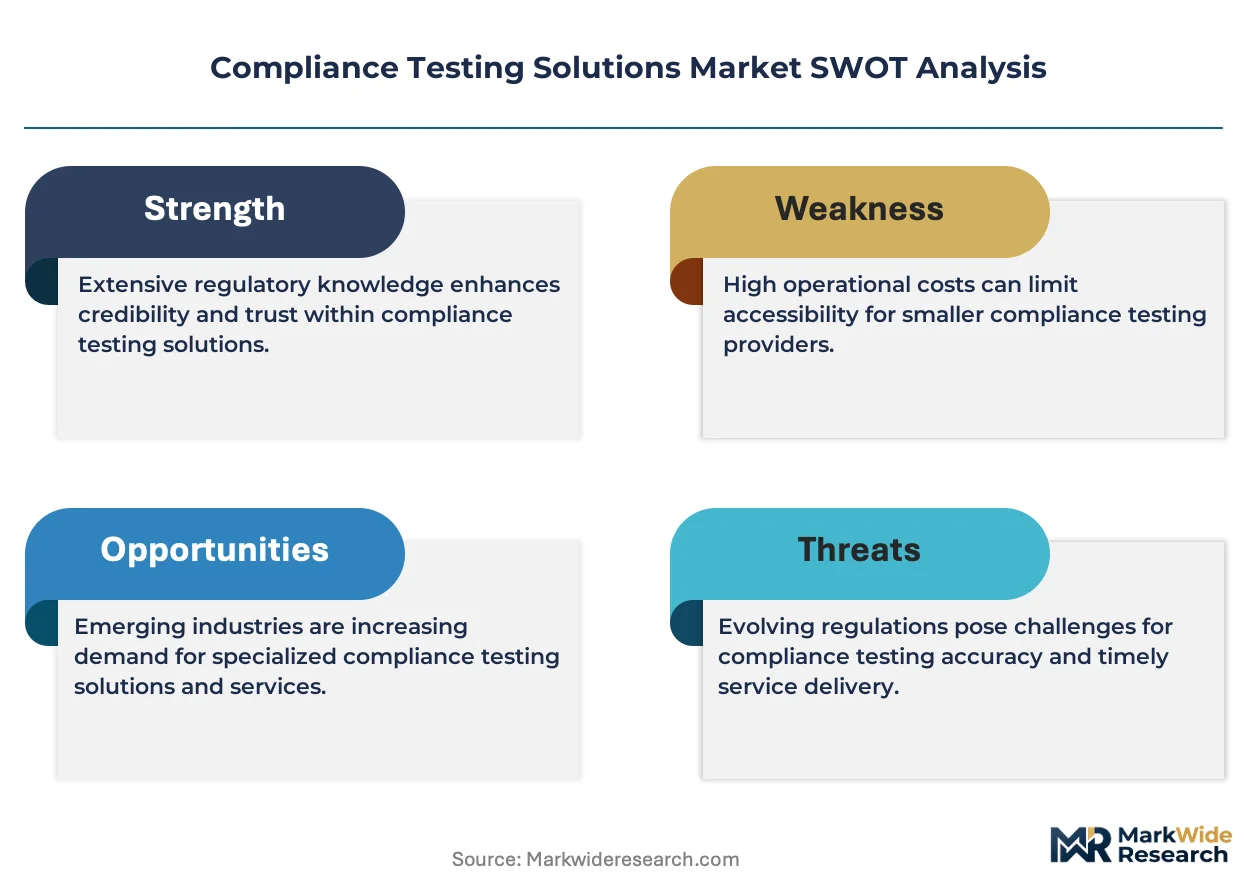
- EU AI Act enforcement:High-risk AI system deployments in automotive and medical devices require third-party conformity assessment, expanding notified-body workloads across German and French laboratories.
- EV platform proliferation:800V architectures and silicon-carbide power electronics introduce new electromagnetic interference profiles that demand specialized high-voltage testing protocols.
- Continuous integration pipelines:Medical device firmware developers embed automated compliance checks within DevSecOps workflows, creating recurring revenue streams for software validation services.
Market Restraints
- Accredited laboratory concentration:Germany and the United States host disproportionate shares of ISO 17025-accredited EMC facilities, creating geographic bottlenecks for Asian manufacturers seeking local testing.
- Capital equipment cycles:Vector network analyzers and anechoic chamber installations require five-to-seven-year depreciation schedules, limiting pricing flexibility during demand downturns.
- Harmonization gaps:Divergent FDA software-as-medical-device guidance and EU MDR cybersecurity annexes force duplicate validation expenditures for dual-market submissions.
Strategic Opportunities
- India laboratory expansion:BIS mandatory certification for electronics and automotive components under Compulsory Registration Order 2.0 outpaces domestic testing capacity.
- Grid-connected storage:Battery energy storage systems for renewable integration require combined electrical safety, EMC, and grid-code compliance testing bundles.
- Digital twin validation:Virtual testing environments for automotive radar and 5G base stations reduce physical prototype iterations before final certification.
Industry Challenges
- Metrology talent scarcity:Calibration technicians with SI-traceable measurement expertise and scripting capabilities for automated test frameworks command premium compensation.
- Legacy equipment integration:Automated test sequences must interface with decade-old spectrum analyzers and power meters through GPIB-to-Ethernet protocol bridges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compliance Testing Solutions Market |
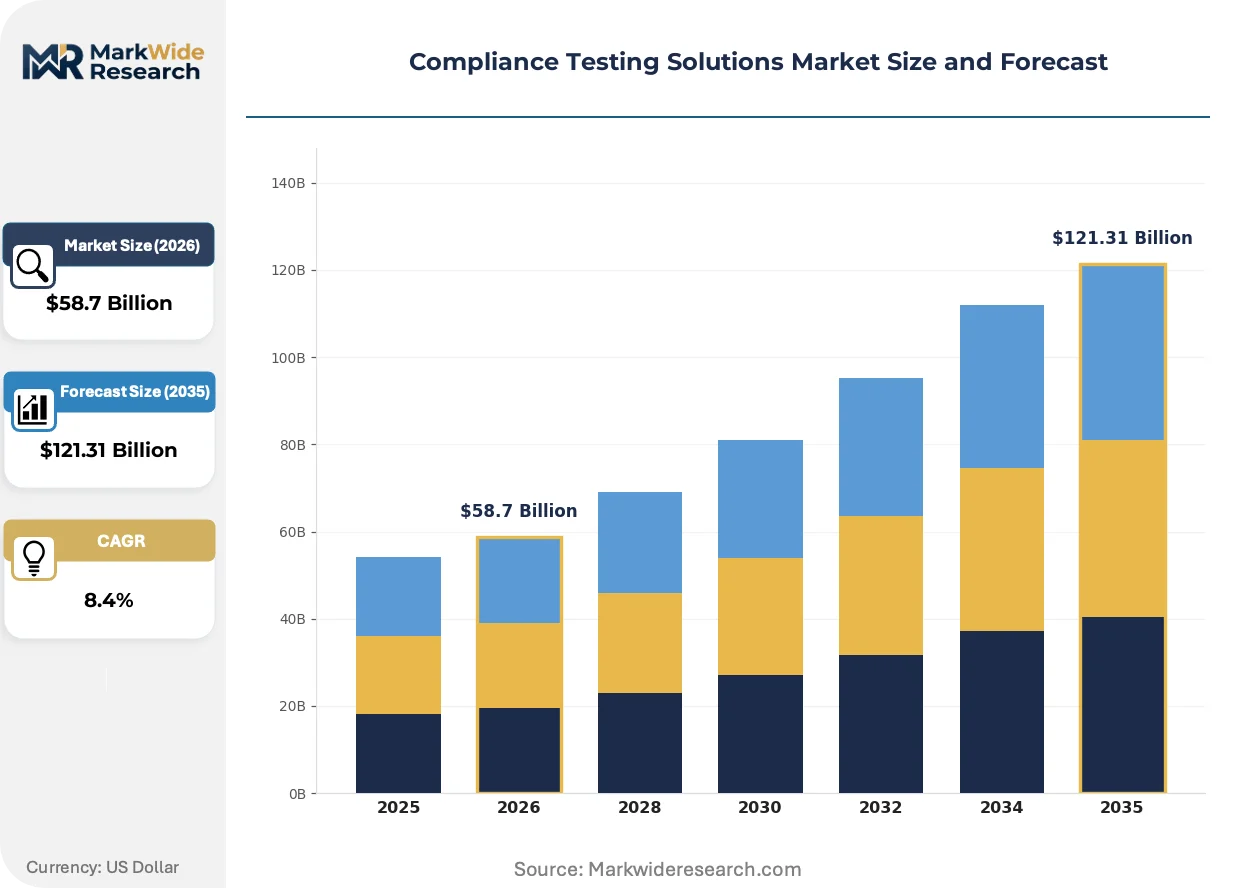
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Electrical Safety, Software Compliance, Environmental Testing, Quality Assurance Industry Vertical: Healthcare, Automotive, Telecommunications, Aerospace Compliance Standard: ISO 9001, IEC 60601, FDA Regulations, CE Marking Testing Method: In-Lab Testing, Field Testing, Automated Testing, Manual Testing |
| Companies Covered | Keysight Technologies, Developing Solutions, Inc., Tata Consultancy Services, SGS, Intertek, TÜV SÜD, Bureau Veritas, Spirent Communications, MiCOM Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compliance Testing Solutions Market Strategic Shifts
Test automation and virtualization are collapsing the traditional boundaries between laboratory validation and production-line quality assurance. Regulatory bodies are accepting simulation-derived evidence for certain compliance demonstrations.
AI-assisted test sequence optimization is rendering obsolete manual script development for repetitive EMC scan routines. Automotive radar suppliers at NXP Semiconductors and Continental deploy machine learning to predict failure modes before chamber occupancy. This compression of pre-certification cycles is reducing time-to-market for 77GHz sensor platforms by eliminating redundant measurement iterations.
REACH substance restrictions and RoHS delegated acts are forcing material requalification across consumer electronics supply chains. Manufacturers must resubmit technical documentation when solder alloys or flame retardants change composition. Industrial equipment OEMs serving European markets now maintain dedicated hazardous substance tracking databases to preempt market surveillance actions by German and French authorities.
Consolidated multi-standard contracts are displacing single-protocol testing engagements at enterprise buyers. Tier-one automotive suppliers now negotiate three-year framework agreements covering ISO 26262, UNECE R155, and CISPR 25 validation. This bundling concentrates procurement power with German and Japanese manufacturers who operate integrated hardware-software release pipelines.
Compliance Testing Solutions Market Segmentation
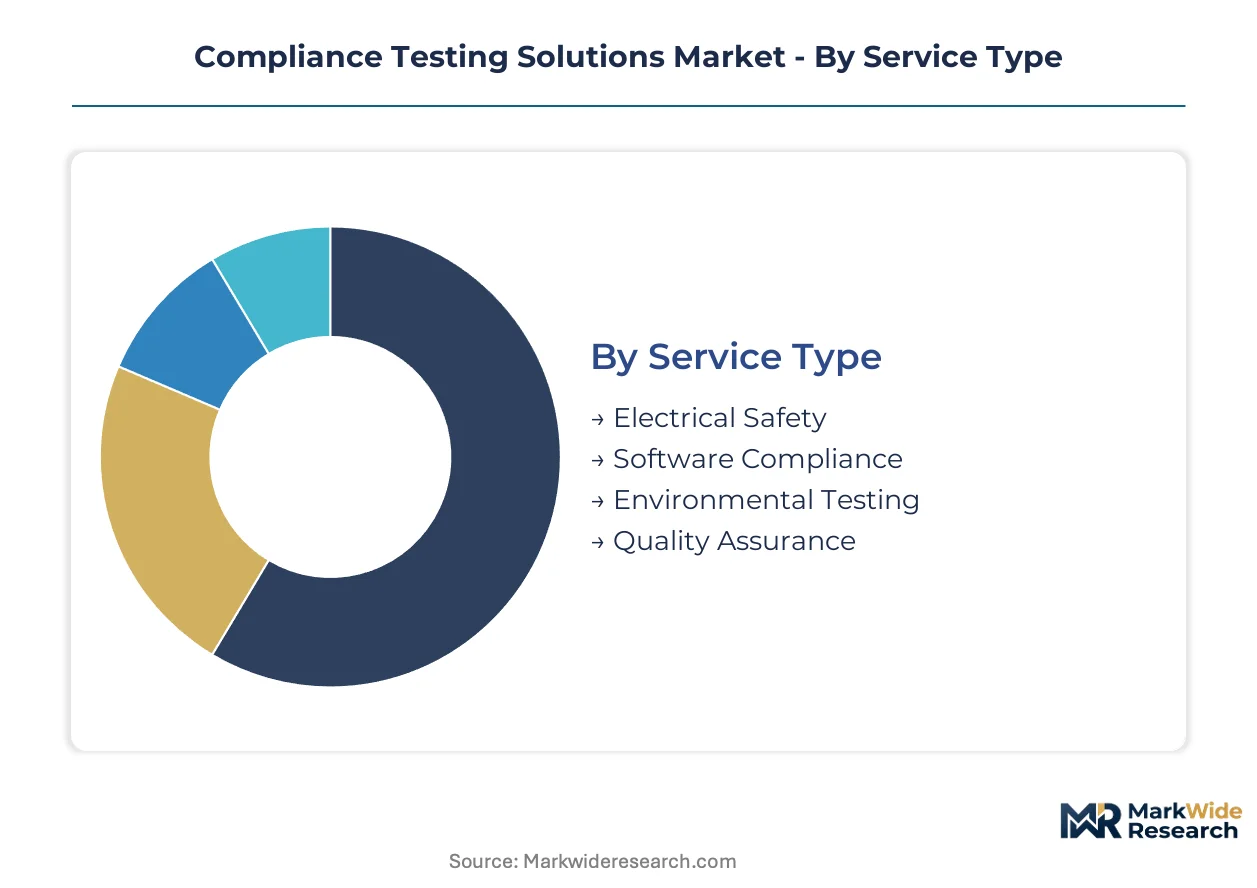
Segmentation in compliance testing solutions reveals how service intensity varies dramatically across verification protocols. Recurring calibration cycles and re-certification mandates create divergent revenue profiles between one-time laboratory engagements and ongoing software validation subscriptions.
Service Type:
After-sales service intensity separates electrical safety programs requiring annual recertification from software compliance engagements demanding continuous integration support.
- Electrical Safety:High-voltage insulation resistance and ground continuity verification using IEC 61010-1 protocols. Demand concentrates in German automotive suppliers facing CE marking enforcement for 800V EV architectures.
- Software Compliance:Automated static analysis and runtime verification for medical device firmware under FDA 21 CFR Part 820 and EU MDR cybersecurity annexes. DevSecOps pipelines at Boston and Stuttgart medical technology clusters generate recurring validation subscriptions.
- Environmental Testing:Thermal cycling, humidity exposure, and salt spray validation per IEC 60068 standards.
- Quality Assurance:Process auditing and management system certification against ISO 9001 and IATF 16949 requirements.
By volume, Electrical Safety leads. By growth pace, Software Compliance is ahead.
Industry Vertical:
Cost tier stratification distinguishes capital-intensive automotive validation programs from leaner healthcare software verification budgets.
- Healthcare:Electromagnetic compatibility and electrical safety testing for active implantable and diagnostic equipment under IEC 60601-1-2. FDA premarket submission requirements and EU MDR technical documentation drive dual-market validation expenditures at Minneapolis and Dublin device manufacturers.
- Automotive:Combined EMC, functional safety, and cybersecurity verification for software-defined vehicles per UNECE R155 and ISO 26262. German OEMs and tier-one suppliers in Munich and Stuttgart contract simultaneous multi-protocol testing to compress release timelines.
- Telecommunications:Radio equipment directive testing and 5G NR base station EMC validation for EU and FCC market access.
- Aerospace:DO-160 environmental qualification and MIL-STD-461 electromagnetic interference testing for avionics suppliers.
By revenue concentration, Automotive dominates. By margin expansion, Healthcare software validation is climbing fastest.
Compliance Standard:
Application context determines whether manufacturers pursue quality management certification, product-specific safety standards, or market-access regulatory approvals.
- ISO 9001:Quality management system auditing and surveillance for organizational process certification rather than product-level verification. Industrial equipment OEMs across France and Italy maintain certification to satisfy procurement prequalification requirements.
- IEC 60601:International electrical safety and electromagnetic compatibility baseline for medical electrical equipment. Japanese and South Korean diagnostic imaging manufacturers seeking EU market access route testing through German notified-body laboratories.
- FDA Regulations:Premarket notification and approval pathway testing for US medical device market entry.
- CE Marking:European market access conformity assessment encompassing multiple directive requirements for industrial and consumer products.
By facility throughput, CE Marking leads. By procedural complexity expansion, FDA software-as-medical-device guidance is gaining share fastest.
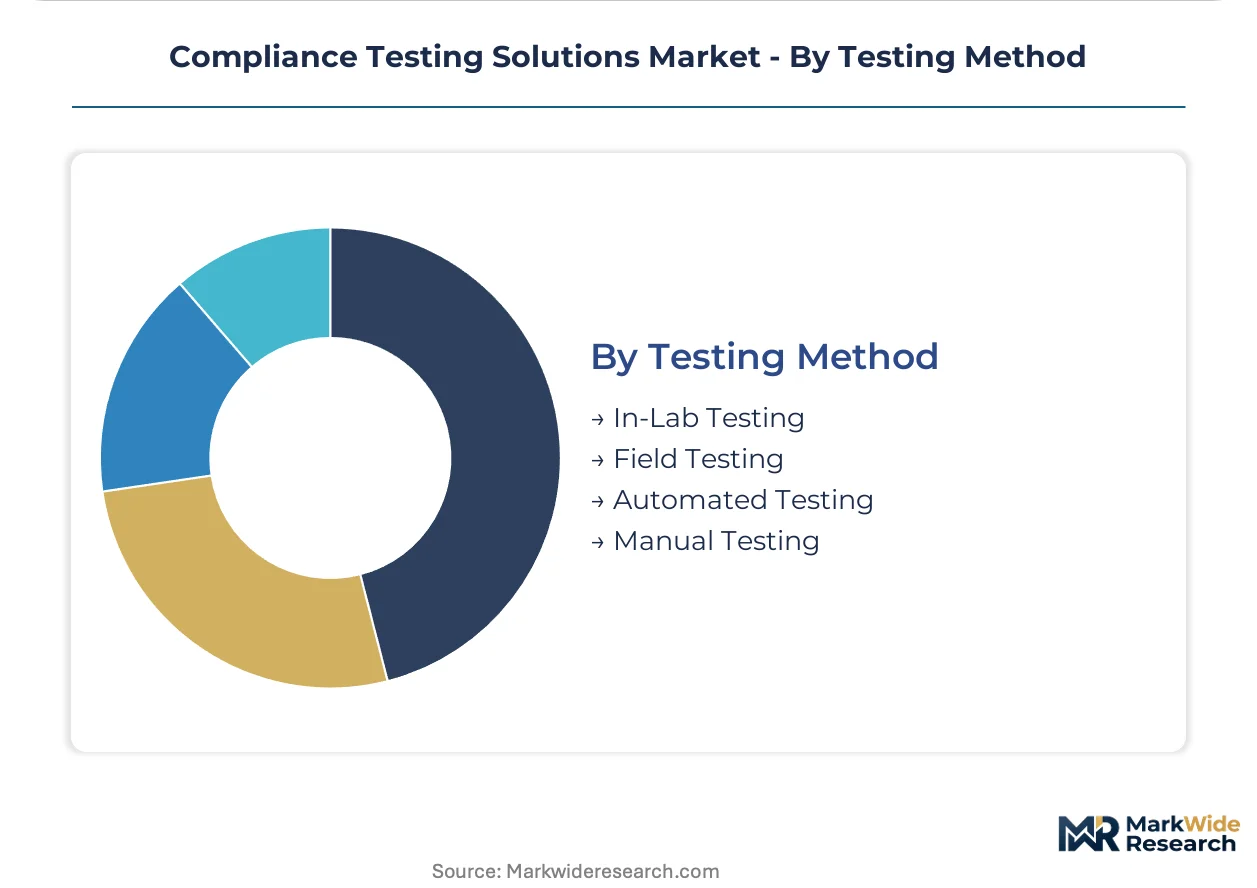
Testing Method:
Customer type separates enterprise manufacturers with captive laboratory infrastructure from mid-tier suppliers dependent on third-party service provision.
- In-Lab Testing:Controlled environment validation within ISO 17025-accredited facilities using calibrated instrumentation traceable to national metrology institutes. German and US laboratories host disproportionate capacity for high-frequency EMC and anechoic chamber measurements.
- Automated Testing:Scripted test sequences executing repetitive measurement routines without manual intervention. Keysight and Rohde & Schwarz instrumentation underpins automotive radar and 5G base station validation workflows.
- Field Testing:On-site verification of installed renewable energy and grid-connected equipment where laboratory simulation proves inadequate.
- Manual Testing:Technician-directed inspection and measurement for low-volume or prototype-stage product evaluation.
By revenue stability, In-Lab Testing leads. By adoption velocity, Automated Testing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's dominance in high-value testing equipment logistics, while the Rhine-Alpine corridor feeds industrial demand clusters across Central Europe. These infrastructure assets concentrate accredited laboratory capacity and metrology-grade instrumentation flows.
Germany
Notified-body laboratories in Munich and Stuttgart handle simultaneous EMC, functional safety, and cybersecurity verification for automotive tier-one suppliers. The EU AI Act enforcement through German accreditation bodies expands conformity assessment workloads for high-risk AI systems in medical devices. TÜV SÜD operates multi-standard testing facilities serving both domestic OEMs and Japanese diagnostic imaging manufacturers seeking EU market access.
United States
FDA premarket submission requirements under 21 CFR Part 820 drive dual-market validation expenditures at Minneapolis and Boston medical technology clusters. The FCC's equipment authorization program governs radio frequency device market entry, compressing timelines for 5G base station suppliers. Keysight Technologies anchors high-frequency EMC validation workflows in California and Texas instrumentation corridors.
China
GB standards alignment with international EMC protocols accelerates domestic laboratory accreditation for automotive and telecommunications equipment. MIIT equipment certification mandates create testing demand for 5G NR base stations and connected vehicle platforms. Yangtze River Delta manufacturing clusters in Shanghai and Suzhou concentrate captive testing infrastructure for consumer electronics exporters.
India
BIS Compulsory Registration Order 2.0 for electronics and automotive components outpaces domestic ISO 17025-accredited facility capacity. CDSCO medical device quality system requirements expand software validation demand at Bengaluru and Hyderabad firmware development clusters. Bureau Veritas and Intertek operate imported testing services bridging the accreditation gap for domestic manufacturers.
Japan
METI industrial standardization programs harmonize JIS EMC requirements with international automotive radar specifications. PMDA quality system regulations for software-as-medical-device submissions drive validation outsourcing from Tokyo and Osaka medical technology corridors. Domestic test equipment manufacturers supply calibrated instrumentation chains traceable to national metrology institutes.
Compliance Testing Solutions Market Competitive Environment
On the supply side, the industry is consolidating around multi-standard contract frameworks that concentrate procurement power with tier-one manufacturers. Three strategic archetypes dominate: instrumentation heritage players anchoring automated test workflows, notified-body networks delivering regulatory accreditation authority, and field-testing specialists extending verification services beyond laboratory boundaries. Competitive moves center on laboratory network expansion into underserviced geographies and digital twin virtualization capabilities that compress pre-certification cycles.
Within the instrumentation tier, Keysight Technologies and Spirent Communications exemplify heritage players leveraging calibrated measurement chains for high-frequency validation. Among European-based accreditation specialists, TÜV SÜD and Bureau Veritas occupy positions anchored by notified-body authority across industrial verticals. SGS represents the field-testing expansion archetype, extending verification capabilities into installed renewable energy and grid-connected equipment where laboratory simulation proves inadequate.
| Leading Market Players |
|---|
| Keysight Technologies |
| Developing Solutions, Inc. |
| Tata Consultancy Services |
| SGS |
| Intertek |
| TÜV SÜD |
| Bureau Veritas |
| Spirent Communications |
| MiCOM Labs |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine corridor's freight cost dynamics amplify pricing power for German laboratory clusters while compressing margins for Asian manufacturers dependent on imported testing equipment. This logistics chokepoint reinforces a three-tier pricing structure that separates premium accredited services from commoditized software validation subscriptions.
Pricing Analysis
Volume-discount tiering structures stratify across premium notified-body contracts, standard multi-protocol bundles, and economy software-as-a-service subscriptions. Price differentiation hinges on ISO 17025 accreditation grade and after-sales calibration bundling. Pricing pressure stems from capital equipment depreciation cycles stretching five-to-seven years, limiting flexibility during demand troughs. Tier-one automotive manufacturers exhibit lowest price sensitivity, while mid-tier electronics suppliers in India and Southeast Asia face acute margin compression.
Supply Chain Analysis
Contract-manufacturing concentration rests with Keysight Technologies and Rohde & Schwarz anchoring calibrated instrumentation production in Germany and the United States. Raw material dependencies center on precision RF components, anechoic chamber absorber materials, and SI-traceable reference standards. Single-source vulnerability concentrates in high-frequency vector network analyzers sourced from limited accredited facilities. Distribution runs through direct enterprise sales channels for tier-one manufacturers, with third-party service networks covering mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity permeates this market as software-defined vehicle architectures and medical device firmware cycles fragment validation demand across specialized niches. The divergence between FDA software-as-medical-device guidance and EU MDR cybersecurity annexes creates distinct regional competency requirements.
For Market Incumbents: Harden laboratory network positions through ISO 17025 accreditation expansion into India and Southeast Asia, where BIS Compulsory Registration Order 2.0 outpaces domestic capacity. Consolidate multi-standard contract frameworks covering simultaneous EMC, functional safety, and cybersecurity verification to preempt tier-one supplier procurement concentration. Threat exposure concentrates in AI-assisted test sequence optimization commoditizing repetitive EMC scan routines. For New Entrants and Emerging Players: Build out digital twin validation capabilities for automotive radar and 5G base station pre-certification, where virtual testing environments reduce physical prototype iterations. Target India's accreditation gap under BIS mandates, where Bureau Veritas and Intertek currently bridge imported testing services. Go-to-market leverage rests on DevSecOps pipeline integration for medical device firmware developers seeking automated compliance subscriptions. For Investors and Strategic Acquirers: Specialized software validation boutiques with FDA 21 CFR Part 820 and EU MDR cybersecurity dual competency represent priority acquisition archetypes. Long-term viability over the next decade hinges on regulatory divergence persistence between US and European medical device frameworks. Inflection monitoring should track EU AI Act enforcement velocity through German and French notified-body workload expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Laboratory Accreditation | Simultaneous ISO 26262, UNECE R155, and CISPR 25 validation compresses automotive release timelines for German OEMs. |
| Digital Twin Test Environment Deployment | Virtual automotive radar validation at NXP Semiconductors and Continental eliminates redundant chamber measurement iterations. |
| India Laboratory Network Expansion | BIS Compulsory Registration Order 2.0 electronics certification demand exceeds domestic ISO 17025-accredited facility supply. |
| DevSecOps Pipeline Integration | Automated compliance embedding within Boston and Stuttgart medical technology clusters generates recurring software validation subscriptions. |
| AI-Assisted Test Sequence Optimization | Machine learning failure mode prediction renders manual EMC scan script development obsolete at automotive radar suppliers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) submission databases, EU notified-body accreditation registries, and automotive OEM supplier quality manuals. Calibration laboratory directors, medical device regulatory affairs managers, Tier 1 supplier procurement executives, and test equipment distribution channel heads provided structured input. Bottom-up triangulation across service-type revenue segmentation and top-down validation against national metrology institute instrumentation shipment data anchored market sizing.
Forecast inputs encompass service type intensity variations, industry vertical cost tier stratification, compliance standard procedural complexity expansion, and testing method adoption velocity across the analysis window. Segmentation dimensions modeled include electrical safety, software compliance, environmental testing, and quality assurance service categories; healthcare, automotive, telecommunications, and aerospace verticals; and in-lab, automated, field, and manual testing methods. CAGRs derived from regression analysis of historical accreditation body workload data and projected regulatory mandate enforcement schedules.
Stress conditions across EU AI Act implementation timelines, FDA software-as-medical-device guidance finalization, and capital equipment replacement cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory divergence persistence and metrology talent scarcity compensation inflation. Quarterly review of German notified-body queue lengths and India BIS accreditation expansion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
Management System Certification Market
Regulatory Compliance Technology
Anti-Money Laundering Systems Market
Regulatory Compliance Technology
Regtech Software Market
Regulatory Compliance Technology
Regulatory Reporting Solutions Market
Regulatory Compliance Technology
US Anti Money Laundering Solution Market
Regulatory Compliance Technology
Nordic Regulatory Affairs Market
Regulatory Compliance Technology
Global Regulatory Technology (Regtech) Market
Regulatory Compliance Technology
United States Sales Tax Compliance Software Market
Regulatory Compliance Technology
Regulatory Information Management System Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
General Data Protection Regulation (GDPR) Market
Regulatory Compliance Technology
Global Anti- Money Laundering Solutions Market
Regulatory Compliance Technology
Compliance and Traceability Solutions Market
Regulatory Compliance Technology
Global GDPR Services Market
Regulatory Compliance Technology
GDPR Assessment Tools Market
Regulatory Compliance Technology
Aviation Compliance Monitoring Software Market