
 Regtech Software Market | 2026-2036
Regtech Software Market Size, Share, and Industry Trends Forecast 2026-2036
Regtech Software Market Insights
The direct enterprise sales channel is fragmenting as specialized regtech vendors bypass traditional systems integrators to sell compliance automation directly to risk officers and chief compliance officers. Thomson Reuters leverages its legacy regulatory content library to anchor premium subscription tiers for tier-one banks. NICE Actimize competes through AI-powered transaction monitoring that sustains analyst productivity in high-volume payment environments. Wolters Kluwer differentiates by embedding jurisdictional rule updates directly into workflow tools, reducing manual interpretation overhead for multinational compliance teams.
Regtech software encompasses applications that automate regulatory compliance, risk governance, and reporting obligations through configurable rule engines, API-connected data pipelines, and machine-learning classifiers trained on enforcement patterns and jurisdictional rule corpora. Its primary commercial purpose is to reduce operational expenditure on manual compliance review while shortening detection latency for money laundering, sanctions breaches, and conduct violations. Compliance Monitoring solutions lead current revenue contribution because banks face continuous audit scrutiny and penalty exposure. Cloud-Based deployment is expanding fastest as financial institutions retire on-premises legacy systems and adopt elastic infrastructure for seasonal regulatory filing peaks. Identity Verification commands premium pricing due to biometric liveness detection and document authentication complexity.
The US Office of the Comptroller of the Currency and the Financial Crimes Enforcement Network shape product roadmaps through enforcement priorities that elevate sanctions screening and beneficial-ownership transparency requirements. The EU AI Act and GDPR impose algorithmic accountability standards that constrain black-box model deployment in credit and fraud decisions. Stakeholders must monitor whether emerging digital-asset regulations in major economies will force platform rebuilds or create modular expansion opportunities for existing compliance stacks.
Market Dynamics
Cloud-native compliance stacks are compressing deployment cycles from months to weeks, forcing incumbent vendors to re-architect monolithic platforms or cede mid-market share to API-first challengers.
Growth Catalysts
- GDPR Article 35 mandates:Data protection impact assessments now require automated documentation trails, pulling European banks toward continuous monitoring platforms.
- Biometric liveness detection:Remote onboarding volumes at UK neobanks have normalized document-authentication workflows that embed 3D face-mapping SDKs.
- Singapore:MAS digital banking licenses impose real-time risk-data reporting standards that only cloud-elastic infrastructure can satisfy.
Market Restraints
- Specialized engineering talent scarcity:Compliance-ML model validation requires hybrid skillsets spanning regulatory interpretation and statistical rigor.
- AWS-Azure-Google concentration:Three hyperscalers control the substrate for most cloud-native regtech deployments, creating single-point-of-failure exposure.
- EU AI Act algorithmic accountability:Black-box credit-scoring models face mandatory explainability thresholds that constrain neural-network architectures.
Strategic Opportunities
- Brazil:PIX instant-payment adoption outpaces local transaction-monitoring capacity, creating whitespace for real-time screening tools.
- Blockchain analytics convergence:On-chain forensics layered with traditional KYC data is opening digital-asset compliance modules for existing AML stacks.
- CSRD sustainability reporting:Mandatory ESG disclosure rules in Europe are extending regtech workflows into carbon-accounting and supply-chain due diligence.
Industry Challenges
- Core banking integration friction:COBOL-era transaction engines at tier-one institutions resist API connectivity, prolonging proof-of-concept timelines.
- Model risk management certification:SR 11-7 compliance for US banks demands exhaustive documentation that slows AI-powered feature rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regtech Software Market |
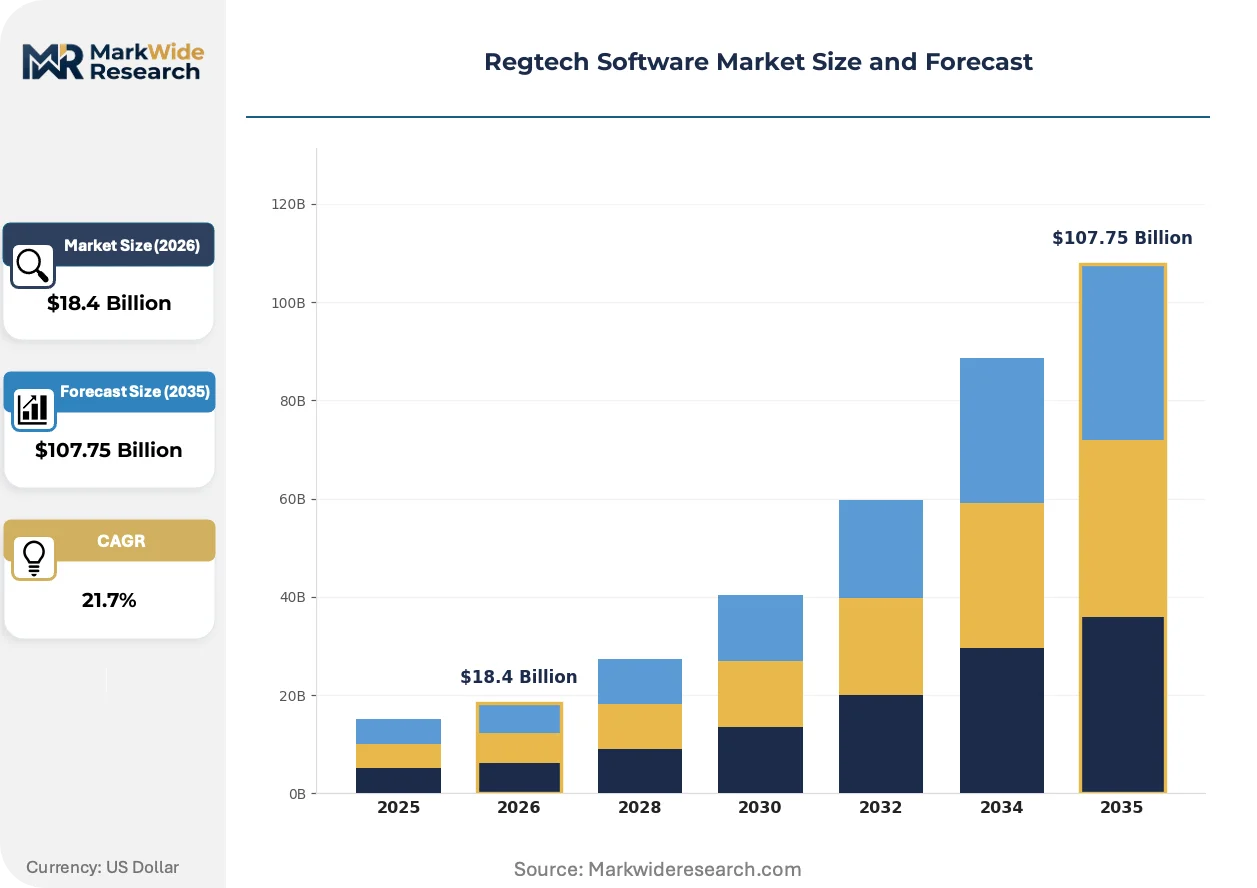
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $107.75 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Risk Management, Compliance Monitoring, Identity Verification, Transaction Analysis, Reporting Automation, Fraud Detection Deployment Model: Cloud-Based, On-Premises, Hybrid, Hosted Services Application: Anti-Money Laundering, Know Your Customer, Regulatory Reporting, Fraud Prevention, Risk Assessment End User Industry: BFSI Institutions, Payment Processors, FinTech Firms, Legal Firms, Insurance Providers, Capital Markets |
| Companies Covered | Thomson Reuters, NICE Actimize, Wolters Kluwer, ComplyAdvantage, Chainalysis, Ascent Technologies, Broadridge Financial Solutions, Deloitte Touche Tohmatsu Limited, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regtech Software Market Trends and Innovations
Distributed ledger interoperability and explainable AI architectures are redefining what compliance infrastructure must prove to auditors and supervisors.
Sandboxed smart-contract environments are virtualizing the settlement-layer testing that previously required live-market exposure. German universal banks now deploy these for derivatives-margin compliance simulation. The approach compresses validation cycles while satisfying BaFin's pre-trade risk-check requirements.
The EU AI Act's risk-tier classification system imposes conformity-assessment obligations on credit-scoring algorithms that exceed human-review thresholds. Automated decision systems in French retail banking now embed counterfactual-explanation modules. Vendors are racing to certify these against notified-body standards before the enforcement window closes.
Buy-side compliance teams now unbundle implementation from software licensing, contracting boutique system integrators for rule-engine configuration while negotiating direct SaaS terms. This bifurcation is most pronounced in London's asset-management cluster, where specialist consultancies have captured workflow-design revenue that incumbent vendors previously monopolized.
Regtech Software Market Segmentation
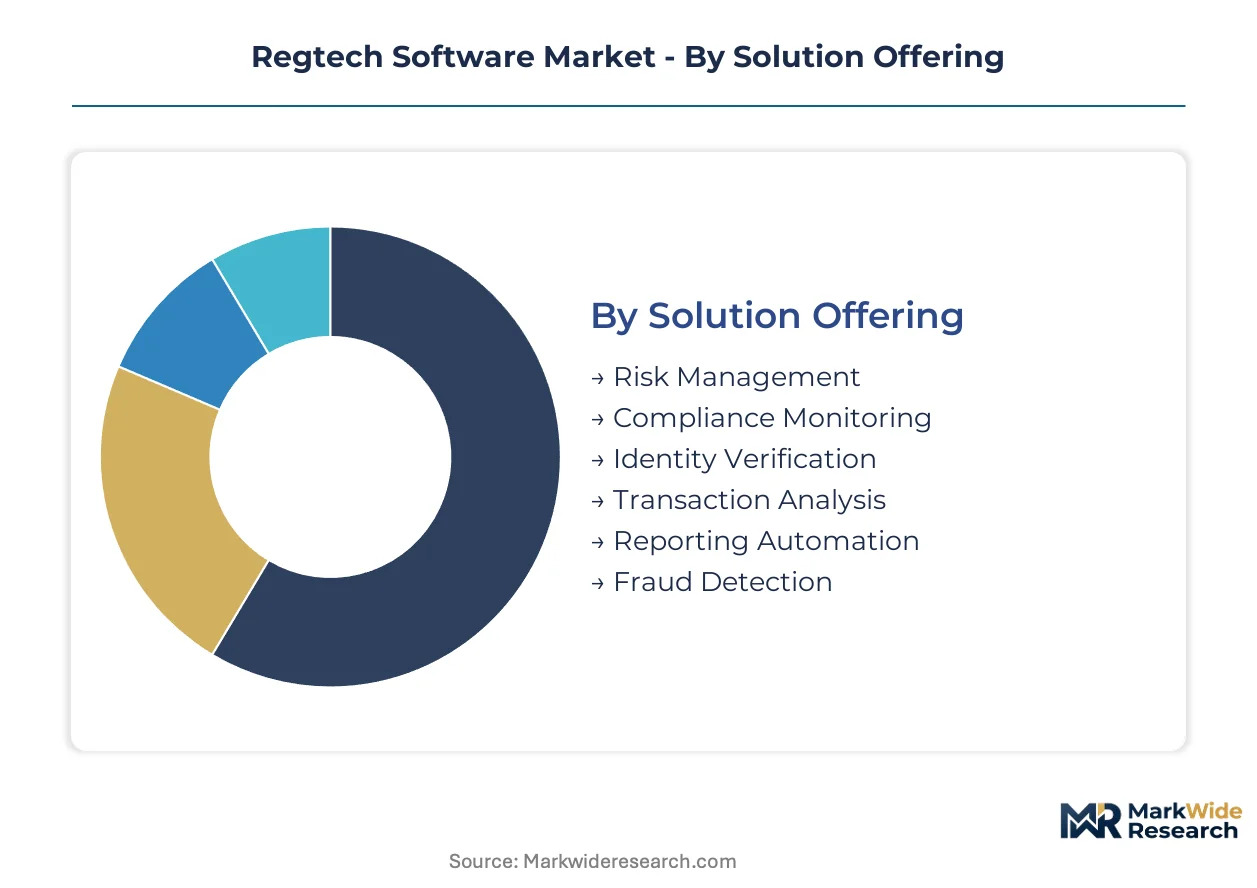
Regtech purchasing cycles vary dramatically by segment, with compliance monitoring platforms renewing annually while core risk engines operate on five-to-seven-year depreciation schedules. Procurement officers weight these rhythms against penalty exposure and audit frequency when allocating capital across solution categories.
Solution Offering:
Compliance Monitoring turns over fastest as regulators issue quarterly guidance updates, while Reporting Automation refresh cycles stretch longest due to legacy spreadsheet dependencies.
- Compliance Monitoring:Continuous audit-trail platforms ingest supervisory alerts and enforcement patterns to flag policy deviations in real time. Tier-one banks in the United Kingdom and Germany deploy these for GDPR Article 35 documentation mandates. MAS digital banking licensees in Singapore require elastic infrastructure for real-time risk-data submission, compressing procurement timelines further.
- Identity Verification:Biometric liveness detection and document-authentication SDKs embed 3D face-mapping for remote onboarding. UK neobanks normalized these workflows during pandemic-era customer acquisition surges. Premium pricing reflects the engineering complexity of spoof-resistant neural architectures and cross-jurisdictional identity federation.
- Risk Management:Enterprise governance platforms aggregate credit, market, and operational risk into unified dashboards for C-suite reporting.
- Transaction Analysis:Real-time payment screening tools parse SWIFT, ACH, and instant-payment rails for sanctions hits and structuring patterns.
- Reporting Automation:XBRL and regulatory filing engines transform raw transaction data into submission-ready formats for SEC, FINRA, and ECB templates.
- Fraud Detection:Behavioral biometrics and device fingerprinting layer atop traditional rules engines to catch account takeover and synthetic identity schemes.
Compliance Monitoring dominates installed base. Identity Verification is where expansion concentrates.
Deployment Model:
Cloud-Based deployments command premium subscription rates, while On-Premises installations carry heavier professional-services attach rates for customization and maintenance.
- Cloud-Based:Elastic infrastructure scales for seasonal filing peaks and M&A-driven entity onboarding without capital expenditure. FinTech firms in Singapore and Germany prefer API-first architectures that bypass traditional systems integrators. AWS, Azure, and Google control underlying substrate, creating concentration risk that procurement officers negotiate around through multi-cloud strategies.
- Hybrid:Sensitive data remains on-premises while compute-intensive analytics burst to public cloud, satisfying data-residency requirements in France and Germany. Tier-one banks with COBOL-era core systems use this bridge architecture to modernize incrementally without wholesale replacement.
- On-Premises:Perpetual licensing persists at institutions with air-gapped security mandates or sovereign-data requirements.
- Hosted Services:Managed private-cloud deployments offer single-tenant isolation without internal infrastructure teams.
Cloud-Based deployments are climbing the fastest. On-Premises retains longest tenure in capital markets infrastructure.
Application:
Know Your Customer workflows face shortest implementation windows, while Regulatory Reporting projects extend longest due to jurisdictional rule-mapping complexity.
- Anti-Money Laundering:Transaction monitoring and suspicious-activity-report generation consume the largest compliance headcount at correspondent banks. AI-powered alert triage sustains analyst productivity when payment volumes surge. Wolters Kluwer and NICE Actimize compete through pre-trained models on enforcement pattern corpora.
- Know Your Customer:Perpetual KYC refresh cycles replace point-in-time checks as regulators demand ongoing beneficial-ownership verification. Brazilian PIX instant-payment adoption outpaces local screening capacity, creating whitespace for real-time tools.
- Regulatory Reporting:Multi-jurisdictional rule engines must reconcile GAAP, IFRS, and local prudential standards into unified submission workflows.
- Fraud Prevention:Real-time authorization scoring intercepts authorized push payment fraud before funds settle.
- Risk Assessment:Credit-decision models face EU AI Act explainability mandates that constrain black-box neural architectures.
Anti-Money Laundering dominates installed base. Know Your Customer is gaining share fastest.
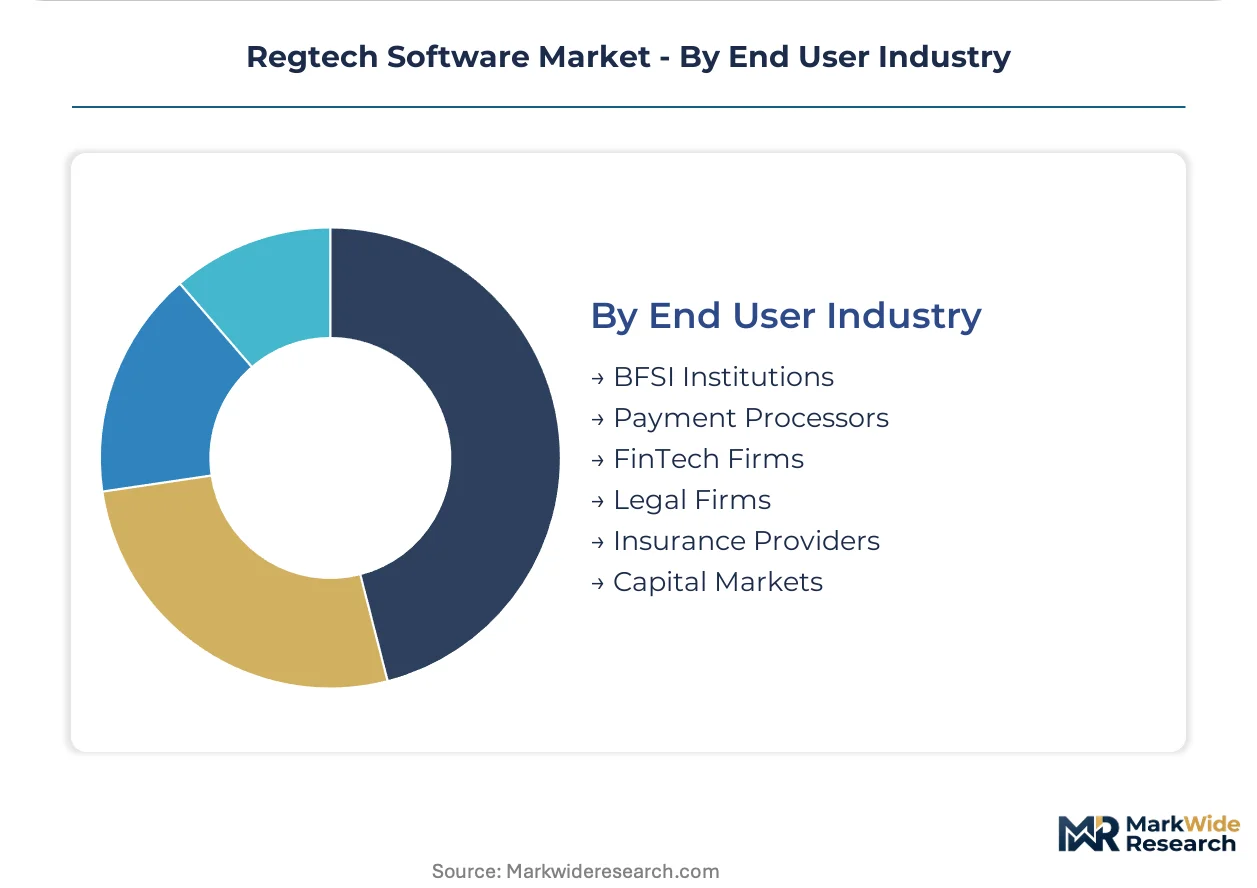
End User Industry:
BFSI Institutions cycle slowest due to procurement committee structures, while FinTech Firms compress vendor selection to weeks through direct risk-officer relationships.
- FinTech Firms:Neobanks and payment platforms prioritize API-native stacks that deploy without professional-services overhead. London and Singapore clusters unbundle implementation from licensing, contracting boutique integrators for rule-engine configuration. MAS digital banking licenses impose infrastructure standards that only cloud-elastic architectures satisfy.
- BFSI Institutions:Universal banks amortize compliance platforms across global footprints, spreading fixed costs across millions of accounts. Core banking integration friction prolongs proof-of-concept timelines when COBOL-era transaction engines resist API connectivity.
- Payment Processors:Real-time rail operators require sub-second sanctions screening without false-positive fatigue.
- Capital Markets:Derivatives-margin compliance and pre-trade risk checks demand sandboxed smart-contract environments for BaFin validation.
- Insurance Providers:Solvency II and NAIC reporting obligations drive actuarial-system integration with compliance workflows.
- Legal Firms:Client-matter screening and conflict-check automation extend regtech into professional-services adjacencies.
BFSI Institutions dominate installed base. FinTech Firms represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The submarine cable corridors linking Frankfurt, London, Amsterdam, Paris, and Dublin underpin Europe's dominance in cross-border financial data flows, creating concentrated demand for jurisdictional compliance orchestration.
United States
FinCEN enforcement priorities and SEC climate disclosure mandates drive procurement of real-time transaction monitoring. The New York-Washington corridor hosts the largest concentration of correspondent banking compliance teams. Cloud-native identity verification vendors bypass traditional integrators to sell directly into risk committees at money-center institutions.
Germany
BaFin's pre-trade risk-check requirements and DORA operational resilience deadlines compress procurement cycles for sandboxed compliance environments. The Frankfurt-Rhine-Main cluster anchors continental Europe's derivatives-margin compliance tooling demand. Universal banks here deploy smart-contract virtualization for settlement-layer testing without live-market exposure.
United Kingdom
FCA consumer duty rules and PRA operational resilience timelines accelerate replacement of spreadsheet-dependent reporting workflows. London's asset-management cluster unbundles implementation from software licensing, contracting boutique integrators for rule-engine configuration. Neobanks normalized biometric liveness detection during pandemic-era onboarding surges.
Singapore
MAS digital banking licenses impose infrastructure standards that only cloud-elastic architectures satisfy. The city-state's real-time risk-data reporting requirements pull regional headquarters toward API-first compliance stacks. Southeast Asian payment platforms route through Singapore for jurisdictional rule-engine calibration.
Brazil
PIX instant-payment adoption outpaces local transaction-monitoring capacity, creating whitespace for real-time screening tools. The central bank's open-finance mandates force incumbent institutions toward modular compliance expansion rather than platform rebuilds. São Paulo's fintech cluster drives fastest regional procurement velocity.
Regtech Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the workflow stack. The vendor base separates into three layers: legacy content libraries anchoring premium subscriptions, AI-native challengers compressing deployment cycles, and boutique configurators capturing unbundled implementation revenue. Consolidation pressure intensifies as API-first entrants force re-architecture of monolithic stacks. Dominant competitive moves include direct-to-risk-officer sales channel development and multi-cloud infrastructure partnerships.
Among legacy information-services conglomerates, Thomson Reuters and Wolters Kluwer occupy positions anchored by jurisdictional rule corpora and embedded workflow tools. NICE Actimize represents the AI-native tier with transaction-monitoring architectures designed for high-volume payment environments. These three exemplify the strategic divergence between content-heavy platform bundling and compute-intensive real-time analytics specialization.
| Leading Market Players |
|---|
| Thomson Reuters |
| NICE Actimize |
| Wolters Kluwer |
| ComplyAdvantage |
| Chainalysis |
| Ascent Technologies |
| Broadridge Financial Solutions |
| Deloitte Touche Tohmatsu Limited |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
Hyperscaler concentration in the United States anchors cloud infrastructure costs for regtech deployments, pushing margin pools toward API-first challengers that bypass traditional systems integrators and capture direct SaaS premiums from risk officers.
Pricing Analysis
Volume-discount tiering structures dominate as tier-one banks negotiate enterprise-wide platform licenses while mid-market institutions consume per-seat SaaS subscriptions. Pricing stratifies across premium, standard, and economy tiers based on jurisdictional rule-engine depth and biometric liveness detection sophistication. Cost compression in the standard tier is intensifying because API-native entrants commoditize basic compliance monitoring features. FinTech firms exhibit highest price sensitivity due to constrained procurement budgets, while universal banks prioritize feature completeness over unit economics.
Supply Chain Analysis
Export-control regimes limiting advanced GPU and AI accelerator flows to Chinese cloud providers reshape infrastructure sourcing strategies for compliance-ML training pipelines. Supply concentrates in the United States, Ireland, and Singapore for hyperscale data centers, with specialized engineering talent pools anchored in London, Frankfurt, and Bangalore. Raw material dependencies span semiconductor fabrication, high-bandwidth memory modules, and rare-earth magnet supply for cooling systems. Single-source vulnerability runs through NVIDIA's dominance in training-grade silicon. Distribution runs through direct enterprise sales channels that fragment as vendors bypass systems integrators to reach chief compliance officers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity crystallizes as unbundling of implementation from licensing creates niche capture points for boutique system integrators and API-first challengers across London, Singapore, and São Paulo financial centers.
For Market Incumbents: Insulate core subscription revenue by embedding jurisdictional rule updates directly into workflow tools, reducing manual interpretation overhead that drives churn. Deepen upstream control over regulatory content libraries through exclusive data partnerships with national financial intelligence units. Prioritize certification investment against EU AI Act conformity-assessment standards before enforcement windows close.
For New Entrants and Emerging Players: Brazilian PIX instant-payment infrastructure offers the most penetrable whitespace as real-time transaction monitoring capacity lags adoption velocity. Target API-native deployment for neobanks and payment platforms seeking sub-implementation-timeline procurement. Lead go-to-market through direct risk-officer relationships that bypass traditional procurement committees.
For Investors and Strategic Acquirers: Capital is best deployed toward AI-native challengers with pre-trained enforcement-pattern models and cloud-elastic architectures that compress deployment cycles. Long-term viability hinges on regulatory moat depth rather than feature breadth. Watch MAS digital banking license issuance velocity as inflection indicator for regional infrastructure demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding KYC workflows into core banking systems reduces COBOL-era friction at tier-one institutions. |
| Geographic Expansion | PIX-compliant transaction monitoring modules capture whitespace in Brazilian instant-payment infrastructure. |
| Strategic Partnership | Multi-cloud infrastructure partnerships with AWS and Azure mitigate hyperscaler concentration risk. |
| Acquisition of Specialist Firm | Boutique system integrators in London capture unbundled implementation revenue from asset managers. |
| Product Launch | Explainable AI architectures satisfy BaFin pre-trade risk-check requirements for derivatives-margin compliance. |
Research Methodology
Initial hypotheses were tested against primary input from chief compliance officers, risk management directors, regulatory affairs leads at tier-one banks, and FinTech platform engineers, then refined through secondary validation against SEC enforcement patterns, MAS licensing disclosures, BaFin circulars, and EU AI Act draft implementing acts. Bottom-up sizing of solution-specific deployments triangulated with top-down spending estimates from financial institution regulatory technology budgets.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling segmentation dimensions spanning deployment model, organization size tier, application complexity, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves and enforcement-priority weightings. Industry-specific forecast inputs incorporated GDPR Article 35 documentation mandate penetration and biometric liveness detection SDK deployment velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed challengers or regulatory sandbox expansions would shift outcomes. Material shifts in EU AI Act enforcement timelines or MAS digital banking license issuance velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
United States Sales Tax Compliance Software Market
Regulatory Compliance Technology
Global Anti- Money Laundering Solutions Market
Regulatory Compliance Technology
Regulatory Change Management Software Market
Regulatory Compliance Technology
Regulatory Reporting Solutions Market
Regulatory Compliance Technology
Aviation Compliance Monitoring Software Market
Regulatory Compliance Technology
Global GDPR Services Market
Regulatory Compliance Technology
Regulatory Information Management System Market
Regulatory Compliance Technology
General Data Protection Regulation (GDPR) Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
GDPR Assessment Tools Market
Regulatory Compliance Technology
Cross-Border Customs and Trade Compliance Orchestration Platforms Market
Regulatory Compliance Technology
Compliance Testing Solutions Market
Regulatory Compliance Technology
Compliance and Traceability Solutions Market
Regulatory Compliance Technology
Global Regulatory Technology (Regtech) Market
Regulatory Compliance Technology
Global AML Software Market
Regulatory Compliance Technology
US Anti Money Laundering Solution Market