
 US Anti Money Laundering Solution Market | 2026-2036
US Anti Money Laundering Solution Market Size, Share, and Industry Trends Forecast 2026-2036
US Anti Money Laundering Solution Market Analytics
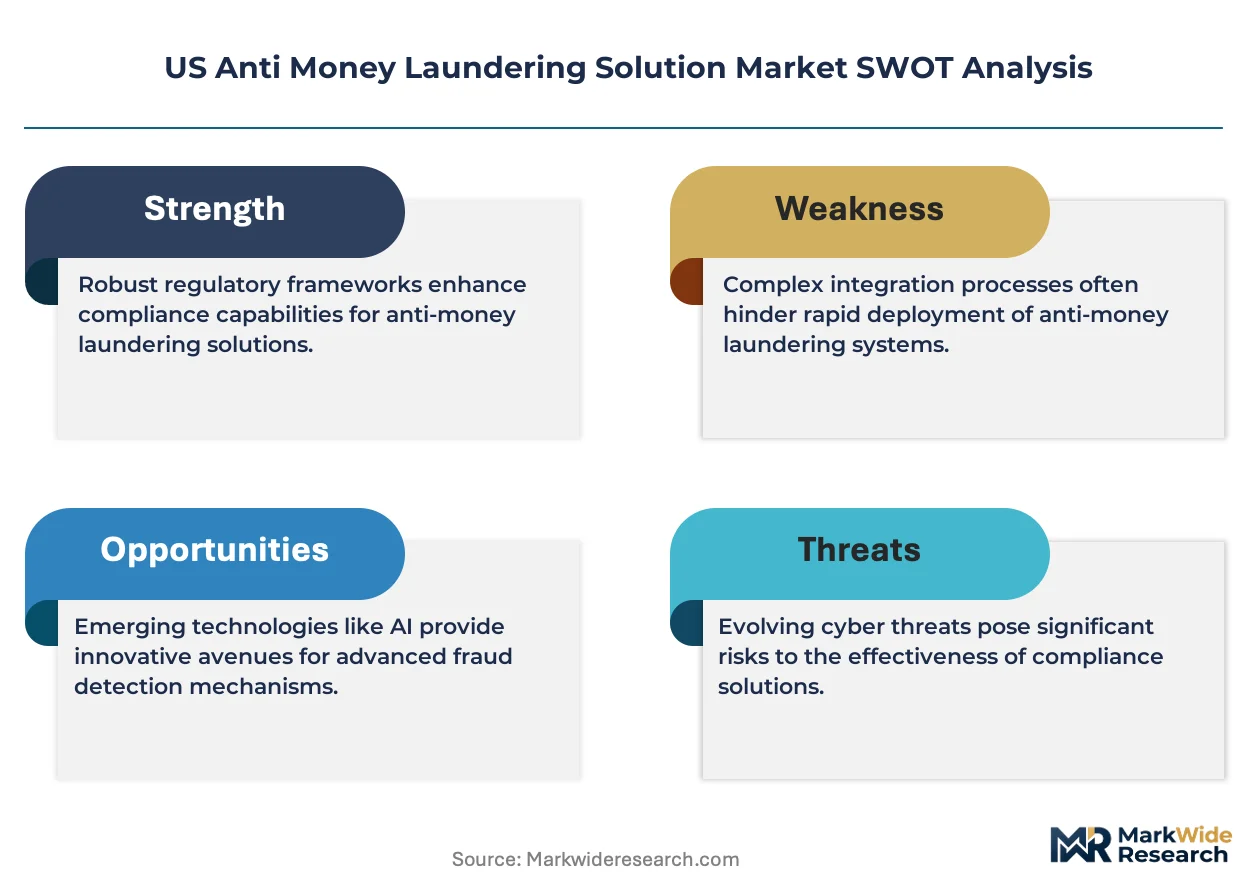
Vendor consolidation from fragmented point solutions toward integrated enterprise platforms is consolidating procurement patterns across tier-one financial institutions. Oracle Corporation leverages its database infrastructure to anchor on-premises deployments at major banks. NICE Actimize competes through specialized risk-scoring algorithms for transaction monitoring. LexisNexis Risk Solutions sustains dominance in identity verification and watchlist screening through proprietary data assets.
Anti money laundering solutions encompass software systems that detect, investigate, and report suspicious financial activity through rule-based engines, machine learning models, and network analytics operating against structured and unstructured data feeds. These platforms serve primarily to satisfy legal obligations under the Bank Secrecy Act while reducing operational costs from false-positive alerts. Transaction monitoring solutions command the largest revenue share due to regulatory mandates for real-time screening of wire transfers and ACH flows. Cloud-based deployment is accelerating fastest as regional banks shed legacy mainframe dependencies. Customer due diligence functionality carries concentrated margin pools because perpetual KYC refresh cycles generate recurring license renewals.
FinCEN, the OCC, and state banking regulators collectively shape product roadmaps through examination priorities and enforcement actions that elevate real-time surveillance standards. The USA PATRIOT Act amendments and forthcoming beneficial ownership database integration are forcing institutions to unify historically siloed compliance workflows. Stakeholders must evaluate whether to build captive AI models or subscribe to vendor-managed platforms as model risk management scrutiny intensifies.
Market Dynamics
FinCEN's Beneficial Ownership Information reporting requirements are compressing procurement cycles as banks race to unify fragmented compliance workflows before enforcement deadlines. This regulatory pressure is accelerating vendor consolidation toward integrated platforms capable of real-time surveillance across historically siloed systems.
Growth Catalysts
- The USA PATRIOT Act amendments:These provisions mandate enhanced due diligence for correspondent banking relationships, forcing institutions to upgrade transaction monitoring infrastructure.
- Wire transfer screening:Real-time surveillance of SWIFT and ACH flows has become non-negotiable for large national banks with complex cross-border footprints.
- Cloud migration:Regional banks are shedding legacy mainframe dependencies, opening subscription revenue pools for SaaS-native compliance platforms.
Market Restraints
- Model risk management scrutiny:OCC examination priorities intensify validation burdens for AI-driven transaction scoring, slowing deployment timelines.
- Perpetual KYC refresh cycles:These generate recurring license costs that strain compliance budgets at mid-tier institutions.
- False-positive alert volumes:Legacy rule-based engines produce investigation backlogs that consume analyst capacity without yielding actionable intelligence.
Strategic Opportunities
- Network analytics convergence:Graph-based detection combining entity resolution with behavioral biometrics is expanding into previously unreachable transaction patterns.
- State banking regulator coordination:Harmonized examination standards across state-chartered institutions create scalable deployment pathways for compliance vendors.
- Unstructured data processing:Natural language extraction from adverse media and legal filings represents untapped automation potential for customer due diligence workflows.
Industry Challenges
- Data engineering talent scarcity:AML platforms require specialized expertise in streaming architecture and feature engineering that commands premium compensation.
- Legacy system integration friction:Core banking modernization timelines rarely align with compliance technology refresh cycles, forcing expensive middleware layers.
- Alert investigation workforce turnover:Analyst burnout from repetitive false-positive review degrades institutional knowledge retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Anti Money Laundering Solution Market |
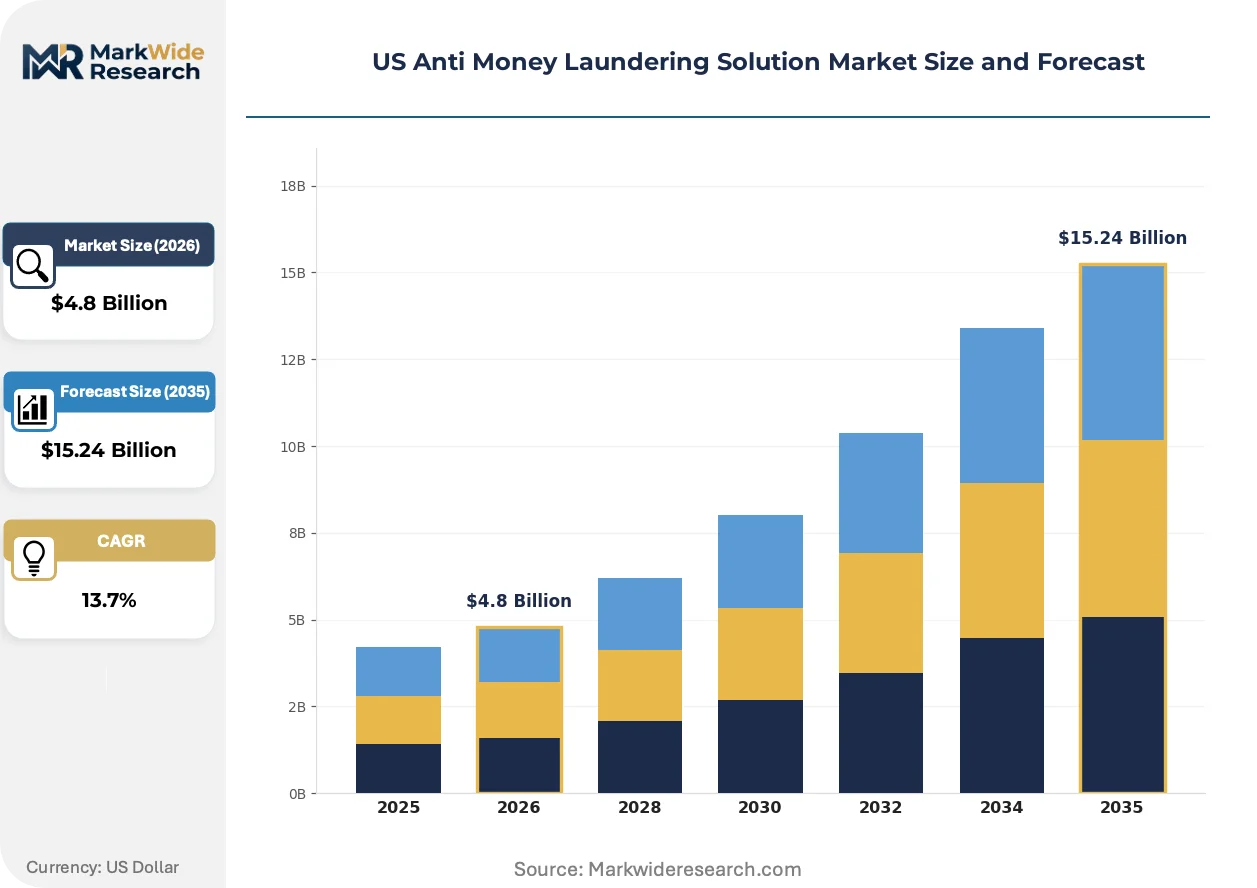
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Transaction Monitoring, Customer Due Diligence, Risk Assessment, Compliance Management Deployment Model: On-premises, Cloud-based, Hybrid, Managed Services End User: Financial Institutions, Insurance Companies, Cryptocurrency Exchanges, Government Agencies Functionality: Reporting, Analytics, Alerting, Integration |
| Companies Covered | Oracle Corporation, NICE Actimize, LexisNexis Risk Solutions, ACI Worldwide, Fiserv Inc, SAS Institute, Inc., Cognizant Technology Solutions, Experian Information Solutions, Inc., FICO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Anti Money Laundering Solution Market Evolving Landscape
Machine learning architectures are displacing static rule libraries across transaction monitoring stacks. This shift compresses detection latency while elevating model governance requirements.
Graph neural networks for entity link analysis are expanding into real-time payment screening at tier-one institutions. These models map beneficial ownership webs and detect mule account formations invisible to linear scoring. The technology is compressing investigation cycle times from days to hours.
FinCEN's forthcoming beneficial ownership database integration is forcing institutions to rebuild customer onboarding pipelines. Banks must reconcile corporate registry data with existing KYC records before regulatory deadlines. Large national banks with complex correspondent networks face the steepest compliance architecture challenges.
Subscription pricing for cloud-native platforms is displacing perpetual license models among regional banks. These institutions prioritize operational expenditure flexibility over capital-intensive on-premises deployments. The shift is most visible in the Southeast and Midwest, where mid-tier institutions dominate the banking landscape.
US Anti Money Laundering Solution Market Segmentation
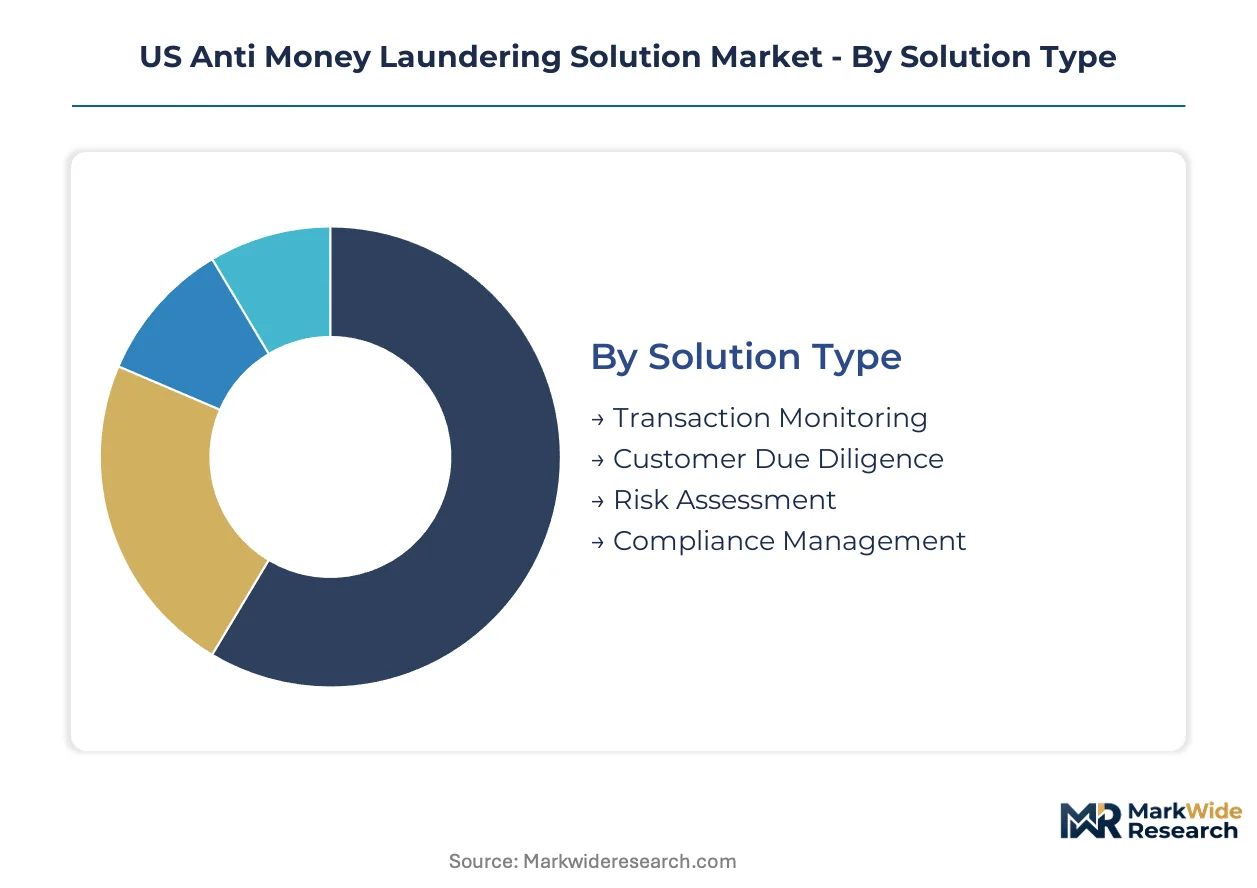
Segmentation in the US Anti Money Laundering Solution Market reveals how procurement priorities diverge across compliance maturity levels. Banks with established risk frameworks prioritize modular upgrades, while newer entrants demand pre-integrated suites that compress deployment timelines.
Solution Type:
Standardization dominates transaction monitoring through regulator-mandated rule libraries, while risk assessment modules retain customization for institution-specific risk appetites.
- Transaction Monitoring:Real-time screening engines process wire transfers and ACH flows against suspicious activity typologies. Large national banks with complex cross-border footprints drive procurement here as FinCEN enforcement elevates surveillance standards.
- Customer Due Diligence:Perpetual KYC refresh cycles automate identity verification and beneficial ownership validation. Regional banks in the Southeast and Midwest concentrate demand as they modernize legacy onboarding pipelines.
- Risk Assessment:Scoring models calibrate customer risk ratings against geography, product usage, and entity relationships.
- Compliance Management:Case management and regulatory reporting workflows streamline SAR filing and audit documentation.
Leading the category by volume: Transaction Monitoring. Growing fastest: Customer Due Diligence.
Deployment Model:
Cost tier stratification separates capital-constrained regional banks from tier-one institutions maintaining on-premises control over sensitive transaction data.
- Cloud-based:SaaS-native platforms deliver elastic compute for transaction volume spikes without infrastructure overhead. Mid-tier institutions prioritize operational expenditure flexibility over capital-intensive deployments.
- On-premises:Database-anchored installations at major banks satisfy data residency requirements and model risk governance protocols. Oracle Corporation leverages existing infrastructure relationships to defend this tier.
- Hybrid:Sensitive screening workloads remain on-premises while analytics layers migrate to cloud environments.
- Managed Services:Third-party operation of alert investigation queues addresses analyst workforce turnover at smaller institutions.
Cloud-based deployments are expanding most quickly among state-chartered banks. On-premises retains dominance at federally regulated institutions with correspondent banking exposure.
End User:
Application intensity varies by regulatory scrutiny exposure, with banking regulators imposing the strictest examination schedules.
- Financial Institutions:Banks and credit unions command the largest procurement volumes as BSA/AML program examinations intensify. FinCEN enforcement actions against compliance deficiencies accelerate replacement cycles.
- Cryptocurrency Exchanges:Virtual asset service providers face emerging Travel Rule obligations and state money transmitter licensing. These entities represent the steepest expansion trajectory as regulatory perimeter expansion continues.
- Insurance Companies:Life insurers and property-casualty carriers deploy AML screening for premium financing and claims payment anomalies.
- Government Agencies:Federal and state law enforcement units utilize analytics platforms for financial crime investigation support.
Financial Institutions anchor procurement volume. Cryptocurrency Exchanges are gaining share fastest as regulatory clarity emerges.
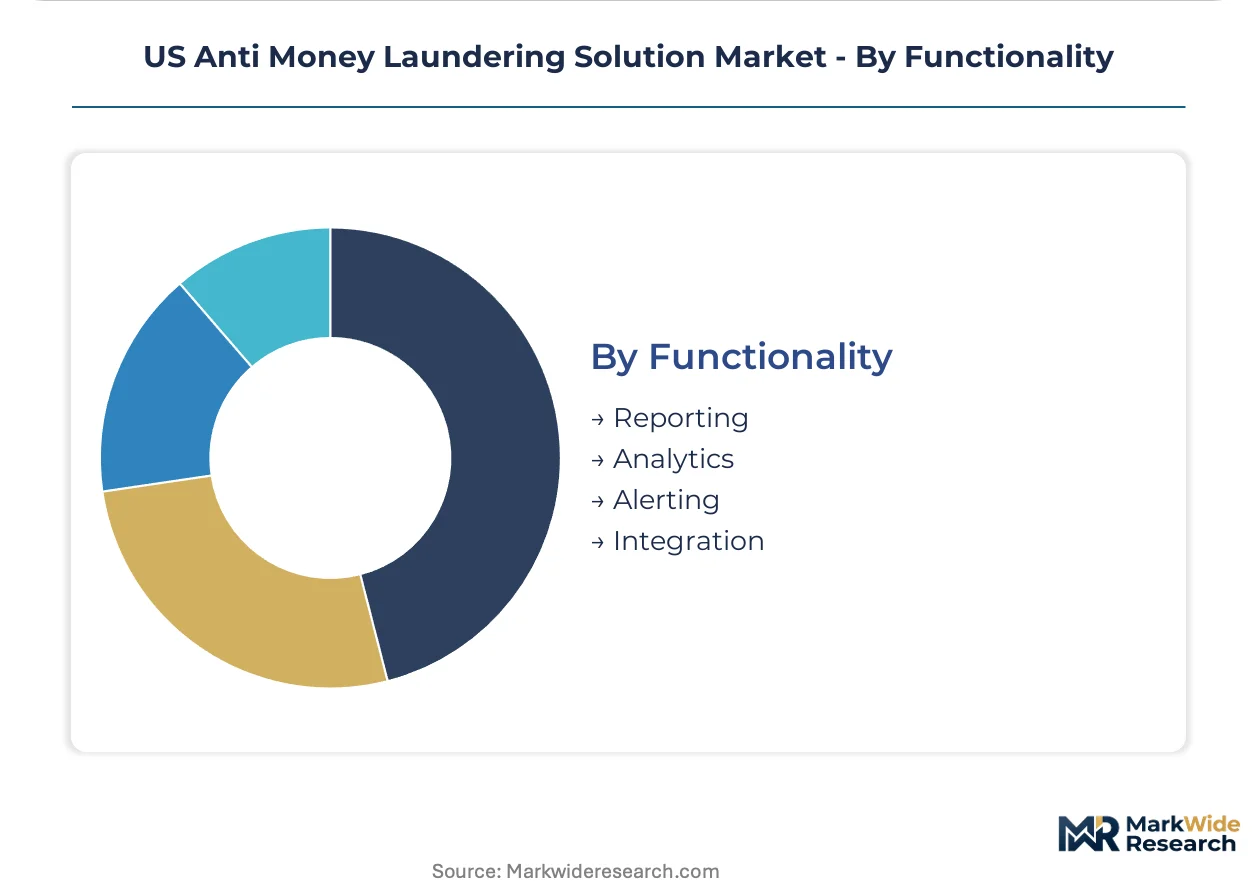
Functionality:
Margin concentration follows automation depth, with analytics commanding premium pricing against commoditized alerting layers.
- Analytics:Machine learning scoring and network graph visualization compress investigation cycle times from days to hours. Tier-one institutions prioritize these capabilities for complex correspondent banking relationships.
- Alerting:Real-time notification engines escalate suspicious patterns to investigation queues. False-positive management remains the primary operational constraint across all deployment scales.
- Reporting:Automated SAR generation and regulatory filing workflows satisfy FinCEN documentation requirements.
- Integration:API connectivity with core banking systems and third-party data providers reduces manual data reconciliation.
Analytics functionality leads by revenue contribution. Integration capabilities are climbing fastest as open banking standards proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center density in Northern Virginia anchors procurement intensity for AML infrastructure across the United States. Financial institutions cluster compliance operations near these compute hubs to minimize transaction screening latency.
Northeast Corridor
Wall Street banks and Boston asset managers drive demand for real-time transaction monitoring. FinCEN enforcement actions against New York-chartered institutions compress replacement cycles for legacy screening platforms. Manhattan and Boston compliance centers prioritize cloud-native deployments to shed mainframe dependencies.
Southeast
Charlotte and Atlanta regional banks modernize customer due diligence pipelines amid FinCEN beneficial ownership deadlines. State banking regulators in North Carolina and Georgia harmonize examination standards that favor integrated platform procurement. Miami correspondent banking operations face heightened scrutiny for cross-border wire screening.
Midwest
Chicago and Minneapolis money center banks consolidate fragmented point solutions into enterprise AML suites. OCC examination priorities elevate model risk governance requirements for AI-driven transaction scoring. Detroit credit unions adopt managed services to address analyst workforce turnover.
Texas
Dallas and Houston energy banks deploy enhanced due diligence for oil and gas sector clients. FinCEN's correspondent banking mandates force upgrades to transaction monitoring infrastructure serving Latin American trade flows. Austin fintechs experiment with graph neural networks for entity link analysis.
Pacific Coast
San Francisco and Los Angeles institutions lead cryptocurrency exchange surveillance adoption. California state regulators impose Travel Rule obligations ahead of federal timelines. Seattle cloud providers anchor SaaS-native compliance platform delivery for regional banks shedding legacy systems.
US Anti Money Laundering Solution Market Competitive Landscape
Vendor consolidation dominates the current landscape as tier-one institutions abandon fragmented point solutions. The market structure concentrates around database-anchored incumbents, specialized risk-scoring boutiques, and SaaS-native challengers. Three archetypes prevail: infrastructure-leveraged platforms, algorithm-specialized vendors, and data-asset-driven screeners. M&A activity and cloud migration partnerships constitute the dominant competitive moves as procurement patterns shift toward integrated enterprise deployments.
Within the infrastructure-leveraged tier, Oracle Corporation and Fiserv Inc occupy positions anchored by existing database relationships at major banks. NICE Actimize exemplifies the algorithm-specialized archetype through its focus on transaction monitoring risk-scoring. These three entities represent the competitive core as regional banks accelerate cloud migration and tier-one institutions defend on-premises control over sensitive transaction data.
| Leading Market Players |
|---|
| Oracle Corporation |
| NICE Actimize |
| LexisNexis Risk Solutions |
| ACI Worldwide |
| Fiserv Inc |
| SAS Institute, Inc. |
| Cognizant Technology Solutions |
| Experian Information Solutions, Inc. |
| FICO |
| Others |
Value Network & Pricing Analysis
Large national banks with complex cross-border transaction footprints concentrate procurement volume and anchor subscription pricing for cloud-native AML platforms. Their demand for real-time surveillance infrastructure shapes vendor bundling strategies across the compliance technology stack.
Pricing Analysis
Managed investigation services bundled with core platform licenses command premium positioning against unbundled software-only tiers. Three-tier pricing structure across premium, standard, and economy levels separates tier-one institutions requiring dedicated model governance from regional banks accepting shared infrastructure. Price differentiation stems from customization depth and FinCEN examination support levels. Pricing pressure intensifies as SaaS-native challengers undercut Oracle Corporation's database-anchored deployments. Mid-tier state-chartered institutions exhibit highest price sensitivity, while federally regulated correspondent banks prioritize control over cost.
Supply Chain Analysis
Proprietary data asset supply rests on LexisNexis Risk Solutions and Experian Information Solutions anchoring identity verification layers with exclusive watchlist feeds. Specialized risk-scoring algorithm development draws from machine learning engineering talent concentrated in Northern Virginia and Seattle tech corridors. Cloud compute infrastructure feeds from Amazon Web Services and Microsoft Azure data center density in Ashburn and Quincy facilities. Single-source vulnerability in beneficial ownership registry data creates exposure as FinCEN builds federal database integration. Distribution runs through direct enterprise sales teams serving tier-one banks and channel partners reaching regional institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Anti Money Laundering Solution Market operates as a vertical-integration race where control over proprietary data assets determines competitive durability. Players are pursuing downstream capture of alert investigation workflows to deepen platform stickiness.
For Market Incumbents: Deploy graph neural network capabilities to defend against SaaS-native challengers encroaching on transaction monitoring share. Consolidate fragmented point solution vendors before regional banks complete cloud migration cycles. FinCEN's beneficial ownership database integration deadline threatens incumbents slow to rebuild onboarding pipelines. Deepen vertical integration into unstructured data processing for adverse media extraction to sustain margin pools in customer due diligence. For New Entrants and Emerging Players: FinCEN's Beneficial Ownership Information reporting requirements in the United States open a window for specialized entity resolution tools targeting mid-tier banks racing compliance deadlines. Cryptocurrency exchange surveillance represents the most penetrable segment as state money transmitter licensing expands regulatory perimeter. White-space exists in natural language processing for legal filing extraction during KYC refresh cycles. Go-to-market through managed services partnerships addresses analyst workforce turnover pain points at credit unions. For Investors and Strategic Acquirers: The window for entry favors algorithm-specialized boutiques with demonstrated model risk governance frameworks. Long-term viability hinges on recurring revenue depth from perpetual KYC refresh cycles rather than one-time transaction monitoring deployments. Target acquisition archetypes include SaaS-native platforms serving Southeast and Midwest regional banks. Watch FinCEN enforcement action velocity as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies historically siloed compliance workflows for FinCEN beneficial ownership deadlines. |
| Acquisition of Specialist Firm | Captures graph neural network talent for real-time entity link analysis capabilities. |
| Strategic Partnership | Links cloud providers with regional banks shedding legacy mainframe dependencies. |
| Geographic Expansion | Targets Southeast state-chartered institutions harmonizing examination standards. |
| Product Launch | Introduces managed investigation services addressing analyst workforce turnover. |
Research Methodology
Multi-period observation of vendor consolidation patterns and cloud migration timelines anchored the trend analysis, supplemented by interviews with compliance technology officers at tier-one banks, state banking regulators, AML program directors, and SaaS platform engineers. Secondary validation drew from FinCEN enforcement action databases, OCC examination priority publications, SEC 10-K disclosures from financial technology vendors, and state money transmitter licensing records. Bottom-up triangulation across deployment model adoption rates converged with top-down market sizing against BSA/AML program expenditure benchmarks.
Input-output matrices mapped transaction volume growth against regulatory mandate implementation schedules across the projection horizon. Segmentation dimensions modeled include solution type, deployment architecture, end-user category, and functionality depth. CAGRs were derived from curve-fitting approaches against historical procurement cycle data and regulatory deadline compression effects. Forecast inputs incorporated correspondent banking relationship complexity indices and cloud infrastructure capex disclosures from major providers.
The model assumes a particular technology adoption path for machine learning architectures displacing rule-based engines; alternative pathways for AI model risk governance scrutiny would alter the outlook. Forecasts reflect assumptions regarding FinCEN enforcement continuity and state banking regulator coordination durability. Regulatory deadline delays or beneficial ownership database integration setbacks represent specific revision risks. A small set of named triggers—enforcement action velocity, cloud migration completion rates, and analyst workforce turnover metrics—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
United States Sales Tax Compliance Software Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
Global GDPR Services Market
Regulatory Compliance Technology
General Data Protection Regulation (GDPR) Market
Regulatory Compliance Technology
Compliance and Traceability Solutions Market
Regulatory Compliance Technology
Global Regulatory Technology (Regtech) Market
Regulatory Compliance Technology
Cross-Border Customs and Trade Compliance Orchestration Platforms Market
Regulatory Compliance Technology
Management System Certification Market
Regulatory Compliance Technology
Anti-Money Laundering Systems Market
Regulatory Compliance Technology
Aviation Compliance Monitoring Software Market
Regulatory Compliance Technology
Global Anti- Money Laundering Solutions Market
Regulatory Compliance Technology
GDPR Assessment Tools Market
Regulatory Compliance Technology
Regulatory Reporting Solutions Market
Regulatory Compliance Technology
Regulatory Change Management Software Market
Regulatory Compliance Technology
Nordic Regulatory Affairs Market
Regulatory Compliance Technology
Regulatory Information Management System Market