
 Management System Certification Market | 2026-2036
Management System Certification Market Size, Share, and Industry Trends Forecast 2026-2036
Management System Certification Market Outlook
Cloud-based audit documentation is realigning how certification bodies price and deliver verification services. SGS SA leverages its global laboratory network to anchor integrated quality-environment-safety offerings. Bureau Veritas SA competes through specialized cybersecurity certification extensions that differentiate its ISO 27001 practice.
Management system certification constitutes a third-party attestation process where accredited bodies evaluate organizational compliance against published standards such as ISO 9001 quality management or ISO 14001 environmental management, typically involving document review, on-site surveillance, and periodic recertification audits to verify sustained conformance. The primary commercial purpose is to reduce buyer risk, unlock supply chain eligibility, and satisfy regulatory or tender prequalification requirements. ISO 9001 certification among manufacturing firms represents the mature revenue base where margin pools have compressed due to commoditized audit execution. ISO 27001 within information technology verticals is expanding fastest as enterprise ransomware exposure intensifies demand for information security attestation.
FDA quality system regulation for medical device manufacturers, OSHA workplace safety mandates, and the SEC climate disclosure rules collectively expand the addressable base for multi-standard certification services in the United States. ISO management standards themselves function as de facto market access requirements, with procurement teams at large enterprises frequently excluding uncertified suppliers from bidding processes. Stakeholders must monitor whether accreditation bodies can expand auditor capacity quickly enough to prevent certification backlogs from constraining revenue conversion.
Market Dynamics
Cloud-based audit documentation platforms are compressing certification cycle times and forcing traditional bodies to restructure pricing models around subscription-based verification workflows rather than per-audit fees.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must demonstrate algorithmic governance through integrated management system audits, expanding demand for multi-standard certification bundles that combine ISO 27001 with quality and environmental attestations.
- Automotive supplier concentration in Germany:Tier-1 manufacturers require simultaneous ISO 9001, ISO 14001, and IATF 16949 certification as a contractual precondition, creating captive demand for bundled verification services.
- Remote audit technologies:Video-enabled surveillance and blockchain-anchored documentation are reducing auditor travel requirements and enabling certification bodies to scale capacity across dispersed client footprints.
Market Restraints
- Accreditation body concentration:Five major national accreditation bodies control over 80% of global recognition agreements, creating bottlenecks when auditor training programs cannot expand capacity quickly enough.
- Commoditized ISO 9001 execution:Mature manufacturing demand has compressed audit margins to near-cost levels, forcing certification bodies to subsidize quality management verification through higher-margin specialty standards.
- Regulatory fragmentation across jurisdictions:Mutual recognition agreements between national accreditation bodies remain incomplete, requiring duplicate audits for multinational enterprises operating across Brazil ANVISA, Saudi SFDA, and Health Canada jurisdictions.
Strategic Opportunities
- Underpenetrated healthcare vertical in North America:FDA quality system regulation for medical device manufacturers creates a regulatory tailwind for ISO 13485 certification services that remains underexploited by generalist certification bodies.
- Cybersecurity certification convergence:Integration of ISO 27001 with SOC 2 and NIST frameworks creates white space for unified information security attestation services targeting SaaS providers and financial technology firms.
- India PLI scheme manufacturing incentives:Production-linked incentive programs for electronics and pharmaceuticals are attracting multinational suppliers who require rapid ISO certification to qualify for government contracts.
Industry Challenges
- Auditor talent scarcity:Certification bodies face acute shortages of dual-qualified professionals capable of conducting integrated audits across quality, environmental, and information security standards simultaneously.
- Legacy system integration friction:Enterprises with decades of paper-based quality management documentation struggle to migrate records into cloud audit platforms without disrupting ongoing certification maintenance cycles.
- Recertification timeline compression:Three-year recertification windows create revenue concentration risk for certification bodies when economic downturns trigger client attrition in synchronized waves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Management System Certification Market |
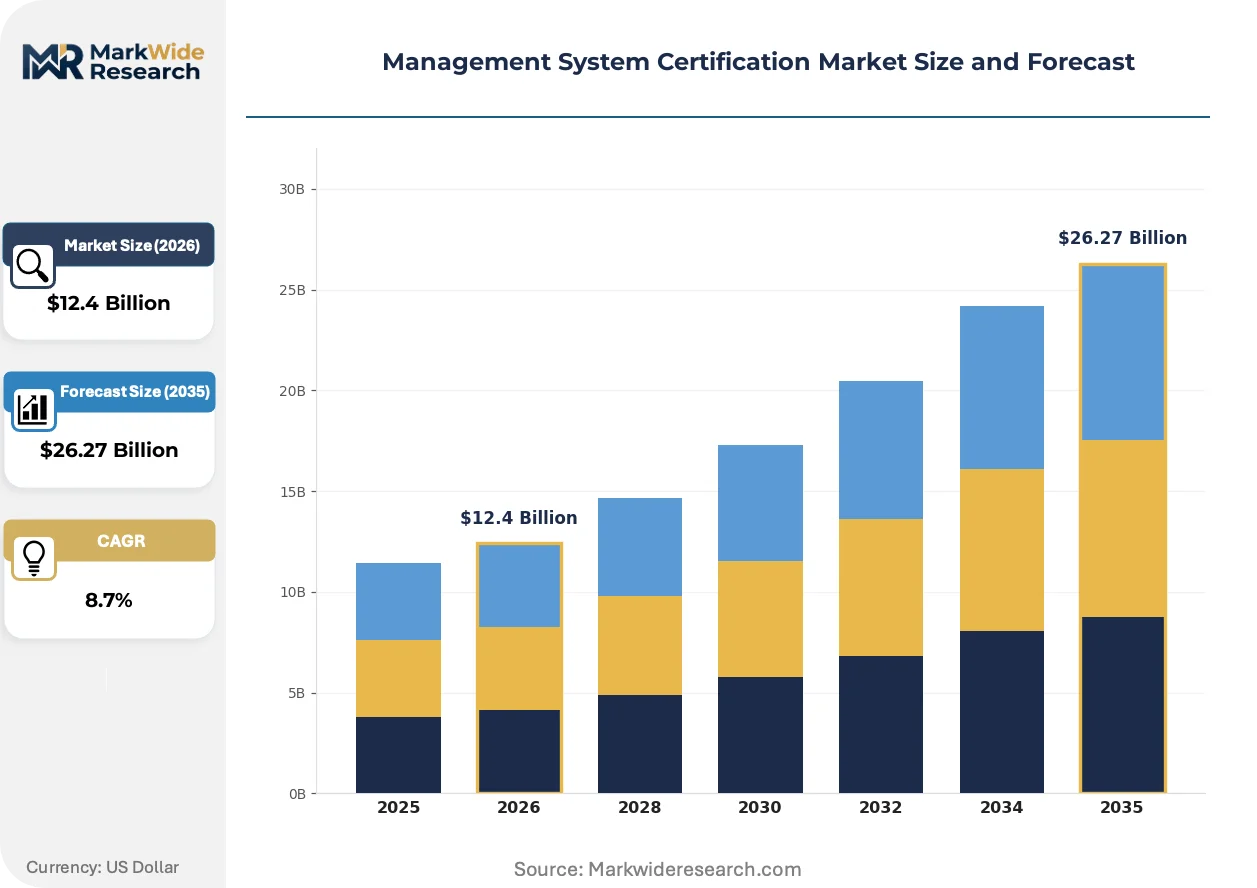
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Certification Type: ISO 9001, ISO 14001, ISO 45001, ISO 27001 Industry Vertical: Manufacturing, Healthcare, Information Technology, Education Service Type: Consulting, Training, Auditing, Compliance Target Audience: SMEs, Large Enterprises, Non-profit Organizations, Government Agencies |
| Companies Covered | Intertek Group plc, TÜV Rheinland AG, SGS SA, Lloyd's Register Group Limited, BSI Group, Bureau Veritas SA, TÜV SÜD AG, DEKRA SE, DNV AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Management System Certification Market Strategic Shifts
Digital verification infrastructure is displacing document-heavy audit protocols and enabling real-time compliance monitoring that threatens traditional periodic surveillance models.
Blockchain-anchored audit trails are unifying document authentication, timestamp verification, and immutable record-keeping into single-platform workflows. Pharmaceutical manufacturers and medical device firms in FDA-regulated environments are adopting these systems fastest to satisfy 21 CFR Part 11 electronic records requirements. This technology is unifying previously separate document control, training records, and corrective action tracking into continuous compliance dashboards that reduce auditor on-site time by half.
CSRD disclosure rules in Europe are mandating double materiality assessments that require certified sustainability data across supply chains. Large enterprises must obtain limited assurance on environmental metrics by 2026, expanding demand for ISO 14001 extensions that incorporate greenhouse gas verification protocols. Automotive suppliers in Germany and France are responding by pre-qualifying certification bodies with climate-specific auditor competencies before contract award.
Buyer concentration among procurement teams at Fortune 500 manufacturers is shifting supplier qualification criteria toward multi-standard certification as a non-negotiable bidding threshold. Small and mid-sized component vendors in industrial equipment and electronics distribution channels are losing contract access to certified competitors. This pattern is most visible in US and German manufacturing clusters where original equipment manufacturers have centralized supplier quality functions and automated certification status verification through third-party databases.
Management System Certification Market Segmentation
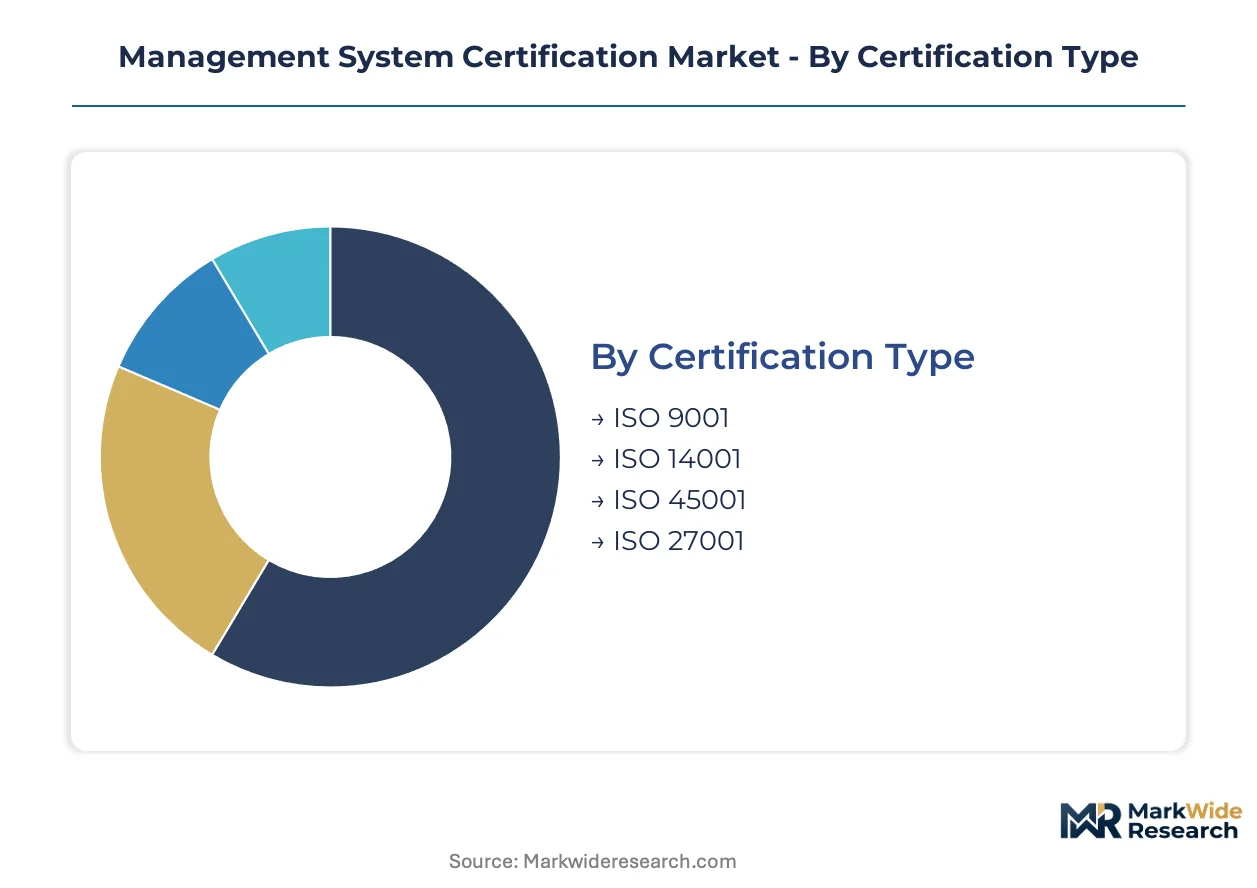
Management system certification demand fragments across four distinct dimensions, with certification type and industry vertical driving the largest revenue pools. Understanding how these segments interact reveals where accreditation bodies can escape commoditized audit pricing and capture premium verification margins.
Certification Type:
Volume concentration sits with mature quality standards, while premium pricing attaches to newer security and safety attestations.
- ISO 9001:Quality management certification requiring documented process controls, management review, and continuous improvement protocols. Manufacturing procurement teams in Germany and the United States treat this as a non-negotiable supplier threshold, though audit margins have compressed to near-cost levels due to commoditized execution.
- ISO 14001:Environmental management attestation governing resource efficiency, pollution prevention, and legal compliance. European automotive suppliers in Stuttgart and Wolfsburg require this alongside quality certification, with CSRD disclosure rules expanding demand for greenhouse gas verification extensions.
- ISO 45001:Occupational health and safety certification built on hazard identification and worker participation frameworks. Healthcare providers across the United States are expanding adoption to satisfy OSHA workplace safety mandates.
- ISO 27001:Information security management attestation covering risk assessment, access controls, and incident response. SaaS providers and financial technology firms in London and New York represent the steepest expansion trajectory as ransomware exposure intensifies.
Mature deployment sits with ISO 9001. Newer deployment is concentrated in ISO 27001.
Industry Vertical:
Application context determines audit complexity and recertification frequency, with regulated industries commanding sustained verification spending.
- Manufacturing:The foundational revenue base spanning automotive, electronics, and industrial equipment subsectors. Tier-1 suppliers in Germany require simultaneous ISO 9001, ISO 14001, and IATF 16949 certification as contractual preconditions.
- Healthcare:Medical device manufacturers and hospital systems subject to FDA quality system regulation and OSHA mandates. ISO 13485 certification for device makers remains underexploited by generalist bodies despite regulatory tailwinds.
- Information Technology:Enterprise software, cloud infrastructure, and cybersecurity vendors. SOC 2 and NIST framework convergence creates white space for unified information security attestation.
- Education:Universities and vocational training providers seeking operational efficiency and risk management credentials. Public procurement requirements in the United Kingdom and Australia drive adoption.
Contractual lock-in concentrates in Manufacturing. Regulatory pressure is intensifying fastest in Healthcare.
Service Type:
Margin structure varies sharply across the verification value chain, with upstream advisory services capturing premium pricing.
- Consulting:Gap analysis, documentation design, and implementation planning delivered before formal audit. Certification bodies in France and Switzerland bundle this with audit services to defend margin position.
- Training:Internal auditor certification and standard-specific competency development. India's PLI scheme manufacturing incentives are accelerating demand for rapid workforce qualification.
- Auditing:Document review, on-site surveillance, and recertification verification. Cloud-based platforms are compressing cycle times and forcing restructuring toward subscription pricing models.
- Compliance:Ongoing monitoring, regulatory update notification, and corrective action support. Pharmaceutical manufacturers in FDA-regulated environments purchase this as a continuous service.
Revenue concentration rests with Auditing. Fastest share gains are occurring in Consulting.
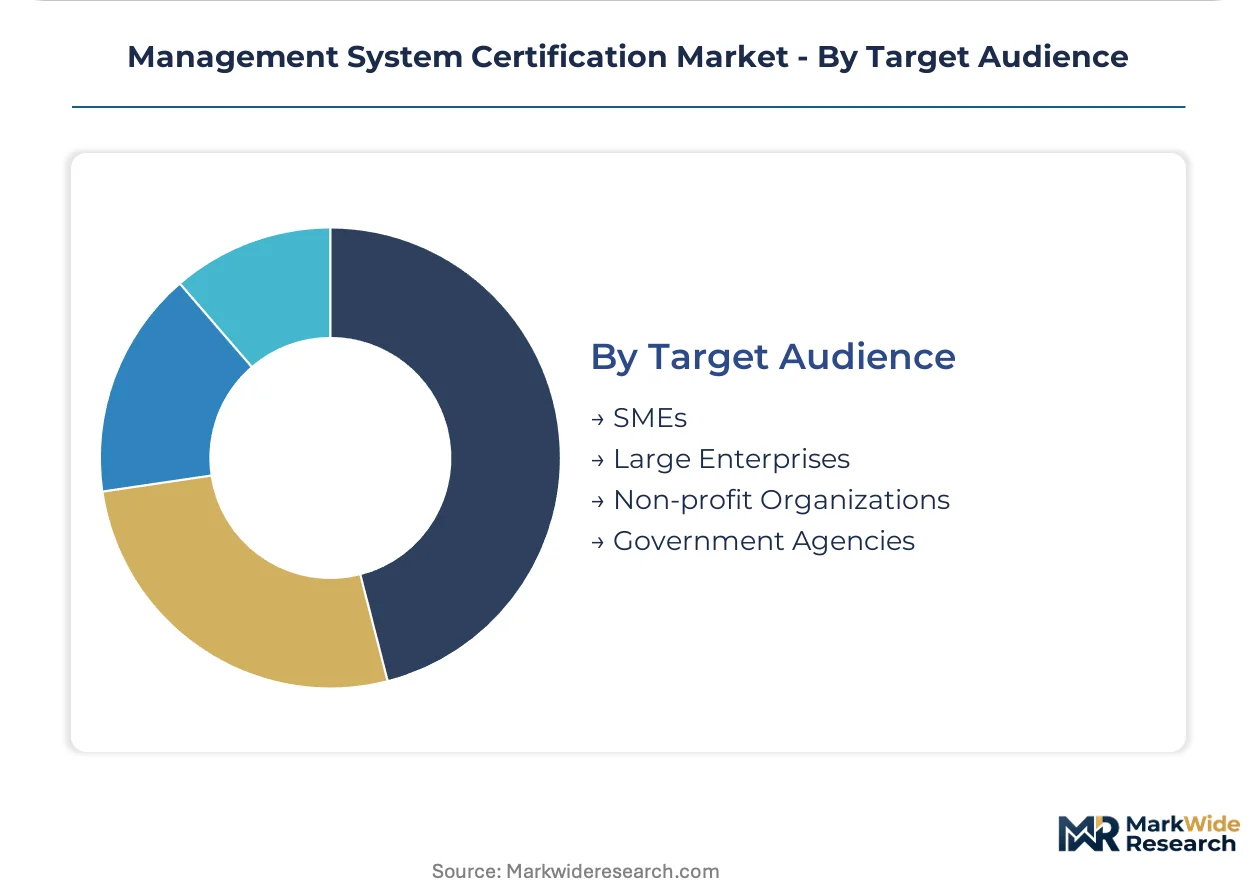
Target Audience:
Customer scale determines purchasing sophistication and bundle complexity, with large enterprises driving multi-standard integration.
- SMEs:Component vendors and specialized service providers seeking single-standard entry-level certification. Automated supplier databases at Fortune 500 manufacturers are excluding uncertified SMEs from bidding processes.
- Large Enterprises:Multinational manufacturers and technology platforms requiring integrated quality-environment-safety attestations. Duplicate audits across Brazil ANVISA, Saudi SFDA, and Health Canada jurisdictions inflate compliance costs.
- Non-profit Organizations:Healthcare systems, educational institutions, and development agencies pursuing operational credibility. Grant-making bodies in the United States increasingly require ISO certification for funding eligibility.
- Government Agencies:Defense contractors, public infrastructure operators, and regulatory bodies themselves. EU AI Act compliance mandates are pressing European public sector entities toward algorithmic governance certification.
Procurement leverage concentrates with Large Enterprises. Emerging demand is building fastest among Non-profit Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany where automotive suppliers bundle multi-standard certifications, while the United States and China expand fastest in healthcare and technology verticals respectively.
United States
Healthcare providers are expanding ISO 45001 adoption to satisfy OSHA workplace safety mandates. FDA quality system regulation for medical device manufacturers creates sustained demand for ISO 13485 certification services. Medical device clusters in Minneapolis and Boston are driving specialist auditor recruitment by certification bodies.
Germany
Tier-1 automotive manufacturers require simultaneous ISO 9001, ISO 14001, and IATF 16949 certification as contractual preconditions. The EU AI Act and CSRD disclosure rules are pressing enterprises toward integrated management system audits. Stuttgart and Wolfsburg supplier networks are pre-qualifying certification bodies with climate-specific competencies.
China
Electronics and automotive manufacturing incentives are accelerating ISO certification demand among export-oriented suppliers. NMPA medical device regulations and MIIT cybersecurity standards create dual compliance pressures. Shenzhen and Shanghai industrial zones are adopting cloud-based audit documentation platforms fastest.
India
PLI scheme manufacturing incentives for electronics and pharmaceuticals are attracting multinational suppliers requiring rapid ISO certification. CDSCO medical device regulations and BIS quality standards expand the addressable base for certification services. Gujarat and Maharashtra industrial corridors are building auditor training capacity to prevent certification backlogs.
United Kingdom
Financial technology firms and SaaS providers are driving ISO 27001 expansion as ransomware exposure intensifies. Public procurement requirements for universities and healthcare systems sustain demand for operational efficiency credentials. London and Southeast England technology clusters are converging ISO 27001 with SOC 2 frameworks.
Management System Certification Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated global networks commanding premium pricing in multi-standard bundles while regional specialists compete on single-standard execution speed. Five major national accreditation bodies control over 80% of global recognition agreements, creating tiered access to lucrative regulated industry verticals. Strategic archetypes include laboratory-anchored integrated service providers, cybersecurity-focused certification extenders, and automotive-specialist bundled verification firms. Dominant competitive moves involve geographic expansion through accreditation body partnerships and portfolio diversification into adjacent ESG attestation services.
Among European-headquartered integrated providers, SGS SA, Bureau Veritas SA, and TÜV Rheinland AG exemplify distinct strategic positioning archetypes. SGS SA represents the laboratory-network-anchored model leveraging global testing infrastructure to bundle quality-environment-safety offerings. Bureau Veritas SA occupies a position exemplifying specialized certification extension, particularly in cybersecurity attestation adjacent to core management system verification. TÜV Rheinland AG anchors the engineering-heritage archetype with deep automotive sector relationships. These three structures illustrate how scale, specialization, and sector focus differentiate competitive positioning without requiring identical service breadth.
| Leading Market Players |
|---|
| Intertek Group plc |
| TÜV Rheinland AG |
| SGS SA |
| Lloyd's Register Group Limited |
| BSI Group |
| Bureau Veritas SA |
| TÜV SÜD AG |
| DEKRA SE |
| DNV AS |
| Others |
Value Chain & Pricing Dynamics
Auditor labor cost indices in Germany and Switzerland cascade through certification body pricing tiers, compressing margins on commoditized ISO 9001 audits while enabling premium capture for integrated quality-environment-safety bundles demanded by automotive suppliers.
Pricing Analysis
Volume concentrates in single-standard ISO 9001 audits where near-cost execution has eliminated pricing power, while margin pools attach to multi-standard bundles combining ISO 27001 with cybersecurity extensions. Price differentiation hinges on auditor specialization depth and geographic coverage breadth, with certification bodies in Stuttgart and Wolfsburg commanding premiums for climate-competent integrated audits. Pricing pressure stems from cloud-based documentation platforms enabling subscription models that displace per-audit fees. SMEs exhibit acute price sensitivity on entry-level certification, whereas Fortune 500 procurement teams prioritize multi-standard coverage over unit cost.
Supply Chain Analysis
Reverse-logistics flows for auditor redeployment and training material redistribution concentrate certification body operational leverage in Germany, the United States, and Switzerland, where accreditation body partnerships anchor market access. Raw material inputs center on specialized labor pools, accreditation licensing fees, and cloud infrastructure subscriptions. Supply chain risk rests on single-source vulnerability in auditor training pipelines controlled by five dominant national accreditation bodies. Distribution runs through direct enterprise sales teams for large accounts and channel partners for SME market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The management system certification market functions as a cost-of-compliance business where EU AI Act algorithmic governance mandates erect regulatory moats favoring accredited bodies with multi-standard auditor capacity.
For Market Incumbents: Deploy cloud-based subscription platforms to restructure revenue from episodic audits toward continuous compliance monitoring, defending against margin erosion in commoditized ISO 9001 execution. Reinforce auditor training pipelines in India and China to preempt capacity bottlenecks that constrain revenue conversion during demand surges from PLI scheme manufacturing incentives.
For New Entrants and Emerging Players: Begin with cybersecurity certification convergence targeting SaaS providers in London and New York, where ISO 27001-SOC 2 integration creates white space absent incumbent bundling. Pursue rapid accreditation partnerships with national bodies in Brazil and Saudi Arabia to capture multinational enterprise demand frustrated by regulatory fragmentation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with automotive sector relationships in Germany and healthcare regulatory expertise in the United States, where FDA quality system mandates sustain durable revenue streams. Monitor CSRD disclosure rule implementation timelines as the inflection signal for climate-attestation service expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Body Partnership | Secures market access in Brazil ANVISA and Saudi SFDA jurisdictions for multinational clients. |
| Cloud Platform Integration | Enables real-time compliance dashboards that reduce auditor on-site time for pharmaceutical manufacturers. |
| Cybersecurity Bundle Development | Captures ISO 27001-SOC 2 convergence demand from financial technology firms in London. |
| Automotive Specialist Acquisition | Deepens IATF 16949 auditor capacity for Tier-1 supplier contracts in Stuttgart and Wolfsburg. |
| Healthcare Regulatory Expansion | Builds ISO 13485 competence for FDA-regulated medical device clusters in Minneapolis and Boston. |
Study Parameters
Document review covered ISO accreditation body annual reports, FDA quality system guidance documents, and EU regulatory filings, complemented by interviews with certification body audit directors, automotive supplier quality managers, healthcare compliance officers, and cloud platform engineering leads. Secondary validation drew from SEC filings of listed verification services firms, customs data on cross-border auditor deployment, and trade association membership statistics. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Cross-referencing historical certification volume patterns against expert panel input shaped the analytical framework, with segmentation modeling across certification type, industry vertical, service tier, and customer scale. CAGRs were derived from regression analysis of auditor capacity expansion rates and regulatory mandate implementation schedules. Forecast inputs incorporated PLI scheme manufacturing incentive timelines and CSRD disclosure phase-in requirements.
Underlying measurement precision varies by segment; mature ISO 9001 markets carry tighter precision than emerging ISO 27001 verticals. Forecasts reflect documented assumptions about accreditation body training program expansion and mutual recognition agreement progression. Practitioners should monitor EU AI Act enforcement intensity and cloud audit platform adoption curves for early signals of structural shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
Regtech Software Market
Regulatory Compliance Technology
Global Anti- Money Laundering Solutions Market
Regulatory Compliance Technology
Global AML Software Market
Regulatory Compliance Technology
GDPR Assessment Tools Market
Regulatory Compliance Technology
US Anti Money Laundering Solution Market
Regulatory Compliance Technology
Regulatory Information Management System Market
Regulatory Compliance Technology
Cross-Border Customs and Trade Compliance Orchestration Platforms Market
Regulatory Compliance Technology
General Data Protection Regulation (GDPR) Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
Compliance Testing Solutions Market
Regulatory Compliance Technology
Nordic Regulatory Affairs Market
Regulatory Compliance Technology
United States Sales Tax Compliance Software Market
Regulatory Compliance Technology
Global Regulatory Technology (Regtech) Market
Regulatory Compliance Technology
Aviation Compliance Monitoring Software Market
Regulatory Compliance Technology
Regulatory Change Management Software Market
Regulatory Compliance Technology
Anti-Money Laundering Systems Market