
 Automotive Hub Motors Market | 2026-2036
Automotive Hub Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Hub Motors Market Outlook
The EU Green Deal is recalibrating the cost-of-entry calculus for European hub motor suppliers, forcing redesigns around embedded carbon tracking and circular material recovery. Robert Bosch GmbH leverages its systems integration heritage to bundle hub motors with brake-by-wire modules. Nidec Corporation anchors volume production through dedicated motor lines serving Asian electric two-wheeler OEMs. ZF Friedrichshafen AG differentiates via mechatronic packaging that shrinks unsprung mass penalties.
Automotive hub motors are electric traction motors integrated directly into a vehicle's wheel hub, eliminating driveshafts and enabling torque vectoring through independent wheel control with power densities exceeding 3 kW per kilogram. Their primary purpose is to simplify powertrain architecture while freeing cabin and chassis space for batteries or cargo. Permanent magnet variants capture the dominant share of value given rare-earth torque density advantages, though asynchronous designs gain traction in commercial vehicles where cost sensitivity outweighs peak efficiency. Direct drive technology leads unit shipments by removing gearbox maintenance, while regenerative braking integration deepens as smart control algorithms improve energy recovery rates.
The EPA tailpipe rules and China's MIIT dual carbon goals jointly compress the timeline for powertrain electrification, with NHTSA safety standards adding crashworthiness tests for in-wheel components. ISO 26262 functional safety certification now gates OEM qualification programs, extending development cycles by twelve to eighteen months for new entrants. Stakeholders must monitor how battery-electric platform standardization affects hub motor interface specifications across vehicle classes.
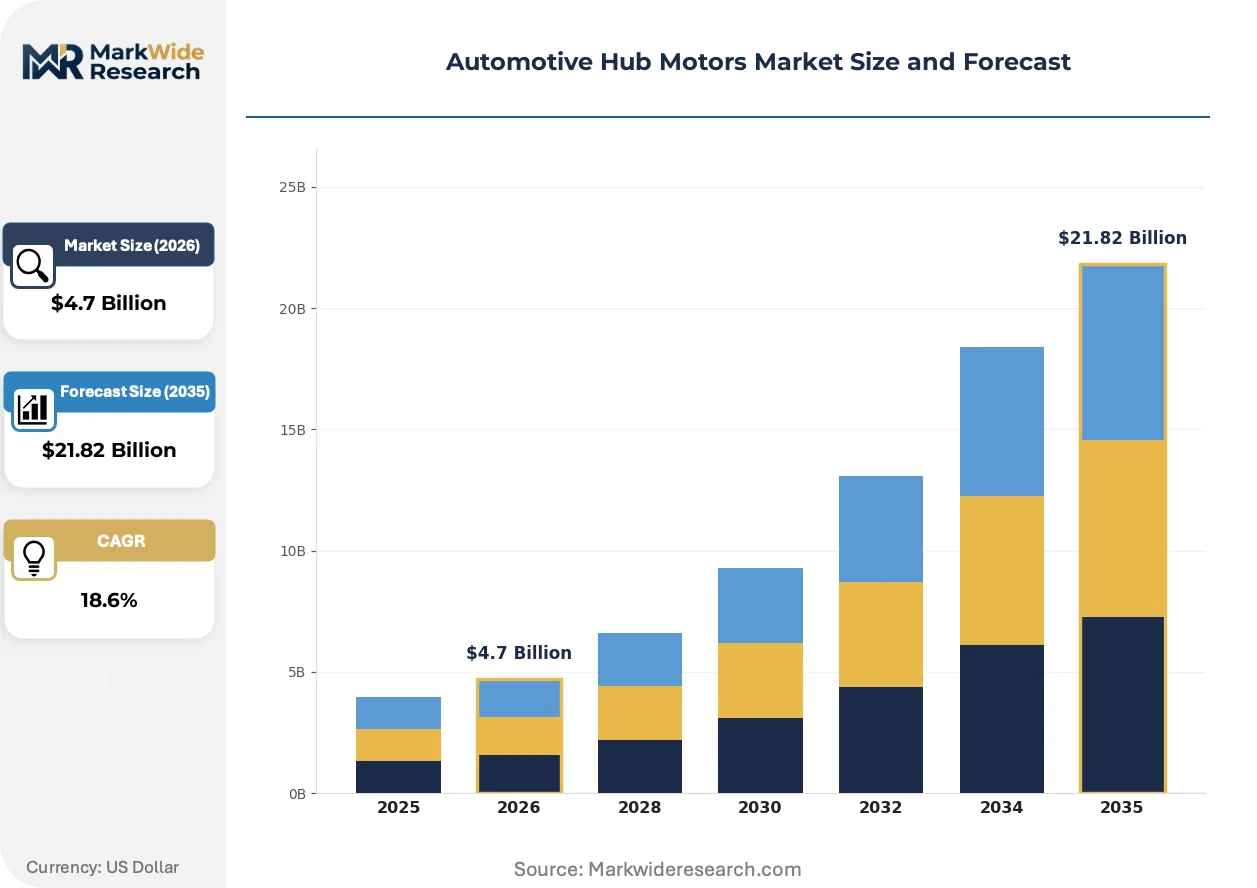
Market Dynamics
The EU Green Deal's embedded carbon tracking mandates are forcing powertrain suppliers to redesign hub motor architectures around circular material recovery, compressing qualification timelines and raising capital barriers for new entrants.
Growth Catalysts
- EU Green Deal carbon intensity benchmarks:Powertrain import rules tighten across European borders, accelerating OEM testing of integrated wheel-motor architectures in Germany's Stuttgart engineering corridor.
- China's MIIT dual carbon goals:Domestic electric vehicle manufacturers scale hub motor procurement to meet state-mandated fleet electrification timelines.
- Permanent magnet torque density advantages:Rare-earth motor variants capture dominant value share as power density thresholds exceed 3 kW per kilogram in passenger applications.
Market Restraints
- Neodymium supply concentration:Rare-earth magnet sourcing depends on concentrated upstream refining capacity, exposing cost volatility and geopolitical friction.
- Unsprung mass penalties:Wheel-integrated motors increase suspension loading, limiting ride quality in premium passenger segments and forcing compensatory chassis engineering.
- ISO 26262 certification gates:Functional safety qualification extends development cycles by twelve to eighteen months, freezing out capital-constrained entrants.
Strategic Opportunities
- Commercial vehicle asynchronous designs:Cost-sensitive fleet operators in North American logistics corridors favor induction motor variants where peak efficiency matters less than total cost of ownership.
- Regenerative braking algorithm convergence:Smart control systems integrating torque vectoring with energy recovery create new IP licensing potential for software-tier suppliers.
- India's PLI scheme for auto components:Domestic manufacturing incentives attract hub motor assembly investment serving two-wheeler and three-wheeler electrification.
Industry Challenges
- Thermal management engineering scarcity:In-wheel motor cooling system design requires specialized fluid dynamics expertise concentrated among legacy Tier-1 suppliers.
- Platform interface standardization delays:Battery-electric skateboard architectures lack unified hub motor mounting specifications, fragmenting R&D investment across incompatible OEM programs.
- Crashworthiness validation protocols:NHTSA safety standards for in-wheel components demand new structural testing regimes without established third-party laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Hub Motors Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushless, Synchronous, Asynchronous, Permanent Magnet End User: Electric Vehicle Manufacturers, OEMs, Aftermarket Providers, Tier-1 Suppliers Technology: Direct Drive, Regenerative Braking, Wireless Charging, Smart Control Application: Passenger Vehicles, Commercial Vehicles, E-Bikes, Robotics |
| Companies Covered | Robert Bosch GmbH, Nidec Corporation, ZF Friedrichshafen AG, Schaeffler AG, QS Motor, Magna International Inc., NTN Corporation, YASA Limited, Heinzmann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Hub Motors Market Strategic Shifts
Powertrain electrification timelines are compressing as regulatory carbon benchmarks tighten simultaneously across multiple jurisdictions, forcing convergence between motor design, thermal management, and vehicle control software.
Silicon carbide power electronics is modularizing inverter architectures for hub motor integration, enabling higher switching frequencies and reduced thermal losses. Tier-1 suppliers in Germany and Japan are adopting these modules for 2027 platform launches. This semiconductor transition is modularizing the boundary between motor and controller, allowing standardized motor housings to accommodate multiple inverter specifications.
The EPA tailpipe rules are tightening fleet-average emissions benchmarks through 2032, accelerating powertrain electrification commitments from Detroit manufacturers. This regulatory pressure forces redesign of light-truck architectures previously resistant to wheel-motor packaging. Heavy-duty pickup segments now face the most aggressive compliance recalibration, with engineering resources shifting from internal combustion refinement to electric axle development.
Fleet procurement is consolidating supplier relationships around integrated powertrain system houses capable of delivering motor-inverter-software bundles. Large commercial operators in North American logistics corridors now specify hub motor performance through total cost of ownership metrics rather than unit price. This buying-pattern shift is most visible in California's drayage truck electrification mandates, where lease structures bundle maintenance and energy costs into single contract vehicles.
Automotive Hub Motors Market Segmentation
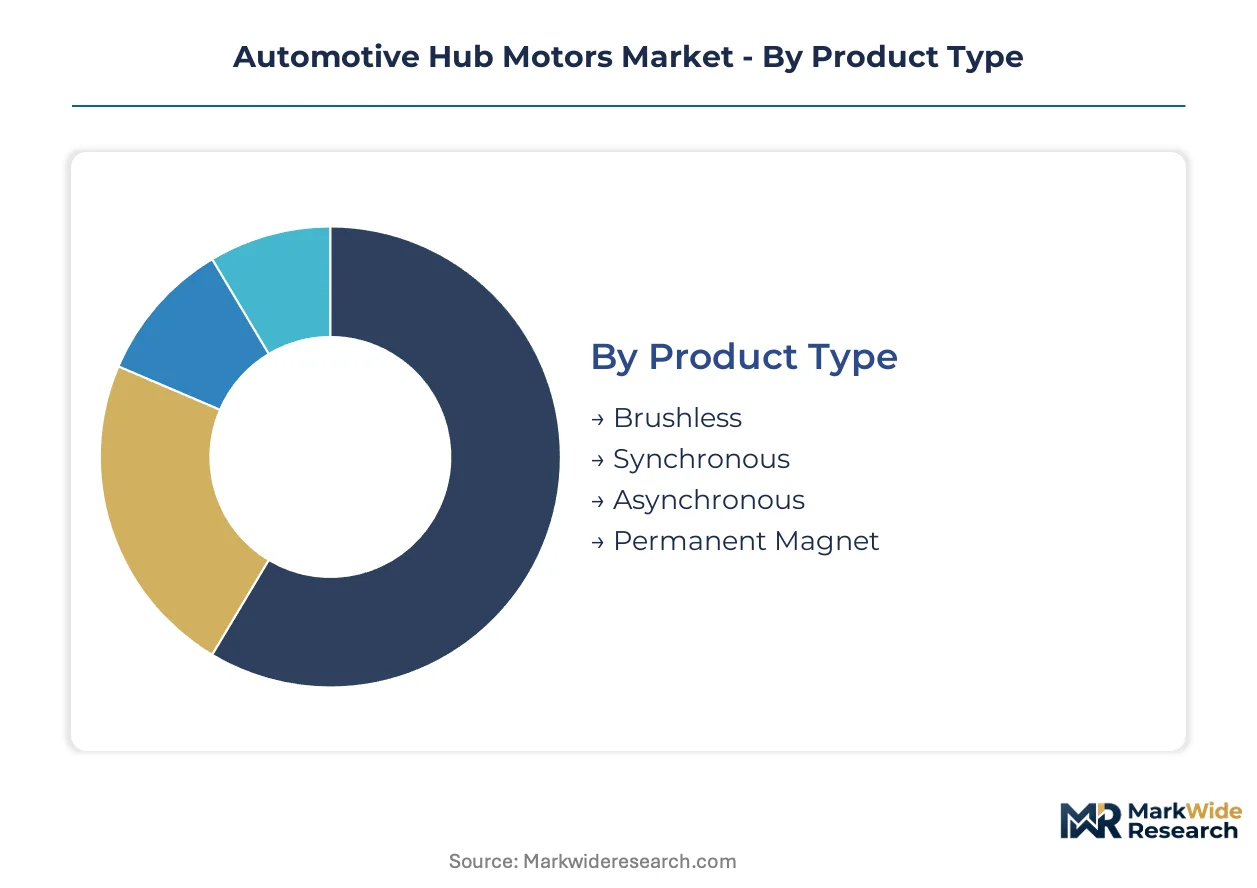
Hub motor architectures diverge sharply across powertrain integration strategies, with each segment demanding distinct thermal management, electromagnetic design, and control software stacks. Procurement patterns concentrate where platform standardization and regulatory compliance intersect.
Product Type:
Supply concentration in rare-earth refining capacity tilts manufacturing economics toward magnet-dependent designs, though induction alternatives gain traction where cost volatility exceeds efficiency premiums.
- Brushless:Eliminates mechanical commutation through electronic switching, reducing maintenance intervals. Demand clusters in German passenger EV programs where ISO 26262 functional safety certification gates supplier qualification.
- Synchronous:Rotor locks to stator field frequency, delivering precise torque vectoring for urban mobility platforms. China's MIIT dual carbon procurement timelines accelerate volume deployment in domestic two-wheeler electrification.
- Asynchronous:Induction rotor construction tolerates wider thermal excursions without demagnetization risk. Commercial fleet operators in North American logistics corridors favor total-cost-of-ownership predictability over peak efficiency.
- Permanent Magnet:Neodymium-iron-boron torque density exceeds 3 kW per kilogram, dominating premium passenger applications. Upstream concentrate in Chinese refining exposes European suppliers to carbon-border adjustment volatility under EU Green Deal tracking mandates.
Today's leader: Permanent Magnet. Tomorrow's challenger: Asynchronous.
End User:
Cost tier stratification separates integrated system houses from component vendors, with qualification timelines and capital requirements determining market access.
- Electric Vehicle Manufacturers:Direct procurement of hub motor-inverter bundles accelerates as skateboard platform standardization compresses supplier tiers. Volume commitments concentrate in China's state-mandated fleet electrification programs.
- OEMs:Stuttgart engineering corridor hosts integrated wheel-motor architecture testing for next-generation electric platforms. Embedded carbon tracking requirements under EU Green Deal reshape qualification protocols.
- Aftermarket Providers:Retrofit kits for light commercial vehicles expand where EPA tailpipe rules force accelerated compliance timelines. Service network density determines geographic penetration.
- Tier-1 Suppliers:Mechatronic packaging expertise commands premium positioning. Brake-by-wire module bundling creates defensive moats against pure-play motor manufacturers.
Electric Vehicle Manufacturers capture procurement volume. Tier-1 Suppliers capture margin expansion.
Technology:
Application intensity varies by duty cycle, with urban stop-start environments maximizing regenerative capture and highway cruising favoring direct-drive simplicity.
- Direct Drive:Gearbox elimination reduces maintenance burden and unsprung mass penalties. E-bike OEMs in India leverage PLI scheme incentives to scale domestic assembly.
- Regenerative Braking:Smart control algorithms integrate torque vectoring with energy recovery, creating IP licensing opportunities for software-tier suppliers. California drayage truck mandates bundle maintenance and energy costs into single contract structures.
- Wireless Charging:Inductive power transfer eliminates connector wear in autonomous logistics applications. Standardization gaps across OEM platforms fragment R&D investment.
- Smart Control:Silicon carbide inverter modularization enables higher switching frequencies with reduced thermal losses. German and Japanese Tier-1 suppliers target 2027 platform launches.
Direct Drive dominates unit shipments. Smart Control climbs the fastest.
Application:
Customer type differentiation separates fleet operators optimizing total cost of ownership from consumer buyers prioritizing ride quality and cabin space liberation.
- Passenger Vehicles:Torque vectoring through independent wheel control enables chassis design simplification. Premium segments absorb unsprung mass penalties through adaptive suspension engineering.
- Commercial Vehicles:Heavy-duty pickup electrification faces aggressive EPA compliance recalibration through 2032. Detroit manufacturers shift engineering resources from combustion refinement to electric axle development.
- E-Bikes:Asian two-wheeler OEMs anchor volume production through dedicated motor lines. Nidec Corporation's dedicated manufacturing capacity serves state-mandated electrification timelines.
- Robotics:Precision positioning requirements favor direct-drive torque density. Logistics automation in North American warehousing corridors specifies hub motors through operational uptime metrics rather than capital expenditure.
Passenger Vehicles anchor value capture. Commercial Vehicles represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electromagnetic engineering talent pools concentrate in Germany's automotive corridor, China's industrial heartland, and Japan's precision manufacturing clusters, anchoring regional development capacity.
Germany
Stuttgart engineering clusters test integrated wheel-motor architectures for next-generation electric platforms. EU Green Deal carbon intensity benchmarks force redesigns around embedded carbon tracking and circular material recovery. Baden-Württemberg hosts brake-by-wire bundling programs linking hub motors with chassis electronics.
China
Domestic electric vehicle manufacturers scale hub motor procurement to meet MIIT dual carbon fleet electrification timelines. Rare-earth refining concentration in Jiangxi and Inner Mongolia shapes magnet-dependent manufacturing economics. Yangtze River Delta OEMs anchor volume production through dedicated motor lines serving state-mandated programs.
United States
Detroit manufacturers shift engineering resources from combustion refinement to electric axle development under EPA tailpipe rules tightening through 2032. Heavy-duty pickup segments face aggressive compliance recalibration. Michigan-based Tier-1 suppliers develop mechatronic packaging to shrink unsprung mass penalties.
Japan
METI industrial policy supports silicon carbide inverter modularization for higher switching frequencies with reduced thermal losses. Tier-1 suppliers target 2027 platform launches integrating motor-controller boundaries. Nagoya precision manufacturing clusters specialize in thermal management fluid dynamics for in-wheel cooling systems.
India
PLI scheme incentives attract hub motor assembly investment serving two-wheeler and three-wheeler electrification. Tamil Nadu and Gujarat manufacturing corridors scale domestic production for Asian electric mobility OEMs. State-mandated electrification timelines compress supplier qualification windows.
Automotive Hub Motors Market Competitive Environment
The competitive structure tilts toward systems integration specialists with heritage in chassis electronics and powertrain bundling. Tier-1 automotive suppliers command premium positioning through mechatronic packaging expertise, while pure-play motor manufacturers compete on torque density specifications. Two dominant competitive moves define current positioning: brake-by-wire module bundling creates defensive moats against component specialists, and silicon carbide inverter partnerships reshape motor-controller interface specifications.
Among Germany-based diversified automotive suppliers, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify the systems integration archetype, leveraging chassis electronics heritage to bundle hub motors with adjacent control modules. Japan's Nidec Corporation occupies a position representing the dedicated motor manufacturer archetype, anchoring volume production through manufacturing scale. These three entities collectively illustrate the market's bifurcation between integrated powertrain houses and specialized motor fabricators.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Nidec Corporation |
| ZF Friedrichshafen AG |
| Schaeffler AG |
| QS Motor |
| Magna International Inc. |
| NTN Corporation |
| YASA Limited |
| Heinzmann GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Electric vehicle OEM procurement committees in Germany's Stuttgart corridor negotiate hub motor supply through bundled brake-by-wire and mechatronic packaging contracts, anchoring a project-based pricing model that rewards systems integration heritage over component torque density specifications.
Pricing Analysis
Bundled motor-inverter-software packages command premium positioning against unbundled component transactions favored by cost-sensitive Asian two-wheeler OEMs. Price differentiation separates ISO 26262-certified suppliers serving European passenger platforms from uncertified vendors in India's PLI-driven electrification programs. Cost compression in induction motor tiers is intensifying because commercial fleet operators in North American logistics corridors prioritize total cost of ownership over peak efficiency metrics. Aftermarket retrofit providers exhibit highest price sensitivity, while Tier-1 mechatronic integrators absorb margin pressure through brake-by-wire module bundling.
Supply Chain Analysis
Reverse-logistics flows for rare-earth magnet recovery are emerging under EU Green Deal circular material mandates, with European suppliers developing closed-loop neodymium refining partnerships to offset carbon-border adjustment exposure. Upstream concentrate in Chinese Jiangxi and Inner Mongolia refining capacity draws from Australian and Burmese rare-earth ore deposits, while silicon carbide semiconductor substrates feed from Japanese and German wafer fabrication. Single-source vulnerability in dysprosium and terbium heavy rare-earth sourcing exposes cost volatility. Distribution runs through dedicated motor lines serving state-mandated electrification programs in China and contract manufacturing clusters in Tamil Nadu and Gujarat.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hub motor assembly investment in India under PLI scheme incentives offers a geographic-arbitrage play against EU carbon-border compliance costs, with Tamil Nadu manufacturing corridors capturing margin expansion unavailable to European suppliers facing embedded carbon tracking mandates.
For Market Incumbents: Hedge neodymium price volatility through long-term offtake agreements with Australian rare-earth miners and accelerate silicon carbide inverter backward integration to defend margin position against pure-play motor manufacturers. Prioritize brake-by-wire certification investment to deepen defensive moats as NHTSA crashworthiness protocols tighten qualification windows.
For New Entrants and Emerging Players: The premium-to-economy price gap in commercial vehicle asynchronous designs offers white-space entry for induction motor specialists targeting North American logistics fleet procurement. India's two-wheeler electrification programs present the most penetrable geography, with domestic assembly partnerships under PLI incentives as the optimal go-to-market angle.
For Investors and Strategic Acquirers: Tier-1 automotive suppliers with chassis electronics heritage are the most active acquirer in this space, consolidating mechatronic packaging capabilities to capture margin expansion from bundled system sales. Five-to-ten year viability hinges on silicon carbide inverter integration competence. Target acquisition archetype: thermal management engineering specialists with in-wheel cooling system IP. The signal to watch is California drayage truck electrification mandate compliance timelines as fleet procurement inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces R&D fragmentation across incompatible OEM skateboard architectures in Germany and China. |
| Battery Supply Agreement | Secures cell allocation for integrated motor-inverter bundles serving state-mandated fleet programs. |
| Software-Defined Vehicle Investment | Enables torque vectoring algorithm licensing to OEMs seeking smart control differentiation. |
| Geographic Manufacturing Footprint | Positions assembly capacity in Tamil Nadu to capture PLI scheme incentives for Asian two-wheeler OEMs. |
| Charging Infrastructure Partnership | Links hub motor regenerative braking systems with wireless inductive power transfer standardization. |
Study Parameters
Direct dialogue with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and thermal management R&D specialists combined secondary validation from MIIT fleet electrification filings, EU Green Deal carbon intensity benchmarks, EPA tailpipe rule dockets, and vehicle production databases. Bottom-up unit shipment modeling triangulated against top-down powertrain electrification spend analysis across passenger, commercial, and two-wheeler segments.
Bottom-up volume builds aggregated hub motor content per vehicle across propulsion architectures, vehicle classes, and regional production clusters, then cross-referenced against top-down OEM capital expenditure disclosures and state-mandated electrification procurement timelines over the projection horizon. Segmentation dimensions modeled include motor topology, end-user tier, technology integration level, and application duty cycle. CAGRs derived from regression analysis of historical procurement patterns against regulatory compliance deadline compression, with silicon carbide adoption curves and rare-earth price volatility as key forecast inputs.
Caveats apply where NHTSA crashworthiness protocol finalization or EU carbon-border adjustment implementation could materially shift the outlook for in-wheel component qualification timelines and embedded carbon tracking compliance costs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
E-Bike Motor Market
Electric Motor
Europe Alternating Current (AC) Motor Market
Electric Motor
Global Two Wheeler Hub Motor Market
Electric Motor
Electric Drives Market
Electric Motor
Car Charger Market
Electric Motor
Automotive Electric Motors Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Electric Motor Sales Market
Electric Motor
Electric Vehicle Flat Wire Motor Market
Electric Motor
Positive Displacement Motor Market
Electric Motor
Electric Motorcycle Market
Electric Motor
Motors for Robot Body and Robot Wheels Market
Electric Motor
Australia Solar E-Bike Market
Electric Motor
Traction Motor Core Market
Electric Motor
Separately Excited Motor Market