
 Global Packaging Robot Market | 2026-2036
Global Packaging Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Global Packaging Robot Market Outlook
Pharmaceutical contract packaging is repositioning demand toward sterile, high-speed delta configurations with integrated vision verification. Fanuc Corporation leverages its CNC heritage to dominate precision motion control in cleanroom palletizing cells. ABB Limited anchors European pharmaceutical lines with collaborative robots certified under updated ISO 10218-2 protocols. Kuka Roboter GmbH sustains automotive parts packaging share through heavy-payload articulated systems with force-torque sensing.
Packaging robots are programmable manipulators equipped with servo-driven joints, end-of-arm tooling, and vision-guided positioning systems operating at cycle speeds exceeding sixty picks per minute, designed to automate primary packing, secondary case packing, and tertiary palletizing across high-volume manufacturing environments. Articulated robots occupy the largest installed base due to six-axis flexibility in dense factory layouts, while collaborative robots represent the fastest-expanding category as pharmaceutical and electronics end users retrofit existing lines without hard guarding. Delta robots concentrate margin pools in food and beverage applications where lightweight parallel kinematics enable sub-millimeter placement accuracy at sustained throughput rates.
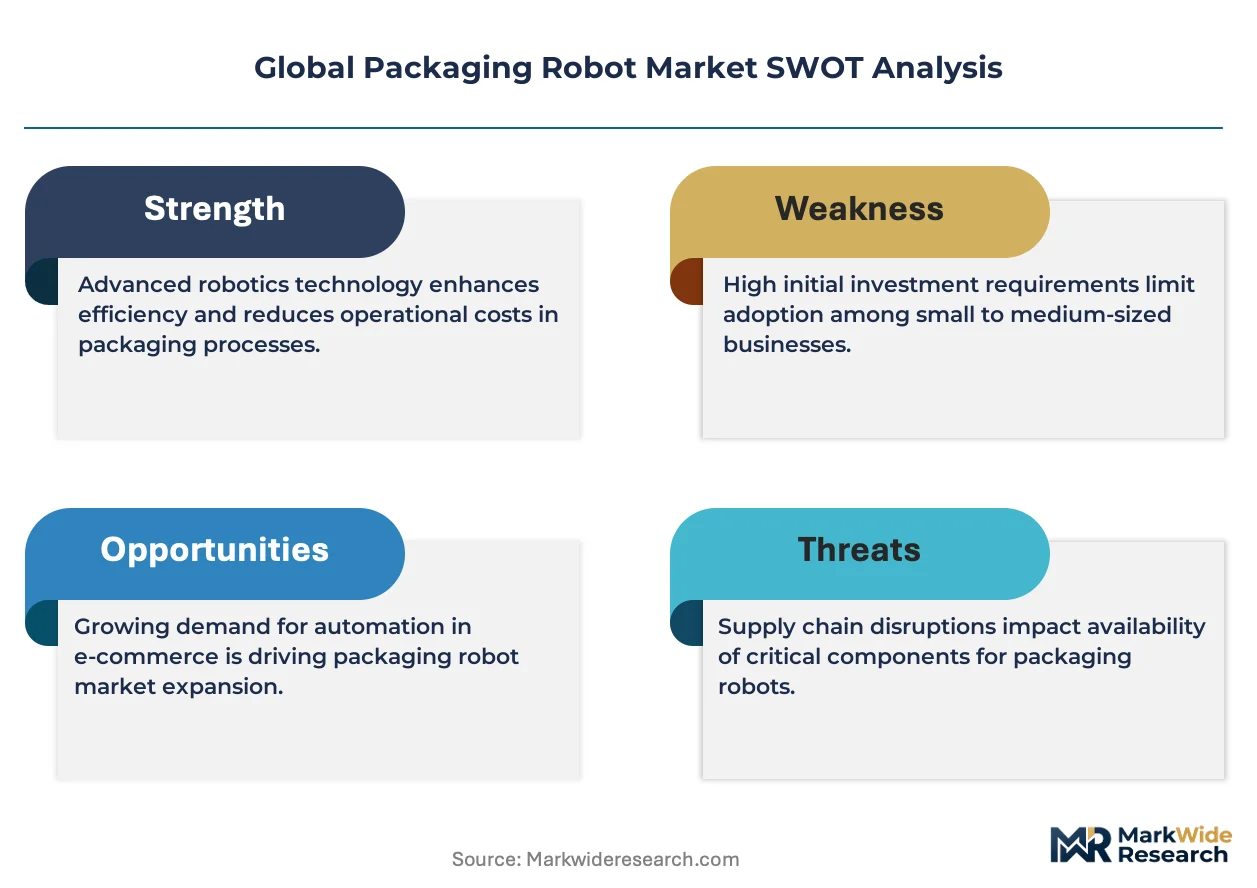
The EU Machinery Directive and ISO 10218 standards govern safety architecture and collaborative operation thresholds, while FDA validation requirements shape pharmaceutical robot qualification protocols in the United States. These frameworks elevate compliance costs for new entrants but create durable competitive moats for established suppliers with certified platform ecosystems. Stakeholders must monitor evolving CE marking requirements under the EU AI Act as machine learning-enabled vision systems proliferate in adaptive packaging workflows.
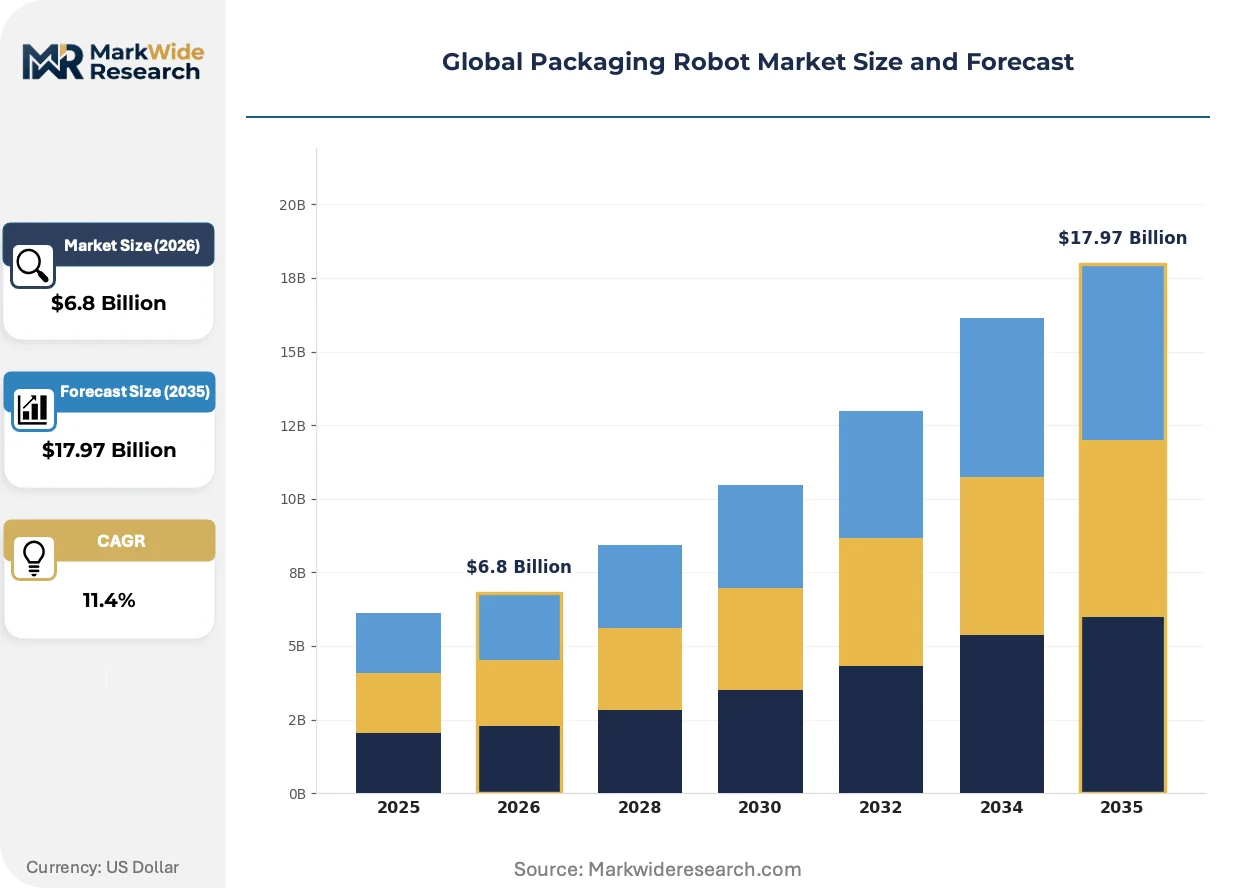
Market Dynamics
ISO 10218-2 collaborative operation protocols are compressing deployment timelines for pharmaceutical and electronics packagers retrofitting legacy lines without hard guarding infrastructure.
Growth Catalysts
- EU Machinery Directive:Updated CE marking requirements under the EU AI Act are accelerating certified platform upgrades for machine learning-enabled vision systems in adaptive packaging workflows.
- Food and beverage producers:Accelerating adoption of delta and articulated systems for hygienic handling is pulling parallel kinematics into high-throughput primary packing applications.
- Germany, Japan, and the United States:Concentrated demand from automotive component suppliers and pharmaceutical contract packagers retrofitting legacy lines is anchoring regional installation bases.
Market Restraints
- Servo motor and harmonic drive supply:Geographic concentration of precision motion component manufacturing in Japan and Germany creates input cost volatility and lead time extension risks.
- FDA validation requirements:Pharmaceutical robot qualification protocols in the United States impose 12-18 month certification timelines that elevate compliance costs for new entrants.
- Manual pick-and-place operations:Low-complexity secondary packing tasks in emerging manufacturing economies retain cost advantages against robotic deployment at current labor rates.
Strategic Opportunities
- India:PLI scheme incentives for electronics manufacturing and pharmaceutical contract packaging are creating greenfield automation demand in underpenetrated secondary packing lines.
- Convergence of collaborative robotics and force-torque sensing:Human-robot collaboration without hard guarding is opening retrofit opportunities in existing cleanroom pharmaceutical facilities.
- EU Green Deal:Circular packaging mandates and extended producer responsibility frameworks are driving demand for adaptive robotic systems capable of handling variable-format sustainable materials.
Industry Challenges
- Multi-axis motion programming:Scarce integration engineers capable of synchronizing delta kinematics with vision-guided positioning systems are extending deployment timelines for food and beverage packagers.
- Legacy PLC architecture:Proprietary communication protocols in existing palletizing lines create integration friction with open-architecture collaborative robot controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Packaging Robot Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, Collaborative Robots, Delta Robots, Cartesian Robots Technology: 3D Vision Systems, Sensors, AI Integration, Machine Learning End User: Food and Beverage, Pharmaceuticals, Electronics, Consumer Goods Application: Packing, Palletizing, Wrapping, Sorting |
| Companies Covered | Kuka Roboter GmbH, Epson Robots, ABB Limited, BluePrint Automation, Krones AG, Fanuc Corporation, Mitsubishi Electric Corporation, Remtec Automation LLC, Yaskawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Packaging Robot Market Strategic Shifts
Machine learning-enabled adaptive control is electrifying competitive positioning across sterile pharmaceutical handling and variable-format food packaging applications.
Direct-drive torque motors are electrifying precision motion architectures in cleanroom delta configurations. Pharmaceutical contract packagers in Germany and Switzerland are adopting these systems for sub-millimeter placement accuracy in sterile vial handling. The technology is electrifying margin pools previously captured by gearbox-dependent articulated systems through reduced maintenance intervals and elimination of lubrication contamination risks.
The EU AI Act's CE marking requirements for machine learning-enabled safety systems are reshaping certification protocols for collaborative packaging deployments. Industrial consequence includes mandatory third-party validation of adaptive vision algorithms in human-robot collaborative cells. Pharmaceutical lines in the Netherlands and Belgium are most affected, with packagers accelerating ISO 10218-2 recertification programs ahead of enforcement timelines.
After-sales service unbundling is fragmenting traditional robot vendor relationships in high-volume food and beverage operations. End users in the United States are procuring maintenance and spare parts through independent automation integrators rather than OEM service contracts. This pattern is most visible in California and Illinois processing facilities where third-party technical labor pools have deepened sufficiently to support non-captive service models.
Global Packaging Robot Market Segmentation
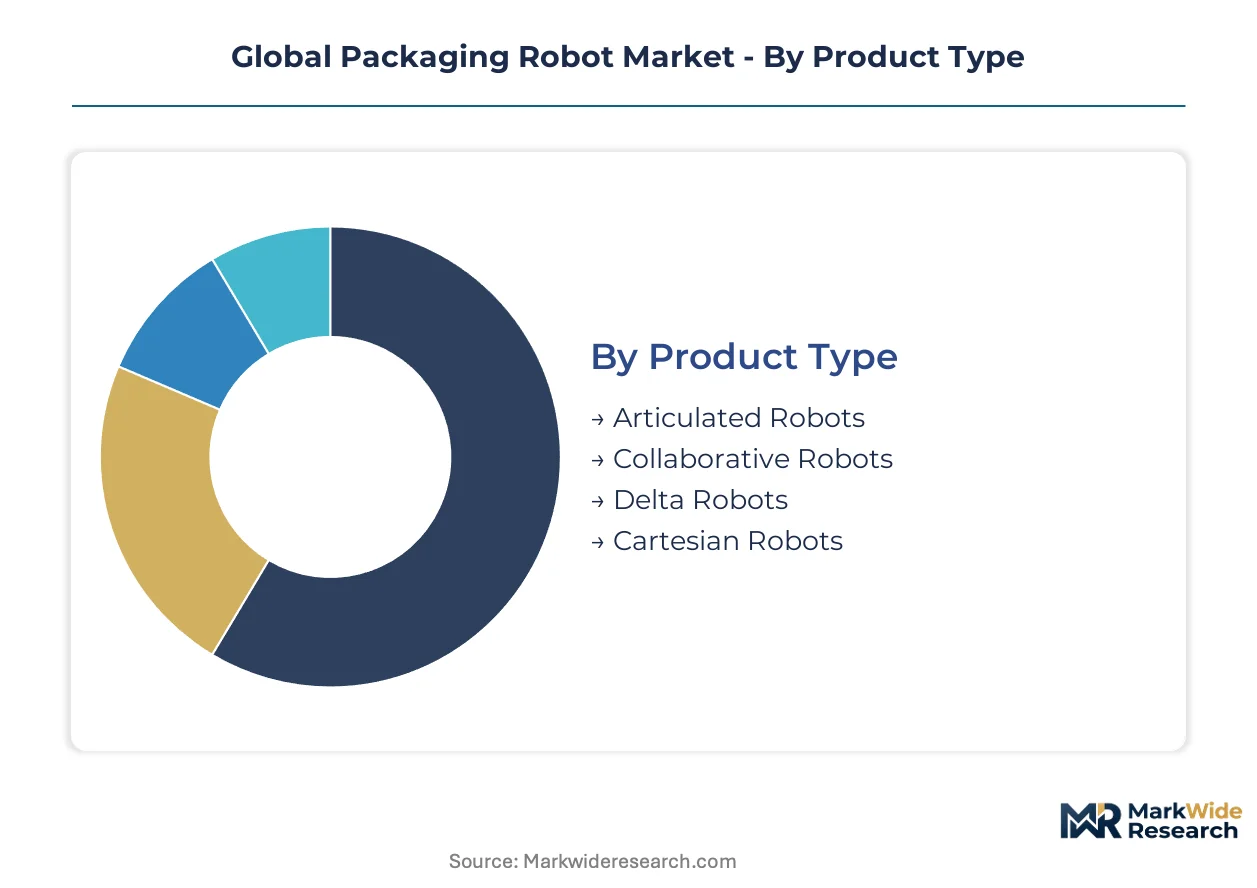
Packaging robot segmentation reveals how supply-side specialization concentrates manufacturing expertise and creates divergent margin structures across kinematic architectures. The analysis maps four critical dimensions where technical specifications, regulatory requirements, and end-use economics intersect to determine competitive positioning.
Product Type:
Supply concentration in precision motion components from Japan and Germany elevates sourcing leverage for specific kinematic configurations over others.
- Articulated Robots:Six-axis serial manipulators with servo-driven rotary joints enable complex motion paths in dense factory layouts. Demand concentrates in German automotive component packaging where payload flexibility and reach envelope adaptability justify higher capital outlay against delta alternatives.
- Collaborative Robots:Force-limited articulated arms with integrated safety-rated monitored stops operate without hard guarding per ISO 10218-2 protocols. Pharmaceutical contract packagers in Switzerland and the Netherlands are retrofitting legacy cleanroom lines fastest, compressing deployment timelines where space constraints prohibit cage installations.
- Delta Robots:Parallel kinematic structures with three or four arms mounted on an overhead base achieve sub-millimeter placement accuracy through lightweight carbon fiber linkages.
- Cartesian Robots:Gantry-style linear actuators with orthogonal X-Y-Z motion suit palletizing and case packing in high-volume beverage operations.
Today's leader: Articulated Robots. Tomorrow's challenger: Collaborative Robots.
Technology:
Cost tier differentiation separates vision-integrated premium configurations from sensor-only baseline systems across pharmaceutical validation requirements.
- 3D Vision Systems:Stereo camera arrays with structured light projection generate point cloud data for random bin picking and defect detection. Food and beverage producers in California processing facilities deploy these for variable-format sustainable packaging handling where material inconsistency defeats 2D approaches.
- AI Integration:Edge-deployed neural networks enable real-time adaptive grasp planning without cloud latency. The EU AI Act's CE marking requirements for machine learning-enabled safety systems are compressing deployment timelines for pharmaceutical lines in Belgium ahead of enforcement.
- Sensors:Force-torque, proximity, and tactile arrays provide closed-loop feedback for collision detection and quality verification.
- Machine Learning:Training pipelines for vision classification and motion optimization improve pick success rates over operational runtime.
Current premium tier: 3D Vision Systems. Fastest-climbing tier: AI Integration.
End User:
Application maturity varies sharply across sectors where FDA validation, FSSAI compliance, or electronics cleanliness standards dictate robot qualification protocols.
- Food and Beverage:Hygienic stainless steel constructions with IP69K washdown ratings handle primary packing of proteins and ready meals. Delta configurations dominate high-throughput dairy operations in Germany where sustained sixty-plus picks per minute throughput justifies parallel kinematic investment.
- Pharmaceuticals:ISO 5 cleanroom-compatible materials with sterile surface finishes and validated software documentation support vial and syringe handling. Contract packagers in India under PLI scheme incentives are greenfielding secondary lines with collaborative systems to bypass hard guarding infrastructure costs.
- Electronics:ESD-safe materials and micron-level placement accuracy protect sensitive components during final assembly packaging.
- Consumer Goods:General-purpose payloads and cycle speeds address case packing and palletizing across variable SKU portfolios.
Margin concentration sits with: Pharmaceuticals. Volume expansion centers on: Food and Beverage.
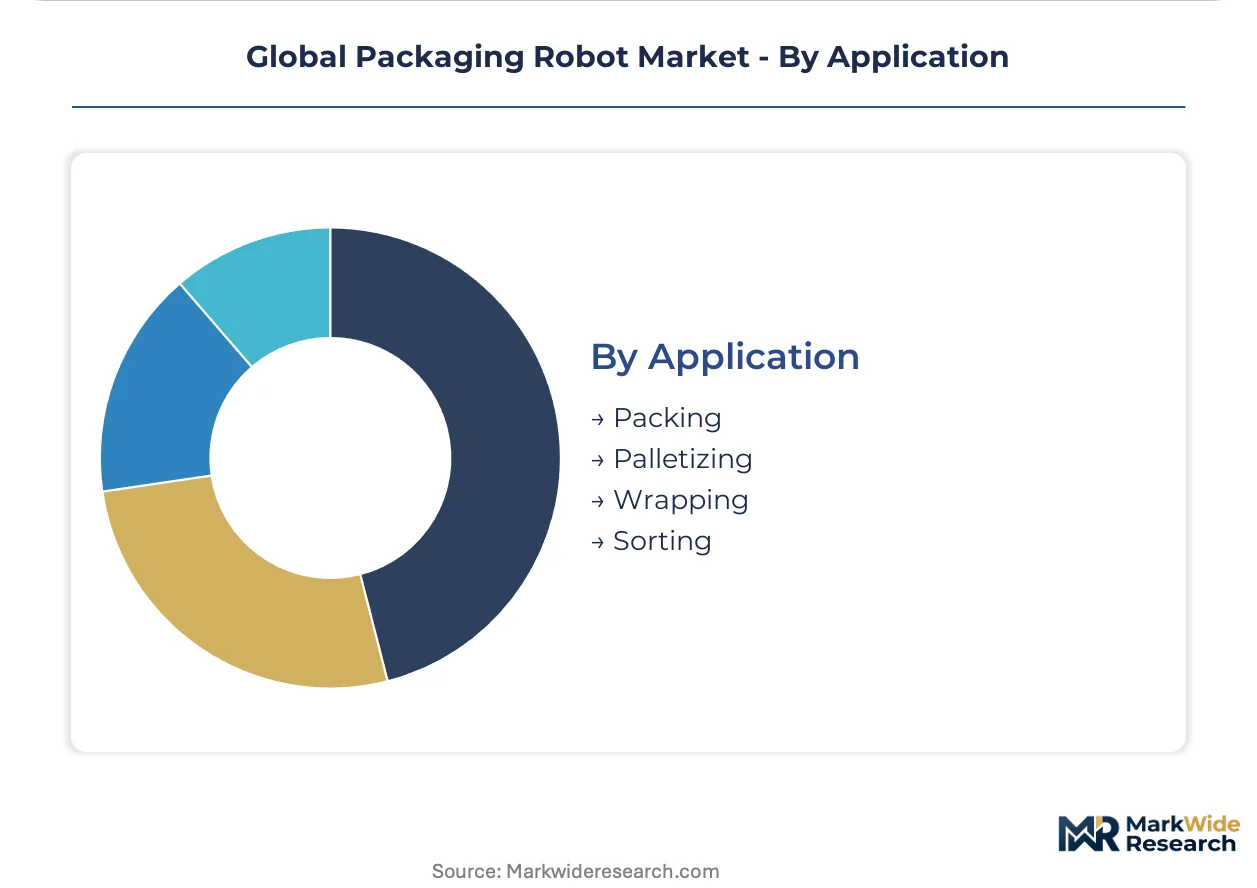
Application:
Customer type segmentation separates OEM line builders from end-user retrofitters with divergent integration capabilities and service procurement preferences.
- Packing:Primary and secondary containerization tasks including filling, capping, labeling, and case erecting. Electronics manufacturers in Japan deploy delta systems for chip tray handling where placement precision outweighs payload requirements.
- Palletizing:Tertiary unit load formation through layer forming, slip sheet insertion, and stretch wrapping. Heavy-payload articulated systems with force-torque sensing sustain automotive parts packaging share in the United States through mixed-SKU flexibility.
- Wrapping:Stretch film application and shrink tunnel feeding for load stabilization and retail presentation.
- Sorting:Vision-guided separation by weight, dimension, or barcode for distribution center fulfillment.
Installed base dominance: Palletizing. Steepest expansion trajectory: Packing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping packaging robot deployment as pharmaceutical and food producers migrate automation investments toward jurisdictions with streamlined certification pathways. The EU Machinery Directive and FDA validation requirements create divergent compliance cost structures that influence regional capital allocation.
Germany
Automotive component suppliers in Stuttgart and Wolfsburg are retrofitting legacy palletizing lines with heavy-payload articulated systems. The EU Machinery Directive's updated CE marking protocols under the EU AI Act are compressing deployment timelines for machine learning-enabled vision systems. Bavarian dairy processors concentrate delta robot installations where sustained high-throughput operations justify parallel kinematic capital outlay.
United States
Pharmaceutical contract packagers in New Jersey and North Carolina face 12-18 month FDA validation timelines that elevate compliance costs for new collaborative robot deployments. California food processing facilities are unbundling after-sales service from OEM contracts, procuring maintenance through independent automation integrators. Illinois beverage operations anchor Cartesian robot demand for high-volume case packing and palletizing applications.
Japan
Precision motion component manufacturing concentrates servo motor and harmonic drive supply in Nagoya and Osaka industrial corridors, creating input cost leverage for domestic robot assemblers. METI industrial automation incentives are accelerating cleanroom-compatible delta configurations for electronics packaging. Yokohama-based pharmaceutical packagers lead ISO 10218-2 collaborative system adoption in sterile vial handling.
India
PLI scheme incentives for electronics manufacturing and pharmaceutical contract packaging are generating greenfield automation demand in underpenetrated secondary packing lines. Maharashtra and Gujarat contract packagers are bypassing hard guarding infrastructure costs through collaborative robot retrofits. CDSCO regulatory alignment with international validation standards is shortening qualification timelines for export-oriented facilities.
Switzerland
Pharmaceutical contract packagers in Basel and Zurich are adopting direct-drive torque motors in cleanroom delta configurations for sub-millimeter placement accuracy. Swissmedic sterile handling requirements exceed EU baseline standards, creating premium positioning for validated robotic platforms. Geneva-area biologics facilities anchor demand for force-torque sensing collaborative systems in existing cleanroom retrofits.
Global Packaging Robot Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with precision motion heritage conferring durable positioning in pharmaceutical validation-intensive applications. The vendor base organizes around three archetypes: CNC-heritage precision motion specialists, diversified industrial automation conglomerates, and regional system integrators with deep vertical expertise. Consolidation pressure concentrates in vision-guided delta configurations where software-hardware integration determines deployment success. Dominant competitive moves include strategic partnerships between robot OEMs and independent automation integrators, plus portfolio diversification into after-sales service unbundling.
Within the precision motion tier, Fanuc Corporation and Yaskawa Electric Corporation exemplify CNC-heritage positioning in servo-driven architectures. Kuka Roboter GmbH anchors European automotive packaging automation through heavy-payload articulated systems. ABB Limited occupies a position in collaborative robotics certified under updated ISO 10218-2 protocols for pharmaceutical cleanroom deployment.
| Leading Market Players |
|---|
| Kuka Roboter GmbH |
| Epson Robots |
| ABB Limited |
| BluePrint Automation |
| Krones AG |
| Fanuc Corporation |
| Mitsubishi Electric Corporation |
| Remtec Automation LLC |
| Yaskawa Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
Direct-drive torque motor adoption in cleanroom delta configurations is compressing maintenance costs while redrawing supplier power maps toward Japanese and German precision motion specialists. This technology transition simultaneously elevates capital requirements for OEMs and tightens input concentration in corridors already dominant for servo motors and harmonic drives.
Pricing Analysis
Distributor margins on collaborative robot systems range from twelve to eighteen percent before installation services, while direct-to-OEM volume contracts for articulated lines command steeper discounts tied to ISO 10218-2 certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical platforms from general-purpose food handling configurations. Pricing pressure stems from independent automation integrators unbundling after-sales service in California and Illinois processing facilities. Contract packagers in India exhibit highest price sensitivity due to PLI scheme capital constraints, while Swiss biologics facilities absorb premium positioning for Swissmedic-compliant sterile handling.
Supply Chain Analysis
India's PLI scheme domestic-content thresholds are redirecting component sourcing toward local assembly partners for electronics and pharmaceutical packaging lines. Servo motor and harmonic drive supply concentrates in Japan and Germany, with carbon fiber linkages and precision bearings drawing from Taiwan and Switzerland. Single-source vulnerability runs through Nagoya-Osaka industrial corridors for torque motor controllers. Distribution runs through authorized robot OEM channels in validated pharmaceutical applications, while independent integrators capture spare parts and maintenance procurement in high-volume food and beverage operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's CE marking requirements for machine learning-enabled safety systems compound demand for certified platform upgrades, creating sustained regulatory tailwinds for adaptive packaging automation.
For Market Incumbents: Cement positioning in pharmaceutical validation-intensive segments through captive supply of ISO 10218-2 certified collaborative controllers, while accelerating backward integration into direct-drive torque motor production to offset Japanese supplier leverage. Independent automation integrators unbundling after-sales service threaten traditional OEM service revenue streams in North American food processing. For New Entrants and Emerging Players: Maharashtra and Gujarat contract packagers operating under PLI scheme incentives represent the most penetrable buyer archetype, with collaborative robot retrofits bypassing hard guarding infrastructure costs in underpenetrated secondary pharmaceutical lines. Target greenfield electronics manufacturing clusters with force-torque sensing platforms certified for cleanroom deployment. Go-to-market through regional system integrators with existing FDA validation relationships accelerates qualification timelines. For Investors and Strategic Acquirers: Roll-up economics work for regional vision-guided delta specialists because software-hardware integration capabilities remain fragmented across European food and beverage automation integrators. Five-to-ten year viability hinges on adaptive grasp algorithm differentiation as machine learning-enabled safety systems proliferate. Watch EU AI Act enforcement timelines in Belgium and the Netherlands as inflection indicators for mandatory third-party validation demand.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10218-2 Recertification Acceleration | Pharmaceutical packagers in Belgium compress deployment timelines ahead of EU AI Act enforcement. |
| Backward Integration into Torque Motors | Cleanroom delta OEMs capture margin pools previously held by gearbox-dependent articulated suppliers. |
| Independent Integrator Partnership | After-sales service unbundling in California and Illinois redirects procurement away from captive OEM contracts. |
| PLI Scheme Localization | Maharashtra electronics manufacturers source compliant components for export-oriented packaging automation. |
| Adaptive Vision Algorithm Validation | Third-party certification of machine learning-enabled safety systems opens pharmaceutical retrofit opportunities. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and integration specialists with secondary validation from customs records, SEC filings, and industrial automation trade databases. Triangulation across stakeholder inputs and published regulatory filings ensures coverage of ISO 10218-2 certification timelines, PLI scheme incentive structures, and FDA validation protocols.
Input-output matrices map articulated, collaborative, delta, and Cartesian robot shipments against pharmaceutical, food and beverage, electronics, and consumer goods installation demand across the projection horizon. Segmentation dimensions include kinematic architecture, vision integration tier, end-use cleanliness standard, and regional regulatory cluster. CAGRs derive from installed base turnover rates and greenfield automation penetration curves, with specific weighting for servo motor supply lead times and collaborative robot safety certification backlogs.
Underlying measurement precision varies by segment; pharmaceutical validation-intensive applications carry tighter precision than emerging economy secondary packing lines. Forecasts reflect documented assumptions regarding EU AI Act enforcement phasing, PLI scheme extension decisions, and harmonic drive supply concentration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
Packaging Automation Market
Packaging Automation
Automated Tray Fill and Seal Machines Market
Packaging Automation
North America Contract Packaging Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market
Packaging Automation
Pre-Assembled Packaging Market
Packaging Automation
APAC Packaging Automation Market
Packaging Automation
Food Packaging Robotics Market
Packaging Automation
Automatic Strapping Machines Market
Packaging Automation
Automatic Glue Machine Market
Packaging Automation
Automated Label Inspection Machines Market
Packaging Automation
Automatic Labeling Machine Market
Packaging Automation
Automatic Die Cutting Machines Market
Packaging Automation
Automatic Capping Machine Market
Packaging Automation
Automatic Powder Filling Machines Market
Packaging Automation
Robotic Packaging Machines Market