
 Arizona Legal Cannabis Market | 2026-2036
Arizona Legal Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
Arizona Legal Cannabis Market Analytics
Pre-roll bundling and multi-pack configurations is rebalancing how recreational buyers evaluate value against per-unit cost in Arizona dispensaries. Curaleaf Holdings leverages its multi-state operational playbook to sustain shelf presence across Phoenix and Tucson retail channels. Copperstate Farms anchors its position through vertical cultivation control, while Grow Sciences differentiates via solventless concentrate technology and small-batch flower releases.
Arizona legal cannabis encompasses dried flower, extracted concentrates, infused edibles, and topical formulations containing THC and CBD, all subject to state-mandated potency testing, contaminant screening, and child-resistant packaging requirements. Flower retains the largest volume share but carries compressed margins due to commoditization; concentrates command premium pricing driven by extraction complexity and potency concentration. Edibles represent the fastest-expanding category as discreet consumption formats attract newer recreational entrants.
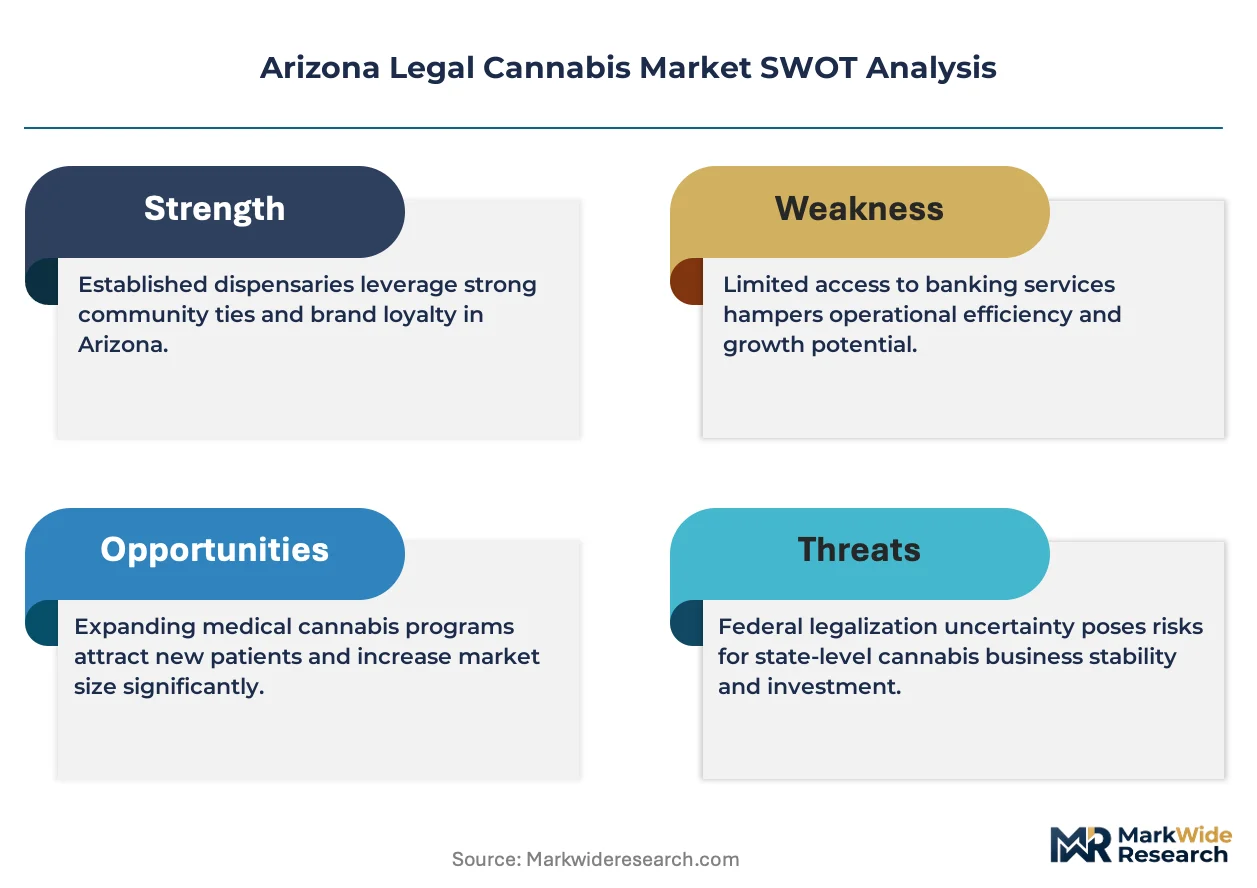
The Arizona Department of Health Services enforces testing protocols for microbial contaminants, residual solvents, and heavy metals, while the Arizona Department of Revenue administers the 16% excise tax on recreational sales that shapes final consumer pricing. Local municipal zoning boards in cities like Phoenix, Mesa, and Flagstaff further constrain retail licensing density, directly limiting market access in high-demand zones. Stakeholders must monitor municipal ballot initiatives and potential legislative adjustments to possession limits and social equity licensing criteria.
Market Dynamics
The Arizona Department of Health Services' potency testing and contaminant screening mandates are compressing product development cycles while forcing capital redeployment toward compliant manufacturing infrastructure.
Growth Catalysts
- Recreational Adult-Use Expansion:Consumer migration from medical to recreational channels broadens addressable demand pools across Phoenix and Tucson metropolitan corridors.
- Solventless Extraction Technology:Mechanical separation methods for concentrates attract health-conscious buyers seeking chemical-free processing pathways.
- Edibles Format Innovation:Micro-dosed beverages and fast-acting nano-emulsion products capture discretionary spending from newer entrants prioritizing discretion.
Market Restraints
- 16% Excise Tax Burden:Arizona Department of Revenue levies compress retail margins and push price-sensitive consumers toward unlicensed supply channels.
- Municipal Zoning Density Limits:Phoenix, Mesa, and Flagstaff licensing caps create artificial scarcity in high-traffic zones, inflating real estate costs for compliant operators.
- Residual Solvent Testing Costs:Laboratory screening for butane, propane, and ethanol remnants adds per-batch expenses that small-batch processors struggle to absorb.
Strategic Opportunities
- Southern Arizona Corridor:Tucson metro area exhibits lower retail saturation relative to population density, offering first-mover positioning for compliant operators.
- Social Equity Licensing Windows:Legislative adjustments to ownership criteria may unlock capital access for community-based applicants previously excluded by financial barriers.
- Topical Formulation Expansion:Transdermal patches and cannabinoid-infused skincare products target wellness consumers outside traditional intoxication-use cases.
Industry Challenges
- Extraction Technician Scarcity:Specialized skill sets for hydrocarbon and CO2 extraction systems command premium wages that mid-scale facilities struggle to match.
- Child-Resistant Packaging Compliance:Arizona Department of Health Services mandates for resealable, opaque containers force continuous redesign cycles and inventory obsolescence.
- Batch Recall Protocol Complexity:Seed-to-sale tracking integration with METRC systems demands dedicated compliance personnel, elevating fixed overhead structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arizona Legal Cannabis Market |
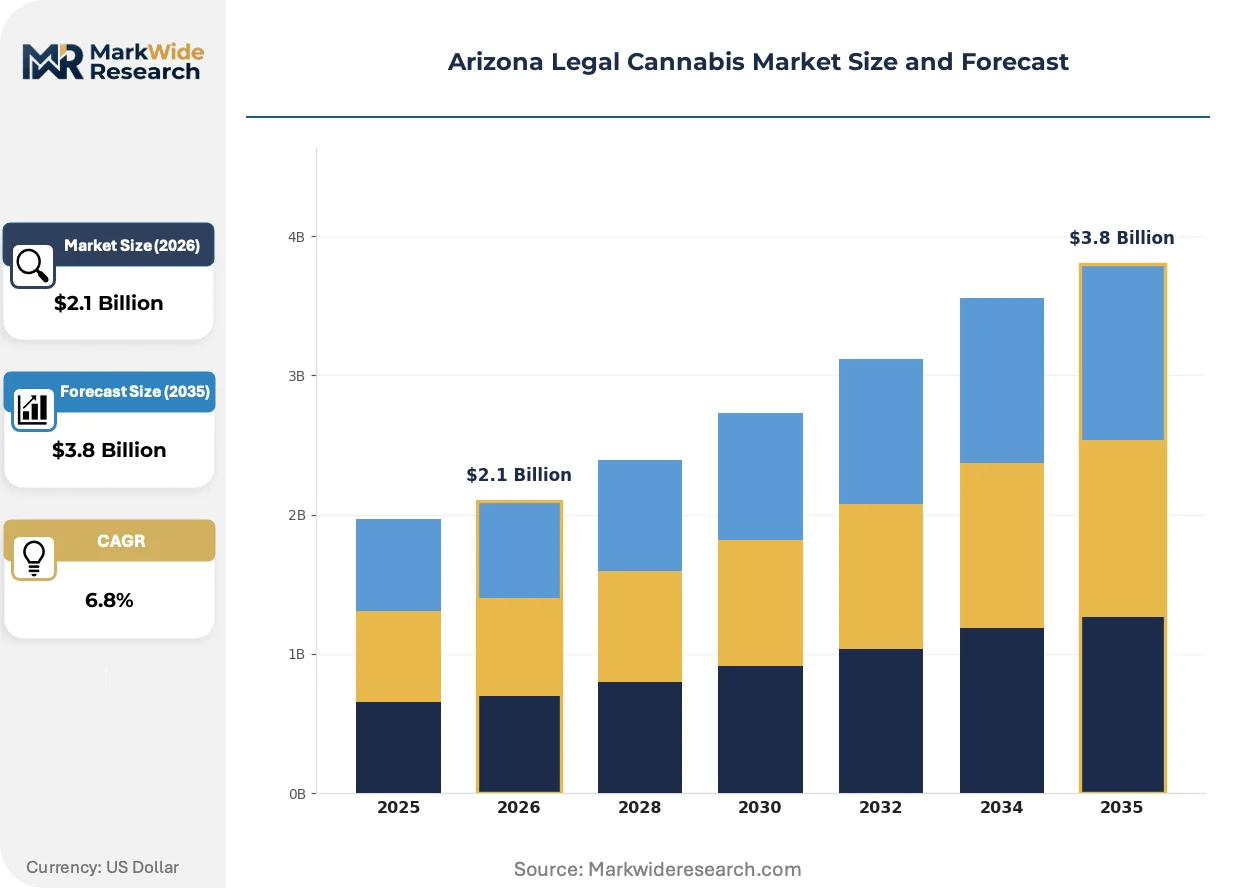
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flower, Edibles, Concentrates, Topicals Distribution Channel: Dispensaries, Delivery Services, Online Retail, Wholesale Customer Type: Recreational Users, Medical Patients, CBD Consumers, Investors End User: Adults, Chronic Pain Patients, Entrepreneurs, Retailers |
| Companies Covered | Curaleaf Holdings, Harvest Health & Recreation, Copperstate Farms, The Flower Shop Dispensaries, Mohave Cannabis Co., Arizona Natural Concepts, Mint Cannabis, Item 9 Labs Corp., Grow Sciences, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arizona Legal Cannabis Market Evolving Landscape
Product formulation and retail configuration are undergoing simultaneous transformation as testing mandates harden and consumer sophistication deepens across Arizona's licensed dispensary network.
Automated pre-roll manufacturing is consolidating production economics for Arizona's highest-volume flower category. Precision weighing and cone-filling systems enable consistent multi-pack bundling that recreational buyers now expect as standard. Dispensary operators deploying this equipment compress labor costs per unit while expanding SKU breadth without proportional inventory investment.
Arizona Department of Health Services microbial screening protocols for Aspergillus and Salmonella are accelerating laboratory consolidation across the state. Third-party testing facilities face capacity constraints as batch volume expands, pushing larger cultivators toward in-house analytical capabilities. Small and mid-tier operators without captive testing infrastructure experience elongated release timelines and working capital pressure.
Discreet consumption preferences are redirecting procurement patterns among newer recreational entrants. Nano-emulsion technology enabling rapid-onset edibles displaces traditional infused chocolates and baked goods in Phoenix-area dispensary merchandising. Tucson retailers report strongest velocity for beverage formats and sublingual strips among consumers seeking alternatives to inhalation methods.
Arizona Legal Cannabis Market Segmentation
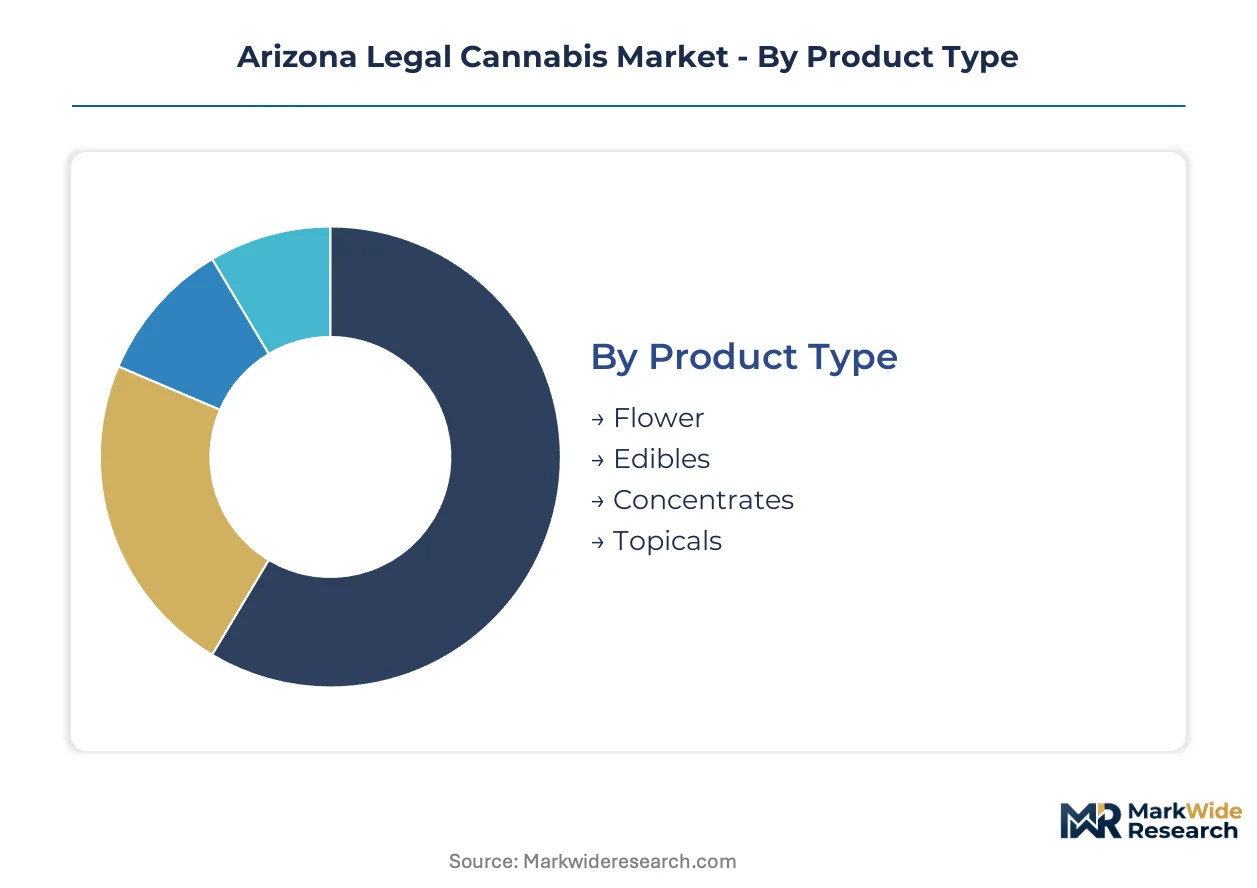
Segmentation in Arizona's legal cannabis market reveals how regulatory fragmentation and consumer migration patterns create divergent compliance burdens and margin structures across product formats and channels.
Product Type:
Arizona Department of Health Services mandates distinct testing protocols for each product category, with microbial screening for flower and residual solvent analysis for concentrates imposing the heaviest laboratory certification requirements.
- Flower:Dried and cured cannabis buds retain the largest volume share across Arizona dispensaries. Phoenix metropolitan corridor retailers report compressed per-gram margins due to cultivation oversupply, though premium small-batch releases from controlled-environment facilities command price premiums.
- Edibles:Infused food and beverage products require homogeneity testing and child-resistant packaging compliance that adds per-unit cost. Tucson metro area retailers observe strongest velocity for nano-emulsion beverages and micro-dosed formats among newer recreational entrants seeking discretion.
- Concentrates:Extracted oils and waxes demand hydrocarbon or CO2 processing infrastructure with residual solvent screening.
- Topicals:Transdermal patches and cannabinoid-infused skincare target wellness consumers outside traditional intoxication-use cases.
Flower sits at the top of the volume ranking, with Edibles climbing the fastest.
Distribution Channel:
Channel economics in Arizona diverge sharply based on municipal zoning density and Arizona Department of Revenue excise tax collection points, with physical retail facing the steepest real estate and compliance overhead.
- Dispensaries:Licensed brick-and-mortar retail locations concentrate in Phoenix and Tucson corridors where municipal caps on licensing density inflate lease costs. Operators deploy automated pre-roll manufacturing and multi-pack bundling to compress labor expenses per transaction.
- Delivery Services:Mobile distribution models expand access to consumers in Flagstaff and Mesa where retail saturation remains below population density. Arizona Department of Health Services tracking mandates require real-time METRC integration for route documentation and chain-of-custody verification.
- Online Retail:Digital ordering platforms face restrictions on direct-to-consumer shipping under state law.
- Wholesale:Business-to-business bulk transactions supply downstream retail and manufacturing operations.
Dispensaries capture the dominant revenue share, while Delivery Services gain ground fastest in underserved municipalities.
Customer Type:
Recreational adult-use expansion has rebalanced Arizona's customer base, with medical cardholder counts declining as former patients migrate to the broader-access recreational channel and its higher per-transaction tax burden.
- Recreational Users:Adult consumers purchasing without medical certification now drive bulk volume growth across Phoenix and Tucson metropolitan areas. This segment prioritizes convenience formats, multi-pack value configurations, and discreet consumption options that minimize odor and visibility.
- Medical Patients:Cardholders retain access to lower-tax product and higher possession limits under Arizona Department of Health Services registration. Chronic condition management users concentrate demand for high-potency concentrates and consistent-dose formulations.
- CBD Consumers:Non-intoxicating cannabinoid seekers purchase hemp-derived or low-THC products.
- Investors:Capital deployment into license holdings and operational equity stakes shapes upstream consolidation.
Recreational Users dominate transaction volume, with Medical Patients contracting as a share of the total customer base.
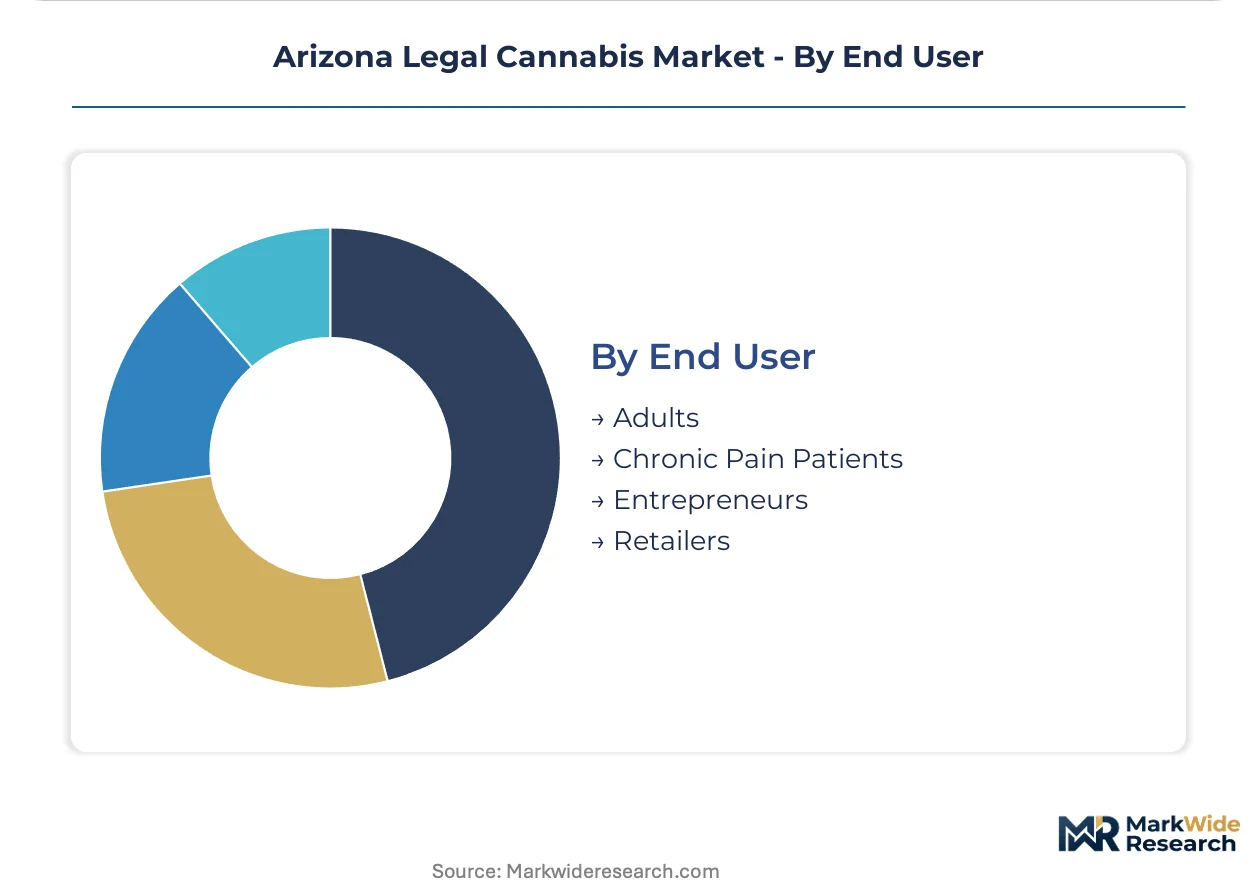
End User:
End-user categories in Arizona reflect both consumption demand and supply-side participation, with entrepreneurial entrants and retail operators functioning as economic actors distinct from final consumers.
- Adults:General population consumers over 21 years constitute the addressable market for recreational sales, with preferences fragmenting across inhalation, ingestion, and topical application methods. Municipal zoning in Phoenix, Mesa, and Flagstaff constrains physical access for this broad demographic.
- Chronic Pain Patients:Individuals managing persistent medical conditions maintain medical card registrations to access tax-advantaged product and higher potency limits. This segment exhibits strongest loyalty to specific cultivators and consistent batch availability.
- Entrepreneurs:License applicants and operational investors navigate social equity criteria and capital requirements.
- Retailers:Dispensary operators and delivery service proprietors function as intermediate demand aggregators.
Adults represent the largest addressable population, while Entrepreneurs face the most restrictive entry barriers under current licensing frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Arizona legal cannabis traces its commercial lineage to the 2010 voter-approved medical program, with recreational adult-use authorization following in 2020. The state's regulatory framework now governs a market concentrated across metropolitan corridors where municipal zoning and testing mandates shape operational density.
Phoenix Metropolitan Corridor
Maricopa County hosts the state's densest retail concentration, with dispensary clusters in Phoenix, Mesa, and Scottsdale serving recreational buyers seeking convenience formats. The Arizona Department of Health Services enforces potency testing and child-resistant packaging mandates that elevate compliance costs for operators. Automated pre-roll manufacturing facilities in Tempe and Gilbert compress production economics for multi-pack bundling.
Tucson Metro Area
Pima County exhibits lower retail saturation relative to population density, creating first-mover positioning for compliant operators expanding southward. The Arizona Department of Revenue collects 16% excise tax at point of sale, with municipal jurisdictions adding supplemental levies. Nano-emulsion beverage production and solventless concentrate processing concentrate in Tucson's industrial zones near interstate corridors.
Flagstaff and Northern Arizona
Coconino County's smaller population base supports limited licensed retail, with delivery services expanding access to dispersed communities. Local zoning boards maintain strict caps on dispensary proximity to schools and residential zones. Cultivation operations leverage higher elevation climate conditions for controlled-environment agriculture.
Prescott and Yavapai County
This central-northern sub-region serves medical patients and recreational consumers across a geographically dispersed catchment area. The Arizona Department of Health Services tracks seed-to-sale movement through METRC integration, requiring real-time compliance documentation. Smaller-scale operators focus on craft flower and limited-batch releases to differentiate from mass-market competitors.
Arizona Legal Cannabis Market Competitive Landscape
The competitive structure tilts toward vertically integrated multi-state operators controlling cultivation, processing, and retail assets. Market concentration remains moderate, with regional specialists retaining meaningful share through localized brand equity and product differentiation. Three archetypes dominate: multi-state platform operators deploying standardized playbooks, in-state vertical integrators emphasizing cultivation control, and craft specialists leveraging small-batch positioning. Competitive moves center on retail license accumulation in zoning-constrained municipalities and solventless extraction technology deployment.
Among multi-state platform operators, Curaleaf Holdings and Harvest Health & Recreation occupy positions emphasizing geographic diversification and operational scale. Copperstate Farms anchors the in-state vertical integration archetype through controlled cultivation assets. Grow Sciences exemplifies the craft specialist tier, differentiating via solventless concentrate technology and limited-release flower programs. These three entities represent the strategic positioning spectrum available to competitors navigating Arizona's testing mandates and municipal zoning constraints.
| Leading Market Players |
|---|
| Curaleaf Holdings |
| Harvest Health & Recreation |
| Copperstate Farms |
| The Flower Shop Dispensaries |
| Mohave Cannabis Co. |
| Arizona Natural Concepts |
| Mint Cannabis |
| Item 9 Labs Corp. |
| Grow Sciences |
| Others |
Value Network & Pricing Analysis
Automated pre-roll manufacturing technology is compressing unit economics while concentrating production capacity among operators deploying capital-intensive filling and weighing systems across Phoenix and Tucson. This equipment shift simultaneously lowers per-unit labor costs and raises barriers for small-batch processors unable to absorb machinery investments, tightening supply concentration around vertically integrated players with captive cultivation assets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Arizona dispensary shelf configurations, with solventless concentrates and controlled-environment small-batch flower commanding top-tier positioning against commodity greenhouse output. Price differentiation stems from extraction complexity and batch consistency certification under Arizona Department of Health Services protocols. Cost compression in economy-tier flower is intensifying because cultivation oversupply in Maricopa County has compressed per-gram margins below sustainable levels for non-integrated operators. Price-sensitive recreational buyers in the Phoenix metropolitan corridor drive volume through multi-pack bundling, while medical patients exhibit lowest sensitivity due to tax-advantaged access and chronic condition loyalty.
Supply Chain Analysis
Logistics and freight costs for compliant cannabis distribution hinge on METRC seed-to-sale tracking requirements that mandate real-time chain-of-custody documentation across all transport legs. Geographic supply concentration centers on Maricopa and Pima counties, where controlled-environment agriculture and extraction processing cluster near interstate corridors and municipal licensing zones. Raw material inputs draw from captive cultivation, third-party biomass sourcing, and solvent supply chains for hydrocarbon and CO2 extraction systems. Single-source vulnerability persists in laboratory testing capacity, where third-party microbial and residual solvent screening bottlenecks elongate batch release timelines. Distribution runs through licensed dispensary retail, delivery services expanding in zoning-constrained municipalities, and wholesale B2B channels supplying downstream manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arizona legal cannabis functions as a stable compounder, with recreational adult-use migration providing durable volume expansion insulated from economic cyclicality. The Arizona Department of Health Services regulatory framework creates predictable compliance costs that favor scaled operators with dedicated infrastructure.
For Market Incumbents: Deepen vertical control over cultivation assets to defend margin position against commodity flower oversupply in Maricopa County. Prioritize automated pre-roll manufacturing capacity expansion in Tempe and Gilbert industrial zones to capture multi-pack bundling economics. Invest in in-house analytical testing infrastructure to bypass third-party laboratory bottlenecks and compress batch release cycles.
For New Entrants and Emerging Players: Delivery service operators present the most penetrable channel for compliant market entry, particularly in Flagstaff and Mesa where municipal zoning caps constrain physical retail density. Target the Tucson metro area for first-mover positioning in nano-emulsion beverage production, where lower retail saturation relative to population density supports premium pricing. Secure social equity licensing windows through community-based partnership structures that satisfy legislative ownership criteria adjustments.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale craft specialists with solventless extraction technology and limited-batch flower programs, where brand equity defends pricing power against commodity pressure. Long-term viability over a five-to-ten year horizon rests on municipal license accumulation in zoning-constrained Phoenix and Scottsdale sub-markets. Watch for Arizona Department of Revenue excise tax rate adjustments as the primary inflection signal for consumer channel migration and unlicensed market competition.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Pre-Roll Manufacturing Deployment | Curaleaf Holdings and Copperstate Farms compress labor costs per unit while expanding SKU breadth in Phoenix corridor dispensaries. |
| Solventless Extraction Technology Investment | Grow Sciences differentiates premium concentrate positioning through mechanical separation methods avoiding residual solvent testing burdens. |
| Delivery Service Geographic Expansion | Mobile distribution models capture underserved Flagstaff and Mesa consumers where municipal zoning limits physical retail access. |
| In-House Laboratory Testing Infrastructure | Large cultivators bypass third-party capacity constraints and accelerate batch release timelines under Arizona Department of Health Services mandates. |
| Social Equity Licensing Partnership Structuring | Community-based applicants unlock capital access through adjusted ownership criteria under potential legislative reforms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dispensary operators, extraction facility managers, compliance officers, and Arizona Department of Health Services regulatory staff alongside secondary validation. Secondary sources included Arizona Department of Revenue excise tax collection data, municipal zoning board licensing records, METRC seed-to-sale tracking disclosures, and industry cultivation capacity databases. Bottom-up demand modeling and top-down regulatory framework analysis triangulated market size and growth trajectory estimates.
Segment-weighting approaches distributed value and volume across product type, distribution channel, and customer type dimensions, with additional stratification by metropolitan corridor and compliance tier. CAGRs were derived from trend extrapolation of recreational adult-use migration patterns, testing mandate cost absorption curves, and municipal licensing saturation rates across the projection horizon. Industry-specific forecast inputs incorporated batch recall protocol complexity, child-resistant packaging redesign cycles, and extraction technician wage inflation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Arizona Department of Health Services testing protocol amendments, municipal ballot initiative results on possession limits, and federal scheduling reclassification discussions. Forecasts reflect documented assumptions about regulatory stability and consumer channel migration velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
Latin America and Caribbean Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Morocco Medical Cannabis Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Trichome Separator/Extractor Market
Cannabis/Marijuana
Veterinary CBD Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
CBD Edibles Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market
Cannabis/Marijuana
Missouri Medical Cannabis Market
Cannabis/Marijuana
Australia Medicinal Cannabis Testing Market
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market