
 EV Traction Motor Market | 2026-2036
EV Traction Motor Market Size, Share, and Industry Trends Forecast 2026-2036
EV Traction Motor Market Analytics
The EU Green Deal's vehicle emissions targets are shifting procurement priorities across European automotive supply chains. Robert Bosch GmbH leverages its integrated powertrain division to capture volume from platform-sharing alliances. Nidec Corporation anchors Asian supply through dedicated EV motor factories in China and Mexico. Siemens AG competes on industrial-scale stator winding automation for tier-one motor contracts.
An EV traction motor converts electrical energy from the battery into mechanical torque for propulsion, typically operating at voltages between 400V and 800V with peak rotational speeds exceeding 15,000 RPM in premium architectures. Liquid cooling dominates high-performance applications where thermal stability preserves magnetic efficiency during sustained highway loads. Passenger cars command the largest absolute volume while commercial vehicles represent the fastest-expanding vehicle category as fleet electrification deadlines tighten. Brushless DC motors maintain share in cost-optimized two-wheeler platforms across Asian urban markets.
The EPA tailpipe standards and China's MIIT new energy vehicle credit system jointly compress development cycles for qualifying motor architectures. ECE R100 electrical safety certification and ISO 26262 functional safety ratings now gate OEM qualification for traction motor suppliers. Stakeholders must monitor rare earth magnet supply corridors and silicon carbide inverter pairing roadmaps as these dual dependencies reshape motor design trade-offs.
Market Dynamics
Silicon carbide inverter pairing roadmaps are compressing motor design cycles as OEMs demand integrated powertrain architectures that optimize thermal efficiency across voltage classes.
Growth Catalysts
- EPA tailpipe standards:The US regulations tighten fleet emissions ceilings, forcing passenger car OEMs to accelerate electric platform rollouts and expand traction motor procurement volumes.
- China's MIIT credit system:The new energy vehicle mandate creates quantifiable compliance incentives that concentrate motor demand among domestic battery-electric platform producers.
- Hairpin winding technology:This conductor geometry improves slot fill factors and reduces copper losses, enabling higher power density in liquid-cooled stator assemblies for highway-duty cycles.
Market Restraints
- Rare earth magnet supply corridors:Concentrated heavy rare earth processing in China's Jiangxi and Inner Mongolia regions creates single-source dependency for high-coercivity neodymium magnets used in permanent magnet synchronous motors.
- ECE R100 certification timelines:The UN electrical safety protocol requires extensive high-voltage isolation testing that extends supplier qualification periods by 8-14 months for 800V architectures.
- Copper price volatility:Stator windings represent 15-22% of motor material cost, exposing manufacturers to London Metal Exchange commodity swings that compress margin buffers on fixed-price contracts.
Strategic Opportunities
- Commercial vehicle fleet mandates:California's Advanced Clean Trucks regulation and EU CO2 standards for heavy-duty vehicles are opening procurement channels for high-torque axial-flux motor architectures in delivery and regional haul segments.
- Two-wheeler electrification:Brushless DC motor platforms for Asian urban mobility remain underpenetrated in Indonesia and Vietnam, where cost-optimized hub motor designs can capture volume from internal combustion engine displacement.
- Silicon carbide inverter convergence:Pairing wide-bandgap power electronics with high-speed permanent magnet motors enables 20,000+ RPM operation, unlocking power density gains for premium passenger car platforms.
Industry Challenges
- ISO 26262 functional safety certification:ASIL-D ratings for torque control systems require specialized embedded software engineering talent that concentrates in Germany's automotive supplier corridor around Stuttgart.
- Stator winding automation capex:High-speed hairpin forming and laser welding equipment demands 8-figure capital commitments that disadvantage mid-tier suppliers competing for tier-one motor contracts.
- Magnet demagnetization modeling:Predicting thermal and mechanical stress effects on rare earth magnetic properties requires multiphysics simulation capabilities that fragment across supplier engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Traction Motor Market |
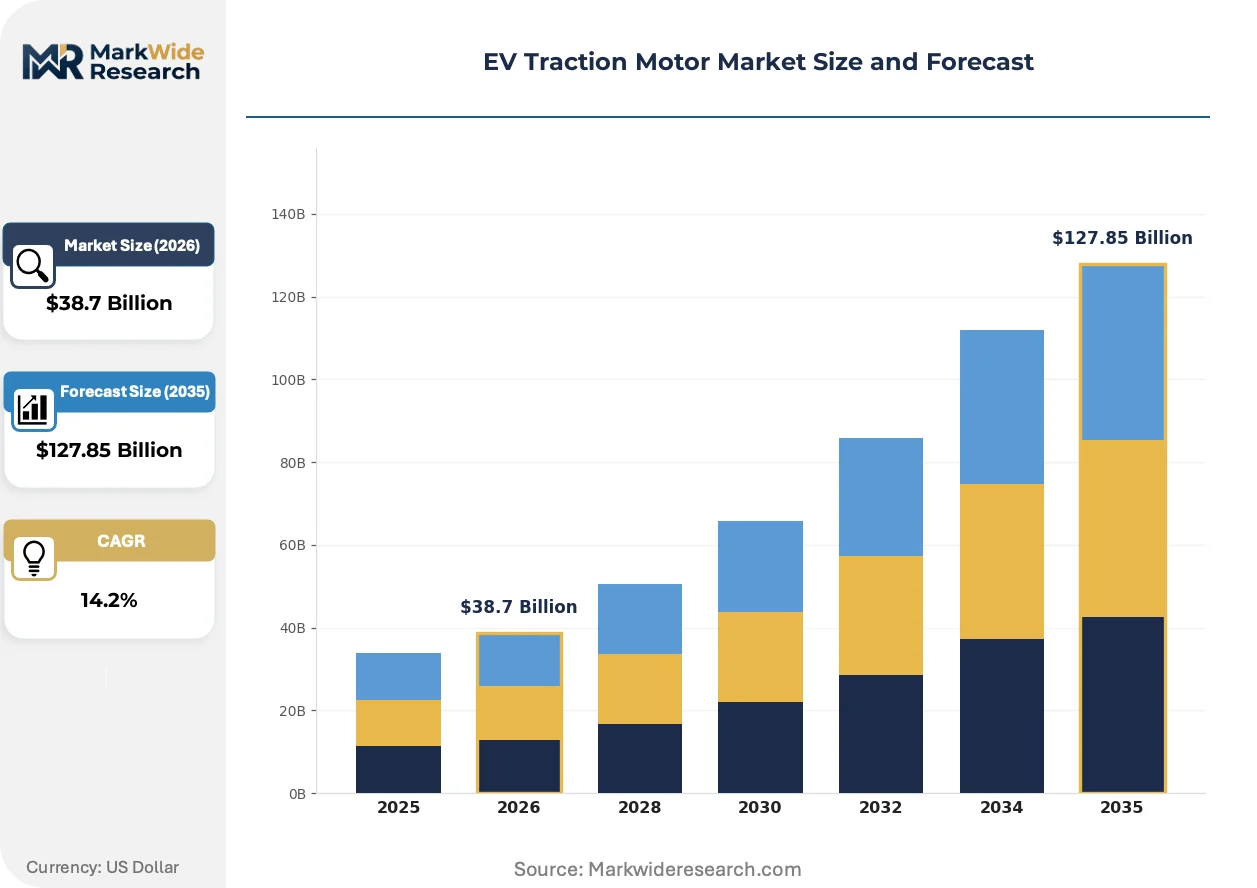
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Brushless DC, Synchronous, Asynchronous, Switched Reluctance Vehicle Type: Passenger Cars, Commercial Vehicles, Two-wheelers, Buses Cooling Method: Air Cooling, Liquid Cooling, Oil Cooling, Hybrid Cooling Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Robert Bosch GmbH, ABB Ltd., Siemens AG, Nidec Corporation, ZF Friedrichshafen AG, Continental AG, Hitachi Automotive Systems Ltd., BorgWarner Inc., Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Traction Motor Market Evolving Landscape
Manufacturing process automation and materials science advances are redefining motor performance benchmarks while regulatory pressure accelerates design cycle compression across automotive supply chains.
Hairpin stator winding is automating conductor insertion and laser welding processes that previously required manual assembly. Tier-one suppliers in Germany and China are deploying robotic winding cells to achieve slot fill factors above 70% in high-volume production. This automation is compressing unit cost curves for 800V-class motors while tightening tolerance bands for thermal performance consistency.
The EU Green Deal's vehicle emissions targets are mandating fleet-average CO2 reductions that cascade into powertrain electrification roadmaps. OEM procurement committees now require silicon carbide-ready motor designs as standard qualification criteria. European passenger car platforms are responding with integrated inverter-motor-gearbox assemblies that simplify thermal management architecture.
Platform-sharing alliances are consolidating motor specifications across multiple vehicle nameplates to amortize development costs. Volkswagen Group's unified cell format and Hyundai-Kia's E-GMP architecture exemplify this specification concentration. This procurement model shift is most visible in Germany and South Korea, where engineering teams negotiate multi-year motor supply agreements spanning 5-10 vehicle programs.
EV Traction Motor Market Segmentation
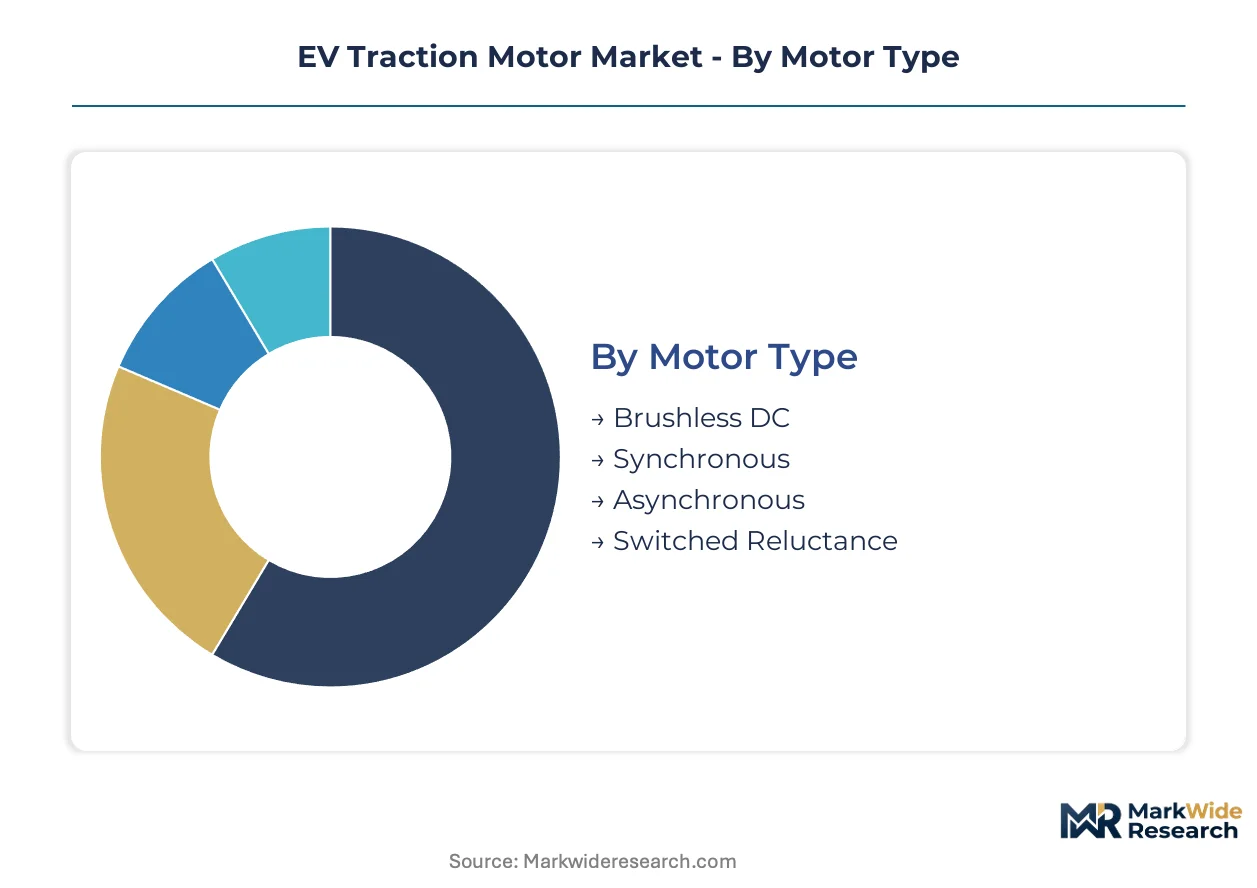
EV traction motor segmentation reveals divergent technical requirements across vehicle architectures. Motor specifications must align with thermal constraints, voltage classes, and duty cycle profiles that vary dramatically between urban two-wheelers and highway-duty commercial fleets.
Motor Type:
Volume concentrates in permanent magnet architectures while cost-optimized platforms explore magnet-free alternatives.
- Synchronous:Permanent magnet synchronous motors dominate premium passenger car platforms with peak efficiencies exceeding 96%. China's Jiangxi rare earth corridor supplies the neodymium-iron-boron magnets that enable high power density in 800V architectures. OEMs in Germany and South Korea specify this topology for flagship electric sedans and performance SUVs.
- Asynchronous:Induction motors eliminate rare earth dependency through copper rotor bars and laminated steel cores. Tesla's early platform designs validated this approach for dual-motor configurations where front axle efficiency matters less than cost control. European commercial vehicle trials are revisiting this topology for depot-charged urban delivery trucks.
- Brushless DC:Trapezoidal back-EMF designs serve cost-sensitive Asian two-wheeler markets with simple sensorless control.
- Switched Reluctance:Magnet-free topology attracts research investment for mining and defense applications requiring fault tolerance.
Today's leader: Synchronous. Tomorrow's challenger: Asynchronous.
Vehicle Type:
Passenger car procurement absorbs the highest absolute unit volumes while commercial electrification timelines reshape supplier priorities.
- Passenger Cars:Platform-sharing alliances consolidate motor specifications across multiple nameplates. Volkswagen Group's unified cell format and Hyundai-Kia's E-GMP architecture exemplify this procurement concentration. Tier-one suppliers compete for multi-year contracts spanning 5-10 vehicle programs.
- Commercial Vehicles:California's Advanced Clean Trucks regulation and EU CO2 standards for heavy-duty vehicles are opening procurement channels for high-torque axial-flux architectures. Regional haul and last-mile delivery segments show the steepest expansion trajectory as fleet operators face 2030 electrification deadlines.
- Two-wheelers:Hub motor designs penetrate Indonesian and Vietnamese urban mobility markets with brushless DC platforms displacing internal combustion engines.
- Buses:Municipal transit electrification in China and Europe drives demand for liquid-cooled high-torque motors with 300kW+ continuous ratings.
Volume crown: Passenger Cars. Fastest climb: Commercial Vehicles.
Cooling Method:
Thermal management architecture determines sustained power output and magnetic stability under highway loads.
- Liquid Cooling:Ethylene-glycol coolant loops maintain stator temperatures below 150°C during sustained autobahn cruising. Hairpin winding geometries pair with liquid cooling to achieve slot fill factors above 70% in German and Chinese production lines.
- Air Cooling:Passive finned housings serve low-speed urban applications where cost minimization outweighs thermal headroom requirements.
- Oil Cooling:Direct rotor spray cooling enables 20,000+ RPM operation in silicon carbide inverter pairings for premium architectures.
- Hybrid Cooling:Combined liquid-stator and oil-rotor systems target motorsport and hypercar applications with extreme duty cycles.
Mainstream standard: Liquid Cooling. Emerging frontier: Hybrid Cooling.
Power Rating:
Platform voltage class and vehicle mass dictate power tier selection across OEM lineups.
- High Power:150-300kW continuous ratings serve premium passenger cars and light commercial vehicles with 800V architectures. Silicon carbide inverter convergence enables power density gains that shrink motor mass while maintaining thermal margins.
- Medium Power:50-150kW segment captures compact and mid-size passenger car platforms with 400V systems. China's MIIT credit system concentrates demand among domestic battery-electric producers optimizing for cost-performance balance.
- Low Power:Below 50kW designs dominate Asian two-wheeler electrification with hub motor integration.
- Ultra High Power:Above 300kW ratings target heavy-duty trucks, buses, and performance applications requiring specialized thermal architectures.
Revenue concentration: High Power. Volume anchor: Medium Power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive electrification engineering through Stuttgart's powertrain supplier corridor, establishing the technical foundations that now diffuse across battery-electric vehicle manufacturing worldwide.
China
MIIT's new energy vehicle credit system concentrates procurement among domestic battery-electric platform producers. The dual carbon goals tighten efficiency requirements for traction motor architectures. Jiangxi and Inner Mongolia processing corridors supply heavy rare earth magnets to motor manufacturers in Shenzhen and Shanghai.
Germany
EU Green Deal vehicle emissions targets cascade into powertrain electrification roadmaps across Stuttgart and Munich engineering centers. ECE R100 certification requirements gate supplier qualification for 800V architectures. Baden-Württemberg's automotive supplier corridor anchors ISO 26262 functional safety engineering talent.
United States
EPA tailpipe standards tighten fleet emissions ceilings, accelerating electric platform rollouts from Detroit and California design studios. California's Advanced Clean Trucks regulation opens procurement channels for high-torque motor architectures. The Midwest manufacturing belt hosts stator winding automation investments for tier-one motor contracts.
Japan
METI industrial policy directs rare earth magnet recycling investments and silicon carbide semiconductor pairing research. Nagoya and Tokyo engineering centers specialize in high-speed permanent magnet motor designs. Toyota City and surrounding Aichi Prefecture clusters integrate motor production with platform-sharing alliances.
South Korea
Hyundai-Kia's E-GMP architecture exemplifies specification concentration across multiple vehicle programs. Seoul and Busan engineering teams negotiate multi-year motor supply agreements spanning passenger car and commercial vehicle platforms. Government battery-electric vehicle subsidies accelerate domestic motor procurement volumes.
EV Traction Motor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and automation depth. The vendor base stratifies between integrated powertrain divisions and specialized motor fabricators. Three archetypes dominate: diversified industrial conglomerates with automotive divisions, pure-play motor specialists with geographic anchoring, and tier-one automotive suppliers with platform-sharing leverage. Competitive moves center on stator winding automation capex commitments and silicon carbide inverter pairing roadmaps.
Within the diversified industrial tier, Robert Bosch GmbH and Siemens AG occupy positions spanning powertrain integration and manufacturing automation respectively. Nidec Corporation exemplifies the geographic-anchoring archetype with dedicated factory investments. These three entities represent the strategic positioning spectrum from integrated system supply to specialized component scale.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| ABB Ltd. |
| Siemens AG |
| Nidec Corporation |
| ZF Friedrichshafen AG |
| Continental AG |
| Hitachi Automotive Systems Ltd. |
| BorgWarner Inc. |
| Valeo SA |
| Others |
Value Network & Pricing Analysis
EU Green Deal vehicle emissions targets gate qualified supply access and premium-tier pricing power for traction motor manufacturers serving European OEM procurement committees. Tier-one suppliers with ECE R100 certification and ISO 26262 ASIL-D ratings command pricing premiums over uncertified competitors locked out of 800V architecture programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the EV traction motor market by certification grade and volume scale. Premium tiers attach to ASIL-D functional safety ratings and silicon carbide-ready designs, while standard tiers serve 400V passenger car platforms with established hairpin winding automation. Price differentiation hinges on thermal performance consistency and stator winding slot fill factors. Cost compression in the economy tier is intensifying because Chinese domestic producers optimize for MIIT credit system compliance at scale. Fleet procurement officers at commercial vehicle operators show highest price sensitivity; luxury passenger car platform engineers show lowest.
Supply Chain Analysis
Magnet remanufacturing and rare earth recovery flows from end-of-life motors are emerging as secondary supply channels reducing virgin material dependency. Jiangxi and Inner Mongolia processing corridors in China, alongside Japanese magnet recycling investments directed by METI policy, anchor global neodymium-iron-boron supply. Heavy rare earth magnet production draws from concentrated chemical separation capacity. Single-source vulnerability in dysprosium and terbium processing creates exposure to export licensing shifts. Distribution runs through tier-one automotive supplier clusters in Stuttgart, Seoul, and Shanghai before final assembly at OEM powertrain integration facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV traction motor market functions as a regulatory compounder where EPA tailpipe standards and China's MIIT credit system jointly accelerate procurement volumes beyond underlying vehicle demand growth.
For Market Incumbents: To counter silicon carbide inverter convergence compressing motor design cycles, deepen stator winding automation capex commitments in Germany's automotive supplier corridor and secure captive magnet supply through offtake agreements with Jiangxi processors. ISO 26262 functional safety certification investment remains the critical defensive moat against mid-tier suppliers bidding on tier-one contracts. For New Entrants and Emerging Players: Regional haul fleet operators in California and the European Union represent the most penetrable buyer archetype for axial-flux motor architectures as Advanced Clean Trucks regulation deadlines tighten. Indonesian and Vietnamese two-wheeler electrification offers white-space volume for cost-optimized brushless DC hub motor platforms displacing internal combustion engines. Go-to-market execution should anchor on direct fleet operator relationships bypassing established tier-one supply hierarchies. For Investors and Strategic Acquirers: Roll-up economics work for specialized motor fabricators with hairpin winding automation capabilities because platform-sharing alliances are consolidating specifications across 5-10 vehicle programs. The five-to-ten year viability window favors targets with silicon carbide-ready design portfolios and existing ECE R100 certification timelines. Monitor silicon carbide inverter pairing roadmaps at premium passenger car OEMs as the inflection signal for which motor architectures capture next-generation platform awards.| Strategic Initiative | Industry Significance |
|---|---|
| Hairpin Winding Automation Scale-Up | Robotic winding cells in Stuttgart and Shenzhen achieve slot fill factors above 70% for 800V motors. |
| Rare Earth Magnet Supply Agreement | Long-term offtakes with Jiangxi processors secure heavy rare earth access for permanent magnet synchronous motors. |
| Silicon Carbide Inverter Partnership | Wide-bandgap pairing enables 20,000+ RPM operation unlocking power density gains for premium architectures. |
| ISO 26262 ASIL-D Certification Investment | Functional safety ratings gate OEM qualification for torque control systems in Stuttgart's engineering corridor. |
| Axial-Flux Motor Platform Development | High-torque architectures capture commercial vehicle procurement channels as fleet electrification deadlines tighten. |
Research Methodology
Bottom-up vehicle platform modeling reconciled against top-down supplier capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, tier-one supplier procurement directors, stator winding equipment manufacturers, and rare earth magnet trading specialists combined with secondary validation from EPA regulatory filings, MIIT new energy vehicle credit databases, ECE R100 certification registries, and IHS Markit vehicle production data. Triangulation between demand-side procurement timelines and supply-side automation capex commitments ensures volume estimates align with observable manufacturing investments.
Historical trendline analysis of passenger car and commercial vehicle electrification roadmaps established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated motor type, vehicle architecture, cooling method, power rating tier, and regional regulatory cluster dimensions. CAGRs were derived from fitted adoption curves weighted by fleet electrification mandate enforcement calendars and OEM platform rollout schedules. Silicon carbide inverter penetration assumptions and rare earth magnet price trajectories fed directly into motor cost curve projections.
Underlying measurement precision varies by segment; passenger car platform-sharing alliances carry tighter precision than fragmented two-wheeler electrification markets. Forecasts incorporate assumptions regarding MIIT credit system enforcement intensity and EU Green Deal implementation timelines that could shift materially. Practitioners should monitor silicon carbide inverter adoption rates at premium OEMs and rare earth export licensing patterns for early signals of motor architecture preference shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Motor Gear Unit Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
GCC Electric Motor Market
Electric Motor
Traction Motor Core Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Smart E-Drive Market
Electric Motor
High Speed Motor Market
Electric Motor
Intelligent Motor Control Market
Electric Motor
Motors for Robot Body and Robot Wheels Market
Electric Motor
Global Automotive Starter Motor Market
Electric Motor
Electric Drives Market
Electric Motor
Large Synchronous Motor Market
Electric Motor
Torque Motor Market
Electric Motor
Kayak Trolling Motor Market