
 Pet Sitting Market | 2026-2036
Pet Sitting Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Sitting Market Intelligence
A shortage of certified pet care professionals is redrawing competitive dynamics across the industry. Rover.com leverages its technology infrastructure to match sitters with pet owners across hundreds of cities. Dogtopia Enterprises anchors its position through specialized daycare and boarding facilities with trained staff. Wag! Group Co. competes on speed, offering on-demand dog walking through its mobile-first platform.
Pet sitting encompasses scheduled care services delivered in a pet's residence or a caregiver's home, typically involving feeding, exercise, medication administration, and companionship for periods ranging from thirty minutes to several weeks. The service functions as a substitute for kennel boarding, preserving familiar environments that reduce animal stress and behavioral disruption. In-home sitting and drop-in visits dominate transaction volume due to lower price points and minimal sitter commitment, while overnight care captures premium margins from extended engagements. Dog walking generates the highest frequency among urban busy professionals, and seniors increasingly drive demand for daily visit packages tailored to aging pets.
The US market operates under a patchwork of state-level contractor classification laws and local animal control ordinances that determine sitter eligibility and liability exposure. The American Pet Products Association and Pet Sitters International maintain voluntary certification programs that influence consumer trust and platform onboarding standards. Stakeholders must monitor evolving municipal regulations on gig worker employment status, as reclassification rulings would reshape cost structures and pricing models across platform-based and independent service channels.
Market Dynamics
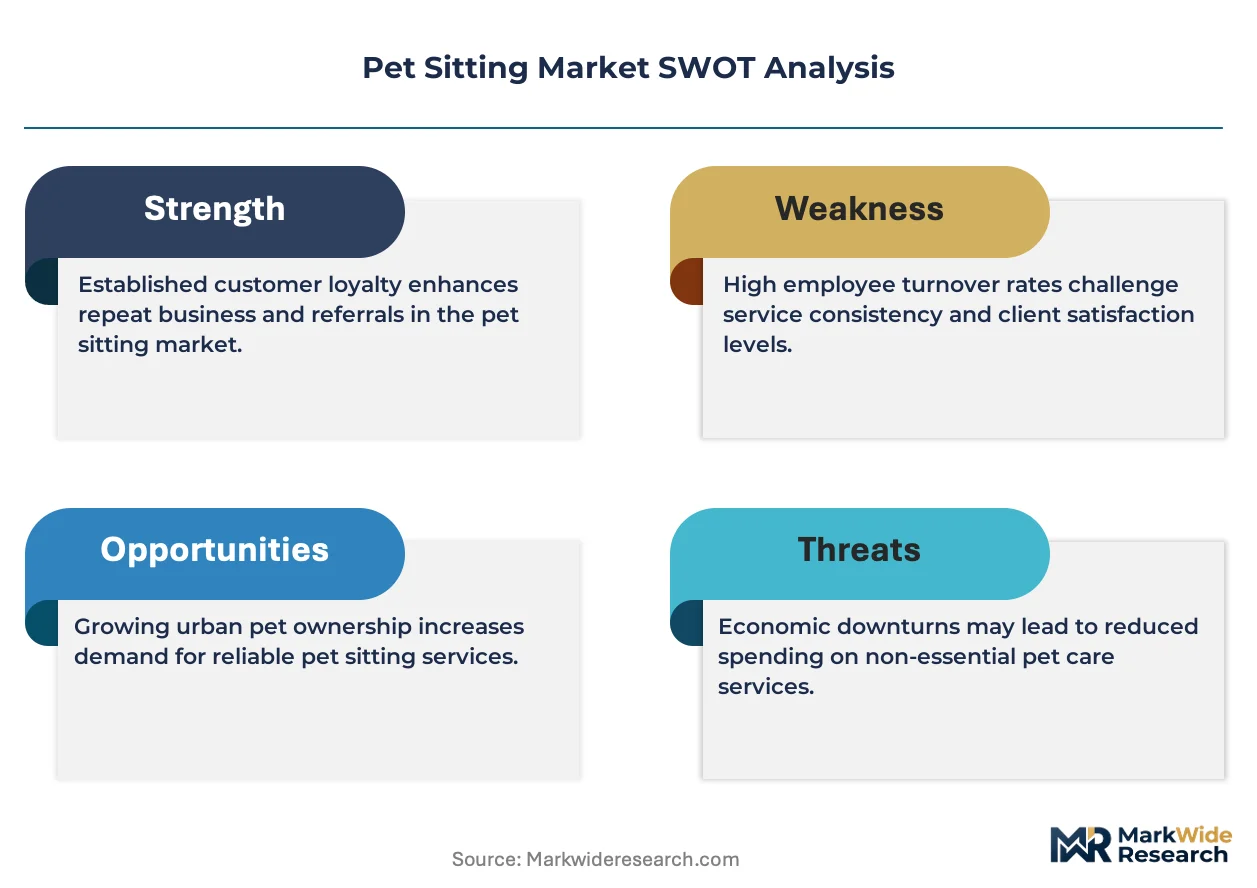
ISO certification standards for animal welfare services are restructuring competitive entry barriers across the pet sitting industry, forcing platforms to invest in training infrastructure and compliance documentation that independent operators struggle to match.
Growth Catalysts
- Urban Pet Density:Millennials and Gen Z pet owners in New York, Los Angeles, and Chicago generate concentrated demand for on-demand pet care platforms that match sitters with owners through algorithmic scheduling.
- Remote Work Normalization:Hybrid work patterns have created irregular schedules that fuel demand for flexible drop-in visits and midday dog walking services rather than traditional kennel boarding.
- Pet Humanization Trends:Owners increasingly reject kennel environments in favor of in-home care that preserves familiar surroundings and reduces separation anxiety in companion animals.
Market Restraints
- Certified Labor Scarcity:The shortage of trained pet care professionals limits platform expansion and forces wage inflation in metropolitan markets where demand concentrates.
- Contractor Classification Risk:Municipal reclassification rulings on gig worker employment status threaten to reshape cost structures and eliminate the variable labor model that underpins platform economics.
- Substitution by Technology:Automated pet feeders, camera-based monitoring systems, and smart dog doors enable owners to reduce sitting frequency for short absences.
Strategic Opportunities
- Senior Pet Specialization:Daily visit packages tailored to aging pets with medication administration and mobility assistance capture premium pricing from the expanding senior pet demographic.
- Corporate Channel Development:Employer-sponsored pet care benefits represent an underdeveloped B2B channel that platforms can penetrate through HR benefit marketplaces.
- Veterinary Integration:Partnerships with clinic networks for post-surgical recovery sitting and chronic condition monitoring create referral-driven revenue streams with higher retention rates.
Industry Challenges
- Insurance and Liability Complexity:Patchwork state-level liability frameworks create compliance friction for multi-state platforms and expose independent sitters to uncovered claims.
- Quality Assurance at Scale:Maintaining consistent service standards across thousands of distributed contractors requires technology investment that compresses margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Sitting Market |
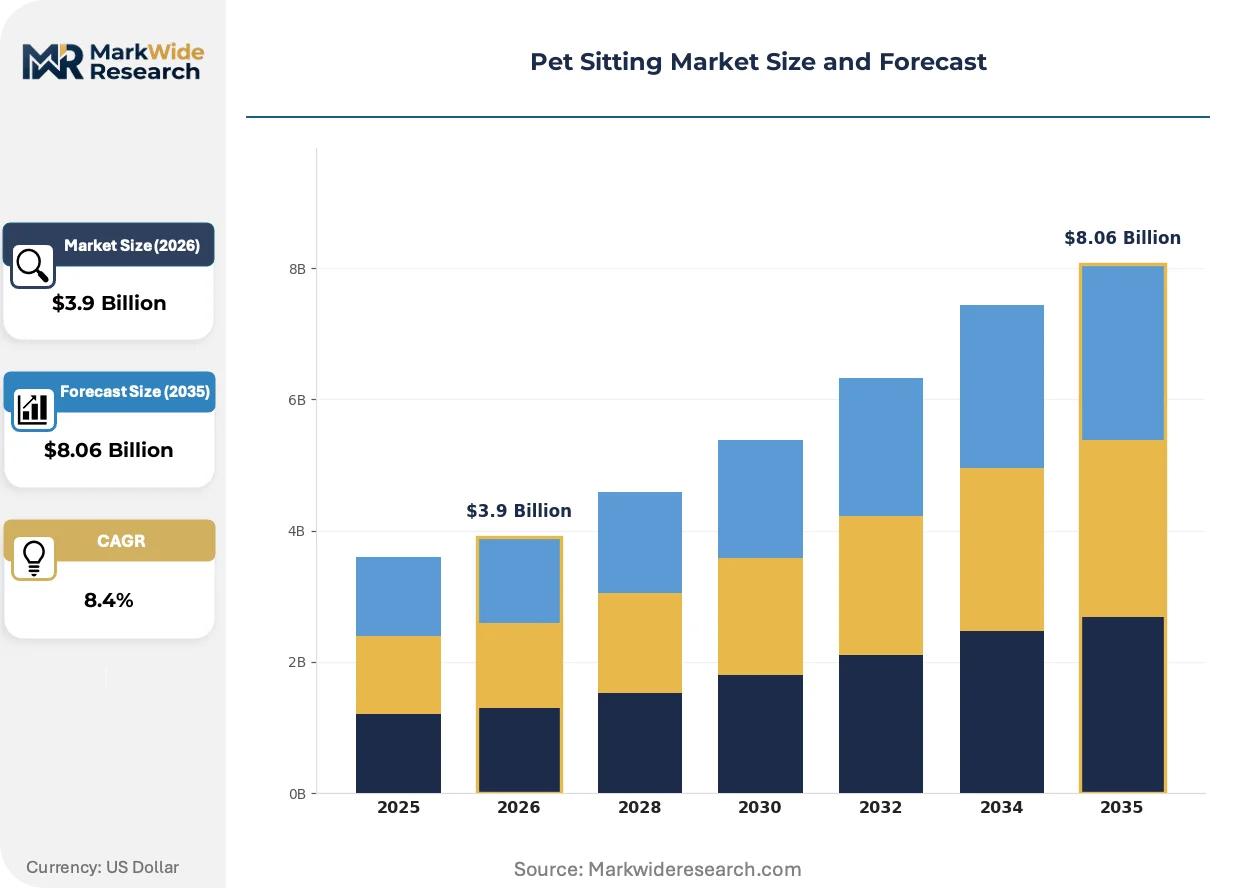
| Market Size in 2026 | $3.9 Billion |
| Market Size in 2035 | $8.06 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In-Home Sitting, Drop-In Visits, Dog Walking, Overnight Care Customer Type: Pet Owners, Busy Professionals, Seniors, Families Pet Type: Dogs, Cats, Birds, Small Mammals Duration: Short-Term, Long-Term, Daily, Weekly |
| Companies Covered | Fetch! Pet Care, Dogtopia Enterprises, Rover.com, Wag! Group Co., PetSmart Inc., Petco Health and Wellness Company Inc., Best Friends Pet Care, TrustedHousesitters Ltd., Camp Bow Wow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Sitting Market Strategic Shifts & Innovations
Technology infrastructure is compressing the traditional matchmaking layer between pet owners and caregivers, while regulatory scrutiny and shifting owner expectations reshape how services are delivered and verified.
AI-powered scheduling and real-time GPS tracking is supplanting manual coordination methods that previously dominated the industry. Urban professionals now expect instant booking confirmation and live walk tracking as standard features. This capability compression is eliminating independent sitters who lack platform-backed technology infrastructure.
ISO animal welfare certification requirements are mandating documented training protocols and facility inspections that raise operational standards across the industry. Service providers must maintain verifiable records of sitter qualifications and incident reporting. Platforms with existing compliance infrastructure are absorbing smaller competitors who cannot meet documentation burdens.
Subscription-based care packages are displacing transactional per-visit purchasing among recurring users. Busy professionals in Chicago and Los Angeles now prefer unlimited monthly walk plans with guaranteed sitter assignment over ad-hoc booking. This shift locks in predictable revenue for platforms while reducing owner price sensitivity to individual visit costs.
Pet Sitting Market Segmentation
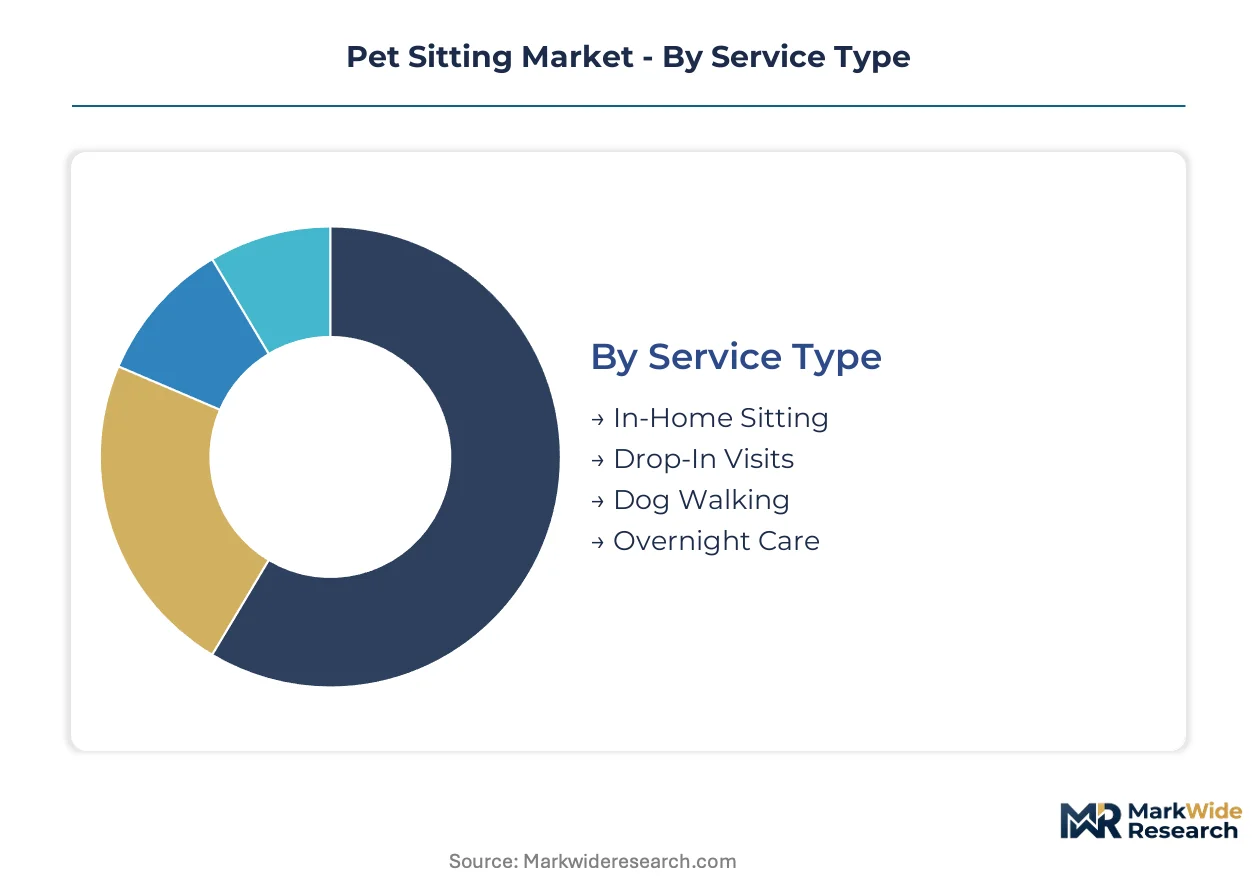
Service configuration and customer profile determine pricing power and retention economics in pet sitting. Regulatory compliance requirements vary sharply across service formats, creating tiered barriers that reshape competitive positioning.
Service Type:
ISO certification standards for animal welfare services impose documentation burdens that favor platforms with training infrastructure over independent operators.
- In-Home Sitting:Caregivers reside in the pet owner's residence for extended periods, maintaining familiar environments that reduce separation anxiety. Demand concentrates among affluent households in New York and Los Angeles where travel frequency exceeds kennel tolerance.
- Drop-In Visits:Brief 30-60 minute welfare checks involving feeding, exercise, and medication administration. Chicago urban professionals drive volume for midday visits that accommodate hybrid work schedules.
- Dog Walking:Scheduled exercise sessions generating highest transaction frequency among urban dog owners. Municipal leash laws and liability insurance requirements create compliance friction for unlicensed operators.
- Overnight Care:Extended stays in caregiver residences or dedicated facilities. Premium pricing reflects facility certification costs and specialized staff training for medical administration.
In-Home Sitting handles the majority of throughput; Dog Walking is expanding most quickly on share.
Customer Type:
Cost tier differentiation separates subscription-based recurring users from transactional purchasers.
- Pet Owners:General category encompassing all companion animal households seeking substitute care during absences. Volume concentrates in metropolitan clusters with high pet density and dual-income households.
- Busy Professionals:Time-constrained urban workers prioritizing convenience and instant booking over price. This segment generates premium margins through unlimited monthly walk plans and guaranteed sitter assignment.
- Seniors:Aging pet owners requiring daily visit packages with medication administration and mobility assistance. Demographic expansion drives demand for specialized geriatric pet care protocols.
- Families:Multi-pet households with irregular schedules favoring flexible booking platforms over traditional kennel arrangements.
Busy Professionals contribute the largest revenue pool; Seniors are gaining share fastest as the aging pet population expands.
Pet Type:
Application requirements vary substantially across species, with canine care dominating platform infrastructure investment.
- Dogs:Exercise-dependent animals requiring walking, feeding, and companionship services. Municipal licensing requirements and leash ordinances impose compliance documentation that platforms manage through centralized verification systems.
- Cats:Lower-maintenance pets suited to drop-in visit formats with litter maintenance and feeding protocols. Independent sitters compete effectively in this segment due to reduced liability exposure.
- Birds:Specialized care involving dietary precision and environmental control. Avian veterinary partnerships create referral channels for certified providers.
- Small Mammals:Rabbits, guinea pigs, and rodents requiring habitat maintenance and species-specific handling. Niche demand concentrates among urban apartment dwellers with space constraints.
Dogs account for the dominant service volume; Small Mammals are climbing the fastest as exotic pet ownership rises in dense urban markets.
Duration:
Margin structure inverts across time horizons, with short engagements commanding premium per-hour rates while long-term packages lock predictable revenue.
- Short-Term:Single-session or brief engagements under 48 hours. Premium pricing reflects coordination overhead and last-minute booking penalties.
- Long-Term:Extended absences exceeding one week, typically involving in-home sitting or overnight facility care. Subscription discounts reduce per-day costs while improving sitter utilization.
- Daily:Recurring weekday services including dog walking and medication administration. Platform algorithms optimize route density to improve contractor earnings.
- Weekly:Structured care packages with guaranteed sitter continuity. Corporate benefit channels increasingly subsidize these arrangements for employee retention.
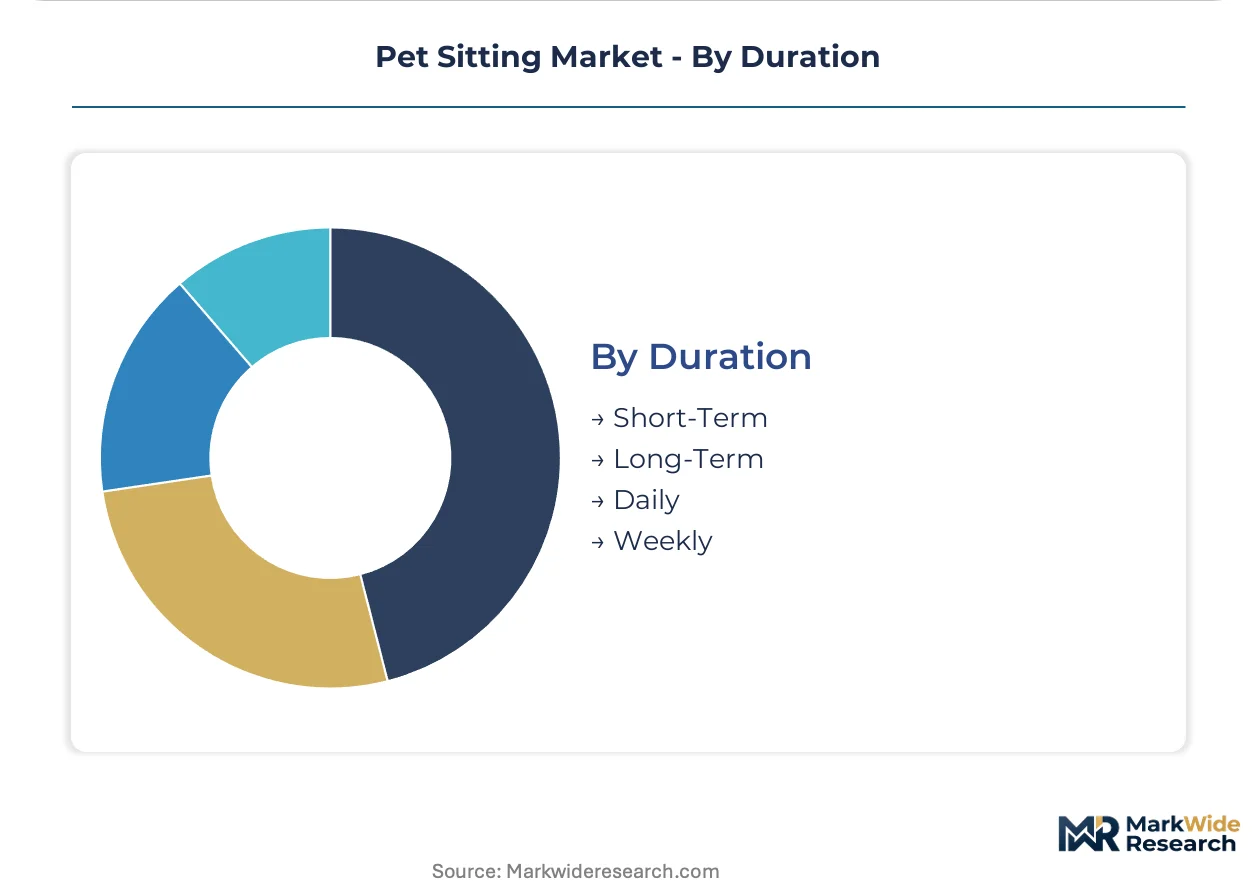
Daily services generate the highest transaction frequency; Weekly packages show the steepest expansion trajectory as employer-sponsored benefits penetrate HR marketplaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet sitting consumption patterns diverge sharply across markets, with US households favoring on-demand platform booking while European owners prioritize certified facility-based care and Asian markets blend informal neighborhood networks with emerging app-based services.
United States
Millennial and Gen Z pet owners in New York, Los Angeles, and Chicago drive concentrated demand for algorithmic matching platforms that coordinate irregular drop-in visits around hybrid work schedules. Municipal contractor classification laws in California and New York create compliance friction as cities debate gig worker reclassification. The Northeast Corridor generates premium pricing for overnight in-home sitting among affluent dual-income households with frequent business travel.
Germany
Pet owners exhibit strong preference for TÜV-certified facilities and documented animal welfare protocols over informal arrangements. The country's federal animal protection ordinance mandates specific training hours for commercial pet handlers, raising entry barriers for independent operators. Bavaria and North Rhine-Westphalia host dense concentrations of specialized daycare centers serving urban professionals in Munich and Düsseldorf.
United Kingdom
London households generate outsized demand for dog walking services among time-constrained finance and tech workers seeking midday exercise solutions. DEFRA's animal activities licensing regulations impose inspection requirements on commercial boarding operations. The Southeast region concentrates premium in-home sitting services for affluent commuters with international travel patterns.
Japan
Aging pet demographics in Tokyo and Osaka fuel demand for specialized geriatric care packages with medication administration protocols. METI's guidelines on service worker standards influence platform onboarding requirements for pet handlers. The Kanto region exhibits highest platform penetration as urban density supports route-optimized dog walking economics.
Australia
Coastal metropolitan markets in Sydney and Melbourne favor house-sitting exchanges that combine pet care with property security for extended absences. State-level animal welfare acts in New South Wales and Victoria require registration of commercial pet boarding premises. Queensland's regional centers show emerging platform adoption among mining sector fly-in-fly-out workers.
Pet Sitting Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with technology platforms commanding urban density markets while facility operators anchor suburban family segments. The structure reveals three archetypes: algorithmic matching platforms, specialized daycare and boarding facilities, and hybrid retail-service chains. Consolidation pressure intensifies as ISO certification requirements favor scaled training infrastructure. Strategic moves concentrate on geographic densification in high-pet-density metros and vertical integration into veterinary referral networks.
Within the platform-matching tier, Rover.com and Wag! Group Co. occupy positions defined by technology infrastructure and mobile-first user experience. Dogtopia Enterprises anchors the facility-based specialist segment with dedicated training protocols and physical presence strategies. These three exemplify how competitive positioning separates digital-native coordination engines from brick-and-mortar care providers.
| Leading Market Players |
|---|
| Fetch! Pet Care |
| Dogtopia Enterprises |
| Rover.com |
| Wag! Group Co. |
| PetSmart Inc. |
| Petco Health and Wellness Company Inc. |
| Best Friends Pet Care |
| TrustedHousesitters Ltd. |
| Camp Bow Wow |
| Others |
Cost & Logistics Intelligence
Platform-scale sitter networks in New York and Los Angeles generate utilization efficiencies that compress per-visit coordination costs below independent operator breakeven, establishing price floors that exclude fragmented competitors from metropolitan density markets. This scale-concentration dynamic concentrates supply-side power among algorithmic matching platforms while forcing wage inflation in certified labor pools.
Pricing Analysis
Long-term subscription contracts dominate revenue architecture across major platforms, with unlimited monthly walk plans locking recurring users into predictable payment streams that reduce per-visit price sensitivity. Three-tier pricing structure across premium, standard, and economy levels separates overnight in-home sitting with ISO-certified sitters from midday drop-ins and algorithm-matched dog walking. Cost compression in the standard tier is intensifying because contractor wage inflation in Chicago and Los Angeles outpaces platform pricing power. Busy professionals exhibit lowest price sensitivity due to convenience premium, while seniors on fixed budgets drive demand for economy-tier daily visit packages.
Supply Chain Analysis
Certified sitter certification bottlenecks in California and New York constrain platform expansion velocity and create regional supply-demand imbalances that ripple through pricing. The labor pool draws from gig-economy platforms, veterinary technician training programs, and independent pet care specialists. Single-source vulnerability concentrates in metropolitan markets where ISO-compliant training infrastructure remains underdeveloped. Distribution runs through mobile-first booking interfaces that compress customer acquisition costs relative to traditional facility-based channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pet sitting penetration remains below saturation across employer-sponsored benefit channels, with hybrid work normalization creating irregular care schedules that subscription platforms capture more efficiently than legacy kennel operators.
For Market Incumbents: Secure ISO certification infrastructure as a defensive moat against municipal reclassification rulings that would eliminate variable labor economics. Deepen backward integration into veterinary referral networks to capture post-surgical recovery sitting demand with higher retention rates. Anchor platform density in Chicago and Los Angeles before competitor route optimization achieves critical mass. For New Entrants and Emerging Players: Anchor in corporate HR benefit marketplaces where employer subsidy reduces customer acquisition friction and locks recurring revenue. Target senior pet specialization in aging urban demographics where medication administration protocols create certification barriers for generalist competitors. Lead with veterinary clinic partnerships rather than direct-to-consumer marketing to establish referral-driven credibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with compliance documentation systems that absorb smaller competitors under ISO animal welfare mandates. Long-term viability hinges on contractor classification regulatory outcomes across California and New York. Monitor municipal gig worker reclassification litigation as the primary inflection signal for platform cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| ISO Certification Infrastructure Investment | Documentation systems satisfy municipal inspection requirements that exclude independent operators from premium pricing tiers. |
| Veterinary Network Partnership | Clinic referrals generate post-surgical recovery sitting demand with retention rates exceeding transactional customer acquisition. |
| Corporate Benefit Channel Penetration | HR marketplace integration locks employer-subsidized subscription revenue with reduced price sensitivity. |
| Senior Pet Specialization Protocol | Geriatric care packages with medication administration capture premium pricing from expanding aging pet demographics. |
| Geographic Density Expansion | Route optimization algorithms improve contractor earnings and retention in high-pet-density metropolitan clusters. |
Research Approach
Initial hypotheses were tested against primary input from platform operations executives, certified pet care trainers, veterinary clinic administrators, and HR benefits managers and refined through secondary validation against municipal animal control ordinances, American Pet Products Association certification databases, SEC filings of publicly traded platform operators, and state-level contractor classification rulings. Bottom-up sitter supply estimates triangulated with top-down pet owner expenditure surveys.
Variance decomposition across service type, customer archetype, pet species, and duration configuration enabled segment-level growth attribution throughout the forecast period. CAGRs were derived from penetration modeling of subscription adoption against hybrid work schedule prevalence and certified labor pool expansion. Industry-specific inputs incorporated municipal gig worker reclassification probability assessments and ISO certification rollout timelines across major metropolitan markets.
Underlying assumptions cover sustained hybrid work normalization and stable contractor classification frameworks, with deviation risk concentrated in municipal employment law shifts and substitution acceleration from automated pet monitoring technologies. Practitioners should keep alternative scenarios live as regulatory enforcement patterns and pet owner technology adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
UK Pet Boarding Market
Pet Care Products
GPS Dog Collar Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
Pet Tag Market
Pet Care Products
Dog Crate Furniture Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
Pet Bathing Supplies Market
Pet Care Products
Saudi Arabia Pet Food Market
Pet Care Products
South Africa Pet Boarding Market
Pet Care Products
Toy Dog Market
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
Poland Pet Food Market
Pet Care Products
Dog Shampoo Market
Pet Care Products
Dog Biscuit Market
Pet Care Products
Asia-Pacific Pet Clothing Market
Pet Care Products
Smart Pet Collar Market