
 Organic Dog Food Market | 2026-2036
Organic Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Dog Food Market Analytics
The capital-intensity divergence between multinational feed manufacturers and artisanal raw-food specialists is reorganizing competitive tiers in organic canine nutrition. Nestlé Purina PetCare leverages its captive supply chain to control ingredient traceability from farm to kibble, while Stella & Chewy's differentiates through freeze-dried raw formulations that command shelf-space premiums in specialty channels. Open Farm anchors its position with blockchain-verified sourcing that appeals to sustainability-motivated buyers.
Organic dog food comprises nutritionally complete formulations manufactured from ingredients certified under national organic programs, requiring minimum organic content thresholds and prohibiting synthetic pesticides, antibiotics, and genetically modified organisms in protein and carbohydrate inputs. Dry food dominates volume throughput due to logistics efficiency and extended shelf stability, though fresh food segments attract margin-rich subscription revenue as cold-chain infrastructure matures. Grain-free formulations retain strong positioning within premium tiers despite ongoing FDA investigations into canine dilated cardiomyopathy correlations.
USDA National Organic Program standards govern label claims in the United States, while EU Regulation 2018/848 shapes import requirements and equivalence determinations for European trade. The FDA Center for Veterinary Medicine monitors adverse event reporting and ingredient safety notifications, creating compliance overhead that favors scaled operators with dedicated regulatory affairs functions. Stakeholders must monitor evolving state-level packaging waste legislation and ingredient disclosure mandates that will reshape formulation transparency requirements.
Market Dynamics
USDA National Organic Program certification requirements are tightening ingredient traceability mandates, forcing manufacturers to restructure supplier relationships and absorb compliance costs that favor scaled operators over artisanal competitors.
Growth Catalysts
- EU Regulation 2018/848 equivalence determinations:Streamlined import pathways for certified organic pet food into European markets reduce regulatory friction for compliant exporters.
- Urban pet ownership density:Metropolitan clusters in the United States concentrate premium pet owners willing to pay certification premiums for human-grade ingredient standards.
- Cold-chain infrastructure maturation:Refrigerated logistics networks enable fresh and raw organic formulations to reach subscription customers with viable shelf-life economics.
Market Restraints
- Organic protein input cost volatility:Certified organic chicken and beef supplies face pricing pressure from competing human food demand and limited pasture availability.
- Supplier concentration in Midwest grain belts:Organic corn and soybean sourcing clusters in Illinois and Iowa create geographic vulnerability to weather-driven crop failures.
- FDA Center for Veterinary Medicine adverse event reporting overhead:Mandatory notification systems impose fixed compliance costs that disproportionately burden small-batch manufacturers.
Strategic Opportunities
- Blockchain-verified sourcing platforms:Distributed ledger technology enables real-time ingredient provenance disclosure that commands retail price premiums in specialty channels.
- Veterinary prescription integration:Therapeutic organic formulations distributed through clinic networks capture recurring revenue from condition-managed canine populations.
- State-level packaging waste legislation:Extended producer responsibility mandates in California and New York create first-mover advantages for recyclable or compostable packaging innovators.
Industry Challenges
- Organic certification timeline compression:USDA-accredited certifier backlogs delay new product launches by six to eighteen months, constraining formulation innovation cycles.
- Veterinary nutritionist talent scarcity:Board-certified animal nutrition professionals command salary premiums that strain mid-tier manufacturer R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Dog Food Market |
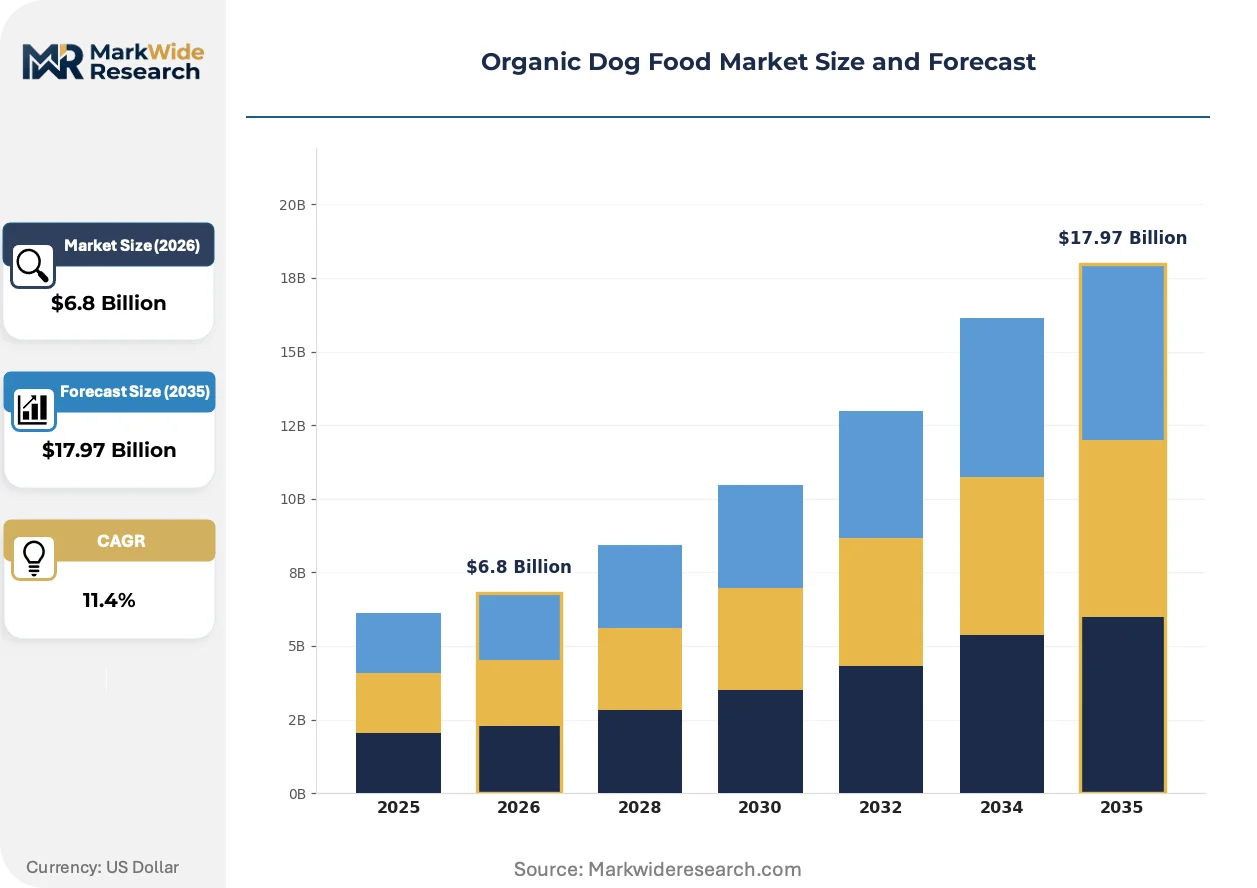
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Fresh Food Ingredient Type: Meat-Based, Grain-Free, Vegan, Holistic Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Veterinary Clinics Customer Type: Pet Owners, Breeders, Pet Retailers, Animal Shelters |
| Companies Covered | Nestlé Purina PetCare, General Mills, Mars Petcare, Castor & Pollux Natural Petworks, Primal Pet Foods, Newman's Own, Grandma Lucy's, Stella & Chewy's, Open Farm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Dog Food Market Evolving Landscape
Freeze-drying technology and cellular agriculture inputs are redrawing formulation possibilities, while regulatory disclosure mandates and direct-to-consumer channel expansion reshape how organic dog food reaches end buyers.
High-pressure processing is fragmenting the raw organic segment by enabling pathogen reduction without thermal degradation of heat-sensitive nutrients. Boutique manufacturers in Colorado and Oregon are adopting HPP systems to meet USDA organic standards while extending refrigerated shelf life. This technology is fragmenting competitive tiers by allowing smaller players to match the safety profiles of multinational freeze-dried operations without capital-intensive lyophilization infrastructure.
EU Regulation 2018/848 imposes stricter residue testing and import documentation requirements for organic pet food entering European markets. Manufacturers must now maintain dual certification paperchains for US and EU equivalence, increasing administrative overhead. Raw and fresh format exporters face the steepest compliance burden, with many redirecting volume toward domestic subscription channels rather than navigating transatlantic regulatory complexity.
Subscription-based replenishment models are displacing conventional retail purchasing among urban millennial and Gen Z pet owners. Direct-to-consumer platforms capture recurring revenue through algorithmic portion sizing and automated delivery schedules. This behavioral shift concentrates most visibly in coastal United States metropolitan areas, where cold-chain last-mile logistics have achieved sufficient density to support fresh-format economics.
Organic Dog Food Market Segmentation
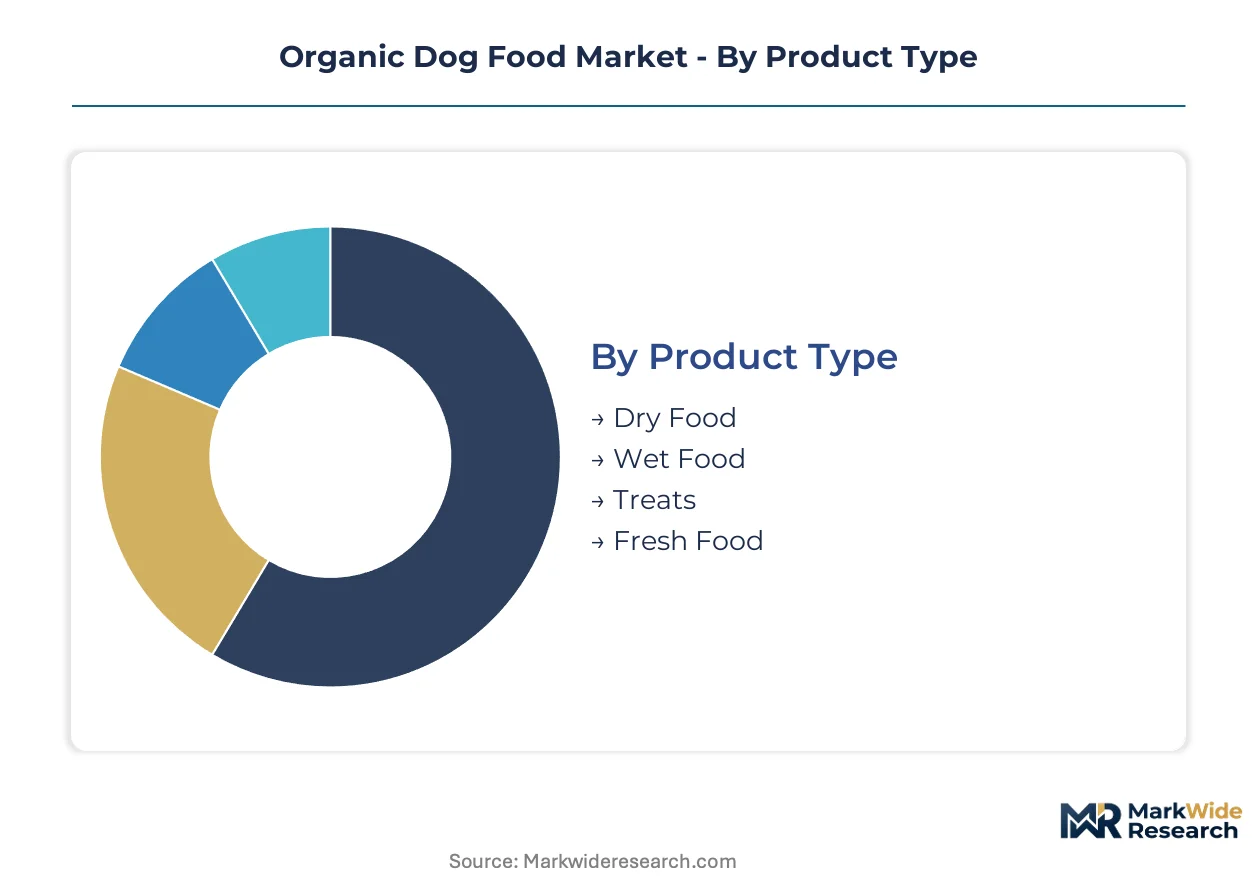
Organic dog food segmentation reveals how certification tiers, ingredient sourcing constraints, and channel economics partition demand across distinct buyer profiles. Each category reflects divergent compliance burdens and margin structures that reshape competitive positioning.
Product Type:
USDA National Organic Program standards impose varying traceability requirements across formats, with moisture content and processing methods determining certification complexity and shelf-life economics.
- Dry Food:Extruded kibble formulations with sub-10% moisture content dominate logistics efficiency and extended shelf stability. Urban pet owners in United States metropolitan clusters favor dry formats for subscription replenishment due to storage convenience and lower shipping costs per calorie delivered.
- Wet Food:Canned or pouch formats with 75-85% moisture content require thermal processing that complicates organic certification retention. Demand concentrates among small-breed owners and senior dog populations in coastal United States cities where palatability premiums justify higher per-serving costs.
- Treats:Supplementary formats with limited nutritional completeness claims face lighter regulatory scrutiny but carry USDA organic label requirements for ingredient percentages.
- Fresh Food:Refrigerated formulations with minimal processing attract subscription revenue in cold-chain-matured corridors.
Dry food handles the majority of throughput; fresh food is the fastest mover on share.
Ingredient Type:
Cost tier differentiation separates premium-positioned formats from mass-market alternatives, with protein sourcing intensity driving per-unit economics and certification timelines.
- Meat-Based:Formulations with certified organic chicken, beef, or fish as primary protein inputs command the highest ingredient costs and longest supplier audit cycles. Breeders and performance-dog owners in United States Midwest agricultural belts prefer meat-based options for growth-stage and working canine nutrition.
- Grain-Free:Carbohydrate substitutions using sweet potato, lentil, or pea inputs retain strong positioning despite FDA Center for Veterinary Medicine investigations into canine dilated cardiomyopathy correlations. Specialty store channels in United States coastal metros sustain grain-free premiums through educated consumer bases willing to parse ingredient panels.
- Vegan:Plant-protein formulations excluding all animal derivatives serve niche ethical-buyer segments with distinct amino acid supplementation requirements.
- Holistic:Integrative formulations incorporating functional ingredients like probiotics and botanicals target condition-managed dogs.
Meat-based formats anchor revenue concentration; grain-free offerings are expanding most quickly on volume.
Distribution Channel:
Volume concentration in veterinary and specialty channels reflects margin tolerance for certification premiums, while mass retail and direct-to-consumer routes scale through operational efficiency.
- Online Retail:Direct-to-consumer platforms with algorithmic portion sizing and automated replenishment capture recurring revenue from millennial and Gen Z pet owners. Subscription density peaks in United States coastal metropolitan areas where cold-chain last-mile logistics support fresh-format economics.
- Specialty Stores:Independent and chain pet retailers with trained staff provide education-intensive environments for premium organic positioning. Urban centers in United States Northeast and Pacific regions sustain specialty channel growth through consumer willingness to pay traceability premiums.
- Supermarkets:Mass retail placement requires price competitiveness that compresses margins on certified organic inputs.
- Veterinary Clinics:Prescription-adjacent distribution captures therapeutic and condition-managed canine populations with recurring purchase patterns.
Online retail is climbing the fastest on share; specialty stores retain the steepest margin structure.
Customer Type:
Application-based segmentation separates individual companion-animal owners from institutional buyers with distinct procurement patterns and nutritional specification requirements.
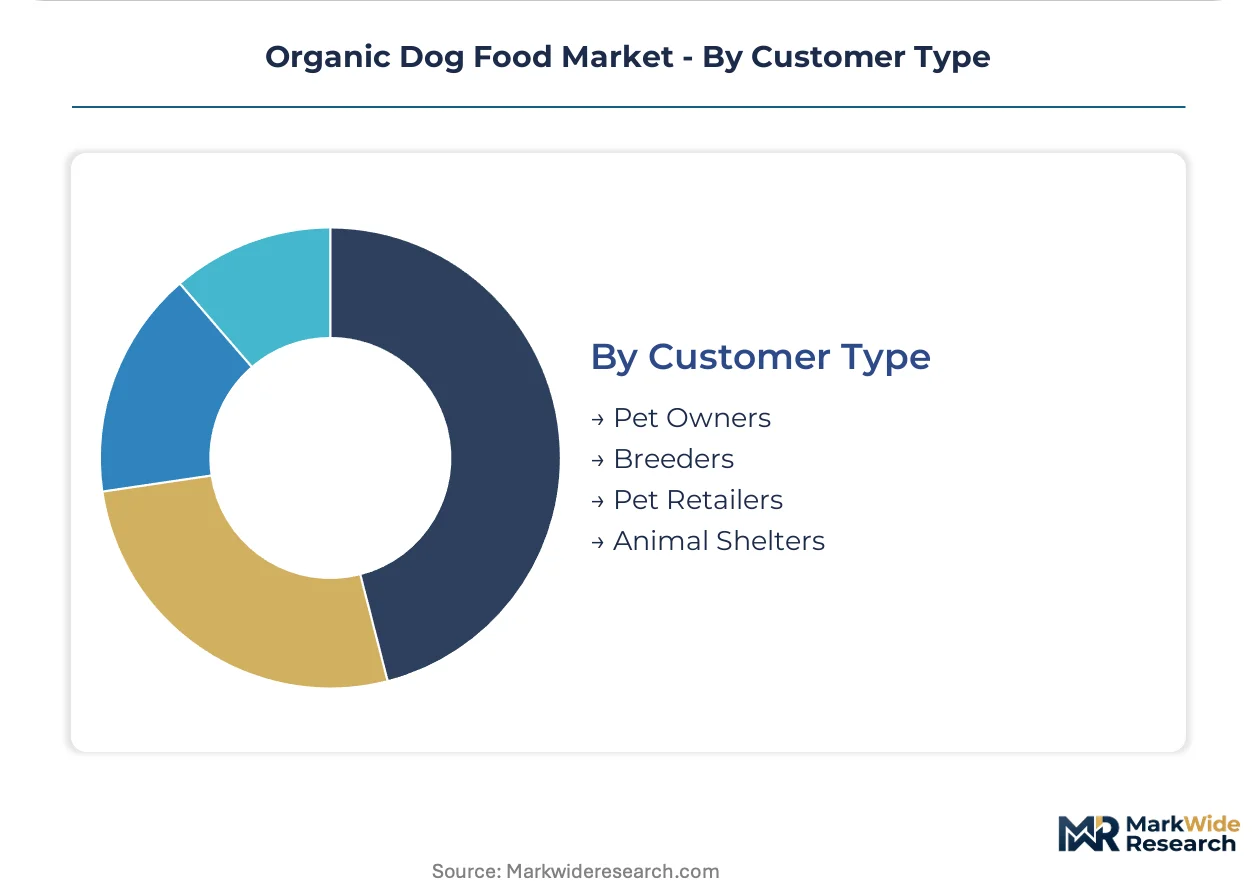
- Pet Owners:Individual households with one to three dogs drive premium-tier adoption through human-grade ingredient preferences and emotional purchasing triggers. United States urban and suburban clusters concentrate this segment through higher disposable income and veterinary service utilization rates.
- Breeders:Commercial and hobby breeding operations prioritize growth-stage formulations with documented nutritional completeness for reproductive health and puppy development.
- Pet Retailers:Reseller and private-label buyers source bulk organic formulations for store-brand positioning in competitive markets.
- Animal Shelters:Non-profit and municipal adoption facilities seek cost-optimized certified organic options for temporary canine populations.
Pet owners generate the dominant revenue share; breeders are gaining traction fastest on volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States coastal metros at roughly double the intensity of German urban centers, where retailer consolidation compresses organic certification premiums. This asymmetry reflects divergent cold-chain maturity and subscription-channel penetration across Atlantic markets.
United States
Urban pet ownership density in New York, Los Angeles, and Seattle drives premium-tier adoption through human-grade ingredient preferences. USDA National Organic Program certification requirements tighten traceability mandates, forcing supplier relationship restructuring. Cold-chain last-mile logistics in Pacific Northwest metropolitan corridors now support fresh-format subscription economics that bypass conventional retail markups.
Germany
EU Regulation 2018/848 equivalence determinations streamline import pathways for certified organic formulations, reducing regulatory friction for compliant exporters. EFSA residue testing protocols impose dual certification paperchains that increase administrative overhead for transatlantic suppliers. Berlin and Munich specialty retail clusters sustain premium positioning through educated consumer bases willing to parse ingredient provenance disclosures.
United Kingdom
Post-Brexit divergence from EU organic equivalence creates certification complexity for importers serving London and Southeast England metropolitan areas. Defra organic standards maintain parallel requirements that delay new product launches by extending certifier audit timelines. Manchester and Birmingham distribution hubs concentrate cold-chain infrastructure investment for fresh-format regional expansion.
France
ANSM and DGCCRF enforcement of EU 2018/848 residue documentation shapes import compliance burdens for raw and fresh format suppliers targeting Paris and Lyon urban markets. Île-de-France retail density supports specialty channel premiums, though mass retail consolidation limits pricing flexibility outside premium tiers. Auvergne-Rhône-Alpes agricultural belts supply certified organic protein inputs with shorter supplier audit cycles than transatlantic alternatives.
Canada
Health Canada and CFIA organic equivalency arrangements with the United States reduce cross-border certification duplication for Ontario and Quebec manufacturers. Toronto and Vancouver metropolitan clusters concentrate premium pet owner demand through veterinary service utilization rates exceeding national averages. Prairie province organic grain sourcing faces weather-driven volatility that compresses formulation margins during drought cycles.
Organic Dog Food Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with multinational feed manufacturers dominating scale economies while artisanal specialists capture formulation innovation premiums. The market structure organizes around three tiers: captive supply chain operators, freeze-dried raw specialists, and blockchain-verified sourcing platforms. Consolidation pressure favors scaled operators with dedicated regulatory affairs functions, while fragmentation persists in raw and fresh segments where high-pressure processing lowers capital barriers. Dominant competitive moves include backward integration into organic protein sourcing and direct-to-consumer channel expansion.
Within the multinational tier, Nestlé Purina PetCare and Mars Petcare occupy positions defined by captive supply chain control and mass retail distribution density. Stella & Chewy's exemplifies the freeze-dried raw specialist archetype commanding shelf-space premiums in specialty channels. Open Farm anchors the transparency-driven segment through blockchain-verified sourcing platforms that appeal to sustainability-motivated buyers in coastal United States markets.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| General Mills |
| Mars Petcare |
| Castor & Pollux Natural Petworks |
| Primal Pet Foods |
| Newman's Own |
| Grandma Lucy's |
| Stella & Chewy's |
| Open Farm |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Midwest organic grain cooperatives and multinational feed manufacturers lock in supply access while dampening price volatility for certified corn and soybean inputs. These arrangements concentrate procurement leverage among scaled operators who can absorb USDA National Organic Program audit costs, leaving artisanal competitors exposed to spot-market protein pricing swings.
Pricing Analysis
The customization-premium spread separates subscription-configured fresh formulations from standard dry kibble SKUs, with algorithmic portion sizing commanding recurring revenue premiums in coastal United States metros. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and ingredient traceability tier. Price differentiation hinges on blockchain-verified sourcing disclosures and cold-chain delivery guarantees. Cost compression in mass retail channels is intensifying because supermarket buyers demand price competitiveness that squeezes organic input margins. Breeders and institutional buyers exhibit highest price sensitivity; urban millennial pet owners in subscription channels show least.
Supply Chain Analysis
Midwest organic grain belt concentration creates a chokepoint where Illinois and Iowa corn and soybean sourcing clusters expose formulations to weather-driven crop failures. Manufacturing draws from United States, Canada, and Germany for certified organic protein inputs, with Australian lamb and New Zealand venison supplementing North American beef and poultry. Supply chain risk centers on single-source vulnerability in USDA-accredited certifier backlogs that delay new product launches. Distribution runs through direct-to-consumer platforms and specialty retail chains, with veterinary clinic networks capturing therapeutic-tier volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where subscription-based replenishment models and blockchain-verified sourcing platforms interoperate to displace conventional retail purchasing. Direct-to-consumer algorithmic portion sizing creates ecosystem lock-in that reshapes competitive dynamics across certification tiers.
For Market Incumbents: Consolidate supplier relationships through backward integration into organic protein sourcing to defend against artisanal freeze-dried specialists capturing shelf-space premiums. Lock in veterinary clinic distribution networks before prescription-adjacent therapeutic formats commoditize. Priority lever: captive supply chain control over Midwest grain origination and Pacific Northwest cold-chain infrastructure.
For New Entrants and Emerging Players: Anchor in fresh-format subscription corridors where cold-chain last-mile logistics density in United States coastal metros remains underpenetrated by scaled operators. White-space targets include state-level packaging waste legislation compliance in California and New York, plus veterinary prescription integration for condition-managed canine populations. Go-to-market angle: high-pressure processing systems that match multinational safety profiles without lyophilization capital intensity.
For Investors and Strategic Acquirers: Blockchain-verified sourcing platforms with established retail partnerships represent the most defensible acquisition target archetype for long-term viability across a 5-10 year window. These assets command pricing power through transparency premiums that sustain margin structures amid input cost volatility. Signal to watch: USDA certifier backlog resolution timelines as inflection indicator for new product launch velocity and formulation innovation cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Protein Sourcing | Captive supply of certified chicken and beef reduces exposure to competing human food demand volatility. |
| Direct-to-Consumer Platform Launch | Algorithmic portion sizing captures recurring revenue from millennial pet owners in coastal United States metros. |
| Blockchain-Verified Sourcing Implementation | Distributed ledger transparency commands retail price premiums in specialty channels and sustainability-motivated buyer segments. |
| Veterinary Prescription Integration | Therapeutic organic formulations distributed through clinic networks lock in recurring purchase patterns for condition-managed dogs. |
| High-Pressure Processing Adoption | Pathogen reduction without thermal degradation enables smaller players to match multinational freeze-dried safety profiles. |
Research Methodology
Cross-validation between regulatory filing analysis and trade data anchors the qualitative findings on organic certification compliance burdens and import pathway economics. Primary interviews with brand managers at multinational feed manufacturers, category buyers at specialty retail chains, supply planners at cold-chain logistics providers, and regulatory affairs leads at USDA-accredited certifiers combined with secondary validation from FDA Center for Veterinary Medicine adverse event databases, USDA National Organic Program certification records, EU Regulation 2018/848 equivalence determinations, and customs import documentation. Bottom-up and top-down triangulation reconciles subscription-platform revenue disclosures with retail audit data.
Sensitivity analysis across protein input cost scenarios, certifier backlog durations, and cold-chain infrastructure buildout rates stress-tests the analytical framework. Segmentation dimensions modeled include product format, ingredient type, distribution channel, and customer archetype across the projection horizon. CAGRs derive from curve-fitting historical subscription growth patterns against veterinary service utilization rates and metropolitan pet ownership density metrics. Forecast inputs incorporate USDA organic acreage expansion trajectories and EU residue testing protocol evolution.
Material uncertainties — organic protein input cost volatility, weather-driven Midwest grain yield fluctuations, and FDA adverse event reporting scope expansion — sit outside the modeled envelope. Forecasts reflect assumptions on certification timeline compression and cold-chain last-mile density maturation. Practitioners should keep alternative scenarios live as state-level packaging waste legislation and veterinary prescription integration requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Parrot Cage Market
Pet Care Products
Cat Shampoo Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
GCC Dog Food Market
Pet Care Products
Asia-Pacific Pet Clothing Market
Pet Care Products
United States Pet Market
Pet Care Products
Pet Pee Pads Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Global Pet Supplies Market
Pet Care Products
Fresh and Frozen Dog Food Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Pet Furniture Market
Pet Care Products
Poland Pet Food Market
Pet Care Products
Outdoor Dog Bed Market