
 Pet GPS Tracker Market | 2026-2036
Pet GPS Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Pet GPS Tracker Market Analytics
Aftermarket subscription revenue is rewriting profit architecture across the pet GPS tracker industry. Tractive leverages recurring geofencing and wellness data fees to sustain above-hardware margins. Garmin anchors its position through ruggedized device engineering and multi-species tracking firmware. Jiobit competes on compact form factors designed for smaller breeds and cats, occupying a niche that larger collar formats cannot address.
Pet GPS trackers combine satellite positioning receivers, cellular or Bluetooth transceivers, and lithium-polymer power cells into wearable form factors that transmit real-time location and activity data to companion mobile applications. Manufacturing prioritizes IP67 or higher ingress protection ratings to withstand submersion and dust exposure during outdoor animal use. Wearable collars dominate unit volume due to standardized neck-strap compatibility across dog breeds, while smart harnesses command premium positioning through distributed sensor arrays that reduce neck-concentrated device weight. Cellular technology segments carry higher average revenue per user because of persistent wide-area connectivity, though Bluetooth variants penetrate cost-sensitive multi-pet households through smartphone-tethered operation.
FCC equipment authorization governs radio frequency emissions for all cellular and GPS transmitting devices sold in the United States, creating compliance cost barriers for new entrants. CE marking under EU radio equipment directives shapes product design for European market access, particularly around battery safety and electromagnetic compatibility testing. ISO standards for animal identification and electronic data exchange provide interoperability frameworks that veterinary software platforms increasingly require. Stakeholders must weigh subscription attach rates against upfront hardware subsidies when evaluating market entry economics.
Market Dynamics
Subscription attach rates are restructuring profit pools across the pet GPS tracker industry, forcing hardware vendors to build recurring revenue infrastructure or accept compressed margins on device-only sales.
Growth Catalysts
- CE marking under EU radio equipment directives:Harmonized electromagnetic compatibility standards reduce per-country certification costs for manufacturers targeting European veterinary software platforms.
- Multi-pet household density in Brazil:Working pet owners in São Paulo and Rio de Janeiro drive demand for smartphone-tethered Bluetooth trackers as affordable monitoring solutions for free-roaming dogs.
- Lithium-polymer cell energy density improvements:Extended battery life between charges reduces owner friction and improves real-time tracking reliability for outdoor animal use.
Market Restraints
- FCC equipment authorization compliance costs:RF emissions testing for cellular and GPS-enabled wearables creates capital barriers for new entrants targeting the United States.
- Concentrated cellular module supply:Dependency on narrow-band IoT chipset vendors exposes manufacturers to allocation constraints and price volatility.
- Bluetooth range limitations:Smartphone-tethered operation fails in rural or large-property settings where cellular alternatives command premium positioning.
Strategic Opportunities
- ISO standards for animal identification:Interoperability frameworks with veterinary software platforms open integration partnerships for data exchange compliance.
- Smart harness form factors:Distributed sensor arrays reduce neck-concentrated device weight, capturing premium positioning among large-breed owners.
- Pet care services procurement:Kennel and daycare monitoring contracts create institutional volume channels beyond direct-to-consumer retail.
Industry Challenges
- IP67 ingress protection certification timelines:Submersion and dust exposure testing extends product development cycles before outdoor-use claims can be marketed.
- Firmware integration complexity:Multi-species tracking algorithms require species-specific behavioral calibration that strains engineering bandwidth.
- Subscription churn management:Geofencing and wellness data services face cancellation pressure when owners perceive insufficient value relative to monthly fees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet GPS Tracker Market |
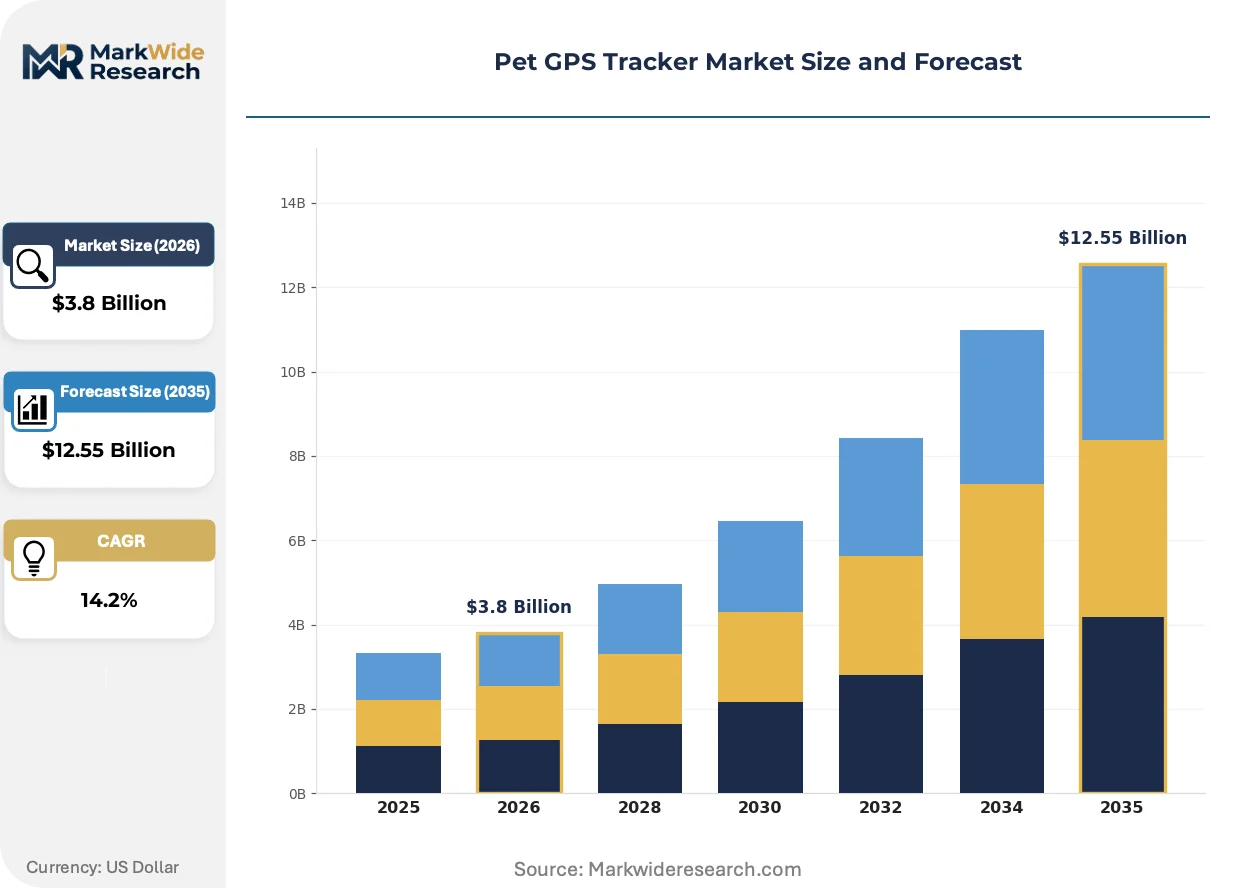
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Collars, Tags, Smart Harnesses, GPS Modules Technology: Bluetooth, Cellular, Radio Frequency, Wi-Fi End User: Pet Owners, Veterinarians, Pet Care Services, Animal Shelters Distribution Channel: Online Retail, Pet Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Fi, LandAirSea, Whistle, SpotOn, Jiobit, Tractive, Garmin, Amcrest, Halo Collar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet GPS Tracker Market Evolving Landscape
Real-time location accuracy and owner peace-of-mind are converging through hardware-software integration that transforms passive tracking into predictive pet safety systems.
Multi-constellation GNSS receivers combining GPS, GLONASS, and Galileo satellite signals are rendering obsolete single-system positioning modules that struggle under tree canopy and urban canyon conditions. Premium collar manufacturers in Germany and the United States have adopted triple-band architectures since 2023. The shift compresses competitive differentiation around raw coordinate precision and shifts value toward predictive geofencing algorithms.
EU radio equipment directives under CE marking frameworks are tightening electromagnetic compatibility testing requirements for battery-powered wearables. Manufacturers must now document specific absorption rate compliance for cellular transceivers operating near animal tissue. Small-form-factor specialists targeting cats and toy breeds face disproportionate redesign costs as antenna miniaturization conflicts with emission limits.
Veterinary clinics are bundling GPS tracker prescriptions with wellness service contracts, displacing pure retail channel dependence. Pet owners in France and Canada receive device subsidies tied to annual vaccination and telehealth packages. This procurement model concentrates buyer power among clinic chains and demands API interoperability with practice management software.
Pet GPS Tracker Market Segmentation
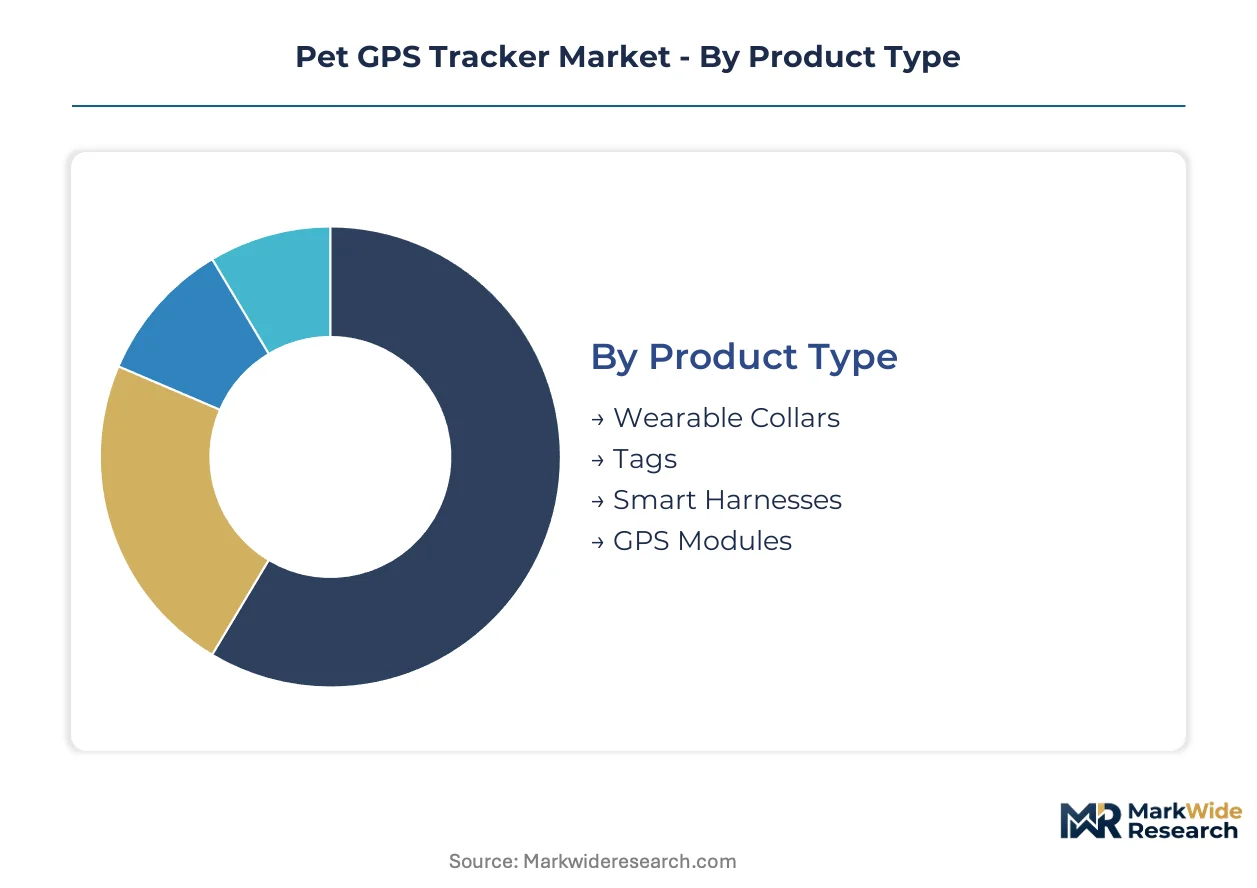
Pet GPS tracker segmentation reveals how hardware form factors, connectivity protocols, and procurement channels create distinct profit pools. Manufacturers must align R&D investment with the specific friction points each segment addresses for end-users.
Product Type:
The use-case spectrum spans casual neighborhood walks to professional working dog operations, with form factor choices directly determining sensor capacity and battery endurance trade-offs.
- Wearable Collars:Standardized neck-strap compatibility across dog breeds drives volume concentration. Demand clusters among suburban pet owners in the United States and Germany seeking all-day comfort without specialized fitting.
- Smart Harnesses:Distributed sensor arrays reduce neck-concentrated device weight for large breeds. Premium positioning captures working dog handlers and search-and-rescue operators requiring load-bearing stability during extended deployments.
- Tags:Compact clip-on formats attach to existing collars for cats and toy breeds. Brazilian working pet owners favor these for free-roaming dogs where minimal weight preserves natural movement.
- GPS Modules:Modular components integrate into custom enclosures for exotic species and livestock applications. Niche demand from wildlife researchers and conservation programs in Australia and South Africa.
The dominant share belongs to wearable collars, while smart harnesses are closing the gap fastest among professional and working dog segments.
Technology:
Cost tier stratification separates subscription-dependent cellular services from smartphone-tethered alternatives that sacrifice range for affordability.
- Cellular:Persistent wide-area connectivity via narrow-band IoT chipsets enables real-time tracking beyond Bluetooth range. Higher average revenue per user attracts manufacturers building recurring revenue infrastructure around geofencing subscriptions.
- Bluetooth:Smartphone-tethered operation penetrates cost-sensitive multi-pet households. FCC equipment authorization requirements are lighter than cellular, accelerating time-to-market for new entrants targeting price-conscious segments.
- Radio Frequency:Proprietary protocols operate without cellular infrastructure in remote areas. Hunting dog trainers in rural Canada and Scandinavia favor these for terrain where cellular coverage fails.
- Wi-Fi:Home-based geofencing with minimal power draw suits indoor-outdoor cats. Limited range constrains adoption to urban apartment dwellers seeking perimeter alerts rather than full GPS tracking.
Cellular technology commands premium positioning through subscription attach rates, with Bluetooth expanding most quickly in emerging market price tiers.
End User:
Volume concentration sits with individual consumers, yet institutional procurement channels are restructuring competitive dynamics through bulk contracts and software integration requirements.
- Pet Owners:Direct-to-consumer retail remains the volume anchor. CE marking compliance and IP67 certification claims influence purchase decisions among safety-conscious buyers in France and the United Kingdom.
- Pet Care Services:Kennel and daycare monitoring contracts create institutional volume beyond retail. ISO standards for animal identification and electronic data exchange open integration partnerships with practice management platforms.
- Veterinarians:Clinic chains bundle GPS tracker prescriptions with wellness service contracts. Buyer power concentrates among veterinary networks in Canada demanding API interoperability.
- Animal Shelters:Budget-constrained operations prioritize low-cost Bluetooth variants for intake tracking. Municipal contracts in São Paulo and Mexico City drive regional procurement patterns.
Pet owners retain the dominant share, while pet care services are gaining share fastest as institutional procurement channels mature.
Distribution Channel:
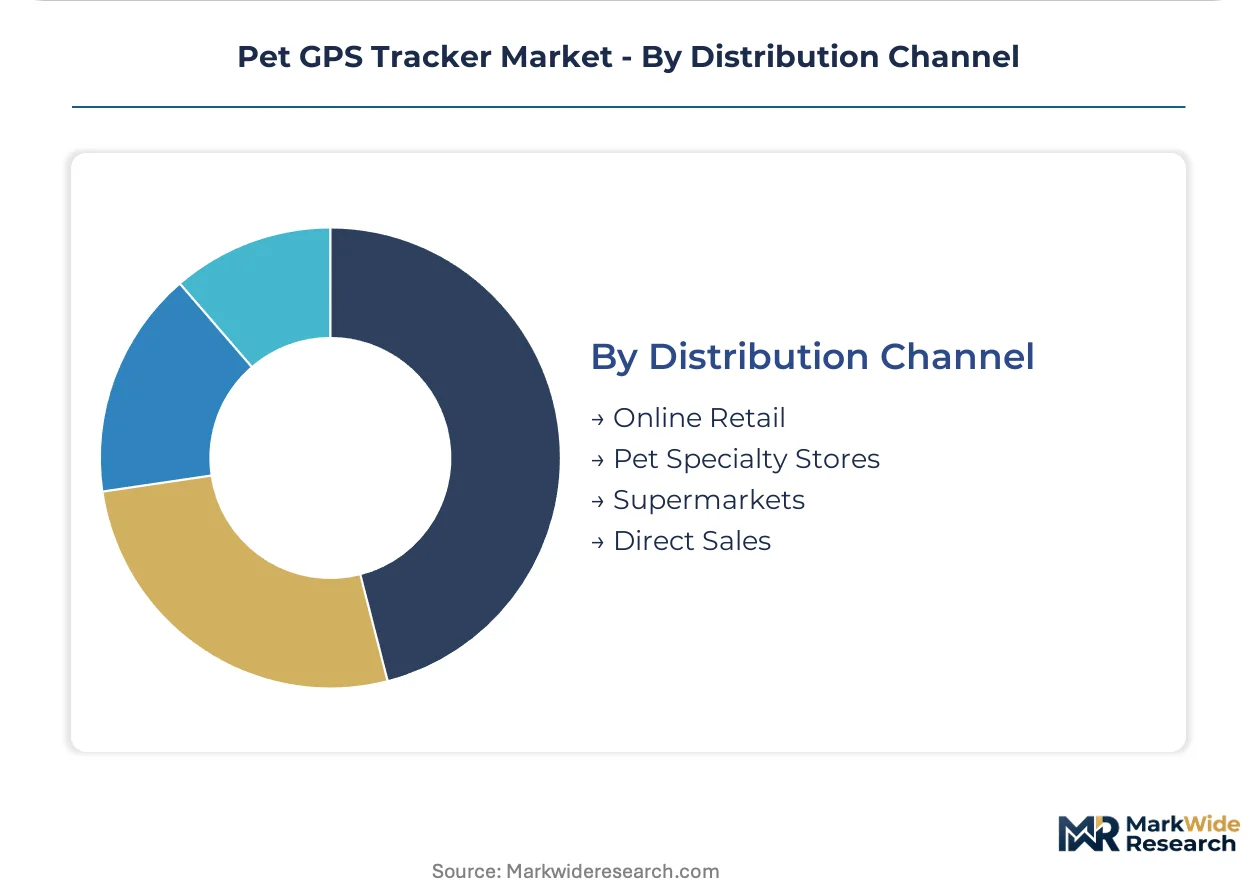
Geography and customer sophistication determine whether education-heavy specialty retail or convenience-oriented online platforms capture the transaction.
- Online Retail:E-commerce platforms dominate in markets with established logistics infrastructure. Subscription attach rates run higher through direct-to-consumer channels that control onboarding flows.
- Pet Specialty Stores:Staff expertise drives conversion for first-time buyers needing fitting guidance. Premium positioning in Germany and Japan relies on in-person demonstration of multi-constellation GNSS accuracy claims.
- Supermarkets:Mass retail placement captures impulse purchases and gift buying. Limited SKU depth restricts assortment to entry-level Bluetooth tags with minimal margin contribution.
- Direct Sales:Manufacturer-owned channels serve enterprise accounts and veterinary clinic chains. Firmware customization and API access negotiations require relationship-based selling absent in retail.
Online retail holds the dominant share, with pet specialty stores climbing fastest as premium positioning and technical differentiation demand consultative selling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Brazilian working pet owners gravitate toward smartphone-tethered Bluetooth solutions, while German buyers absorb premium cellular subscriptions without volume hesitation.
United States
FCC equipment authorization mandates RF emissions testing for all cellular and GPS-enabled wearables, elevating compliance costs for new entrants. Pet ownership concentrates in suburban corridors outside Atlanta, Dallas, and Phoenix where large properties necessitate wide-area tracking. Kennel and daycare operators in Florida and Texas are procuring institutional monitoring contracts at accelerating rates.
Germany
CE marking under EU radio equipment directives governs electromagnetic compatibility and specific absorption rate compliance for battery-powered wearables. Premium collar manufacturers in Bavaria and Baden-Württemberg adopted triple-band GNSS architectures during 2023. Munich-based engineering firms supply multi-constellation receiver modules to European device assemblers.
Brazil
Working pet owners in São Paulo and Rio de Janeiro drive demand for affordable smartphone-tethered Bluetooth trackers. ANVISA regulates battery safety for consumer electronics without imposing cellular-specific RF testing burdens. Free-roaming dog culture in southeastern metropolitan zones favors minimal-weight clip-on formats over collar-integrated hardware.
France
Veterinary clinic chains in Île-de-France bundle GPS tracker prescriptions with annual vaccination and telehealth service contracts. CNIL guidelines shape data handling practices for location-tracking applications serving pet owners. Lyon and Marseille host distribution hubs supplying specialty retail channels across southern Europe.
Canada
Health Canada and PMRA govern device safety for animal-tracking electronics entering the Canadian market. Hunting dog trainers in rural Ontario and Quebec favor radio-frequency protocols where cellular infrastructure fails. Toronto and Vancouver veterinary networks are consolidating buyer power through API interoperability demands.
Pet GPS Tracker Market Competitive Landscape
Capability concentration sits with specialized firmware developers; scale advantage sits with diversified electronics manufacturers. The vendor base organizes into three tiers: subscription-native platforms, ruggedized hardware specialists, and compact-form-factor innovators. Consolidation pressure runs highest among hardware-only vendors lacking recurring revenue infrastructure. Dominant competitive moves include strategic partnerships with veterinary software platforms and backward integration into cellular module sourcing.
Within the subscription-native tier, Tractive and Fi exemplify recurring-revenue architectures built around geofencing and wellness data services. Garmin anchors the ruggedized hardware segment through multi-species tracking firmware and load-bearing engineering heritage. Jiobit occupies a position among compact-form-factor specialists targeting weight-constrained applications for cats and toy breeds.
| Leading Market Players |
|---|
| Fi |
| LandAirSea |
| Whistle |
| SpotOn |
| Jiobit |
| Tractive |
| Garmin |
| Amcrest |
| Halo Collar |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Los Angeles freight corridors absorb volatile container rates that compress hardware margins for cellular-enabled trackers while amplifying price spreads between subscription-native vendors and hardware-only assemblers. FCC equipment authorization testing costs in the United States create fixed cost barriers that favor larger manufacturers with volume leverage over emerging entrants.
Pricing Analysis
Aftermarket subscription revenue drives lifetime value across the pet GPS tracker industry. Pricing stratifies across premium cellular tiers with geofencing bundles, standard Bluetooth-tethered units, and economy clip-on tags for multi-pet households. Price differentiation rests on IP67 certification grade and narrow-band IoT chipset integration. Cost compression in the Bluetooth tier intensifies because Brazilian working pet owners prioritize affordability over wide-area connectivity. Animal shelters exhibit highest price sensitivity; veterinary clinic chains absorb premium cellular subscriptions without volume hesitation.
Supply Chain Analysis
Lithium-polymer cell feedstock draws from South Korean and Chinese chemical processors, while narrow-band IoT chipsets concentrate in Taiwanese semiconductor fabs. Munich-based engineering firms supply multi-constellation GNSS receiver modules to European device assemblers. Single-source vulnerability runs through concentrated cellular module vendors exposed to allocation constraints. Distribution runs through direct-to-consumer online platforms and pet specialty retail channels with consultative fitting support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pet GPS tracker market expansion qualifies as high-growth disruption justified by triple-band GNSS architecture adoption since 2023 that renders obsolete single-system positioning modules. Veterinary software platform integration is restructuring procurement channels beyond pure retail dependence.
For Market Incumbents: Entrench recurring revenue infrastructure through API interoperability investments with practice management platforms. Secure backward integration into cellular module sourcing to mitigate allocation risk from narrow-band IoT chipset vendors. Defensive patent positioning around multi-species behavioral calibration algorithms protects against firmware specialists.
For New Entrants and Emerging Players: Build out white-space presence in smart harness form factors for large-breed and working dog applications where load-bearing stability commands premium positioning. Target municipal animal shelter contracts in São Paulo and Mexico City with low-cost Bluetooth variants. Go-to-market through pet care services procurement channels bypasses saturated direct-to-consumer retail.
For Investors and Strategic Acquirers: Compact-form-factor specialists with veterinary software platform integration capabilities represent the priority acquisition archetype for this market. Long-term viability concentrates on subscription attach rate sustainability and firmware differentiation rather than hardware scale. Monitor ISO standards adoption timelines as inflection indicators for data exchange compliance mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Investment | Veterinary clinic chains in Canada and France demand practice management software integration. |
| Cellular Module Backward Integration | Mitigates allocation constraints from narrow-band IoT chipset vendors in Taiwan. |
| Smart Harness Form Factor Launch | Captures premium positioning among search-and-rescue operators requiring load-bearing stability. |
| CE Marking Acceleration | EU radio equipment directive compliance opens harmonized access across European veterinary platforms. |
| Pet Care Services Procurement Partnership | Kennel and daycare monitoring contracts in Florida and Texas create institutional volume channels. |
Research Methodology
The analysis maps cellular connectivity tiers, Bluetooth-tethered segments, and smart harness form factors, each validated through firmware engineering directors, veterinary clinic procurement managers, pet specialty retail buyers, and narrow-band IoT chipset suppliers. Primary interviews combined with secondary validation from FCC equipment authorization filings, CE marking documentation, ISO standards registries, and customs trade data for lithium-polymer cell imports. Bottom-up unit shipment estimates triangulated against top-down subscription revenue pools.
Assumptions held fixed include narrow-band IoT network coverage expansion trajectories and IP67 certification adoption rates, while cellular module pricing and veterinary software platform consolidation timelines were varied across sensitivity scenarios. Segmentation dimensions modeled encompass connectivity protocol, hardware form factor, procurement channel, and end-user archetype. CAGRs derived from logistic adoption curves fitted to cellular subscription attach rate histories and Bluetooth penetration patterns in emerging markets. Forecast inputs incorporated lithium-polymer energy density improvement curves and multi-constellation GNSS receiver cost decline trajectories.
Sensitivities concentrate around FCC equipment authorization timeline delays, narrow-band IoT chipset allocation disruptions, and veterinary clinic chain consolidation patterns that could accelerate or compress institutional procurement adoption. Forecasts reflect documented assumptions without guarantee of realization. Cross-checking against cellular carrier IoT connection disclosure trends and veterinary software platform API partnership announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Toy Dog Market
Pet Care Products
Argentina Pet Food Market
Pet Care Products
Pet Apparel Market
Pet Care Products
China Pet Training Services Market
Pet Care Products
Dog Treats Market
Pet Care Products
Pet Waste Removal Services Market
Pet Care Products
Pet Relaxants Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
UAE Cat Food Market
Pet Care Products
Dog Vitamins Market
Pet Care Products
Japan Organic and Natural Pet Food Market
Pet Care Products
Smart Dog Collar Market
Pet Care Products
Pet Pens Market
Pet Care Products
Bird Cages and Accessories Market
Pet Care Products
Pet Meal Kit Delivery Services Market