
 PET Market | 2026-2036
PET Market Size, Share, and Industry Trends Forecast 2026-2036
PET Market Intelligence
The push for high-purity food-grade recycled PET (rPET) is collapsing the traditional price and quality gap between virgin and secondary materials. This shift creates new competitive dynamics for resin producers. Indorama Ventures leverages its extensive global manufacturing footprint to offer a wide portfolio of both virgin and recycled grades to multinational brands. DAK Americas, a subsidiary of Alpek, focuses its operations on serving the North and South American packaging markets with specialized resin formulations.
Polyethylene terephthalate (PET) is a thermoplastic polymer resin of the polyester family, produced through the polymerization of ethylene glycol and terephthalic acid. Its primary industrial value comes from its excellent clarity, strength, light weight, and gas barrier properties. Beverage containers continue to constitute the largest application segment, commanding significant volume. However, the PET films segment is expanding rapidly, driven by its use in flexible food packaging and protective layers for electronics.
Regulatory frameworks are a primary influence on material specifications and market access. In the United States, the FDA oversees food contact substance notifications for PET and rPET. The European Food Safety Authority (EFSA) provides scientific opinions that form the basis for EU-wide authorization of recycling processes. In China, GB standards dictate the quality and safety requirements for all food-related packaging materials. Producer success increasingly depends on navigating these divergent regional standards for recycled content and material safety.
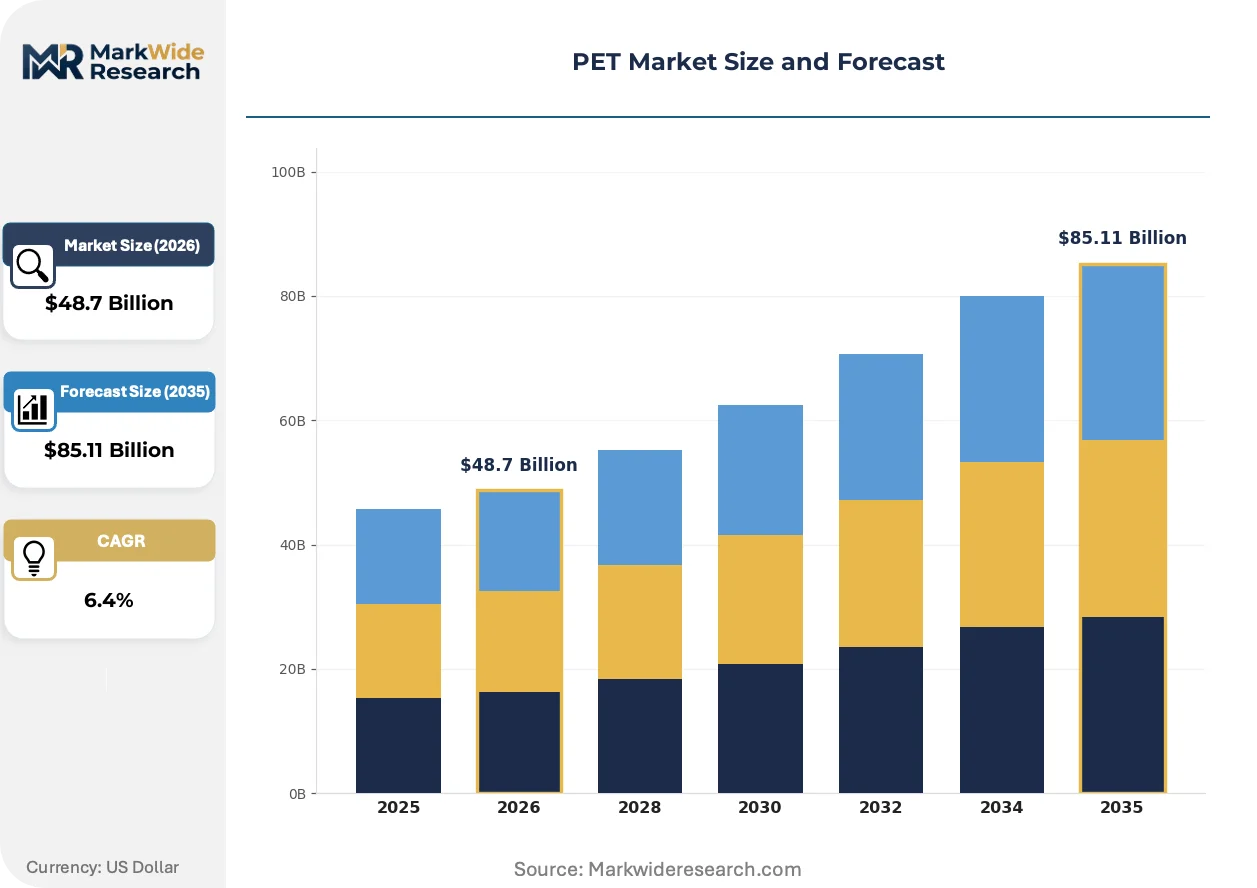
Market Dynamics
The push for circularity, enforced by recycled content mandates, is the central force shaping PET supply. Advanced chemical recycling enables food-grade rPET that competes directly with virgin material, collapsing traditional quality and price distinctions for resin producers.
Growth Catalysts
- Recycled Content Mandates:The European Union's Single-Use Plastics Directive, requiring specific percentages of recycled content in beverage bottles, creates guaranteed demand for rPET and stimulates investment in collection.
- Chemical Recycling Advancement:Innovations in glycolysis and methanolysis are producing high-purity rPET, enabling its use in demanding food-contact applications previously reserved for virgin resin.
- Film Segment Expansion:Demand from the flexible food packaging industry for PET films with high barrier properties is accelerating, providing a fast-growing alternative to the mature beverage container market.
Market Restraints
- Feedstock Volatility:The price and availability of purified terephthalic acid (PTA) and monoethylene glycol (MEG) are subject to fluctuations in crude oil markets, impacting production costs.
- Collection Infrastructure Gaps:In many countries, particularly in Southeast Asia and parts of the Americas, inadequate post-consumer collection systems create a bottleneck for rPET feedstock supply.
- Material Substitution Threat:Aluminum cans and glass bottles are gaining share in the premium beverage segment, presenting a direct substitution threat to PET bottles based on consumer perception and sustainability marketing.
Strategic Opportunities
- Bio-PET Commercialization:Developing partially or fully bio-based PET from renewable feedstocks like sugarcane ethanol offers a pathway to decarbonize production and appeal to brands with net-zero targets.
- Fiber Market Circularity:Expanding the use of bottle-grade rPET flakes for high-quality polyester staple fiber production addresses the sustainability demands of the global apparel and home textiles industries.
- Indian Market Penetration:India's expanding middle class and formalizing retail sector create significant white space for PET packaging in food, beverage, and personal care segments where penetration is still low.
Industry Challenges
- Regulatory Divergence:Producers face significant compliance costs and logistical complexity in navigating disparate food-contact safety standards for rPET between the US (FDA), Europe (EFSA), and China (GB standards).
- Sorting Technology Investment:Achieving the purity required for food-grade rPET necessitates high capital expenditure in advanced near-infrared (NIR) and robotic sorting systems at materials recovery facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate Resin, PET Bottles, PET Films, PET Sheets, PET Fibers Application: Beverage Containers, Food Packaging, Textile Fibers, Automotive Components, Electronics Packaging End User: Processors, Textile Manufacturers, Packaging Companies, Consumer Goods Producers, Electronics Assemblers Packaging Type: Blow Molding, Injection Molding, Sheet Molding, Film Lamination, Extrusion Coating |
| Companies Covered | Mars Petcare, Nestlé Purina PetCare, Hill's Pet Nutrition, Blue Buffalo, General Mills, The J.M. Smucker Company, Freshpet, Diamond Pet Foods, Affinity Petcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Market Strategic Shifts & Innovations
Industrialization of PET recycling is defining the market's next phase. Innovations are focused on upgrading post-consumer material into a direct substitute for virgin resin, altering supply chain economics and creating new value streams from waste.
Advanced depolymerization processes break down post-consumer PET waste into its base monomers, terephthalic acid and ethylene glycol. Major beverage and consumer packaged goods companies are driving adoption to meet recycled content goals. This technology is miniaturizing the performance gap between virgin and recycled polymers, rendering them chemically indistinguishable for food-contact use.
The United Kingdom's Plastic Packaging Tax imposes a direct financial levy on packaging that contains less than a specified threshold of recycled material. This policy creates a powerful economic incentive for resin converters and brand owners to reformulate products. The beverage and fast-moving consumer goods sectors are most affected, accelerating their procurement of high-quality rPET to mitigate tax liabilities.
Brand-owner specifications are evolving from a pure cost-per-ton basis to a value-based model that incorporates sustainability certifications. This disrupts the traditional commodity resin sales model, favoring suppliers who can provide traceability and certified recycled content. This shift is most prominent among multinational food and beverage companies in Europe and North America with public ESG commitments.
PET Market Segmentation
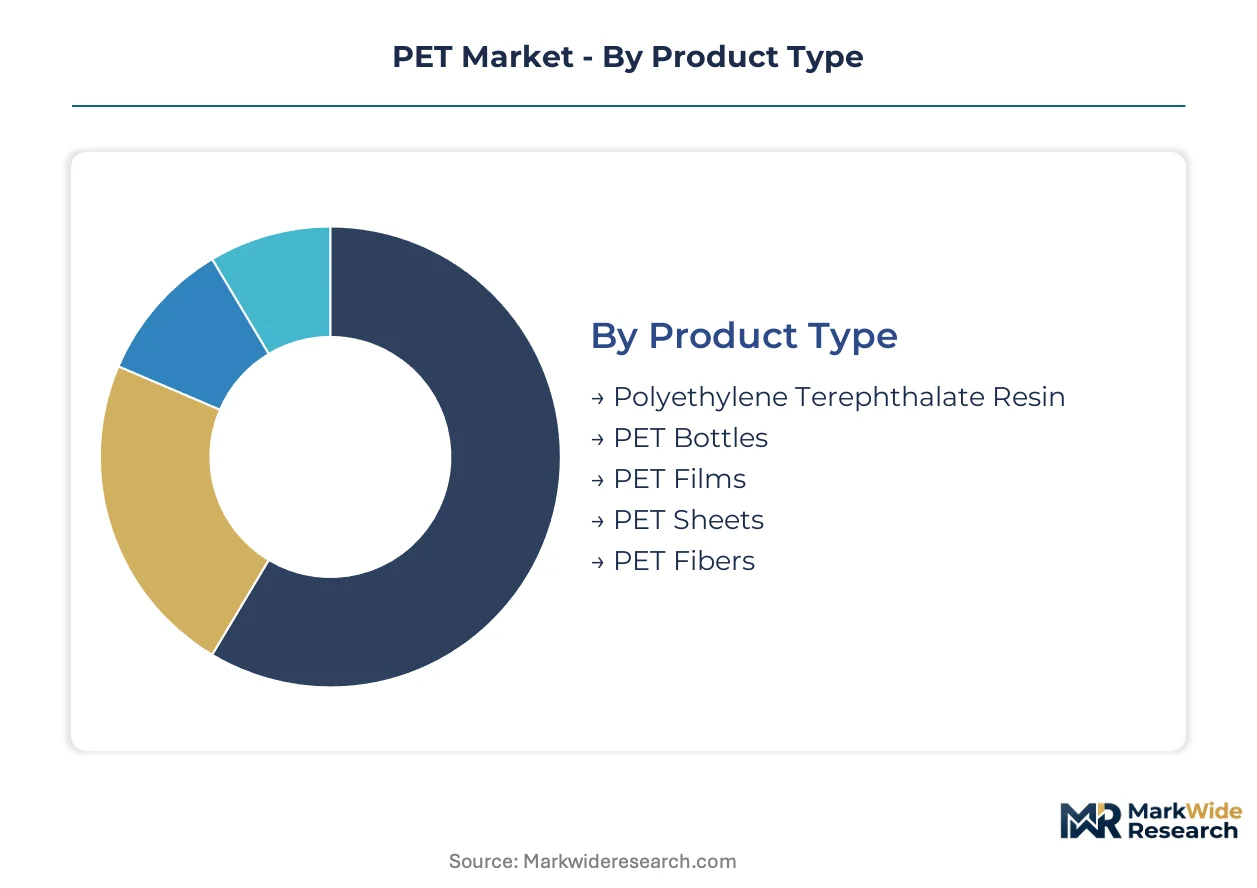
The PET market exhibits diverse segmentation, reflecting varied end-use requirements and processing technologies. Understanding these distinctions is critical for stakeholders to navigate material specifications, regulatory compliance, and demand drivers across different product forms and applications.
Product Type:
Regulatory bodies like the FDA and EFSA significantly influence product type specifications, particularly for food-contact applications.
- Polyethylene Terephthalate Resin:This is the base polymer material, produced from ethylene glycol and terephthalic acid. Demand for virgin resin remains high in regions like China due to large-scale polyester fiber production and packaging consumption.
- PET Bottles:These are molded containers known for clarity, strength, and gas barrier properties, primarily used for beverages. Regulatory mandates for recycled content in the EU's Single-Use Plastics Directive directly stimulate demand for rPET bottle production.
- PET Films:Thin, flexible sheets of PET offer high barrier properties, finding increasing use in flexible food packaging and protective layers for electronics.
- PET Sheets:Rigid PET sheets are utilized in thermoforming applications for blister packaging and clear display boxes, valued for their transparency and impact resistance.
- PET Fibers:Polyester staple fibers derived from PET are a major component in textiles, with growing interest in circularity solutions for apparel and home furnishings.
Established volume favors PET Bottles; emerging adoption favors PET Films.
Application:
Volume concentration drives application segment dynamics, particularly in high-consumption sectors.
- Beverage Containers:This segment represents the largest application for PET, leveraging its clarity, light weight, and barrier properties for water, soft drinks, and juices. Recycled content mandates in the EU directly shape material procurement for beverage brands.
- Food Packaging:PET films and trays are increasingly used for flexible and rigid food packaging due to their barrier performance and safety for direct food contact. China's expanding retail sector fuels demand for packaged food solutions.
- Textile Fibers:PET is depolymerized and re-polymerized into polyester fibers for clothing and home textiles, addressing sustainability demands in the global apparel industry.
- Automotive Components:PET finds niche applications in automotive interiors and under-the-hood components, valued for its strength-to-weight ratio and chemical resistance.
- Electronics Packaging:PET films provide protective layers and packaging solutions for electronic devices, leveraging their transparency and electrical insulation properties.
Beverage Containers maintain the largest market share, while Food Packaging is expanding most quickly.
End User:
Customer type dictates material specifications and procurement strategies across the PET value chain.
- Processors:These entities convert raw PET resin into intermediate forms like preforms, films, or sheets, supplying them to downstream manufacturers. Their operations are heavily influenced by feedstock volatility in PTA and MEG markets.
- Textile Manufacturers:These companies utilize PET fibers to produce fabrics and garments, increasingly seeking recycled content to meet brand sustainability goals.
- Packaging Companies:These firms directly convert PET preforms into bottles or films into flexible packaging, serving brand owners across food and beverage sectors. They face compliance costs navigating disparate food-contact safety standards globally.
- Consumer Goods Producers:Brands in beverages, food, and personal care drive demand for specific PET grades, increasingly prioritizing certified recycled content over pure cost.
- Electronics Assemblers:These end-users incorporate PET films and components into electronic devices, valuing the material's protective and insulating properties.
Packaging Companies form the direct demand base, with Consumer Goods Producers dictating sustainability requirements.
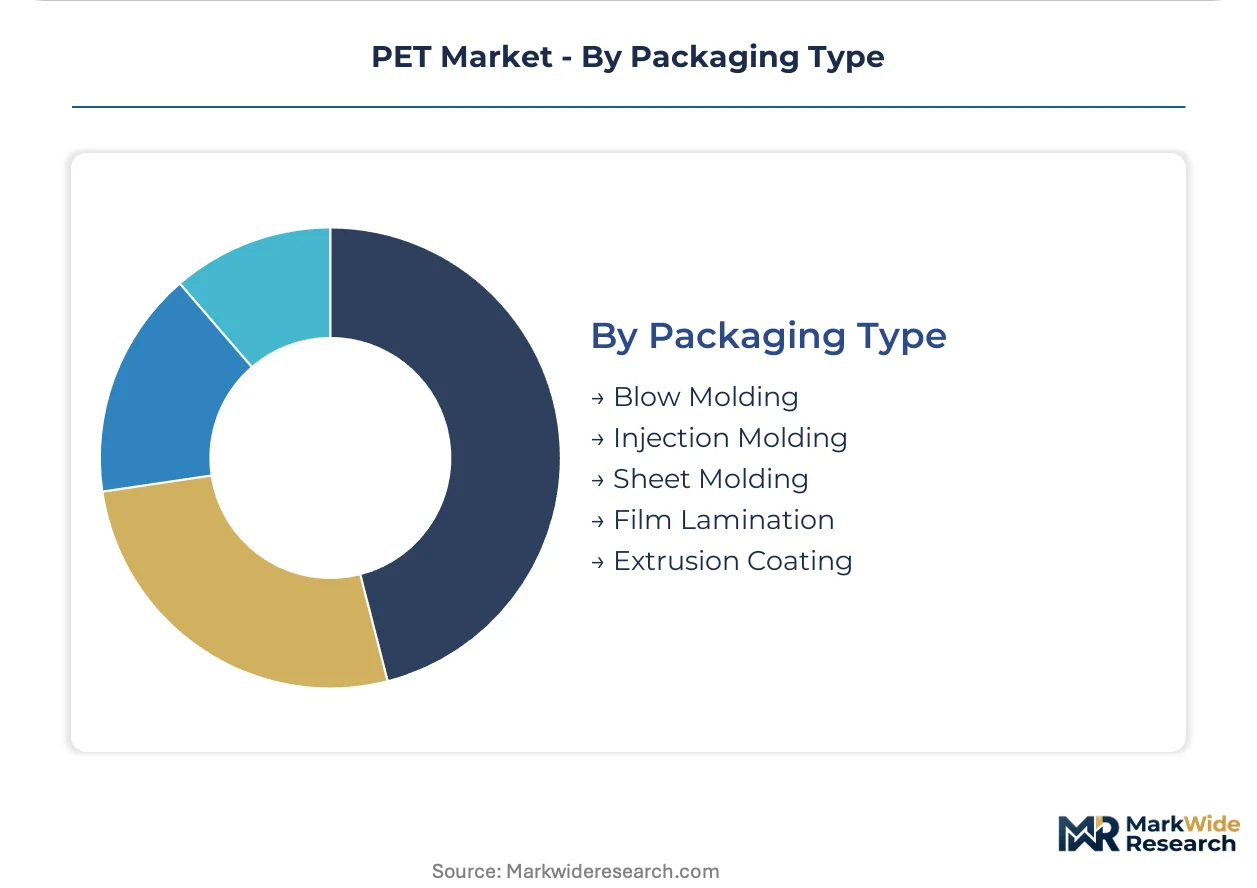
Packaging Type:
Application method defines the physical form and functional properties of the final PET product.
- Blow Molding:This process shapes PET preforms into bottles and containers by inflating them within a mold, yielding lightweight, high-strength packaging. This method is central to the beverage container segment, driven by large-scale production requirements.
- Injection Molding:This technique forms PET resin into precise shapes like bottle preforms, caps, or small rigid components, offering high dimensional accuracy. It provides the initial form for many blow-molded products and is essential for intricate designs.
- Sheet Molding:PET sheets are formed through extrusion and then thermoformed into trays, blister packs, and other rigid packaging, valued for transparency and rigidity.
- Film Lamination:PET films are combined with other materials to create multi-layer flexible packaging, enhancing barrier properties for food preservation.
- Extrusion Coating:A thin layer of PET is applied onto a substrate to impart barrier properties and heat sealability, commonly used in flexible packaging structures.
Blow Molding remains crucial for high-volume beverage applications, while Injection Molding offers broader versatility for complex parts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows from Asian producers to European and North American consumer markets define PET market dynamics. Recycled content mandates and expanding industrial applications are driving distinct regional growth patterns. Regulatory frameworks significantly influence material specifications and market access.
China
Demand from large-scale polyester fiber production and packaging consumption fuels China's PET market. GB standards dictate quality and safety requirements for all food-related packaging materials. The Yangtze River Delta region drives significant PET manufacturing and consumption within the country.
United States
The United States market sees consistent demand from beverage containers and expanding food packaging applications. The FDA oversees food contact substance notifications for PET and rPET, ensuring material safety. The Gulf Coast petrochemical hub supports PET monomer production for domestic use.
Germany
Recycled content mandates in the EU's Single-Use Plastics Directive create guaranteed demand for rPET in Germany. EFSA provides scientific opinions that form the basis for EU-wide authorization of recycling processes. North Rhine-Westphalia hosts major chemical and packaging industry operations, driving innovation.
India
Expanding middle class and formalizing retail sector create significant white space for PET packaging in India. BIS standards apply to packaging materials, influencing quality and safety requirements. Western India, including Maharashtra and Gujarat, represents a significant manufacturing base for PET conversion.
Brazil
Growing consumer goods market, particularly for beverages and personal care, drives PET demand in Brazil. ANVISA regulates food contact materials, impacting PET packaging specifications and material choices. São Paulo state is a key industrial center for packaging and chemical production, serving Latin America.
PET Market Key Industry Players
Listed leaders compete with private specialists across technological innovation and production scale, shaping the PET market structure. This market exhibits a tiered competitive landscape, featuring large integrated resin producers and specialized rPET recyclers. Key archetypes include global chemical conglomerates, regional packaging solution providers, and niche film manufacturers. Companies primarily engage in strategic partnerships to secure recycled feedstock and invest in capacity expansion for advanced chemical recycling.
Within the consumer goods sector, companies like Mars Petcare and Nestlé Purina PetCare exemplify brand owners driving demand for sustainable packaging solutions. These multinational entities influence material procurement strategies by prioritizing certified recycled content and traceability in their packaging choices. Their specifications for PET packaging, particularly for food-contact applications, mandate high purity and compliance with various regional standards. Hill's Pet Nutrition further demonstrates how consumer goods producers dictate material specifications and sustainability requirements for their product lines. Their collective procurement patterns reinforce the shift towards circularity within the packaging supply chain, directly impacting resin suppliers and converters globally.
| Leading Market Players |
|---|
| Mars Petcare |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition |
| Blue Buffalo |
| General Mills |
| The J.M. Smucker Company |
| Freshpet |
| Diamond Pet Foods |
| Affinity Petcare |
| Others |
Cost & Logistics Intelligence
Global PET production economies of scale drive concentration among integrated resin producers, which in turn influences pricing floors for both virgin and recycled materials. This dynamic creates competitive pressure across the supply chain.
Pricing Analysis
The technology-generation pricing gap between virgin PET and high-purity rPET is collapsing, creating new market dynamics. Pricing operates on a commodity spot and contract-based long-term offtake model, with differentiation based on quality grade, FDA/EFSA certification, and geographic delivery costs. Pricing pressure stems from feedstock volatility and the push for virgin-rPET parity. Multinational brands exhibit lower price sensitivity for certified rPET, while smaller converters remain highly sensitive to virgin resin costs.
Supply Chain Analysis
Inbound logistics costs, particularly container availability and port congestion along key Asia-Europe trade lanes, directly impact PET supply chain efficiency. Supply concentrates in China and the US Gulf Coast, drawing from raw material dependencies like purified terephthalic acid and monoethylene glycol. Feedstock volatility, influenced by crude oil markets, represents a significant structural risk. Distribution runs through established global trade flows, connecting Asian production hubs with consumer markets in Europe and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PET market faces significant substitution defense, particularly against the rising preference for aluminum cans and glass bottles in premium beverage segments.
For Market Incumbents: Shield market share through sustained investment in advanced chemical recycling technologies. Diversify product portfolios to offer both virgin and certified rPET grades, leveraging extensive global manufacturing footprints. This strategy mitigates the threat from material substitution and addresses evolving regulatory demands for circularity. For New Entrants and Emerging Players: Differentiate on sustainability credentials and specialized applications. Target underpenetrated markets like India for PET packaging expansion, or niche segments such as high-barrier PET films for flexible food packaging. A go-to-market strategy emphasizing traceability and bio-based PET solutions can appeal to brands with net-zero targets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated rPET recyclers and innovators in bio-PET development for long-term viability. Acquisition targets should include companies with proven chemical recycling processes or strong intellectual property in renewable feedstock polymerization. The signal to watch is the successful commercial-scale deployment of new depolymerization plants by major players.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Chemical Recycling | Increases supply of high-purity rPET, meeting growing demand from brand owners and regulatory mandates. |
| Development of Bio-based PET Feedstocks | Offers a pathway to decarbonize production, aligning with net-zero targets for sustainability-focused brands. |
| Strategic Partnerships for Collection Infrastructure | Enhances the availability of post-consumer PET waste, addressing a critical bottleneck in rPET feedstock supply. |
| Geographic Market Penetration in Emerging Economies | Captures new demand for PET packaging in regions with expanding middle classes and formalizing retail sectors. |
| Investment in Advanced Sorting Technologies | Improves the quality and purity of collected PET waste, making it suitable for food-grade rPET production. |
Research Approach
A standing panel of resin producers, packaging converters, brand owners, and recycling technology providers provided ongoing calibration for market assumptions. This primary qualitative input was triangulated with extensive secondary data from regulatory bodies like the FDA and EFSA, trade association reports, and company financial filings. The approach combined bottom-up market sizing with top-down validation to ensure robust data integrity.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The forecast framework modeled segmentation dimensions including product type, application, end-user, packaging type, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and projected impacts of recycled content mandates and chemical recycling capacity deployment. Key inputs included feedstock price forecasts and regulatory compliance timelines.
The analysis sits within stated boundaries; outcomes outside significant crude oil price shocks or unforeseen regulatory changes would require recalibration. Forecasts reflect documented assumptions regarding technological advancement and market adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Japan Pet Clothing Market
Pet Care Products
Pet Grooming Market
Pet Care Products
North America Pet Food Market
Pet Care Products
United Kingdom Pet Food Market
Pet Care Products
Pet Accessories Market
Pet Care Products
US Pet Treats Market
Pet Care Products
Cannabidiol CBD Pet Market
Pet Care Products
Dog Vest Market
Pet Care Products
Disposable Absorbent Pet Pad Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
Netherlands Pet Boarding Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Pet Pens Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Pet Lodging Market