
 Baby Swaddle Wrap Market | 2026-2036
Baby Swaddle Wrap Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Swaddle Wrap Market Analysis
REACH textile chemical restrictions is expanding compliance burdens for manufacturers sourcing dyed fabrics across European supply chains. Ergobaby leverages its vertically integrated design-to-retail model to absorb these testing costs without margin erosion. Happiest Baby anchors its position through pediatrician-endorsed sleep technology that commands premium placement in hospital gift shops. Halo differentiates via flame-resistant fabric certifications that satisfy stricter nursery safety codes in North American jurisdictions.
A baby swaddle wrap is a rectangular or pouch-shaped textile garment, typically measuring 40 to 48 inches per side, constructed from woven or knit materials with adjustable closures designed to restrict infant limb movement while maintaining hip-safe flexion. The product serves the commercial purpose of reducing startle reflex disruption during sleep cycles while supporting thermoregulation in neonates. Cotton knit and bamboo fabric categories lead volume shipments due to breathability performance that commands repeat purchases from temperature-conscious parents. Sleep enhancement applications generate the fastest expansion as wearable-monitor integration creates a connected nursery ecosystem that retailers promote aggressively.
The US Consumer Product Safety Commission and the EU's REACH framework jointly govern flammability standards and chemical disclosure requirements that determine market access for imported swaddles. Oeko-Tex Standard 100 and Global Organic Textile Certification operate as de facto gatekeeping mechanisms that specialty retailers now require before purchase-order execution. Stakeholders must monitor pending ASTM updates on infant sleep product definitions that could reclassify certain swaddle designs as regulated medical devices.
Market Dynamics
Certification mandates from Oeko-Tex Standard 100 and REACH textile chemical restrictions are compressing margins for non-compliant manufacturers while rewarding vertically integrated producers who control dyeing and finishing in-house.
Growth Catalysts
- Pediatric sleep technology integration:Wearable-monitor compatibility is converting swaddles into data-collection garments that parents purchase through hospital discharge channels.
- REACH chemical disclosure expansion:European textile regulations are forcing supply chain transparency upgrades that specialty retailers now demand as a baseline for purchase orders.
- First-time parent segment:Sleep-training product prioritization among millennial and Gen Z parents is pulling premium organic cotton swaddles into mainstream retail placement.
Market Restraints
- Organic cotton input cost volatility:Climate-driven yield fluctuations in India and Turkey are destabilizing raw material pricing for certified organic producers.
- Flammability testing concentration:US Consumer Product Safety Commission compliance requires third-party laboratory access that clusters around domestic testing facilities, creating geographic bottlenecks.
- Swaddle-to-sleep-sack substitution:Transitional garments that permit leg movement are displacing traditional wrap designs as parents seek longer product lifecycles.
Strategic Opportunities
- Hospital gift shop channel:Pediatrician-endorsed placement in maternity ward retail environments captures decision-makers at peak receptivity moments.
- ASTM infant sleep product reclassification:Pending definitional updates may create regulatory moats for manufacturers prepared to meet medical device standards.
- Thermoregulation sensor convergence:Integration of moisture-wicking bamboo fabrics with temperature-monitoring hardware enables premium positioning in connected nursery ecosystems.
Industry Challenges
- Global Organic Textile Standard certification timelines:Multi-month audit cycles delay product launches and tie up working capital in inventory staging.
- Hip-safe flexion engineering talent:Pediatric biomechanics expertise required for safe swaddle design is concentrated among a small pool of infant product specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Swaddle Wrap Market |
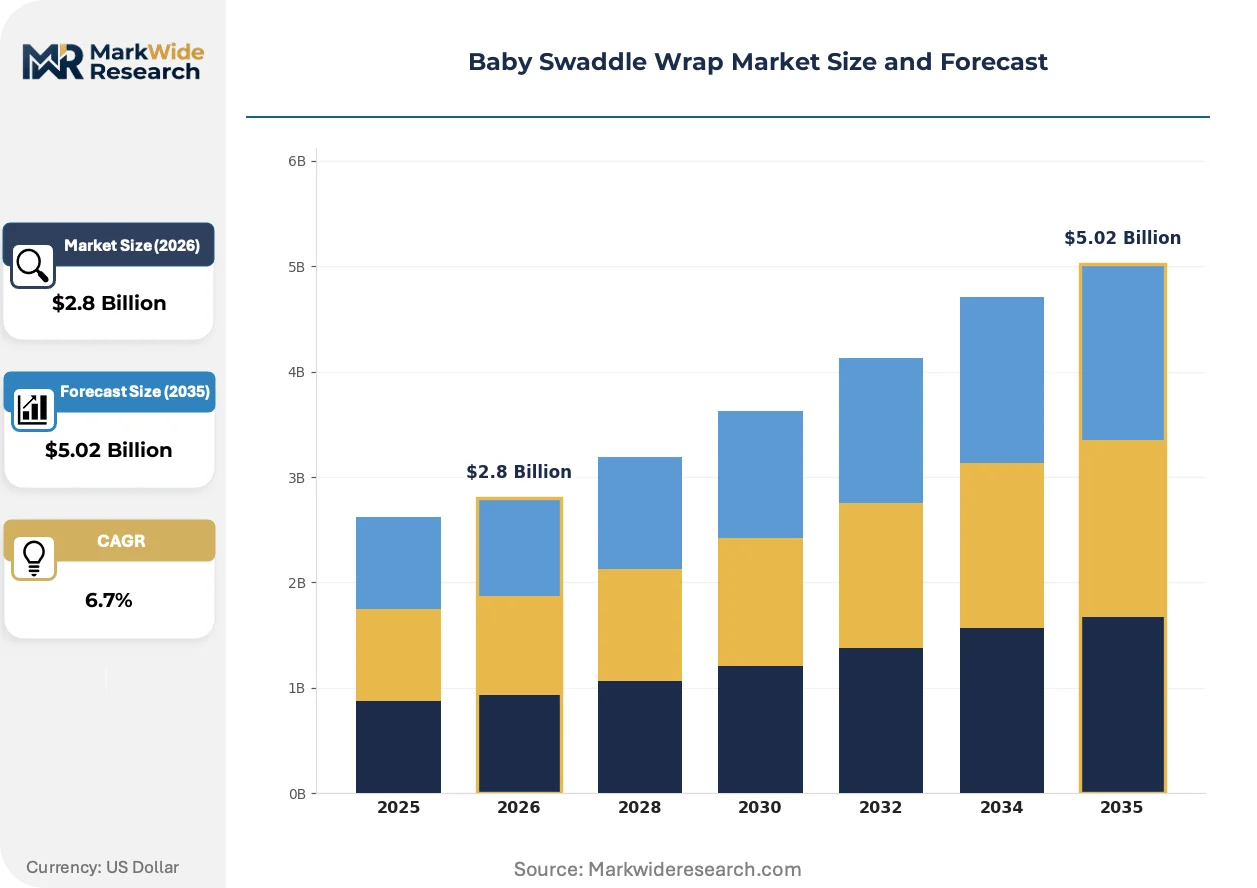
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Muslin, Cotton Knit, Fleece, Bamboo Fabric, Jersey, Velour Application: Newborn Care, Sleep Enhancement, Temperature Regulation, Comfort Aid, Soothing, Mobility Restriction End User: Parents, Neonatal Clinics, Daycare Centers, Pediatricians, Baby Boutiques, Childcare Providers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Baby Expos, Medical Supply Stores, Direct Sales |
| Companies Covered | Ergobaby, Happiest Baby, Love to Dream, KeaBabies, Woolino, Aden + Anais, Halo, Solly Baby, SwaddleDesigns, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Swaddle Wrap Market Emerging Trajectories
Material science advances and certification-driven procurement are converging to redefine product specifications and channel access requirements across the swaddle category.
Phase-change material coatings are absorbing excess body heat from neonates during sleep cycles and releasing it during temperature drops. First-time parents in the United States are adopting these thermoregulating swaddles at accelerating rates through specialty baby boutiques. This thermal management capability is absorbing the premium-price tier that static cotton wraps previously occupied, compressing margins for conventional knit competitors.
REACH textile chemical restrictions are expanding disclosure requirements for azo dyes and formaldehyde-based finishing agents across European supply chains. Manufacturers sourcing dyed fabrics from non-EU countries must now maintain extensive chemical testing documentation to maintain market access. Small and mid-sized producers serving Germany and France are responding by consolidating supplier relationships and shifting to undyed or naturally pigmented fabric alternatives.
Certification-driven preference shifts are displacing price-based purchasing among specialty retail buyers who now require Oeko-Tex Standard 100 documentation before purchase-order execution. Independent boutiques and hospital gift shops are rejecting non-certified inventory regardless of cost advantages. This behavioral change is most visible in United States coastal metropolitan markets where organic and clean-label positioning commands shelf space allocation.
Baby Swaddle Wrap Market Segmentation
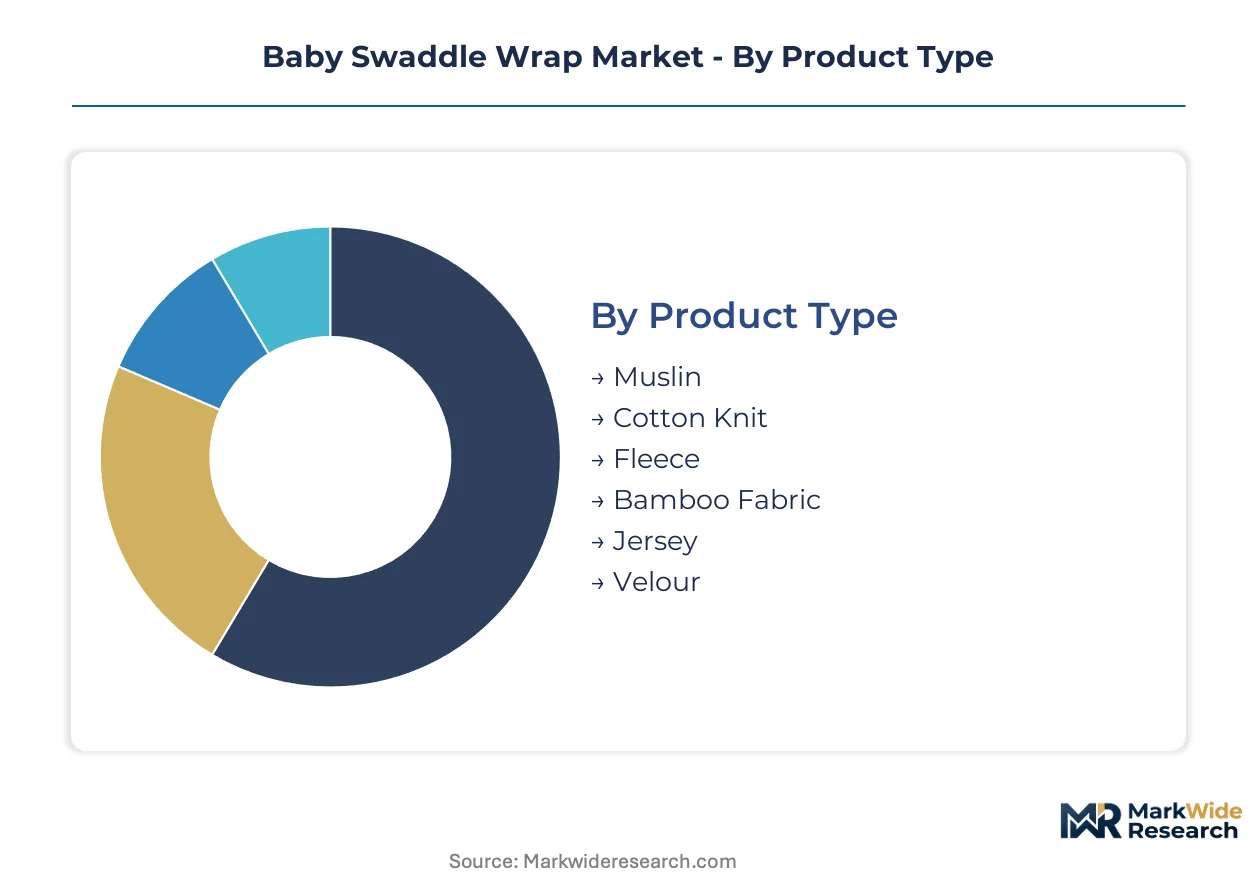
Swaddle wrap manufacturers must align material specifications, distribution channels, and end-user requirements to capture value across distinct usage contexts. Segment boundaries increasingly blur as temperature-regulating fabrics migrate from premium positioning into mass-market sleep enhancement applications. Certification requirements and channel access rules now determine which product configurations reach specific buyer groups.
Product Type:
Standalone swaddle wraps dominate volume shipments, while embedded sensor-compatible fabrics occupy the premium integration tier where wearable-monitor convergence creates new price anchors.
- Cotton Knit:Interlocked loop construction delivers stretch recovery that maintains consistent compression across repeated wash cycles. Demand clusters among first-time parents in the United States seeking breathable, temperature-neutral options for year-round nursery use.
- Bamboo Fabric:Cellulose-derived rayon fibers wick moisture three times faster than conventional cotton, creating thermal management advantages that command placement in specialty retail. Parents in coastal metropolitan markets prioritize this segment for humidity-variable climates where infant thermoregulation failsafe.
- Muslin:Open-weave cotton gauze construction maximizes airflow for summer-born infants in warm-climate regions.
- Fleece:Synthetic polyester pile provides insulative properties suited to cold-weather nursery environments.
- Jersey:Single-knit construction offers economical stretch characteristics for price-sensitive volume channels.
- Velour:Cut-pile cotton or synthetic blend delivers tactile softness for gift-oriented purchase occasions.
Volume placements concentrate in Cotton Knit; the faster expansion belongs to Bamboo Fabric.
Application:
Cost tier stratification separates medical-grade positioning from consumer convenience, with reimbursement-adjacent applications commanding price premiums over discretionary comfort purchases.
- Sleep Enhancement:Wearable-monitor integration transforms passive textiles into data-collection garments that pediatricians recommend through hospital discharge protocols. This application captures the steepest expansion trajectory as connected nursery ecosystems penetrate mainstream retail.
- Temperature Regulation:Phase-change material coatings and moisture-wicking substrates address neonatal thermoregulation failures that disrupt sleep cycles. Parents in Germany and France prioritize certified chemical-free variants under REACH disclosure requirements.
- Newborn Care:Standardized wrap designs address startle reflex suppression in the first eight weeks postpartum.
- Comfort Aid:Soft-texture prioritization targets gift purchasers seeking tactile reassurance.
- Soothing:Gentle compression applications address colic and fussiness without clinical positioning.
- Mobility Restriction:Hip-safe flexion engineering supports developmental orthopedic requirements in clinical settings.
Revenue concentration sits with Sleep Enhancement; margin expansion favors Temperature Regulation.
End User:
Customer type determines certification burden and channel access, with institutional buyers imposing documentation requirements that exclude uncertified suppliers.
- Parents:Millennial and Gen Z first-time buyers prioritize sleep-training products and organic certifications, driving premium placement in specialty retail. This segment absorbs the majority of volume through repeat purchase behavior triggered by garment wear-out.
- Neonatal Clinics:Medical-grade procurement requires Oeko-Tex Standard 100 documentation and hip-safe flexion engineering validation. Clinics in the United States source through group purchasing organizations that consolidate supplier qualification.
- Pediatricians:Endorsement-driven placement in hospital gift shops captures decision-makers at peak receptivity moments.
- Baby Boutiques:Curated assortment strategies favor certified organic and clean-label positioning.
- Daycare Centers:Volume procurement emphasizes durability and standardized sizing for multi-infant environments.
- Childcare Providers:Home-based operators prioritize cost efficiency over certification premiums.
Procurement scale favors Parents; institutional validation through Neonatal Clinics unlocks premium positioning.
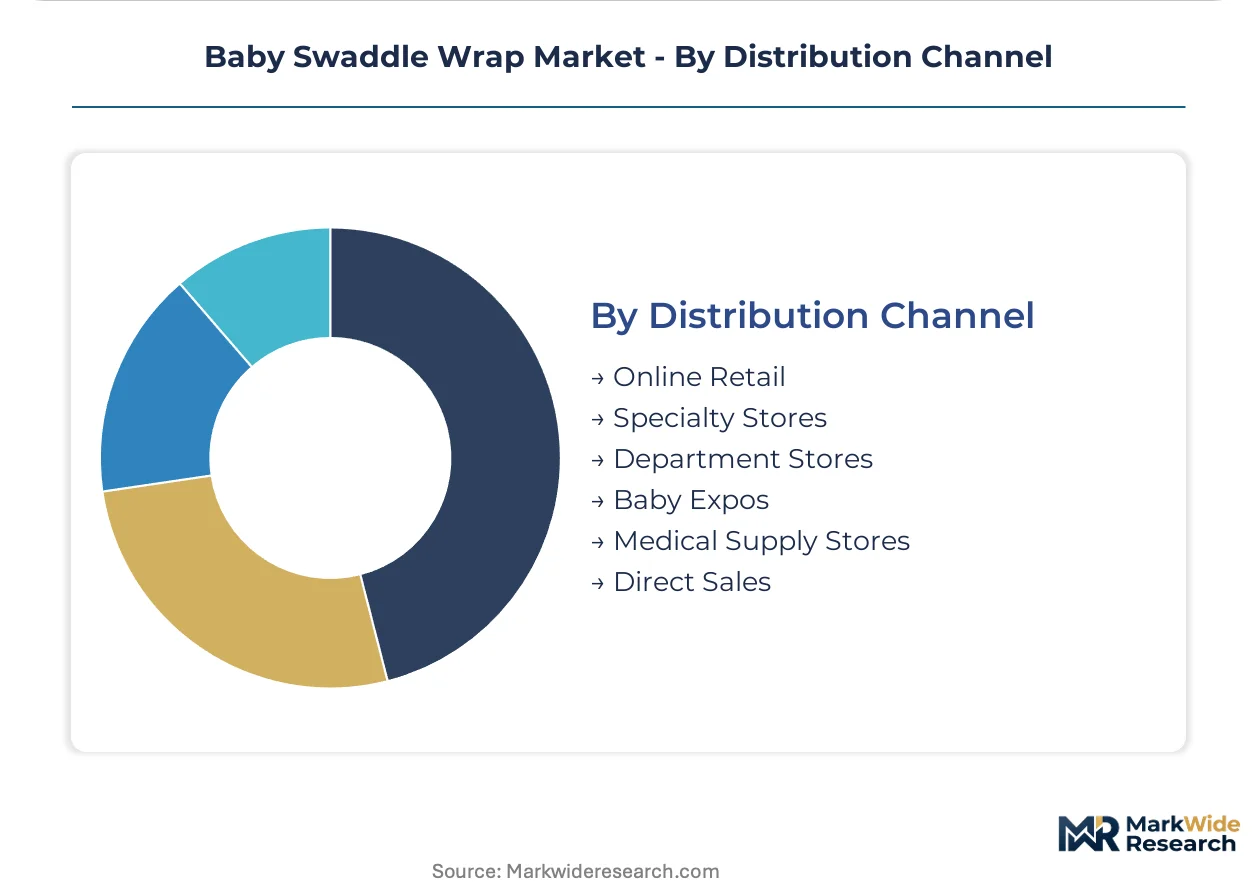
Distribution Channel:
Geographic reach and certification gatekeeping separate channels, with medical-adjacent routes requiring documentation that mass retail bypasses.
- Online Retail:Direct-to-consumer platforms enable detailed certification storytelling and subscription replenishment models. Amazon and dedicated parenting sites capture the majority of Cotton Knit and Bamboo Fabric volume through search-optimized listings.
- Specialty Stores:Curated physical environments in the United States coastal metros require Oeko-Tex Standard 100 documentation before purchase-order execution. These outlets command margin premiums through tactile evaluation and staff consultation.
- Medical Supply Stores:Institutional procurement channels serve Neonatal Clinics with bulk pricing and qualification documentation.
- Department Stores:Mass-market placement emphasizes economy-tier Jersey and Fleece variants.
- Baby Expos:Event-based sampling converts first-time parents through hands-on demonstration.
- Direct Sales:Manufacturer-owned channels bypass retailer margin extraction for premium sensor-integrated products.
Shipment volume flows through Online Retail; margin protection concentrates in Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parents in the United States drive the majority of premium organic cotton swaddle demand, with coastal metropolitan markets commanding certification standards that shape procurement patterns elsewhere. Specialty retailers in Germany and France enforce REACH chemical disclosure requirements that filter supplier access. Hospital gift shop channels in Japan and Australia create localized endorsement pathways for pediatrician-recommended brands.
United States
Millennial first-time parents prioritize sleep-training products and Oeko-Tex Standard 100 documentation, pulling premium bamboo and organic cotton swaddles into mainstream retail placement. The US Consumer Product Safety Commission governs flammability standards that determine import eligibility for woven and knit infant textiles. Los Angeles and New York Metro specialty boutiques reject non-certified inventory regardless of cost advantages, compressing margins for conventional producers.
Germany
Parents under REACH textile chemical restrictions demand extensive azo dye and formaldehyde disclosure documentation, consolidating procurement around qualified European suppliers. ECHA enforcement actions against non-compliant imports have accelerated supplier relationship consolidation among mid-sized distributors. Bavaria's organic textile manufacturing cluster around Augsburg supplies naturally pigmented fabric alternatives that bypass synthetic finishing agent requirements.
France
Temperature-conscious parents in Paris and Lyon prioritize phase-change material coatings for neonatal thermoregulation, absorbing the premium-price tier previously occupied by static cotton wraps. ANSM guidance on infant sleep product safety influences hospital discharge kit composition across maternity wards. The Île-de-France region hosts specialty retail chains that require Global Organic Textile Standard certification before purchase-order execution.
Japan
Pediatrician endorsement carries exceptional weight in Tokyo and Osaka hospital gift shop channels, where sleep technology integration commands placement premiums. METI standards for textile chemical safety align with Oeko-Tex benchmarks, reducing regulatory friction for certified imports. The Kanto region's dense concentration of neonatal clinics creates institutional procurement scale that rewards documentation-heavy supplier relationships.
Australia
Parents in Sydney and Melbourne coastal markets prioritize moisture-wicking bamboo fabrics for humidity-variable nursery environments. The Therapeutic Goods Administration monitors infant product claims that approach medical device thresholds, creating compliance preparation incentives for sensor-integrated swaddle developers. Queensland's subtropical climate drives year-round demand for thermoregulation-focused product configurations.
Baby Swaddle Wrap Market Vendor Landscape
United States producers anchor the premium-tier certification vector; European specialists hold the chemical-compliance documentation tier. The vendor base splits between vertically integrated design-to-retail operators and fabric-sourcing assemblers who absorb testing cost burdens through margin compression. Three archetypes dominate: pediatrician-endorsed technology integrators, organic certification specialists, and flame-resistant safety standard bearers. Capacity expansion into captive dyeing facilities and strategic partnerships with hospital procurement consortia represent the dominant competitive moves.
Within the endorsement-driven tier, Happiest Baby and Halo exemplify positioning strategies that convert clinical credibility into retail channel access. Ergobaby occupies a position among vertically integrated operators who control design-to-retail workflows. These three entities represent distinct archetypes: technology-pediatrician convergence, safety-certification anchoring, and supply chain integration. Their collective presence shapes tier boundaries that smaller fabricators struggle to penetrate without documentation investments or clinical relationship development.
| Leading Market Players |
|---|
| Ergobaby |
| Happiest Baby |
| Love to Dream |
| KeaBabies |
| Woolino |
| Aden + Anais |
| Halo |
| Solly Baby |
| SwaddleDesigns |
| Others |
Supply Flow & Price Mechanics
First-time parent concentration in specialty retail channels anchors premium pricing for certified organic cotton and bamboo fabric swaddles, while mass-market buyers absorb economy-tier jersey alternatives through volume discounters. Oeko-Tex Standard 100 documentation requirements create price stratification that rewards compliant producers with shelf space premiums and marginalizes uncertified competitors.
Pricing Analysis
Short lead-time premiums dominate hospital gift shop procurement, where pediatrician-endorsed brands command placement fees for immediate maternity ward availability. Three-tier pricing structure across premium sensor-integrated, standard certified-organic, and economy conventional-cotton levels segments buyers by certification sensitivity. Cost compression in the economy tier intensifies because Indian and Turkish organic cotton yield volatility destabilizes input costs. Neonatal clinics exhibit lowest price sensitivity due to reimbursement-adjacent procurement, while home-based childcare providers drive spot-market discounting.
Supply Chain Analysis
Regional distribution centers in Los Angeles and New York Metro consolidate inbound shipments from India, Turkey, and China before last-mile deployment to specialty boutiques. Raw material flows draw from Indian organic cotton gins, Turkish textile mills, and Chinese bamboo viscose processors. Single-source vulnerability concentrates in azo dye finishing agents subject to REACH disclosure restrictions. Distribution runs through hub-and-spoke patterns anchored by coastal metropolitan warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification mandate escalation is forcing margin compression that eliminates undifferentiated assemblers, consolidating share among vertically integrated operators with captive dyeing capabilities.
For Market Incumbents: Cement market position through backward integration into Oeko-Tex-certified dyeing facilities that neutralize REACH compliance cost disadvantages. Secure exclusive pediatrician endorsement contracts for hospital gift shop placement before ASTM reclassification raises medical device barriers. Threat substitution from sleep-sack transitional garments demands hip-safe flexion engineering differentiation. For New Entrants and Emerging Players: Direct-to-consumer subscription models offer lowest channel access friction for sensor-integrated premium swaddles bypassing specialty retailer gatekeeping. Target underpenetrated neonatal clinic procurement in Japan and Australia where documentation-heavy supplier relationships deter incumbent expansion. White-space exists in thermoregulation sensor convergence for subtropical climate zones. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists with captive Indian organic cotton supply and existing Oeko-Tex certification in Augsburg-adjacent manufacturing clusters. Five-to-ten year viability hinges on ASTM medical device reclassification preparation. Watch pending FDA guidance on infant sleep product definitions as inflection indicator for regulatory moat valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | Oeko-Tex Standard 100 documentation unlocks specialty retailer purchase orders in coastal US metros. |
| Hospital Channel Partnership | Pediatrician endorsement placement captures decision-makers at peak receptivity in maternity wards. |
| Sensor Integration Development | Wearable-monitor compatibility converts passive textiles into data-collection garments for connected nurseries. |
| Backward Integration | Captive dyeing facilities absorb REACH testing costs without margin erosion for European market access. |
| Geographic Manufacturing Footprint | Augsburg cluster proximity reduces synthetic finishing agent compliance burdens under ECHA enforcement. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this baby swaddle wrap market assessment. Primary interviews with infant product brand managers, specialty retailer category buyers, neonatal clinic procurement officers, and textile certification auditors combined with bottom-up shipment analysis and top-down retail audit validation. Secondary sources included US Consumer Product Safety Commission flammability standard updates, ECHA REACH enforcement actions, Oeko-Tex certification databases, and Global Organic Textile Standard audit records.
Data-stream reconciliation across product type, application, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical volume trends and elasticity-adjusted price trajectories. Industry-specific forecast inputs incorporated organic cotton yield volatility indices from Indian and Turkish agricultural bureaus and ASTM infant sleep product reclassification probability assessments.
The model holds under stable regulatory certification requirements; deviation in REACH chemical disclosure expansion or ASTM medical device reclassification timing would shift volume and value trajectories. Forecasts reflect documented assumptions regarding millennial parent segment prioritization of sleep-training products and specialty retailer gatekeeping behavior. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Smart Bottle Warmers Market
Baby Products
Puppy Teething Toys Market
Baby Products
Baby Portable Co-Sleeper Market
Baby Products
Australia Baby Care Products Market
Baby Products
Baby Feeding Bottles Market
Baby Products
Baby Care and Mother Care Market
Baby Products
Home Care Packaging Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Smart Crib Market
Baby Products
Global Baby Car Seats Market
Baby Products
Italy Baby Care Products Market
Baby Products
France Baby Care Products Market
Baby Products
Baby Stroller Market
Baby Products
Feeding Bra Market
Baby Products
North America Baby Bottle Market
Baby Products
US Baby Care Products Market