
 Soft Sole Baby Shoes Market | 2026-2036
Soft Sole Baby Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Sole Baby Shoes Market Insights
Premium leather certification is bifurcating the competitive landscape as parents prioritize podiatrist-endorsed construction. Robeez leverages its medical-advisory relationships to sustain pricing power in the North American specialty channel. Bobux anchors the Australasian market through vertically controlled tanning partnerships that guarantee chrome-free leather sourcing.
Soft sole baby shoes are footwear designed for pre-ambulatory and early-walking infants, typically constructed with flexible leather or textile uppers and minimal structural rigidity to permit natural foot development and proprioceptive feedback. Canvas and cotton segments dominate unit volume through mass-market accessibility, while leather commands disproportionate margin pools due to durability claims and dermatological safety positioning. Slip-on closure types lead in the 0-6 month bracket where caregiver convenience overrides adjustability needs, whereas Velcro gains share in the 6-18 month window as fit precision becomes critical for active cruisers.
The US Consumer Product Safety Commission governs small-part choking hazards and flammability standards, while the EU REACH regulation restricts phthalates and azo dyes in infant-contact textiles, effectively filtering low-cost synthetic entrants from Western European shelves. China's GB standards for infant and child textile safety, administered by SAMR, create a parallel compliance architecture that domestic champions like Goodbaby navigate with lower certification overhead than foreign competitors. Stakeholders must monitor evolving chemical restriction lists and pediatric orthopedic endorsement protocols as the primary arbiters of brand credibility and shelf access.
Market Dynamics
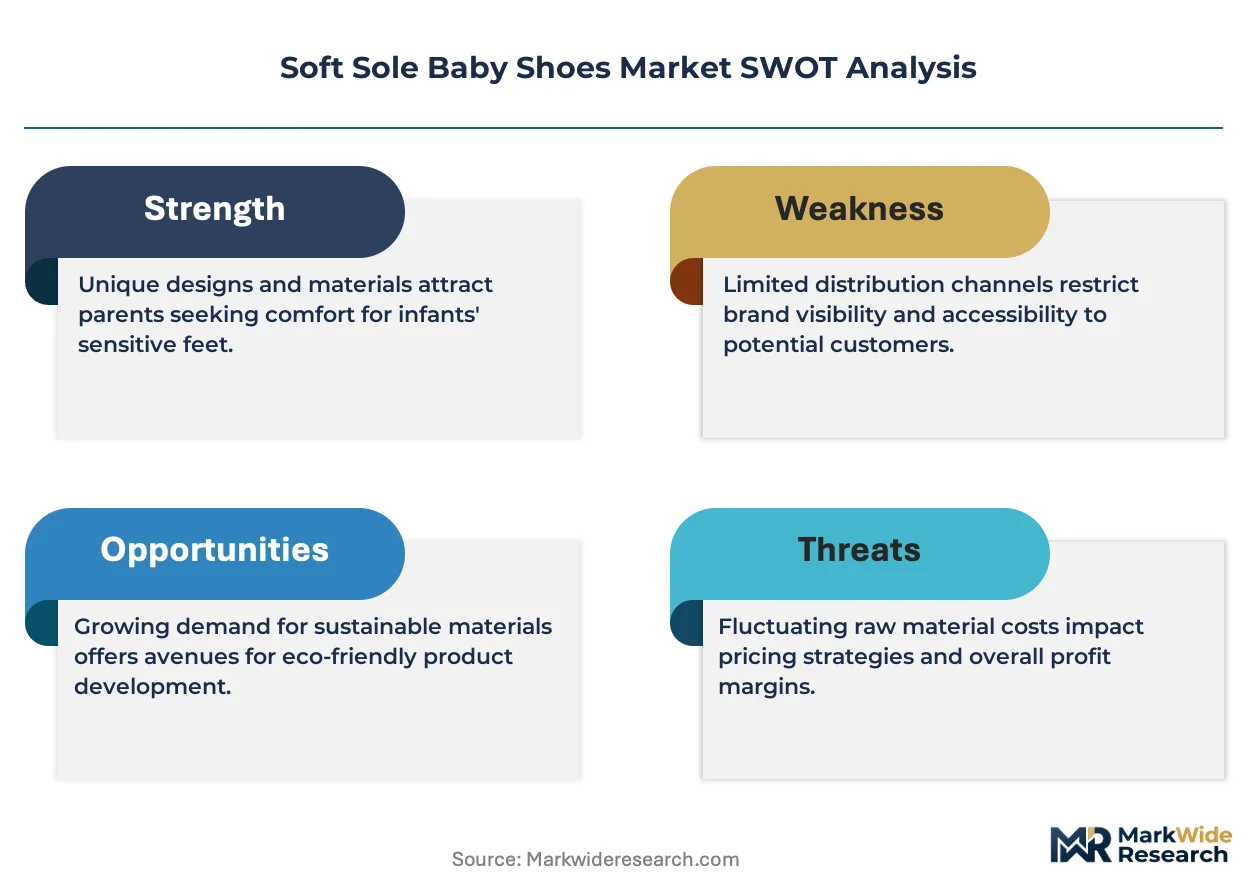
EU REACH chemical restrictions are forcing a wholesale reconfiguration of tanning chemistry and textile finishing across the soft sole baby shoes supply chain, elevating compliance costs for synthetic-dependent manufacturers while rewarding chrome-free leather specialists.
Growth Catalysts
- Pediatric orthopedic endorsement protocols:Podiatrist recommendations now carry decisive weight in caregiver purchase decisions, creating premium pricing power for medically validated construction methods.
- China's GB standards evolution:SAMR-administered infant textile safety rules tighten annually, advantaging domestic champions with established compliance infrastructure over import-dependent competitors.
- Millennial urban parent density:Concentrated demand in Shanghai, Beijing, and Shenzhen generates sufficient volume to justify dedicated premium leather production lines.
Market Restraints
- Chrome-tanning input dependency:Vegetable-tanning alternatives require 3-4x longer processing cycles and specialized tannery partnerships, constraining rapid scale-up.
- EU REACH azo dye restrictions:The regulation's expanding prohibited substance list forces continuous reformulation of textile colorants, fragmenting supplier relationships.
- Synthetic leather substitution threat:Polyurethane microfiber alternatives achieve price points 40-60% below full-grain leather, pressuring mid-tier positioning.
Strategic Opportunities
- Subscription-based sizing programs:Direct-to-consumer models offering quarterly size replacements address the 6-18 month rapid growth window, locking in recurring revenue.
- India's BIS certification pathway:Early movers establishing ISI-marked domestic production gain preferential access to organized retail shelf space ahead of mandatory standards enforcement.
- 3D foot-scanning integration:Converging smartphone photogrammetry with AI sizing algorithms enables remote fit precision, reducing return rates in e-commerce channels.
Industry Challenges
- Pediatric biomechanist talent scarcity:The specialized knowledge required to validate natural foot development claims outstrips available qualified professionals, elongating product development timelines.
- Multi-jurisdiction certification synchronization:Simultaneous compliance with US CPSC small-part standards, EU REACH chemical limits, and China GB testing creates documentation complexity and launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Sole Baby Shoes Market |
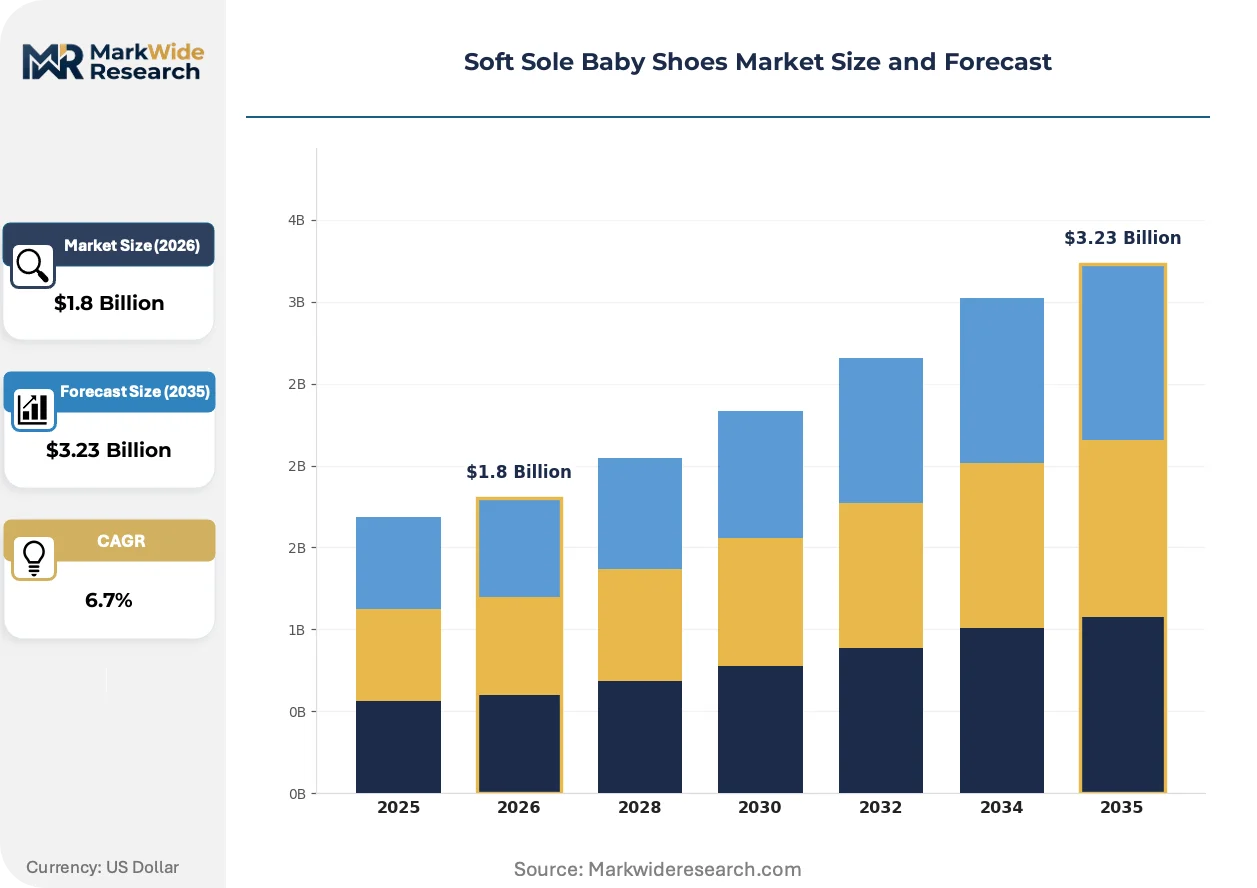
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leather, Canvas, Cotton, Synthetic Size: 0-3 Months, 3-6 Months, 6-12 Months, 12-18 Months Closure Type: Velcro, Slip-On, Laces, Zipper Design Style: Casual, Dressy, Sports, Novelty |
| Companies Covered | Robeez, Bobux, Stride Rite, ABCkids, BOBDOG, Goodbaby, Carter's, Freshly Picked, Softstar Shoes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Sole Baby Shoes Market Trends and Innovations
Digital fit technologies and biomaterial chemistry are converging to transform how soft sole baby shoes are specified, manufactured, and distributed, compressing traditional channel structures while elevating technical performance requirements.
Laser-perforated vegetable-tanned leather is bifurcating the premium segment by delivering dermatological safety credentials alongside breathability performance. Millennial parents in coastal Chinese cities and German-speaking Europe adopt these constructions fastest, paying sustained premiums for chrome-free certification. The technology is bifurcating competitive positioning between medically endorsed specialists and commodity leather assemblers unable to source compliant tannery partnerships.
REACH Substances of Very High Concern candidate list expansion is systematically eliminating phthalate plasticizers and certain azo dyes from infant-contact textiles. Western European retailers now demand full material disclosure to SVHC thresholds, filtering out suppliers lacking toxicological testing infrastructure. Small-scale artisan producers in Southern Europe face disproportionate compliance burdens relative to vertically integrated Asian manufacturers with captive laboratories.
Caregivers increasingly prioritize podiatrist-validated construction over brand heritage or aesthetic differentiation when selecting first-walker footwear. Specialty children's footwear boutiques and pediatric orthopedic clinics are displacing generalist department stores as primary discovery channels for 6-18 month segments. This concentration is most pronounced in Australia's major metropolitan markets, where TGA-recognized therapeutic claims carry substantial marketing weight.
Soft Sole Baby Shoes Market Segmentation
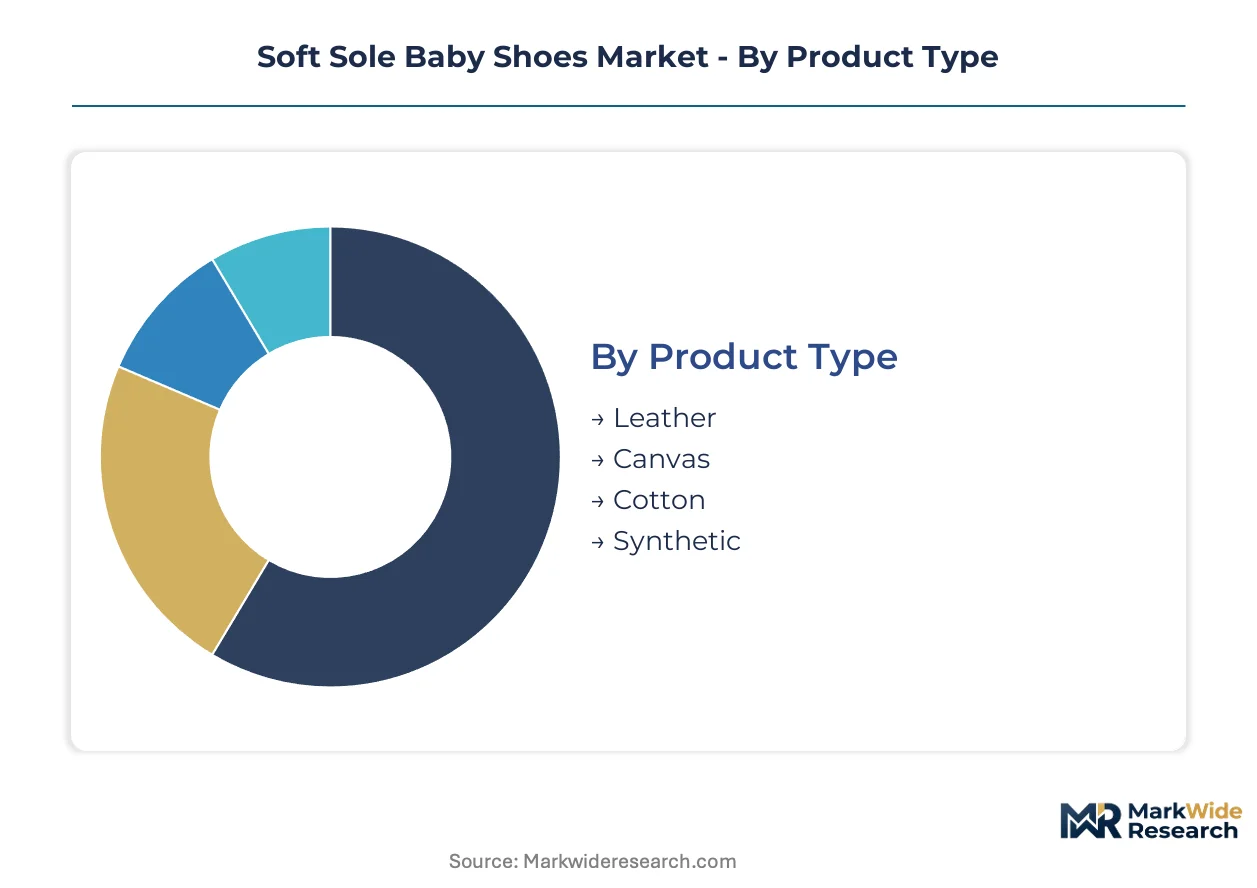
Material chemistry and infant developmental stages create distinct performance requirements across soft sole baby shoes. Caregivers prioritize podiatrist-endorsed constructions for early walkers while convenience drives pre-ambulatory selections. Each segmentation dimension carries unique substitution pressures from adjacent categories.
Product Type:
Polyurethane microfiber alternatives exert acute price pressure on natural materials, forcing clear differentiation strategies.
- Leather:Full-grain and vegetable-tanned constructions dominate premium positioning through chrome-free certification and dermatological safety credentials. Millennial parents in Shanghai and Shenzhen absorb sustained price premiums for podiatrist-validated leather soles that permit natural proprioceptive feedback during early walking phases.
- Canvas:Woven cotton duck and twill constructions anchor mass-market accessibility through machine-washable convenience and seasonal pattern refresh cycles. Urban Chinese parents favor canvas for daycare environments where frequent cleaning outweighs durability concerns.
- Cotton:Soft jersey and terry cloth uppers serve the 0-6 month pre-walking segment where structural rigidity remains unnecessary.
- Synthetic:PU microfiber and bonded leather alternatives achieve 40-60% price discounts against full-grain leather, pressuring mid-tier positioning.
Canvas retains volume leadership; leather holds the steepest expansion curve.
Size:
Developmental milestones dictate replacement frequency and channel preferences across age brackets.
- 0-3 Months:Pre-ambulatory infants require minimal structural support. Slip-on cotton constructions dominate hospital gift markets and first-time parent registries.
- 3-6 Months:Cruising preparation introduces first walker considerations. Caregivers in Beijing and Guangzhou prioritize podiatrist-endorsed leather constructions for this transitional window.
- 6-12 Months:Active cruising demands precise fit adjustability. Velcro closure adoption peaks here as rapid foot growth necessitates weekly size verification.
- 12-18 Months:Confident walking shifts preference toward durability and outdoor protection. Leather soles with reinforced toe caps gain traction among urban parents.
The 6-12 month bracket generates highest replacement velocity; 12-18 months shows the strongest margin expansion.
Closure Type:
Caregiver dexterity constraints and infant mobility levels determine mechanical preference.
- Velcro:Hook-and-loop fasteners enable rapid size adjustment during diaper changes and mid-activity refitting. Active cruisers in the 6-18 month window generate concentrated demand where fit precision prevents trip hazards.
- Slip-On:Elasticized ankle openings dominate the 0-6 month segment where single-handed application matters most. Sleepers and pre-ambulatory infants constitute primary end-use.
- Laces:Traditional tie closures persist in dressy occasions and orthopedic customizations requiring precise tension control.
- Zipper:Side-zip constructions occupy niche positioning for wide-foot infants needing expanded entry apertures.
Slip-on constructions retain volume leadership; Velcro gains share fastest.
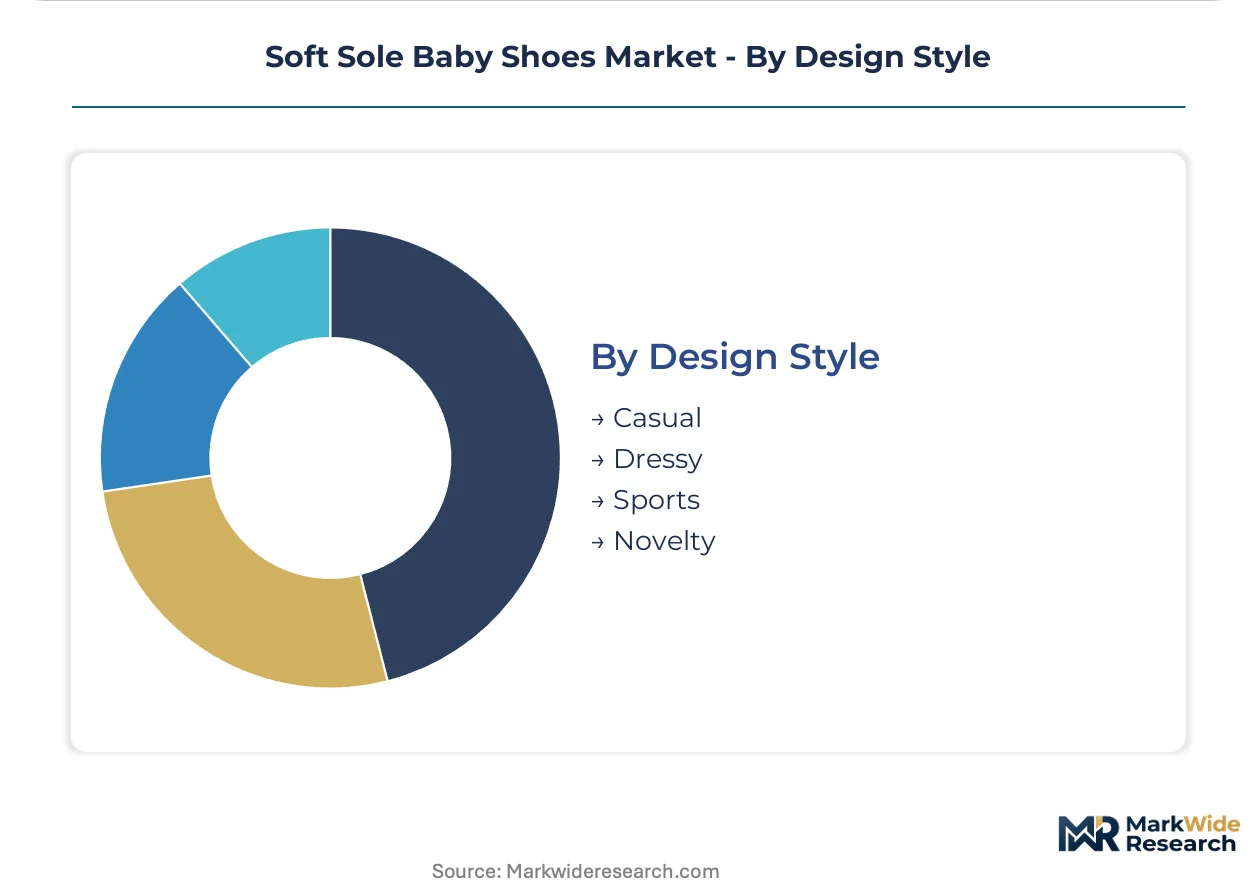
Design Style:
Occasion-based segmentation separates everyday utility from photographic and social presentation needs.
- Casual:Everyday wearable constructions prioritize machine washability and neutral color palettes. Canvas and cotton materials dominate this high-rotation segment.
- Dressy:Patent leather and embellished constructions serve family photography, religious ceremonies, and formal gatherings. Limited wear cycles justify premium pricing.
- Sports:Athletic-inspired aesthetics with reinforced soles target active toddlers in suburban environments.
- Novelty:Character licensing and seasonal motifs drive gift market velocity through impulse purchase channels.
Casual styling retains volume leadership; dressy constructions command the highest unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor domestic manufacturers in China and India while Western markets rely on specialized imports from chrome-free tanneries. Trade flows concentrate premium leather constructions toward EU and North American retail channels.
China
Millennial parents in Shanghai and Shenzhen drive premium leather absorption for the post-one-child-policy generation. SAMR-administered GB standards for infant textile safety tighten annually, advantaging domestic champions with established compliance infrastructure. Guangzhou anchors vegetable-tanned leather production clusters serving both domestic and export markets.
United States
Pediatric orthopedic endorsement protocols carry decisive weight in caregiver purchase decisions across urban coastal markets. The US Consumer Product Safety Commission governs small-part choking hazards and flammability standards for infant footwear. California and New York Metro concentrate specialty children's footwear boutiques displacing generalist department stores.
Germany
ECHA REACH Substances of Very High Concern candidate list expansion eliminates phthalate plasticizers from infant-contact textiles. Retailers demand full material disclosure to SVHC thresholds, filtering suppliers lacking toxicological testing infrastructure. Bavaria hosts precision tanneries specializing in chrome-free certification for premium export markets.
Australia
TGA-recognized therapeutic claims carry substantial marketing weight in major metropolitan markets. Podiatrist-validated construction displaces brand heritage as the primary purchase criterion. Melbourne and Sydney concentrate specialty children's footwear boutiques with medical-advisory relationships.
India
BIS certification pathways for infant textile safety create preferential access to organized retail shelf space. Early movers establishing ISI-marked domestic production gain structural advantages ahead of mandatory standards enforcement. Maharashtra and Gujarat host emerging leatherworking clusters targeting premium export positioning.
Soft Sole Baby Shoes Market Competitive Landscape
Concentration sits with medically endorsed specialists and vertically integrated tannery operators rather than mass-market assemblers. The competitive terrain separates chrome-free leather validators from commodity producers unable to source compliant supply partnerships. Three archetypes dominate: podiatry-advisory specialists, captive-tannery integrators, and direct-to-consumer subscription operators. Capacity expansion in vegetable-tanning partnerships and strategic licensing of digital fit technologies constitute the primary competitive moves.
Among North American podiatry-advisory specialists, Robeez and Stride Rite exemplify medically validated construction archetypes. Bobux represents the captive-tannery integrator model through Australasian vertically controlled sourcing. Goodbaby occupies a position within the domestic champion tier leveraging China's GB standards compliance infrastructure.
| Leading Market Players |
|---|
| Robeez |
| Bobux |
| Stride Rite |
| ABCkids |
| BOBDOG |
| Goodbaby |
| Carter's |
| Freshly Picked |
| Softstar Shoes |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements with chrome-free tanneries in Bavaria and Guangzhou lock in both supply access and price visibility for premium leather specialists, insulating them from REACH-driven input cost volatility that disrupts synthetic-dependent competitors.
Pricing Analysis
Millennial parents in Shanghai anchor three-tier pricing structure across premium, standard, and economy levels. Chrome-free certification and podiatrist endorsement command substantial premiums over commodity leather, while polyurethane microfiber alternatives intensify cost compression in mid-tier positioning. Caregivers in mass-market channels exhibit acute price sensitivity, whereas specialty boutique customers absorb sustained premiums for dermatological safety credentials.
Supply Chain Analysis
Vegetable-tanning capacity bottlenecks in Southern Germany and Guangdong province constrain rapid scale-up for compliant leather output. Raw material flows draw from Argentinian hides, Italian tanning chemicals, and Chinese textile components. Single-source vulnerability concentrates in chrome-free tanning expertise. Distribution runs through specialty children's boutiques and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among millennial parents in urban China, as consolidated demand in Shanghai and Shenzhen generates sufficient volume to justify dedicated premium production lines and reshape supplier negotiations.
For Market Incumbents: Fortify medical-advisory relationships and captive tannery partnerships against synthetic substitution threats. Deepen backward integration into vegetable-tanning capacity in Guangdong to secure REACH-compliant supply. Lock in podiatrist endorsement protocols as a defensive moat against mid-tier price erosion. For New Entrants and Emerging Players: BIS certification fast-track for Indian domestic production opens preferential shelf access ahead of mandatory enforcement. White-space exists in 3D foot-scanning integration for e-commerce fit precision. Target subscription-based sizing programs in the 6-18 month rapid growth window through direct-to-consumer launch. For Investors and Strategic Acquirers: Captive-tannery operators with chrome-free certification represent the most defensible acquisition archetype in a five-to-ten-year window. Monitor REACH Substances of Very High Concern candidate list expansion as the primary inflection signal for compliance cost divergence between leather specialists and synthetic assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Chrome-Free Tannery Partnership | REACH compliance secures shelf access in German and French retail channels. |
| Direct-to-Consumer Subscription Launch | Recurring revenue locks in millennial parents during rapid infant growth phases. |
| Pediatric Orthopedic Certification | TGA-recognized claims displace brand heritage in Australian metropolitan markets. |
| 3D Foot-Scanning Integration | AI sizing algorithms reduce e-commerce return rates for active cruiser segments. |
| India BIS Certification Pathway | ISI-marked production gains preferential access to organized retail ahead of mandates. |
Research Methodology
A spread of perspectives from tannery operations managers, pediatric orthopedic clinic procurement heads, specialty children's boutique buyers, and brand supply chain directors converged on the working assumptions. Secondary validation drew from SAMR GB standards filings, ECHA REACH candidate list updates, US CPSC recall databases, and customs trade records. Bottom-up unit economics and top-down category spend estimates were triangulated to anchor volume and value outputs.
Material chemistry, infant developmental stage, closure mechanism, and regional regulatory cluster segmentation dimensions were modeled across the projection horizon. CAGRs were derived from replacement velocity curves in each age bracket and premium absorption rates in coastal Chinese cities. Forecast inputs incorporated tanning capacity expansion timelines and evolving chemical restriction protocols.
Decision-makers should treat outputs as directional under sustained REACH enforcement and millennial urban parent density assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as BIS certification timelines and smartphone photogrammetry adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Smart Baby Monitor Market
Baby Products
Postpartum Products Market
Baby Products
US Baby Care Products Market
Baby Products
Brazil Baby Care Products Market
Baby Products
Pregnancy Products Market
Baby Products
Baby Portable Co-Sleeper Market
Baby Products
Baby Playpens Market
Baby Products
Baby Care and Mother Care Market
Baby Products
Diaper Pails Market
Baby Products
Baby Bedding Market
Baby Products
Baby Changing Light Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Infant Care and Baby Care Equipment Market
Baby Products
Asia-Pacific Baby Care Products Market
Baby Products
Baby Tableware Market
Baby Products
Smart Bottle Warmers Market