
 Baby Powder Market | 2026-2036
Baby Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Powder Market Intelligence
A divergence in R&D investment for talc-free alternatives is reorganizing the competitive landscape. Legacy players face pressure to reformulate, while newer entrants gain share on a platform of ingredient transparency. The Honest Company specializes in clean-label, organic products, building a loyal consumer base. In contrast, Pigeon Corporation leverages its deep penetration in Asian infant care channels to maintain its market position.
Baby powder is an astringent cosmetic preparation applied to the skin to absorb moisture and reduce frictional chafing. Formulations are primarily composed of either refined talc, a hydrous magnesium silicate, or cornstarch, often with added fragrances. Cornstarch-based formulations represent the fastest-growing segment, driven by consumer safety preferences. The distribution channel mix is shifting, with online platforms and specialty stores gaining share from traditional supermarkets and pharmacies.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Chemicals Agency (ECHA) are tightening controls on cosmetic ingredients, particularly talc. These standards, alongside national rules from bodies like India's CDSCO, mandate stringent purity testing and influence product formulation. Stakeholders must now navigate a complex path of ingredient sourcing, product liability, and transparent consumer communication to ensure long-term viability.
Market Dynamics
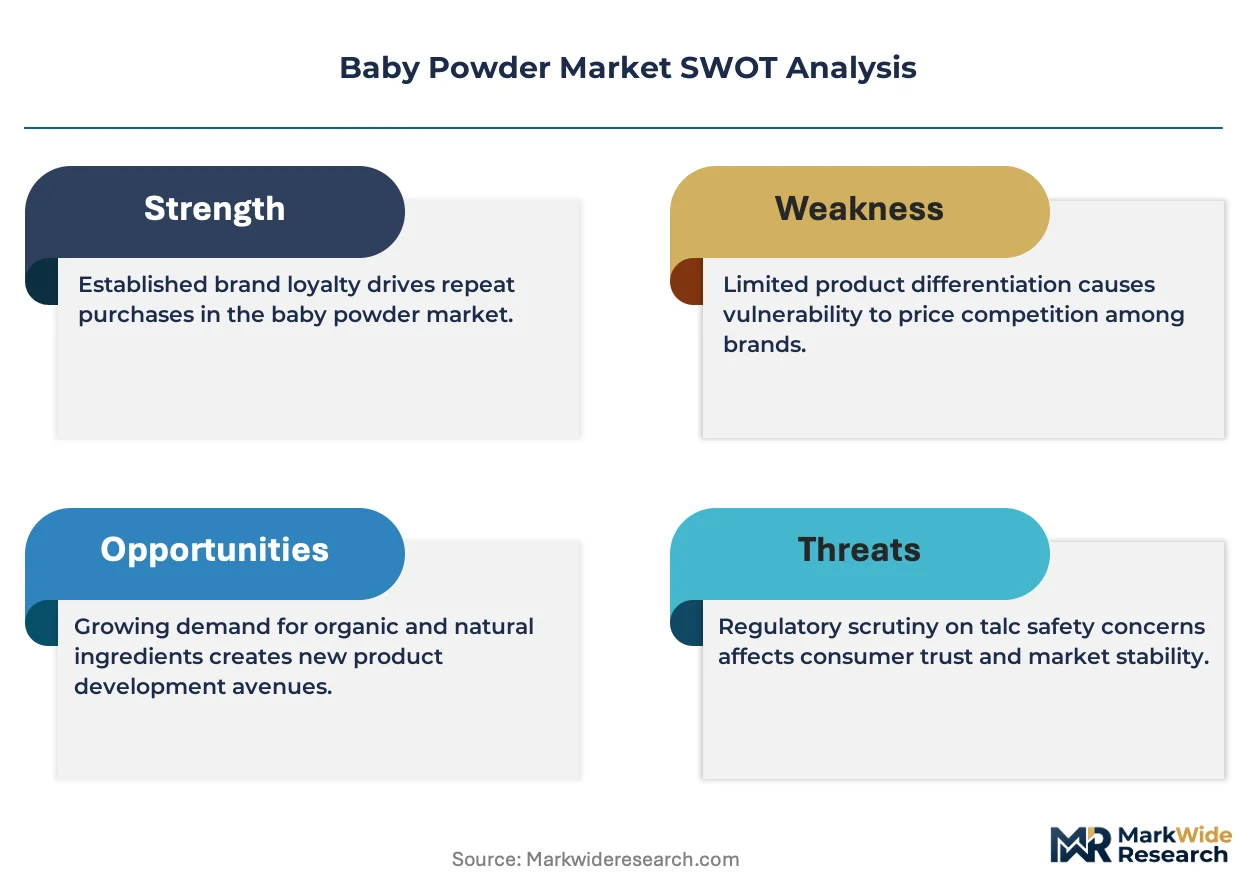
The fundamental dynamic shaping the baby powder market is the industry-wide reformulation away from talc. This shift, driven by a combination of intense regulatory pressure, consumer safety concerns, and significant product liability litigation, is reorganizing the material science foundation of the category.
Growth Catalysts
- Adult Cosmetic Applications:The expansion of baby powder use beyond infant care into adult cosmetics, where it serves as a finishing powder or dry shampoo, is opening new consumer segments.
- Premium Product Demand:The pursuit of organic and natural ingredients is creating a dedicated market segment, with demand for high-end, certified products centered in developed economies like Australia and South Korea.
- Plant-Based Alternatives:Innovation in talc-free formulations using cornstarch, arrowroot powder, and rice starch is meeting consumer preference for transparent and perceived safer ingredients, driving new product development.
Market Restraints
- Substitution by Lotions and Creams:Liquid and cream-based moisturizers and diaper rash treatments present a significant substitution threat, offering similar benefits without the risk of airborne particle inhalation.
- Regulatory Fragmentation:Navigating disparate purity standards and testing protocols for cosmetic talc from the US FDA, Europe's ECHA, and India's CDSCO creates significant compliance complexity and cost.
- Input Cost Volatility:The price of certified organic cornstarch and other plant-based inputs is higher and more volatile than that of commodity-grade talc, pressuring manufacturers' gross margins.
Strategic Opportunities
- Medicated Powder Formulations:There is an opportunity to develop specialized powders with active pharmaceutical ingredients for specific dermatological conditions, targeting the pharmacy and clinical channels.
- Male Grooming Segment:Formulating and marketing powders specifically for the male grooming market, addressing needs like anti-chafing and moisture control for sports, represents an underpenetrated application.
- Direct-to-Consumer Channels:Establishing direct-to-consumer (DTC) e-commerce platforms allows brands to control the narrative around ingredient safety and build a direct relationship with consumers seeking transparency.
Industry Challenges
- Supply Chain Realignment:Shifting sourcing from established talc mining operations to agricultural supply chains for corn or tapioca requires new procurement expertise, quality assurance protocols, and logistics networks.
- Product Liability Exposure:The ongoing specter of litigation related to talc-based products creates substantial financial risk and increases the difficulty and cost of securing adequate liability insurance.
- Consumer Education on Alternatives:Brands face the challenge of communicating the benefits and safety of new formulations without disparaging legacy products or creating undue alarm among the public.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Powder Market |
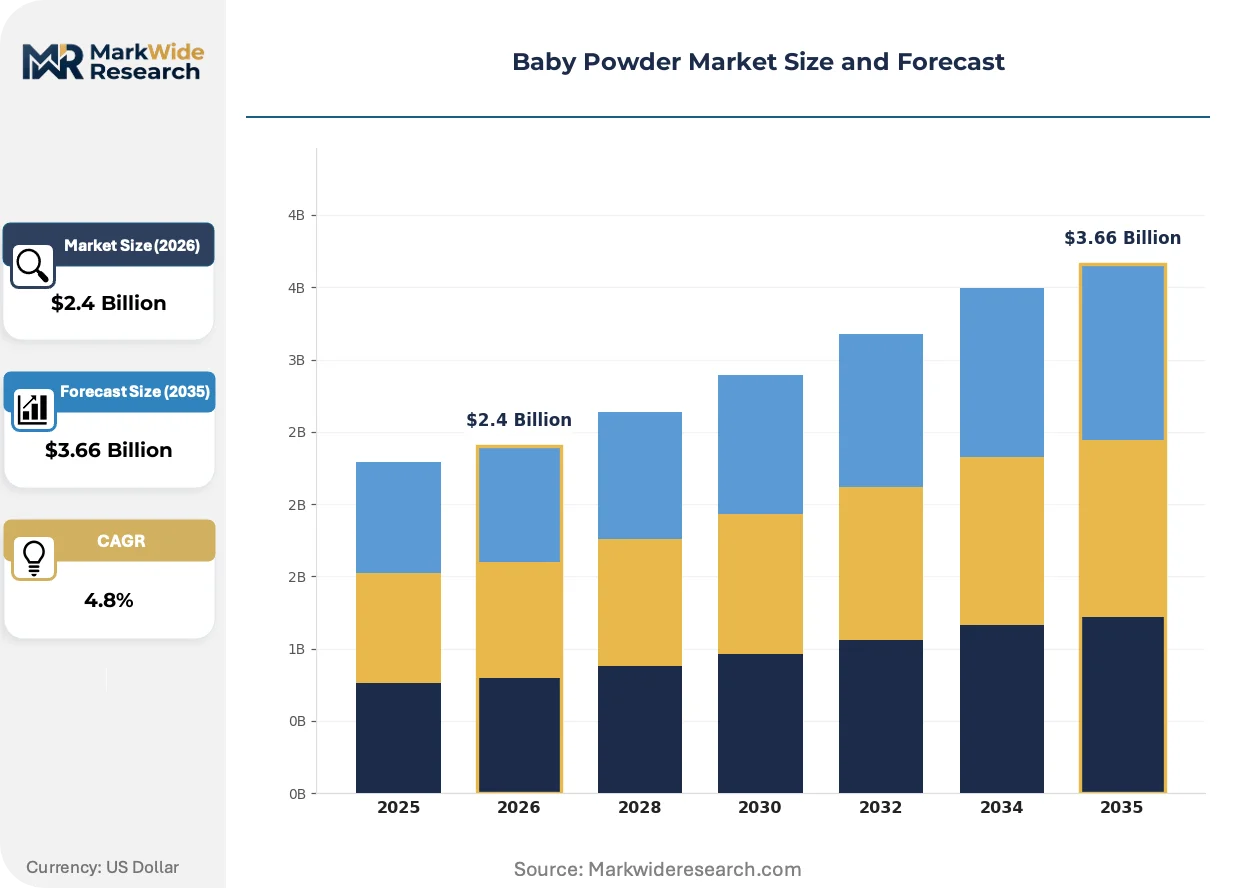
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Formulation Type: Talc-based, Cornstarch-based, Organic, Synthetic Packaging Type: Plastic Bottles, Resealable Pouches, Jars, Tubs Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores Target Age Group: Infants, Toddlers, Children, Adults |
| Companies Covered | Johnson & Johnson, Procter & Gamble, Pigeon Corporation, Himalaya Wellness, Chicco, PZ Cussons, Beiersdorf AG, Burt's Bees, The Honest Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Powder Market Strategic Shifts & Innovations
An industry-wide re-evaluation of ingredient safety and transparency is fundamentally altering product development, supply chain sourcing, and brand communication. This movement is creating clear winners and losers as the market pivots from its legacy material base to a new generation of formulations.
Plant-derived absorbents, particularly cornstarch, rice starch, and arrowroot powder, provide the core functionality for new product development. Health-conscious parents and adult consumers are the primary adopters of these alternative formulations. This rapid shift toward botanical ingredients is supplanting the historical dominance of mineral talc across all cosmetic powder applications, from infant care to adult personal hygiene.
Stricter testing mandates for asbestos in talc-containing cosmetics are being implemented by regulators, including the US Food and Drug Administration (FDA) and the European Chemicals Agency (ECHA). This regulatory tightening elevates compliance costs and legal risks for any manufacturer still utilizing cosmetic-grade talc. The talc-based product segment is most affected, prompting accelerated reformulations and market exits in geographies like Canada and the EU.
Consumer demand for ingredient transparency and clean-label products is altering distribution patterns. Purchases are increasingly made through specialty online retailers and direct-to-consumer websites that provide detailed product information. This digital-first purchasing behavior disrupts the traditional dominance of mass-market supermarkets and pharmacies. The shift is most pronounced in North America and Australia, where online research heavily influences buying decisions for baby care products.
Baby Powder Market Segmentation
Understanding the baby powder market's segmentation reveals key shifts in consumer preferences and regulatory impacts across product types. This granular analysis highlights where innovation is critical and where traditional product lines face the most significant pressures. Strategic planning must address these distinct segment dynamics to maintain market relevance.
Formulation Type:
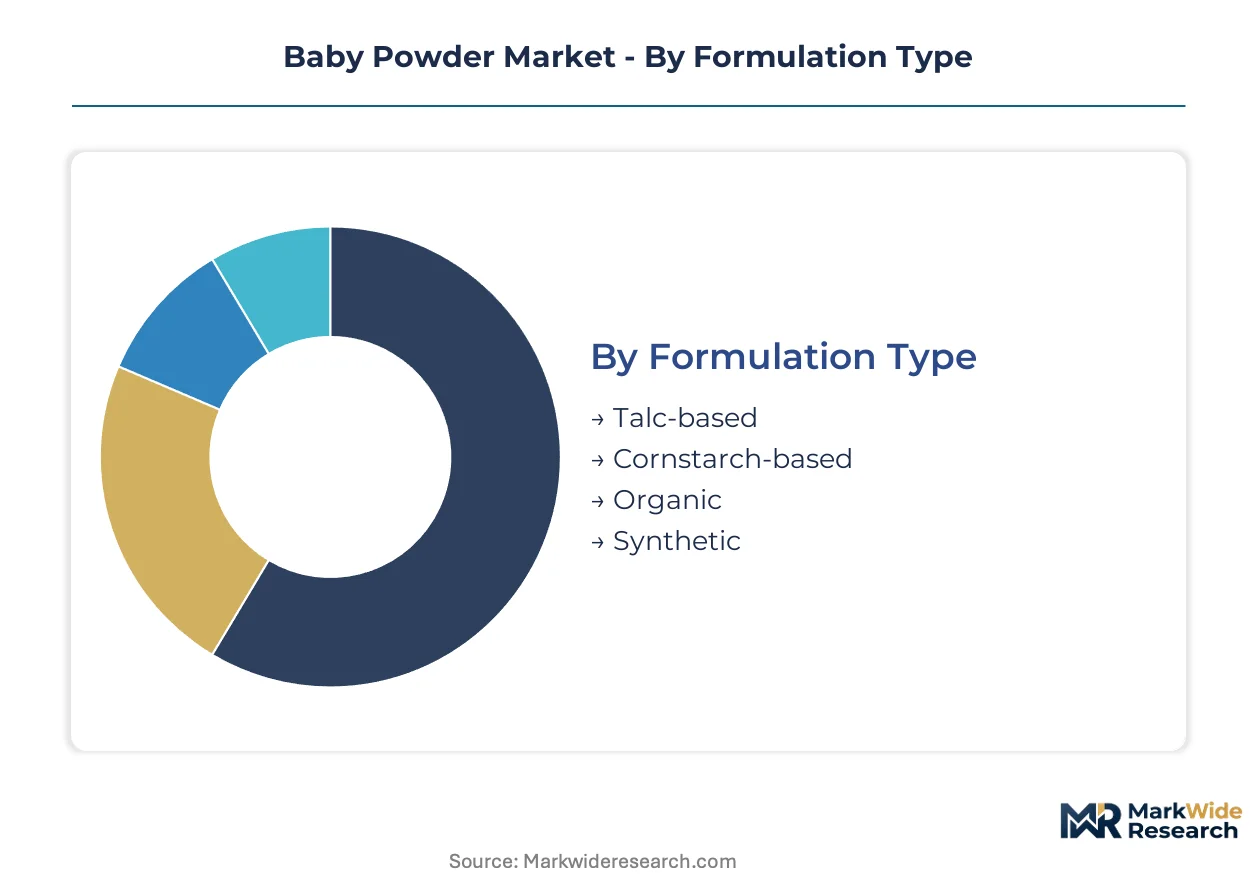
The formulation type segment faces intense substitution pressure, particularly for traditional talc-based products, as consumers increasingly opt for perceived safer alternatives. This shift reorganizes market share and necessitates significant R&D investment for legacy manufacturers.
- Cornstarch-based:These formulations utilize finely milled cornstarch as the primary absorbent, offering a natural and widely accepted alternative to talc. Demand for cornstarch-based powders is concentrating in North America and Europe, driven by parental safety concerns and robust marketing of plant-derived ingredients.
- Organic:Organic formulations are distinguished by ingredients certified to specific agricultural standards, ensuring absence of synthetic pesticides or GMOs. Premium demand for organic baby powder products is strong in markets like South Korea and Australia, where health-conscious consumers prioritize ingredient purity.
- Talc-based:Products primarily composed of hydrous magnesium silicate, historically dominant for absorbency. Regulatory scrutiny from the US FDA and ECHA impacts this segment.
- Synthetic:These formulations often include synthetic polymers or silica, designed for specific absorbency or texture properties.
Talc-based formulations anchor the volume base while organic formulations gain share at the steepest rate.
Packaging Type:
The packaging type segment reflects varying cost tiers and consumer convenience preferences, influencing both product shelf appeal and environmental impact. Manufacturers balance material costs with consumer demand for sustainable and easy-to-use formats.
- Plastic Bottles:These are rigid containers, typically made from HDPE or PET, offering durability and ease of dispensing. Plastic bottles remain a high-volume packaging choice due to their cost-effectiveness and established manufacturing infrastructure in global markets.
- Resealable Pouches:Flexible packaging solutions, often made from multi-layer films, designed for refilling larger containers or for travel. Demand for resealable pouches is expanding in Europe and North America, driven by sustainability trends and consumer desire for reduced plastic waste.
- Jars:Often glass or rigid plastic, jars provide a traditional aesthetic and easy access to the product. This packaging type appeals to consumers seeking a premium or artisanal product presentation.
- Tubs:Larger capacity containers, usually plastic, suitable for bulk purchasing or professional use. Tubs are common in institutional settings or for consumers with high-volume usage.
Plastic Bottles dominate for cost-effectiveness, while Resealable Pouches show the fastest expansion in eco-conscious markets.
Distribution Channel:
Distribution channels are evolving to meet diverse customer purchasing behaviors, ranging from convenience-driven mass market shoppers to those seeking specialized products and detailed ingredient information. This shift impacts brand visibility and market access for new entrants.
- Online:E-commerce platforms and brand-specific direct-to-consumer websites facilitate purchases with detailed product information and home delivery. Online channels are gaining significant share in North America and Australia, influencing buying decisions for baby care products.
- Specialty Stores:These retail outlets focus on niche markets such as organic products, natural health, or baby boutiques, offering curated selections and expert advice. Specialty stores attract consumers seeking premium and transparently sourced formulations, particularly in urban centers.
- Supermarkets:Large format grocery stores offering a wide range of consumer goods, including baby powder. This channel caters to a broad consumer base.
- Pharmacies:Retail establishments focused on health and wellness products, often stocking medicated or sensitive-skin formulations.
Online platforms capture significant new customer acquisition, while Supermarkets maintain broad household penetration.
Target Age Group:
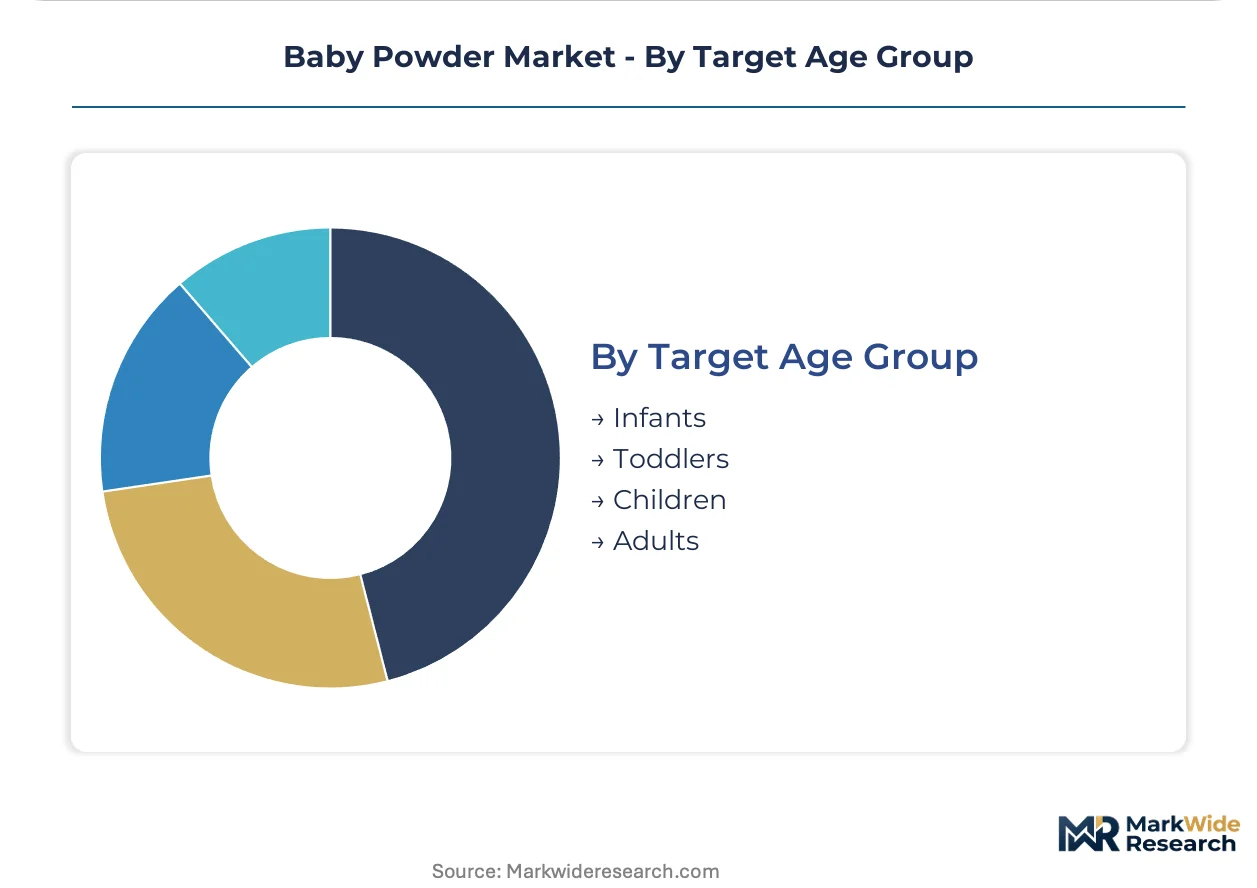
The target age group segmentation reveals distinct volume drivers and application needs, influencing product formulation and marketing strategies. Manufacturers are expanding product lines to address specific requirements across different life stages beyond traditional infant care.
- Infants:This segment comprises newborns and very young children, where baby powder is traditionally used for moisture absorption and diaper rash prevention. Infant care products dominate the market volume, driven by consistent birth rates and established parental practices.
- Adults:This segment includes individuals using baby powder for various cosmetic and personal hygiene applications, such as finishing powder, dry shampoo, or anti-chafing. The adult cosmetic application segment is expanding rapidly, particularly in developed economies, opening new consumer segments.
- Toddlers:Children between one and three years old, continuing to use baby powder for moisture control and skin comfort.
- Children:This group, generally above three years old, may use specialized powders for sports or general hygiene.
Infants remain the largest consumer group, but the adult segment is accelerating its market presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for baby powder exhibits varying elasticity across regions. Consumers in developed markets prioritize premium, organic formulations, demonstrating lower price sensitivity. Conversely, price remains a significant factor for mass-market products in emerging economies. This divergence shapes regional product development.
United States
Demand for cornstarch-based formulations is high, driven by parental safety concerns and clean-label marketing. The US Food and Drug Administration (FDA) mandates stricter testing for asbestos in cosmetic talc. California's health-conscious consumer base influences national trends toward plant-based alternatives.
South Korea
Premium organic baby powder products see strong demand, reflecting high consumer spending on certified ingredients. The Ministry of Food and Drug Safety (MFDS) enforces rigorous standards for cosmetic ingredient purity. Seoul's urban centers show concentrated adoption of high-end, imported botanical powders.
Germany
European consumers seek transparently sourced, talc-free formulations, valuing ingredient safety. The European Chemicals Agency (ECHA) influences product formulation through strict chemical substance regulations. The Rhine-Main region, a hub for chemical and cosmetic industries, drives innovation in synthetic and plant-based alternatives.
India
Infant care products dominate the market, with traditional usage patterns driving volume demand. India's Central Drugs Standard Control Organization (CDSCO) sets national purity testing standards for cosmetic ingredients. Mumbai's large consumer base and distribution networks facilitate broad market penetration for affordable options.
Australia
Health-conscious parents prioritize organic and natural baby powder options, seeking environmental certifications. The Therapeutic Goods Administration (TGA) regulates cosmetic claims and ingredient safety for products sold locally. Sydney and Melbourne metros exhibit strong demand for imported premium brands and specialty organic lines.
Baby Powder Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the baby powder market. The competitive landscape shows a tiered structure, where deeply entrenched legacy brands operate alongside agile, ingredient-focused new entrants. Strategic archetypes include multinational consumer goods giants, specialized organic product manufacturers, and regional infant care specialists. These players primarily engage in portfolio diversification, geographic expansion, and strategic partnerships to secure market share.
Multinational consumer goods companies, such as Johnson & Johnson, maintain broad market reach through established distribution networks and brand recognition. These players are currently navigating significant reformulation challenges and product liability exposure related to traditional talc-based products. In contrast, The Honest Company represents the clean-label, organic product archetype, building a loyal consumer base through transparent ingredient communication and digital-first distribution. Pigeon Corporation, a Japanese-based company, exemplifies regional specialization, leveraging its deep penetration in Asian infant care channels to sustain its market position amidst changing consumer preferences.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Procter & Gamble |
| Pigeon Corporation |
| Himalaya Wellness |
| Chicco |
| PZ Cussons |
| Beiersdorf AG |
| Burt's Bees |
| The Honest Company |
Cost & Logistics Intelligence
Long-term supply agreements for certified plant-based ingredients lock in both supply access and price visibility for manufacturers. This structure mitigates input cost volatility for cornstarch and other botanical absorbents. Strategic sourcing ensures consistent quality amidst rising demand for natural formulations.
Pricing Analysis
Brand loyalty for transparently sourced products underpins sustained value, especially for premium organic formulations. The dominant pricing model is transactional, with tiered pricing separating organic-certified products from conventional offerings. Price differentiation stems from ingredient purity and brand reputation. Pricing pressure intensifies for talc-based products due to ongoing litigation costs. Adult consumers seeking specialized cosmetic applications exhibit lower price sensitivity compared to mass-market infant care buyers.
Supply Chain Analysis
Sourcing of certified organic cornstarch and arrowroot powder presents a chokepoint, as agricultural supply chains for these specific grades are less mature than traditional mineral talc operations. Geographic supply concentrates in agricultural regions of North America for cornstarch and Southeast Asia for tapioca. Raw material dependencies include cornstarch, rice starch, and specific fragrance compounds. Commodity price volatility for these agricultural inputs poses a structural risk. Distribution runs through a hybrid model, combining traditional retail with expanding online and specialty store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baby powder market, despite its shifts, presents a defensive moat story, primarily due to regulatory entrenchment and the high switching costs associated with parental trust in infant care products.
For Market Incumbents: Secure consistent supply chains for plant-based alternatives to mitigate raw material volatility and regulatory risks. Invest in advanced R&D for novel absorbent materials to outmaneuver emerging clean-label brands. Consolidate market share in adult cosmetic applications, a segment less exposed to traditional infant care controversies. Reformulate legacy talc-based products to avoid product liability exposure and maintain brand reputation.
For New Entrants and Emerging Players: Under-served demand for hyper-allergenic, plant-based formulations represents a service-layer gap that new entrants can exploit. Target health-conscious parents in developed economies like Australia and South Korea with certified organic products. Focus on direct-to-consumer e-commerce platforms to control the narrative around ingredient transparency. Offer subscription models for recurring purchases to build customer loyalty. The most penetrable segment is premium organic infant care.
For Investors and Strategic Acquirers: The market sits at a reformulation and consolidation phase that favors agile, clean-label specialists with strong intellectual property in plant-based ingredients. Long-term viability is strong for brands that successfully navigate regulatory shifts and build consumer trust in alternative formulations. Acquisition targets should include companies with robust, certified organic supply chains and established direct-to-consumer channels. The signal to watch is the pace of regulatory harmonization for cosmetic ingredients across major economic blocs.
| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation to Talc-Free | Mitigates product liability risks and addresses evolving consumer safety concerns in infant care. |
| Direct-to-Consumer Channel Development | Builds direct customer relationships and enhances transparency around ingredient sourcing and product benefits. |
| Investment in Organic Certifications | Captures premium pricing and meets demand from health-conscious consumers in developed economies. |
| Geographic Expansion into Adult Cosmetics | Diversifies product applications and accesses new consumer segments beyond traditional infant care. |
| Supply Chain Diversification for Botanicals | Reduces reliance on single-source inputs and stabilizes costs for plant-based raw materials. |
Research Approach
A spread of perspectives from brand managers, regulatory affairs leads, specialty retailers, and raw material suppliers converged on the working assumptions for this study. Primary interviews with industry stakeholders were combined with secondary validation from cosmetic industry reports, government health agency guidelines, and trade association publications. This approach employed both bottom-up and top-down triangulation methods.
Formulation type, packaging format, distribution channel, and target age group constituted the primary segmentation dimensions modeled. The analytical framework projected market sizing and growth trajectories across the analysis window. Compound annual growth rates were derived from historical data analysis and forward-looking market drivers. Key forecast inputs included regulatory tightening on talc and consumer preference shifts towards plant-based alternatives.
Material uncertainties — including unforeseen shifts in regulatory enforcement or novel product liability claims — sit outside the modeled envelope of this study. Forecasts reflect assumptions documented through extensive research and expert consultation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Smart Baby Monitor Market
Baby Products
China Maternity Goods Market
Baby Products
Baby Swing Market
Baby Products
Baby Tableware Market
Baby Products
Baby Gift Basket Market
Baby Products
Durable Juvenile Products Market
Baby Products
Potty Training Seat Market
Baby Products
Baby Cradles Market
Baby Products
Maternity Products Market
Baby Products
Baby Changing Station Market
Baby Products
Travel Pillow Market
Baby Products
Baby Pacifier Thermometer Market
Baby Products
Baby Wipes Market
Baby Products
Australia Baby Care Products Market
Baby Products
Baby Bouncers Market
Baby Products
Kids Activity Box Market