
 Self Service Analytics Market | 2026-2036
Self Service Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Self Service Analytics Market Intelligence
Enterprise-grade governance and real-time query performance is bifurcating the competitive landscape into premium certified platforms and lighter departmental tools. Microsoft leverages its Azure cloud fabric and Power BI ecosystem to anchor large enterprise accounts with unified security policies. Tableau Software differentiates through deep visual analytics specialization and a designer-centric interface that sustains premium pricing in data-literate organizations.
Self service analytics denotes software environments enabling non-technical users to query, visualize, and disseminate data without engineering dependency, typically incorporating in-memory processing engines, semantic data layers, and drag-and-drop interface protocols for operational and strategic decision support. Cloud-based deployment leads in new bookings as organizations prioritize elastic compute scaling and reduced infrastructure ownership, while hybrid architectures retain share in regulated verticals where data residency constraints govern workload placement. Among industry verticals, finance and healthcare concentrate near-term margin pools due to compliance-intensive reporting requirements and the complexity of integrating governed self-service with legacy data warehouses.
The EU AI Act and GDPR impose algorithmic transparency and data minimization obligations that shape platform architecture choices for vendors serving European enterprises. In the United States, HIPAA and SEC disclosure rules create segment-specific compliance modules that vendors must maintain for healthcare and capital markets access. Stakeholders should monitor how generative query interfaces alter user skill requirements and whether governance automation can keep pace with expanded access tiers.
Market Dynamics
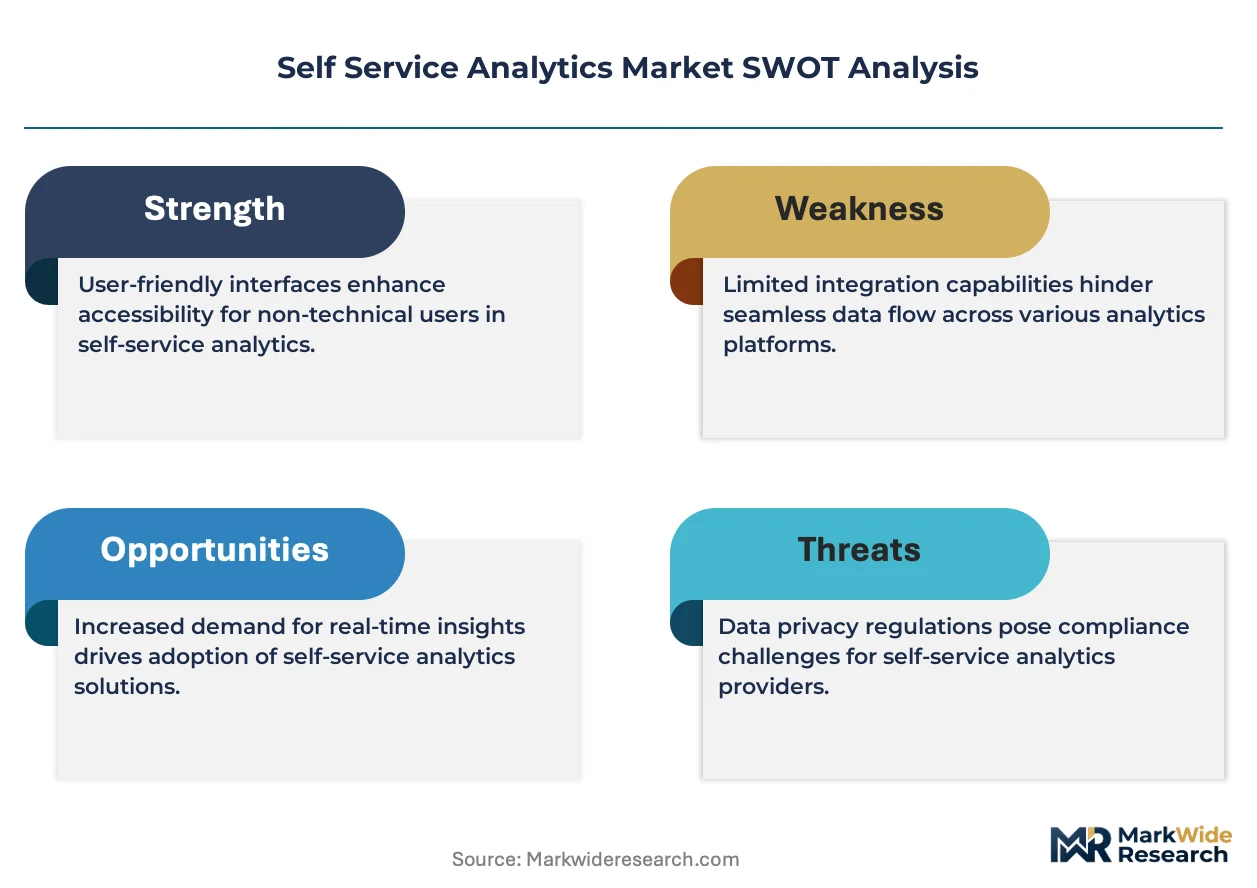
The Self Service Analytics Market is experiencing fundamental restructuring as generative query interfaces compress the technical barrier between business users and enterprise data warehouses. This shift is forcing platform vendors to rearchitect semantic layers and governance automation to accommodate exponentially expanding access tiers without sacrificing data integrity.
Growth Catalysts
- GDPR-class data sovereignty mandates:European enterprises must maintain resident data processing capabilities, accelerating cloud platform modernization and creating captive demand for compliant self-service infrastructure.
- Healthcare operational digitization:HIPAA-governed providers deploy clinical dashboards without IT intermediation, driving specialized compliance modules and governed semantic layers for protected health information.
- In-memory processing commoditization:Elastic compute scaling from hyperscale cloud providers reduces query latency barriers, enabling real-time self-service analytics for operational decision support.
Market Restraints
- Data residency fragmentation:Divergent national sovereignty rules (China's data localization, Russia's data storage laws, India's draft data protection framework) force multi-region infrastructure duplication.
- Legacy warehouse integration complexity:Decades-old on-premise data architectures resist semantic abstraction, requiring costly middleware layers for governed self-service exposure.
- Skill scarcity in data governance:Shortage of professionals capable of designing row-level security policies and lineage tracking systems constrains enterprise rollout velocity.
Strategic Opportunities
- EU AI Act algorithmic transparency requirements:Automated explanation generation for AI-augmented queries creates premium functionality demand among European financial services and healthcare enterprises.
- Natural language-to-SQL convergence:Large language model integration with semantic layers enables conversational analytics interfaces for non-technical executive users.
- India's PLI scheme for data centers:Domestic cloud infrastructure incentives position the country as an emerging hub for Asia-Pacific self-service analytics delivery.
Industry Challenges
- Multi-cloud governance orchestration:Enterprises distributing workloads across AWS, Azure, and Google Cloud face inconsistent policy enforcement and identity federation complexity.
- Real-time pipeline engineering talent:Scarcity of streaming data architects capable of maintaining sub-second latency for operational dashboards limits use case expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self Service Analytics Market |
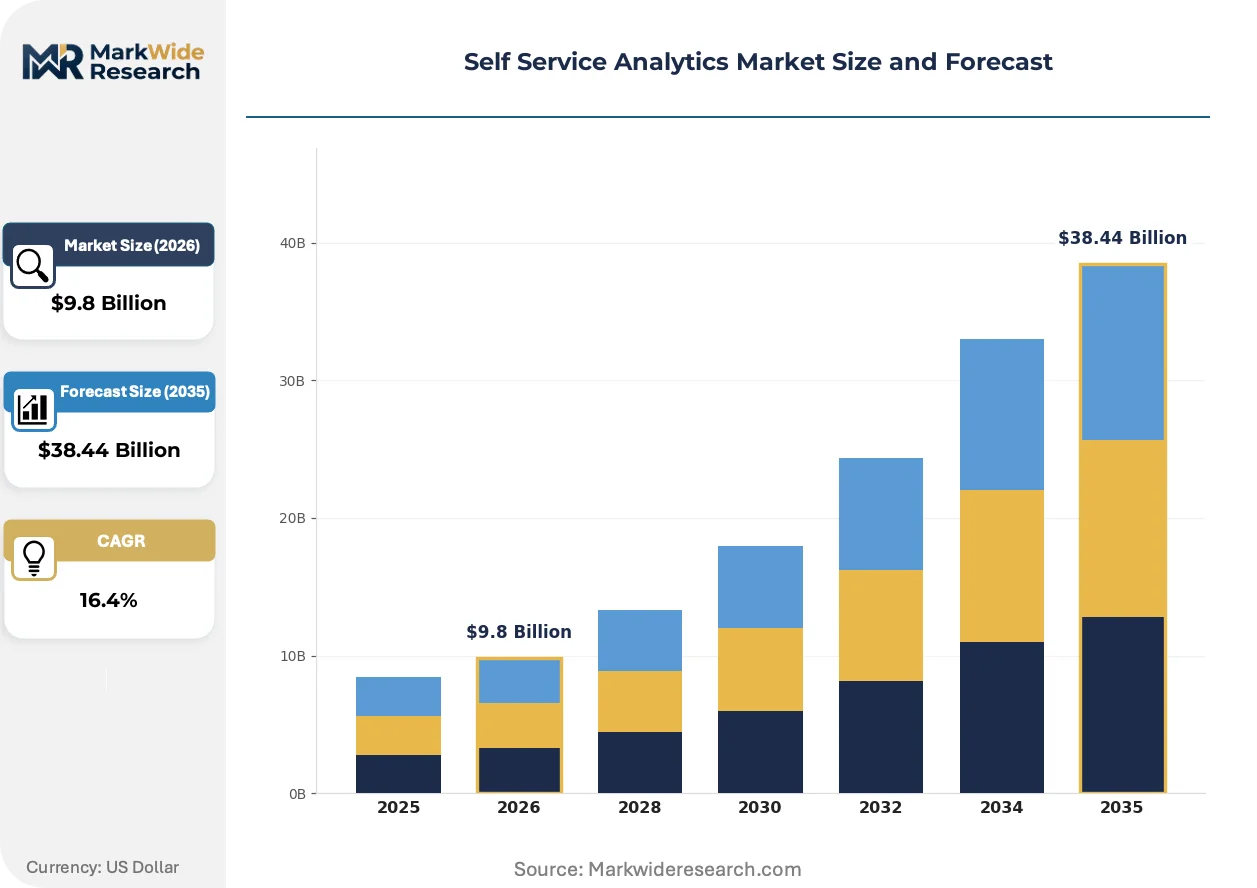
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Solution: Data Visualization, Reporting Tools, Dashboard Software, Data Preparation Industry Vertical: Finance, Retail, Healthcare, Manufacturing |
| Companies Covered | Microsoft, Tableau Software, IBM, Qlik Technologies, SAP, Oracle, TIBCO Software, ThoughtSpot, Sisense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self Service Analytics Market Strategic Shifts & Innovations
Self-service analytics is undergoing architectural transformation as embedded intelligence and automated governance reshape how organizations democratize data access. Three convergent developments are redefining platform requirements and competitive differentiation.
Edge-deployable analytics runtimes are miniaturizing the self-service stack for field operations and manufacturing floors. Oil and gas operators deploy containerized query engines directly to offshore platforms and remote well sites, enabling local decision support without satellite bandwidth dependency. This compression is miniaturizing the traditional centralized data warehouse model into distributed semantic nodes.
The EU AI Act's risk classification framework imposes documentation and human oversight obligations on high-stakes automated decision systems. Financial institutions in Frankfurt and Amsterdam must maintain audit trails for algorithmic credit scoring and fraud detection queries, driving demand for integrated lineage and explanation capabilities. Healthcare providers in France and Germany are retrofitting clinical analytics workflows to accommodate the Act's transparency mandates before enforcement deadlines.
Enterprise buyers now unbundle implementation services from platform licensing, contracting specialized systems integrators for semantic layer design while negotiating direct SaaS relationships. This disintermediation pressures vendor professional services margins and elevates partner ecosystem quality as a selection criterion. The pattern is most pronounced in United States healthcare and capital markets, where procurement teams have matured their self-service analytics sourcing capabilities.
Self Service Analytics Market Segmentation
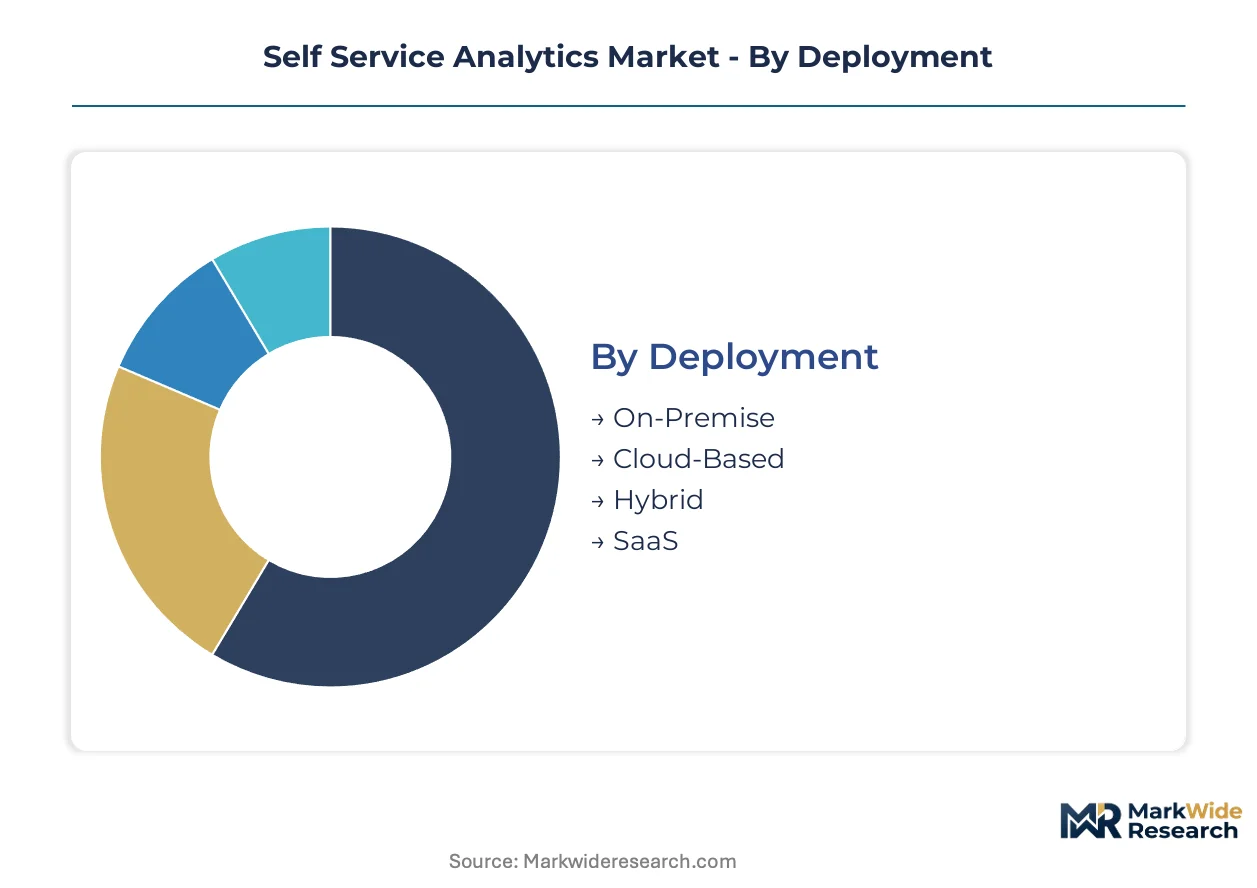
Self-service analytics platforms fragment across deployment architectures, user sophistication, and compliance intensity. Each segment carries distinct margin profiles and vendor competitive requirements.
Deployment:
GDPR, HIPAA, and China's data localization laws create divergent infrastructure mandates that reshape deployment preferences across jurisdictions.
- Cloud-Based:Hyperscale elasticity enables sub-second query response for operational dashboards without capital expenditure. United States enterprises with mature SaaS procurement functions concentrate demand here, driven by IT budget consolidation and reduced infrastructure ownership burdens.
- SaaS:Fully managed service layers abstract semantic governance and automated patching, appealing to mid-market organizations lacking dedicated data engineering capacity. European financial services firms prioritize compliant SaaS instances with EU-resident data processing to satisfy GDPR and EU AI Act obligations.
- Hybrid:Workload splitting between on-premise governed data and cloud compute addresses regulated verticals with legacy warehouse investments. Healthcare providers in the United States deploy hybrid architectures to keep HIPAA-protected records on-premise while leveraging cloud analytics for de-identified operational metrics.
- On-Premise:Complete data sovereignty and air-gapped security for defense and classified government workloads.
Cloud-Based handles the majority of throughput; SaaS is expanding most quickly on share.
End User:
Procurement authority and governance maturity separate segments more sharply than organization size alone.
- Large Enterprises:Centralized data offices mandate unified semantic layers and row-level security policies across thousands of users. These organizations negotiate enterprise-wide platform contracts with professional services for custom governance automation, particularly in United States capital markets where SEC disclosure rules demand audit-ready lineage.
- SMEs:Departmental purchasing with limited IT support drives preference for pre-configured templates and embedded intelligence. India's manufacturing clusters and service exporters represent concentrated emerging demand as digital competitiveness pressures intensify.
- Government Agencies:Federated security clearance levels and public procurement regulations impose specialized compliance modules.
- Educational Institutions:Research data management and student privacy requirements shape feature prioritization.
Large Enterprises dominate current revenue; SMEs are climbing the fastest on share.
Solution:
Functional unbundling allows buyers to source specialized components while maintaining interoperability through standardized APIs.
- Data Visualization:Drag-and-drop interfaces with 50+ chart types and real-time rendering engines. Designer-centric tools sustain premium pricing in data-literate organizations where executive consumption patterns demand polished presentation layers.
- Dashboard Software:Operational monitoring with alerting thresholds and mobile-responsive layouts. Healthcare operational digitization in the United States and EU drives specialized clinical dashboard deployments for real-time patient flow and resource utilization.
- Reporting Tools:Scheduled distribution and paginated layout engines for regulatory submission formats.
- Data Preparation:Automated cleansing, transformation, and enrichment workflows for non-technical users.
Data Visualization commands the largest installed base; Dashboard Software is gaining share fastest.
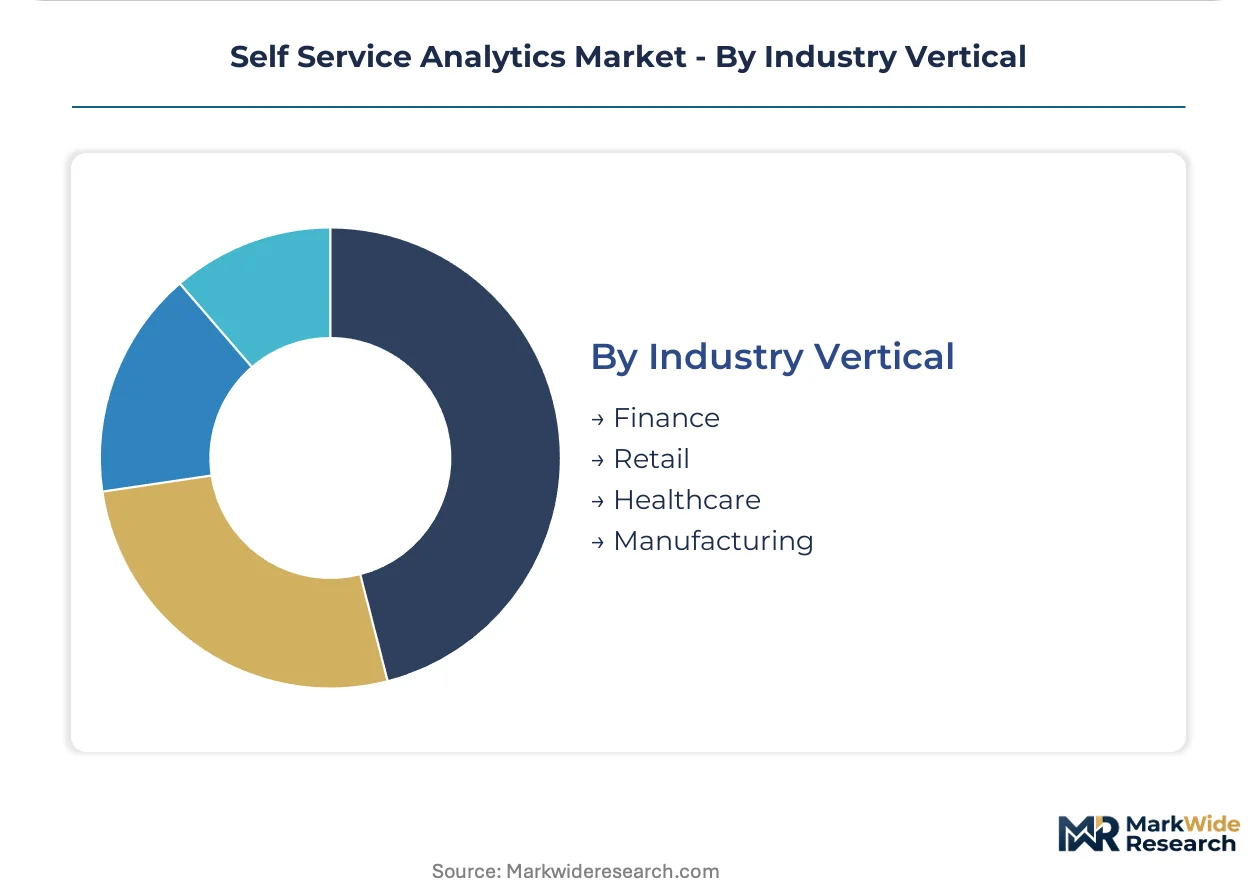
Industry Vertical:
Compliance intensity and legacy system complexity create divergent implementation economics across sectors.
- Healthcare:HIPAA-governed protected health information requires specialized semantic layers with automated de-identification and access logging. United States health systems deploy clinical self-service without IT intermediation, driving demand for governed data catalogs and patient privacy modules.
- Finance:SEC disclosure rules and EU AI Act algorithmic transparency mandates impose documentation burdens on automated credit and fraud analytics. Frankfurt and Amsterdam financial institutions retrofit workflows for audit trail maintenance before enforcement deadlines.
- Retail:Omnichannel inventory and customer analytics with moderate compliance requirements.
- Manufacturing:Industrial IoT integration and supply chain visibility with edge-deployable runtime requirements.
Healthcare captures the steepest margin pool; Finance is expanding most quickly on compliance-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net software licensing exports from the United States exceed analytics technology imports by substantial margins, while European data sovereignty mandates and Asia-Pacific cloud infrastructure incentives reshape regional deployment patterns.
United States
Enterprise IT consolidation and mature SaaS procurement functions drive hyperscale cloud analytics adoption. HIPAA and SEC disclosure rules create specialized compliance modules for healthcare and capital markets. Health systems in Texas and California deploy clinical self-service dashboards without IT intermediation, accelerating governed semantic layer demand.
Germany
EU AI Act algorithmic transparency mandates and GDPR data residency requirements dominate platform selection criteria. Frankfurt financial institutions retrofit credit scoring workflows for audit trail maintenance before enforcement deadlines. Bavarian manufacturing clusters adopt edge-deployable analytics runtimes for shop-floor decision support.
United Kingdom
Financial services regulatory pressure and post-Brexit data adequacy negotiations shape cross-border analytics governance. London capital markets demand integrated lineage capabilities for automated trading surveillance. Edinburgh and Manchester health trusts pilot NHS-compliant self-service clinical reporting.
India
PLI scheme incentives for domestic data centers position the country as an emerging Asia-Pacific delivery hub. RBI and SEBI data localization guidance drives compliant cloud infrastructure investment. Karnataka and Telangana software clusters concentrate SaaS platform engineering for global export markets.
Japan
METI digital transformation directives and aging workforce pressures accelerate conversational analytics interface adoption. Tokyo financial institutions integrate natural language-to-SQL capabilities for executive consumption. Osaka manufacturing networks deploy hybrid architectures balancing on-premise governance with cloud elasticity.
Self Service Analytics Market Key Industry Players
Listed leaders compete with private specialists across governance automation and semantic layer sophistication. The vendor base separates into three tiers: hyperscale cloud platforms with unified security fabrics, visual analytics specialists with designer-centric interfaces, and emerging conversational query disruptors. Consolidation pressure intensifies as generative interfaces commoditize traditional differentiation vectors. Dominant competitive moves include strategic partnerships for semantic layer integration and geographic expansion through compliant regional cloud instances.
Within the hyperscale platform tier, Microsoft and Oracle anchor enterprise accounts with unified security policies spanning Azure and cloud infrastructure portfolios. Tableau Software occupies a position exemplifying premium visual analytics specialization, sustaining pricing power in data-literate organizations through interface design differentiation. Among private specialists, ThoughtSpot and Sisense represent the conversational analytics and embedded intelligence archetypes respectively.
| Leading Market Players |
|---|
| Microsoft |
| Tableau Software |
| IBM |
| Qlik Technologies |
| SAP |
| Oracle |
| TIBCO Software |
| ThoughtSpot |
| Sisense |
| Others |
Cost & Logistics Intelligence
Ninety-day implementation cycles for enterprise semantic layer deployment compress vendor cash conversion and amplify pricing leverage for buyers with multi-year SaaS commitments. This lead-time compression concentrates margin pressure on mid-tier platform providers lacking hyperscale cloud infrastructure subsidies.
Pricing Analysis
Enterprise IT buyers anchor SaaS subscription pricing across three consumption tiers calibrated to query volume and governance automation depth. Price differentiation hinges on row-level security certification grade and dedicated customer success engineering. Pricing pressure stems from generative interface commoditization eroding traditional visual analytics premiums. Mid-market organizations exhibit highest price sensitivity; capital markets firms with SEC audit requirements show lowest.
Supply Chain Analysis
Just-in-time provisioning dominates cloud-native deployments while strategic reserved capacity commitments secure compute pricing for hybrid architectures. Engineering talent concentrates in United States, India, and Germany. The supply chain draws from hyperscale cloud infrastructure, open-source query engines, and specialized systems integrators. Single-source vulnerability sits with concentrated GPU availability for AI-augmented workloads. Distribution runs through direct vendor sales with partner-led implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Self-service analytics represents a high-growth disruption as natural language-to-SQL interfaces collapse technical barriers between business users and enterprise data warehouses. The EU AI Act algorithmic transparency mandates accelerate governance automation investment cycles.
For Market Incumbents: Compound platform stickiness through embedded semantic layer partnerships with legacy data warehouse vendors. Deepen governance automation R&D to outpace conversational query disruptors. Vertical integration into specialized compliance modules for HIPAA and SEC disclosure rules defends margin position against lighter departmental tools. For New Entrants and Emerging Players: Differentiate on edge-deployable analytics runtimes for manufacturing and oilfield operations underserved by centralized cloud architectures. White-space targets include Bavarian automotive clusters and Texas Permian Basin operators. A channel-first go-to-market through industrial systems integrators accelerates field deployment credibility. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because generative interfaces commoditize traditional differentiation vectors and reward scale economics in governance automation. Target acquisition archetype: conversational analytics specialists with proven natural language-to-SQL engines. The signal to watch is hyperscaler partnership announcements embedding third-party semantic layers into native cloud data warehouses.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding governance automation into Microsoft Azure and AWS data lake architectures captures enterprise procurement workflows. |
| Geographic Expansion | EU-resident cloud instances satisfy GDPR and EU AI Act mandates for Frankfurt financial institutions and Paris healthcare networks. |
| Acquisition of Specialist Firm | Conversational query engines from emerging vendors accelerate natural language interface roadmaps for incumbent platforms. |
| Strategic Partnership | Systems integrator alliances for semantic layer design address buyer unbundling of implementation from licensing. |
| Product Launch | Automated explanation generation modules target EU AI Act compliance deadlines for Amsterdam credit scoring workflows. |
Research Approach
Desk research of SEC filings, hyperscaler capex disclosures, and EU regulatory databases preceded structured interviews with CTOs, IT procurement officers, platform engineers, and healthcare data governance leads. Primary fieldwork across United States, Germany, and India validated secondary estimates through bottom-up deployment sizing and top-down IT budget allocation analysis.
Variance decomposition across deployment model, organization size, vertical compliance intensity, and regional adoption pattern shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated cloud infrastructure pricing trajectories and generative interface adoption curves without year-specific milestones.
Material uncertainties — regulatory enforcement timing for EU AI Act, hyperscaler pricing volatility, and legacy warehouse modernization pace — sit outside the modeled envelope. Forecasts reflect assumptions about governance automation maturation and conversational query interface reliability. Revision becomes warranted when generative interface accuracy benchmarks cross enterprise production deployment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Data Analysis Tools Market
Analytics
Procurement Analytics Market
Analytics
Canada Contact Center Analytics Market
Analytics
United States Geospatial Analytics Market
Analytics
Customer Journey Analytics Market
Analytics
Manufacturing Predictive Analytics Market
Analytics
Business Intelligence and Analytics Software Market
Analytics
United Kingdom Geospatial Imagery Analytics Market
Analytics
Asia-Pacific Contact Center Analytics Market
Analytics
Application Analytics Market
Analytics
Europe Emotion Analytics Market
Analytics
Latin America Big Data Analytics Market
Analytics
Imagery Analytics Market
Analytics
Global Clickstream Analytics Market
Analytics
Greece ICT Market
Analytics
Application Metrics and Monitoring Tools Market