
 China Surveillance IP Camera Market | 2026-2036
China Surveillance IP Camera Market Size, Share, and Industry Trends Forecast 2026-2036
China Surveillance IP Camera Market Insights
Cloud-based video management subscription layers is hardening the commercial model beyond one-time hardware sales. Hikvision Digital Technology leverages its integrated silicon-to-software stack to control deployment costs across provincial government tenders. Dahua Technology anchors its position through deep manufacturing scale in Zhejiang province. Zhejiang Uniview Technologies differentiates via AI-native camera architectures designed for edge analytics in transportation corridors.
A surveillance IP camera is a networked digital imaging device that captures, compresses, and transmits video data via Internet Protocol to centralized or distributed storage systems, typically operating at resolutions from 2MP to 8MP with H.265 encoding and Power-over-Ethernet connectivity for continuous security monitoring and automated analytics. The technology dimension shows IP systems displacing legacy analog infrastructure as municipal buyers prioritize remote manageability and firmware upgrade paths. Dome cameras dominate indoor commercial installations where discreet positioning matters, while bullet cameras lead perimeter defense deployments across industrial zones and transportation nodes.
MIIT cybersecurity review requirements and GB/T standard compliance for networked cameras are tightening market access for uncertified equipment, directly shaping procurement specifications in government and critical infrastructure verticals. SAMR antitrust scrutiny of dominant vendors is influencing channel pricing transparency and distributor margin structures. Stakeholders must monitor evolving data localization mandates and domestic encryption standards that could force architectural redesigns of cloud-connected surveillance platforms.
Market Dynamics
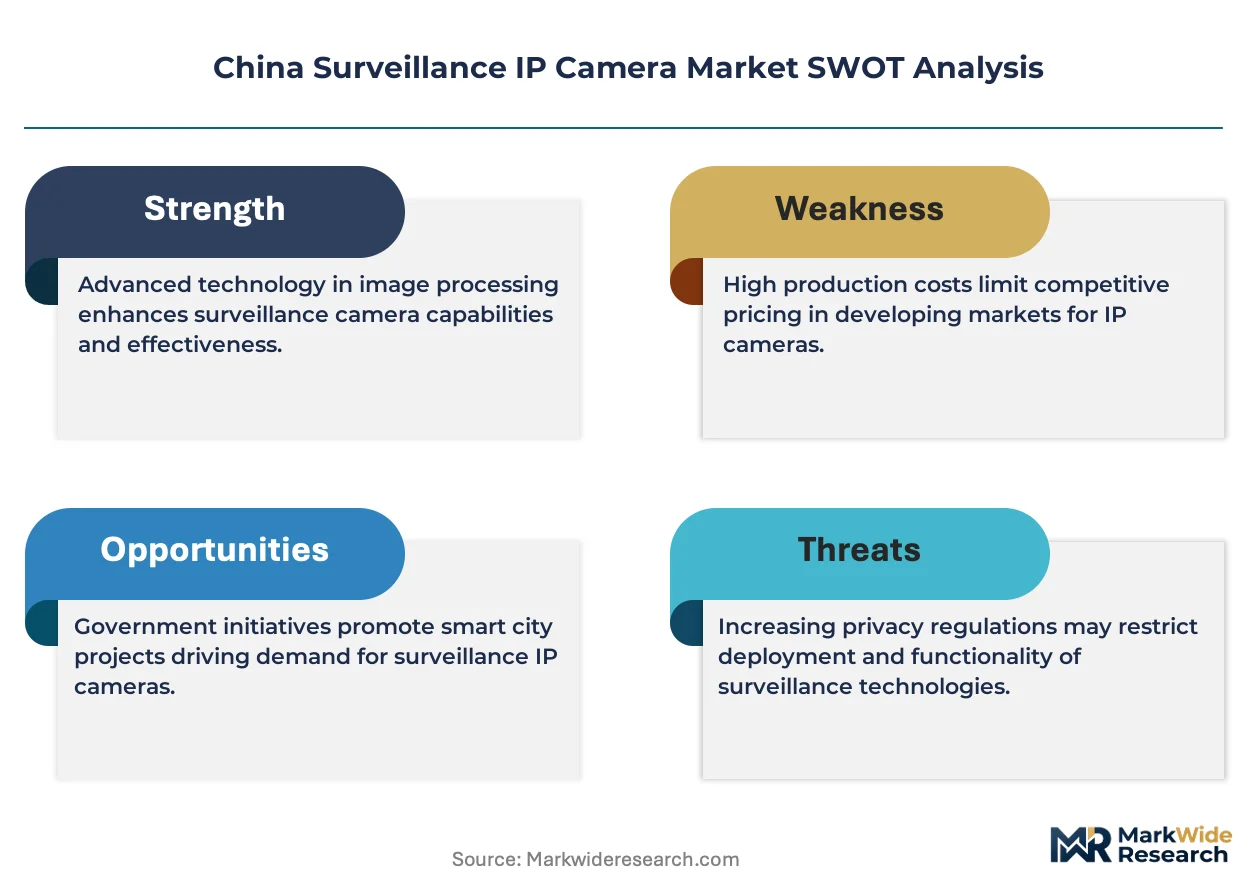
MIIT's cybersecurity certification mandate for IoT devices is compressing supplier qualification timelines while forcing architectural redesigns across cloud-connected surveillance platforms deployed in smart city infrastructure.
Growth Catalysts
- Smart city infrastructure mandates:Municipal digitization programs in coastal provinces are accelerating networked video system procurement for public safety applications.
- GB/T standard harmonization:Unified technical specifications for networked cameras are reducing integration friction across provincial government tenders.
- Edge analytics hardware maturation:AI-native camera architectures are enabling real-time processing in transportation corridors without centralized server dependency.
Market Restraints
- Silicon supply concentration:Image sensor fabrication capacity clusters in Taiwan and South Korea create input vulnerability for domestic camera assembly.
- SAMR antitrust enforcement:Pricing transparency investigations are compressing distributor margin structures and channel profitability.
- Data localization compliance costs:Cross-border video transmission restrictions are forcing redundant domestic cloud infrastructure investment.
Strategic Opportunities
- Central and western province penetration:Public safety digitization budgets in Sichuan and Shaanxi remain underdeployed relative to eastern coastal benchmarks.
- Multi-sensor fusion architectures:Thermal-visible-LiDAR convergence is opening perimeter defense applications in critical infrastructure verticals.
- MIIT domestic encryption standards:Certified suppliers gain preferential access to government and state-owned enterprise procurement channels.
Industry Challenges
- Firmware security engineering talent scarcity:Embedded systems security expertise required for MIIT certification outpaces domestic training pipeline output.
- Legacy analog migration complexity:Municipal buyers face integration friction when hybridizing existing coaxial infrastructure with IP backbones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Surveillance IP Camera Market |
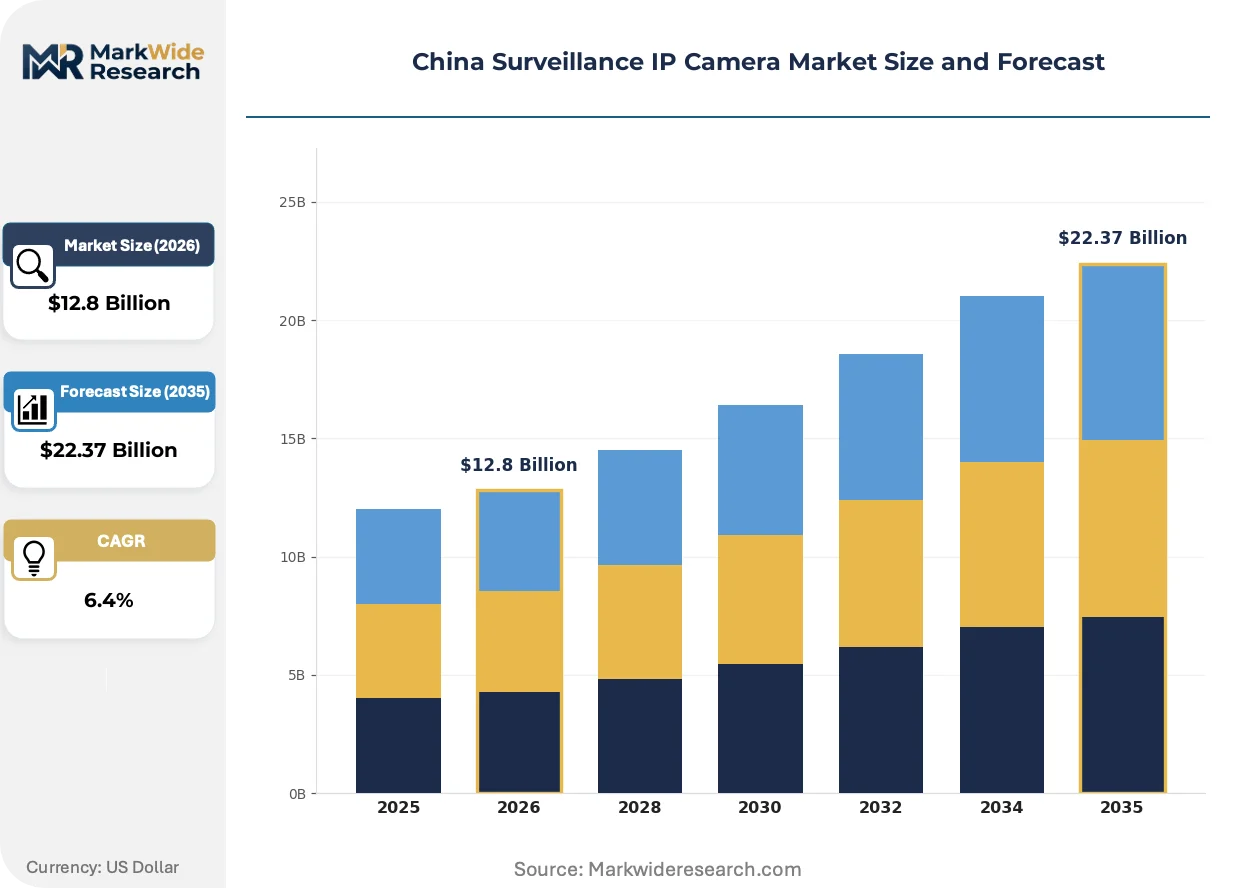
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Camera, Bullet Camera, PTZ Camera, Box Camera Technology: Analog, IP, Hybrid, Wireless End User: Government, Retail, Transportation, Residential Installation Type: Indoor, Outdoor, Wall-mounted, Ceiling-mounted |
| Companies Covered | Hikvision Digital Technology, Dahua Technology, Zhejiang Uniview Technologies, Tiandy Technologies, TVT Digital Technology, Bokysee, ZKTeco, Hanwha Vision, Anpviz, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Surveillance IP Camera Market Trends and Innovations
Computational imaging and edge-native processing architectures are compressing the traditional server-centric surveillance model while redistributing value capture toward semiconductor and firmware layers.
AI-driven scene analysis is automating anomaly detection in crowded transportation hubs and industrial perimeters. Municipal traffic management authorities in Hangzhou and Shenzhen are deploying these systems at scale. The technology is automating operator workload reduction while enabling 24/7 monitoring coverage that human staffing cannot economically support.
MIIT's cybersecurity review framework is tightening network access control requirements for imported components in government-facing deployments. Domestic certification timelines now extend hardware qualification cycles by several quarters. Critical infrastructure verticals are responding by accelerating qualification of domestically sourced image processing chipsets.
Subscription-based video management software is displacing perpetual license models in commercial and municipal accounts. System integrators in Guangdong and Jiangsu are bundling cloud storage tiers with hardware procurement. This shift is most visible among mid-tier municipal buyers seeking operational expenditure predictability over capital-intensive server deployments.
China Surveillance IP Camera Market Segmentation
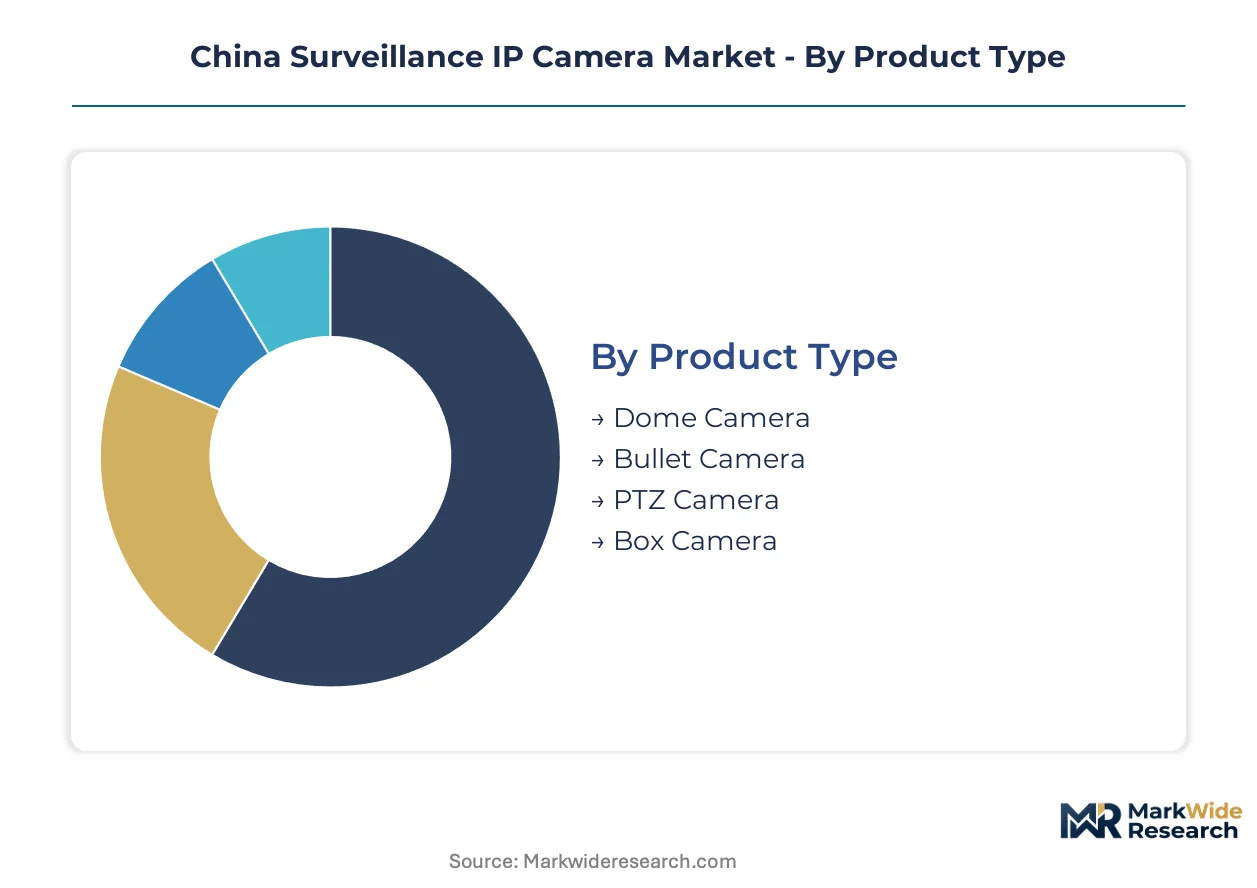
Segmentation in China's surveillance IP camera market reveals how procurement specifications diverge across buyer types and deployment environments. Municipal tender documents increasingly weight cybersecurity certification and edge analytics capability over base hardware specifications.
Product Type:
Camera form factor selection hinges on concealment requirements, environmental exposure, and operator control needs across deployment scenarios.
- Dome Camera:Encased hemispherical housings with vandal-resistant polycarbonate domes enable 360-degree pan-tilt capability in discreet ceiling installations. Hangzhou metro stations and Shenzhen commercial complexes specify these for passenger flow monitoring where aesthetic integration matters alongside GB/T compliance.
- Bullet Camera:Cylindrical weather-sealed housings with integrated IR illuminators deliver fixed-angle coverage across extended perimeters. Industrial zones in Zhejiang province deploy these at transportation nodes and logistics hubs where long-range visibility and deterrence visibility outweigh concealment.
- PTZ Camera:Motorized pan-tilt-zoom mechanisms enable operator-directed tracking of moving subjects across wide areas.
- Box Camera:Modular lens-interchangeable bodies serve specialized applications requiring telephoto or wide-angle optics.
Dome cameras lead on scale through smart city indoor procurement volumes; bullet cameras lead on momentum through perimeter defense digitization in industrial corridors.
Technology:
Signal transmission architecture determines remote manageability, cybersecurity surface area, and infrastructure migration path for municipal buyers.
- IP:Networked digital cameras with H.265 encoding and PoE connectivity enable centralized firmware management and cloud analytics integration. MIIT cybersecurity certification mandates are accelerating displacement of legacy infrastructure in coastal province tenders.
- Hybrid:Dual-signal devices bridge coaxial legacy cabling with IP backbone connectivity, easing municipal migration friction where analog sunk costs persist.
- Analog:Traditional closed-circuit systems with coaxial transmission retain presence in budget-constrained county-level installations.
- Wireless:Wi-Fi or cellular-connected devices serve temporary deployments and retrofit scenarios where structured cabling proves prohibitive.
IP systems dominate current procurement specifications; hybrid configurations gain share fastest in central and western province retrofit programs.
End User:
Budget authority and cybersecurity compliance stringency shape vertical demand concentration and supplier qualification requirements.
- Government:Provincial public safety bureaus and municipal traffic authorities command the largest procurement volumes with mandatory MIIT certification and domestic encryption standards.
- Transportation:Airport authorities, rail operators, and port administrators require edge-native analytics for real-time crowd and vehicle flow optimization.
- Retail:Shopping mall operators and chain stores prioritize loss prevention analytics with cloud-based subscription management.
- Residential:Property developers and homeowners associations drive demand for cost-optimized Wi-Fi connected devices with mobile app integration.
Government vertical leads on absolute procurement value; transportation infrastructure shows steepest expansion trajectory through corridor digitization mandates.
Installation Type:
Mounting configuration selection correlates directly with environmental exposure, tamper risk, and field-of-view optimization requirements.
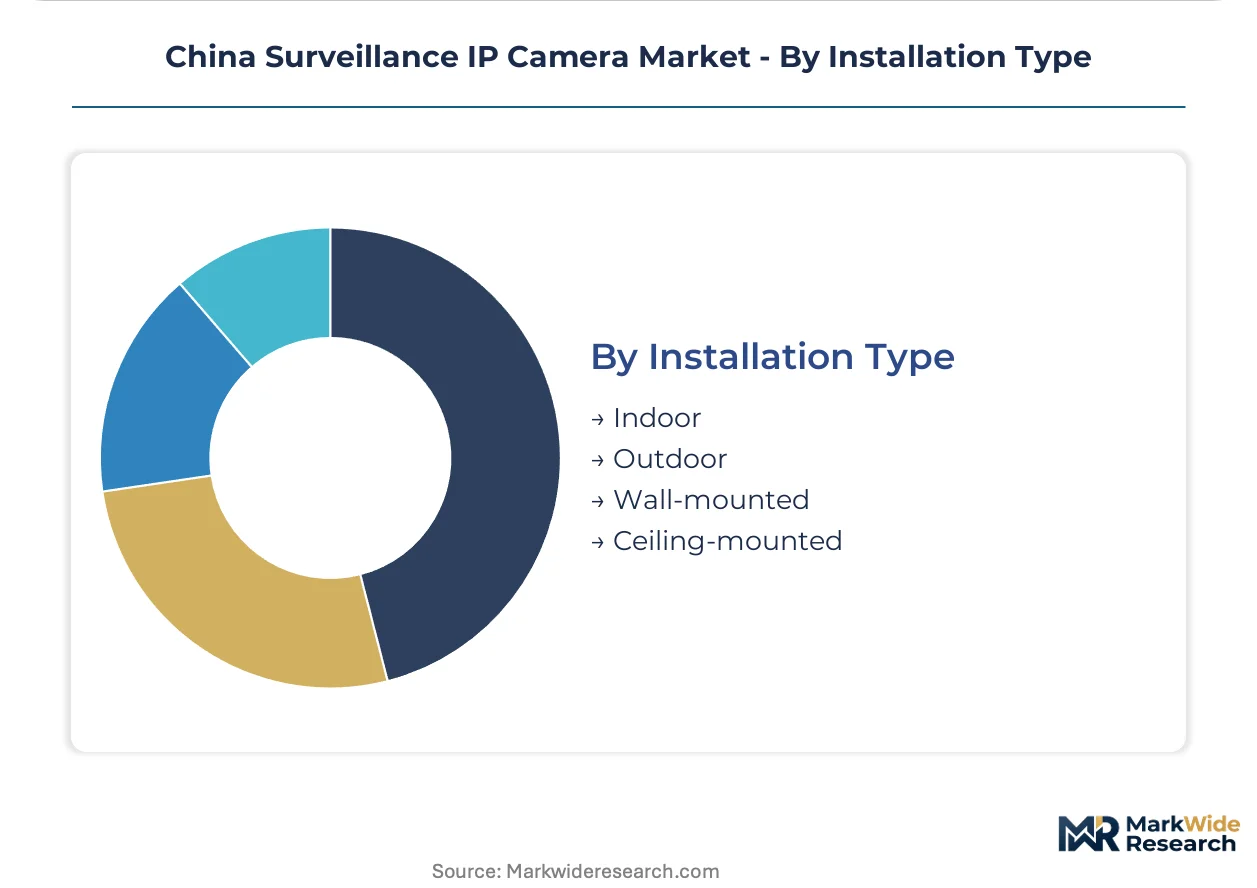
- Outdoor:Weather-rated IP66+ housings with integrated heaters and IR illumination withstand temperature extremes and precipitation across perimeter deployments.
- Indoor:Climate-controlled environment designs optimize for lower power consumption and acoustic discretion in commercial and institutional settings.
- Wall-mounted:Bracket-fixed positioning maximizes horizontal coverage angles across building exteriors and corridor intersections.
- Ceiling-mounted:Recessed or surface-mounted suspension enables downward sightlines optimized for crowd density analysis and retail traffic patterns.
Outdoor installations lead on hardware value per node; ceiling-mounted configurations expand most quickly through smart building integration in eastern coastal commercial developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands surveillance IP camera procurement volumes that dwarf individual European markets, while India's municipal digitization programs generate faster percentage growth from a smaller installed base. Provincial budget allocation patterns and cybersecurity certification timelines create distinct competitive dynamics across national boundaries.
United States
Federal infrastructure grants and municipal bond issuances fund smart city video deployments in Chicago and Los Angeles. FCC equipment authorization requirements and NDAA Section 889 procurement restrictions shape supplier qualification for government contracts. Texas and Florida concentrate perimeter defense installations across critical energy and transportation infrastructure.
Germany
Railway station modernization and industrial facility security drive IP camera replacement cycles in Bavaria and North Rhine-Westphalia. GDPR video data processing rules and BSI IT security certification constrain cloud-connected architecture designs. Stuttgart's automotive manufacturing corridors deploy edge-analytics systems for supply chain monitoring.
India
Smart Cities Mission funding and state-level safe city programs accelerate networked video procurement in Maharashtra and Karnataka. BIS certification mandates for electronic security equipment extend hardware qualification timelines. Delhi-Mumbai Industrial Corridor projects integrate IP surveillance with traffic management systems.
Japan
Tokyo Olympics legacy infrastructure and aging population security needs sustain municipal camera deployments. METI IoT security guidelines and JIS standards compliance requirements filter supplier access to government channels. Osaka-Kobe manufacturing zones prioritize vandal-resistant dome configurations for factory automation monitoring.
South Korea
Sejong smart city construction and KTX rail network expansion generate concentrated demand for transportation-grade cameras. MFDS cybersecurity frameworks for connected devices and KISA certification programs regulate procurement specifications. Busan port authority digitization projects specify marine-rated bullet cameras for container terminal coverage.
China Surveillance IP Camera Market Competitive Landscape
Top-tier vendors anchor government and critical infrastructure procurement, while mid-tier specialists compete on price-sensitive commercial and residential segments. Market structure shows oligopolistic concentration at the premium tier with fragmented competition below. Three archetypes dominate: integrated silicon-to-system manufacturers, pure-play camera fabricators, and software-centric platform providers. Capacity expansion in Zhejiang province and strategic partnerships for AI chipset sourcing represent the primary competitive vectors reshaping positioning.
Within the integrated manufacturing tier, Hikvision Digital Technology and Dahua Technology exemplify vertically consolidated operations spanning image sensor sourcing through cloud platform deployment. Zhejiang Uniview Technologies occupies a position representing the AI-native specialization archetype, with company naming indicating Hangzhou-region concentration. These three entities collectively represent the cybersecurity-certified supplier base that MIIT qualification requirements have concentrated toward government-facing procurement channels.
| Leading Market Players |
|---|
| Hikvision Digital Technology |
| Dahua Technology |
| Zhejiang Uniview Technologies |
| Tiandy Technologies |
| TVT Digital Technology |
| Bokysee |
| ZKTeco |
| Hanwha Vision |
| Anpviz |
| Others |
Pricing and Supply Chain Analysis
Provincial public safety bureaus and municipal traffic authorities concentrate procurement authority, anchoring project-based pricing with multi-year service bundling rather than transactional hardware sales.
Pricing Analysis
Capacity additions in Zhejiang province are reshaping price floors across the mid-tier camera segment. Three-tier pricing structure across premium, standard, and economy levels stratifies by MIIT cybersecurity certification grade and edge analytics capability. Pricing pressure stems from SAMR antitrust investigations compressing distributor margins. County-level buyers exhibit highest price sensitivity; critical infrastructure verticals demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Hangzhou and Shenzhen operate hub-and-spoke patterns feeding provincial integrators. Image sensor fabrication draws from Taiwan and South Korea; lens modules source from Japan and Germany. Single-source vulnerability in advanced CMOS supply creates procurement risk. Distribution runs through state-owned enterprise procurement platforms and authorized systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion hinges on subscription-based video management software displacing perpetual licenses, capturing recurring revenue streams beyond one-time hardware deployment.
For Market Incumbents: Lock in government procurement channel access through accelerated MIIT cybersecurity certification investment. Deepen manufacturing scale in Zhejiang to defend against emerging AI-native camera specialists. Channel control represents the critical lever against pricing transparency mandates. For New Entrants and Emerging Players: Systems integrators in Sichuan and Shaanxi provinces present underexploited channel partnerships for central and western province penetration. Target transportation corridor digitization programs with thermal-visible fusion architectures. Pursue joint qualification with domestic image processing chipset suppliers to bypass incumbent certification timelines. For Investors and Strategic Acquirers: Semiconductor firms seeking edge AI deployment are the most active acquirer in this space. Five-to-ten year viability favors suppliers with captive silicon-to-software stacks. Acquisition target archetype: AI-native camera specialists with MIIT certification and transportation vertical traction. Watch domestic encryption standard adoption curves as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Cybersecurity Certification Acceleration | Certified suppliers gain preferential access to government procurement channels under tightening GB/T compliance mandates. |
| Edge Analytics Hardware Maturation | AI-native camera architectures enable real-time processing in Hangzhou and Shenzhen transportation corridors without server dependency. |
| Subscription-Based Video Management Migration | Cloud storage tiers bundled with hardware procurement shift municipal buyers toward operational expenditure predictability. |
| Central and Western Province Channel Expansion | Sichuan and Shaanxi public safety digitization budgets remain underdeployed relative to eastern coastal benchmarks. |
| Domestic Image Processing Chipset Qualification | Critical infrastructure verticals accelerate qualification of domestically sourced silicon to reduce Taiwan and South Korea input vulnerability. |
Research Methodology
Bottom-up municipal procurement modeling reconciled against top-down supplier shipment tracking forms the analytical core. Primary interviews with provincial public safety bureau procurement officers, systems integrator technical directors, MIIT certification consultants, and semiconductor supply chain managers combined with secondary validation from customs trade records, MIIT certification databases, provincial tender announcement aggregators, and GB standards documentation.
Input-output matrices map camera form factor, technology architecture, end-use vertical, and installation environment against provincial budget allocation patterns across the projection horizon. CAGRs derive from segment-level unit economics and pricing trajectory modeling. Forecast inputs include MIIT certification timeline assumptions and smart city infrastructure deployment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cybersecurity regulation evolution and semiconductor supply chain restructuring. Forecasts reflect documented assumptions around provincial budget continuity and GB/T standard harmonization pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
Security Cameras (IR Illuminator) Market
Video Surveillance Systems
AI CCTV Market
Video Surveillance Systems
Global GCC Video Surveillance Storage Market
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Central Monitoring Station Market
Video Surveillance Systems
United Kingdom Video Surveillance Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
Global Body Worn Cameras Market